
 North America Condensed Milk Market | 2026-2036
North America Condensed Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America Condensed Milk Market Insights
Mexico's dairy belt expansion is reconfiguring supply dynamics across the continent. Nestlé S.A. leverages its multi-country processing footprint to secure raw milk access in both the United States and Mexico. Eagle Family Foods Group LLC anchors its position through specialized sweetened condensed milk production for industrial bakery accounts. The J.M. Smucker Company competes via brand recognition in retail channels, extending its shelf-stable dairy portfolio across North American grocery networks.
Condensed milk denotes cow's milk from which water has been removed to approximately half its original volume, yielding a viscous liquid with elevated sugar content in sweetened variants or reduced fat profiles in evaporated formats, primarily serving as a shelf-stable ingredient for confectionery, beverage, and prepared food manufacturing. Sweetened condensed milk dominates value contribution due to its irreplaceable role in caramel production and traditional dessert formulations across Latin American and Southern U.S. cuisines. Evaporated milk occupies a mature but stable position in home cooking segments, while flavored condensed milk variants are gaining traction among younger retail consumers seeking convenience in dessert preparation. Packaging in cans persists as the manufacturing default, though pouches are emerging in food service bulk procurement for operational efficiency gains.
The FDA governs dairy product standards of identity in the United States, directly constraining permissible fat and solids content in condensed milk sold interstate, while Health Canada and PMRA administer parallel compositional requirements and agricultural chemical residue limits affecting cross-border trade. Mexico's national dairy regulator enforces labeling and sanitary standards that processors must satisfy for market access, creating a three-jurisdiction compliance burden for integrated North American suppliers. Stakeholders must monitor evolving sugar reduction mandates and plant-based labeling disputes, as these policy currents threaten to recategorize traditional condensed milk products or shift consumer perception in ways that reshape procurement priorities across bakery and food service channels.
Market Dynamics
The FDA's updated dairy labeling standards are forcing processors to reformulate product compositions, tightening claims around fat content and solids concentration while bakery demand concentrates in the southeastern United States.
Growth Catalysts
- Artisanal bakery expansion:Small-batch dessert producers across Mexico and the United States are absorbing greater volumes of sweetened condensed milk for caramel and traditional confectionery applications.
- Shelf-stable logistics:Canned and pouch formats enable extended distribution reach into food service networks lacking refrigerated supply chain infrastructure.
- Cross-border dairy belt integration:Raw milk sourcing corridors linking Mexican agricultural zones with U.S. processing clusters are reducing input volatility for integrated suppliers.
Market Restraints
- Input cost volatility:Fluctuations in global sugar prices and regional raw milk procurement costs compress margins for processors lacking long-term supply contracts.
- Three-jurisdiction compliance burden:Parallel FDA, Health Canada, and Mexican national dairy regulator standards create formulation conflicts and label adaptation costs for North American suppliers.
- Plant-based substitution:Oat and coconut-based condensed alternatives are capturing retail shelf space and consumer trial among younger demographics seeking dairy-free dessert ingredients.
Strategic Opportunities
- Flavored variant development:Chocolate, dulce de leche, and coffee-infused condensed milk formats are gaining traction among convenience-seeking home bakers in U.S. metropolitan markets.
- Pouch format adoption:Food service bulk procurement is shifting from traditional cans to flexible packaging for operational efficiency in high-volume bakery and beverage manufacturing.
- Sugar reduction positioning:Evaporated milk variants with modified solids profiles can capture reformulation demand as FDA sugar disclosure requirements tighten.
Industry Challenges
- Reformulation timeline compression:FDA standards of identity updates require rapid product redevelopment cycles, straining R&D bandwidth at mid-sized processors.
- Sanitary certification complexity:Cross-border facility audits under Mexican, Canadian, and U.S. dairy safety protocols demand redundant quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Condensed Milk Market |
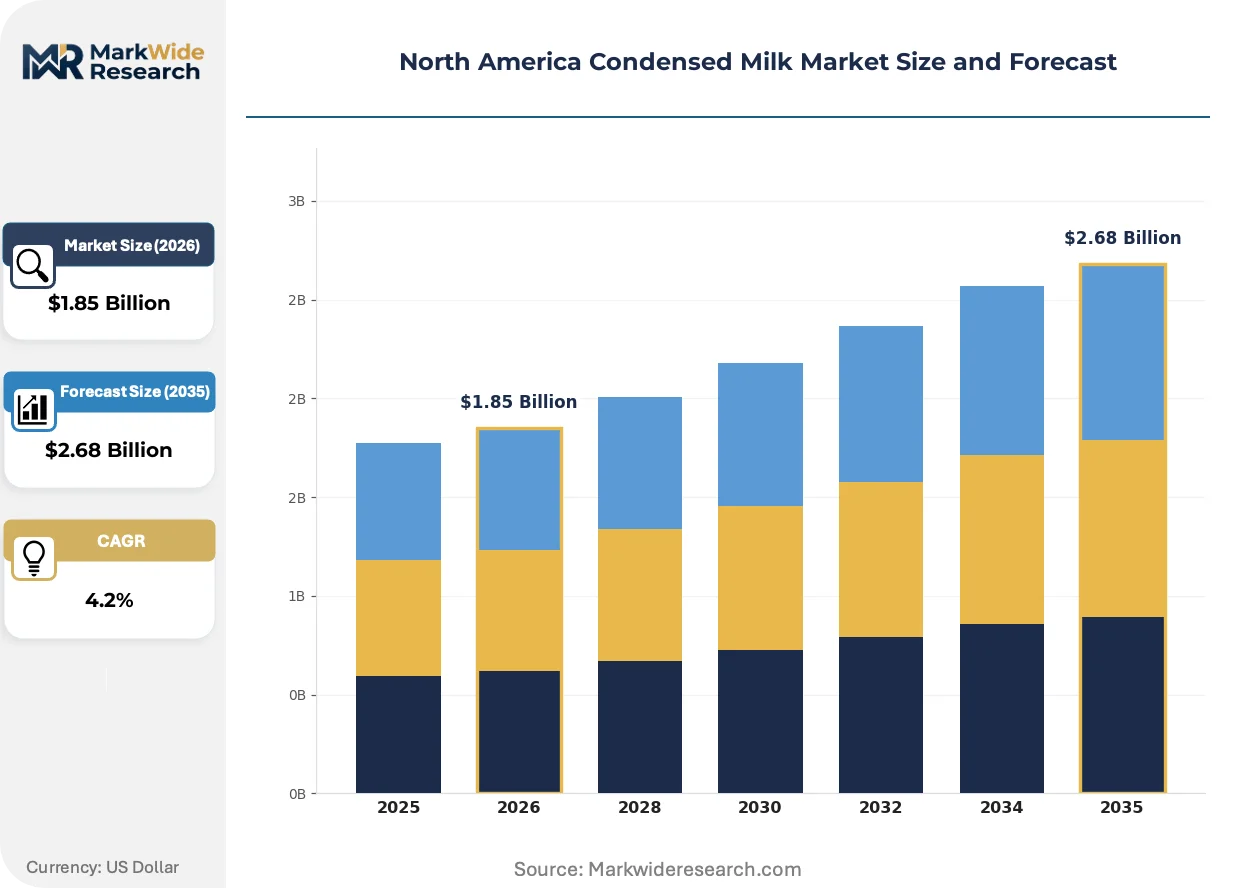
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened Condensed Milk, Unsweetened Condensed Milk, Evaporated Milk, Flavored Condensed Milk Packaging Type: Can, Tetra Pack, Jar, Pouch End User: Food Service, Retail, Home Cooking, Bakery Distribution Channel: Supermarkets, Online, Convenience Stores, Wholesale |
| Companies Covered | Nestlé S.A., Eagle Family Foods Group LLC, The J.M. Smucker Company, Santini Foods, Inc., Goya Foods Inc., Meijer, Inc., Meadow Gold Dairies, Arla Foods amba, O-AT-KA Milk Products Cooperative, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Condensed Milk Market Trends and Innovations
Processing technology and packaging format evolution are compressing traditional manufacturing economics while regulatory disclosure requirements and procurement centralization reshape how buyers engage suppliers.
Aseptic processing systems with extended shelf-life stabilization are rendering obsolete conventional retort canning for high-volume food service contracts. Industrial bakery and beverage manufacturers in Texas and California are adopting these systems to reduce energy input costs and warehouse footprint. The technology is rendering obsolete regional processor business models dependent on refrigerated distribution networks.
Health Canada's updated nutrition fact table regulations and parallel FDA added-sugar line-item disclosure mandates are forcing label redesigns across sweetened condensed milk portfolios. Processors must reconcile divergent serving-size definitions and daily-value calculations for cross-border retail SKUs. The regulatory friction most impacts value-added flavored variants where sugar content exceeds single-ingredient evaporated milk benchmarks.
Consolidated procurement by national bakery chains and quick-service restaurant distributors is compressing supplier negotiation cycles and unbundling technical service from commodity pricing. Regional dairy cooperatives are losing direct relationships with end-users as buying power concentrates with procurement platforms serving multi-state food service networks. The shift is most visible in the southeastern United States, where dairy processing clusters now negotiate primarily through distributor intermediaries rather than direct bakery accounts.
North America Condensed Milk Market Segmentation
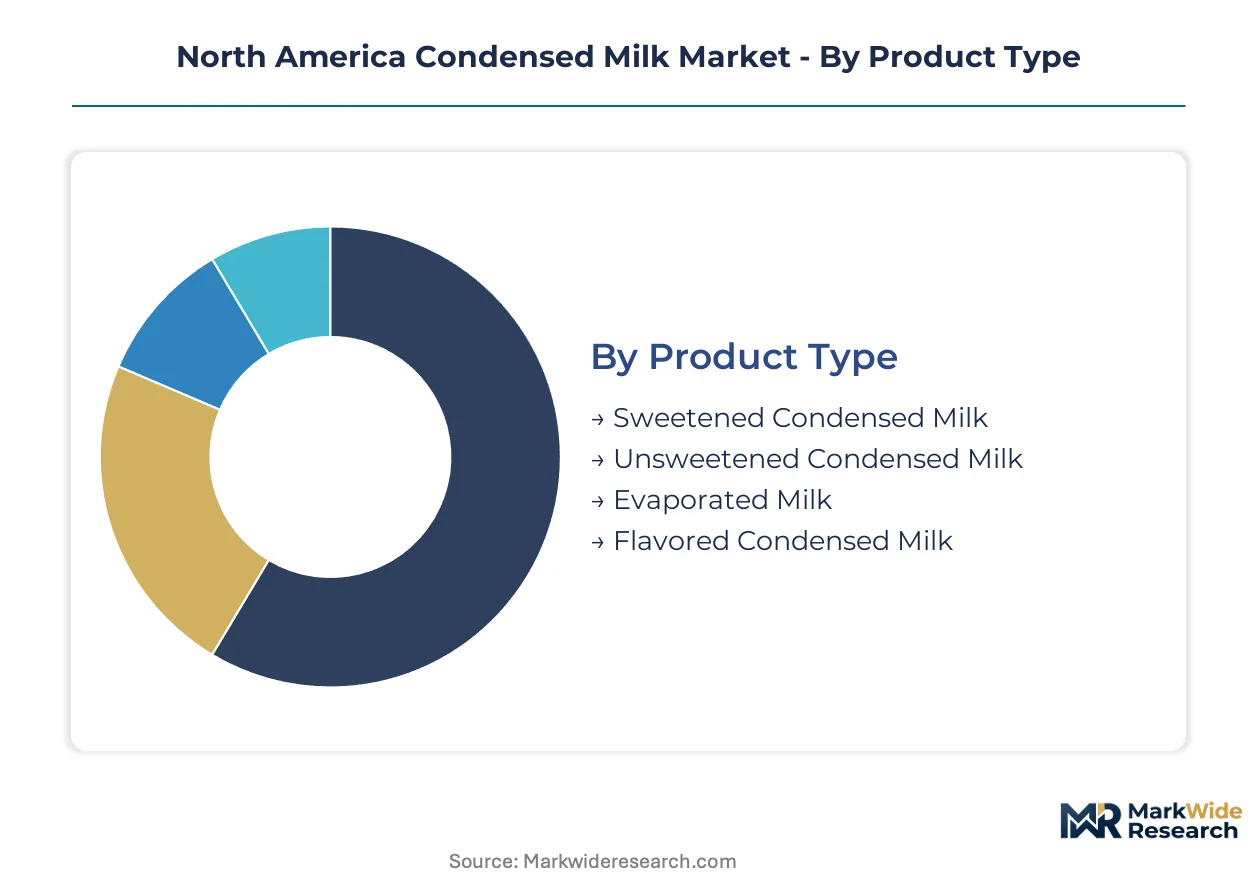
Segmentation in the North America condensed milk market reveals divergent profit pools and inventory velocities. Product format and packaging choices determine shelf-life economics, while end-user concentration shapes procurement centralization and price realization.
Product Type:
Sweetened condensed milk turns inventory fastest due to caramel and dessert manufacturing pull, while evaporated milk sits longer in home-cooking channels with episodic demand patterns.
- Sweetened Condensed Milk:Viscous liquid with elevated sucrose content serving as the irreplaceable base for dulce de leche and traditional Latin American confectionery. Demand concentrates in Texas and California industrial bakeries where artisanal dessert production scales rapidly. Reformulation pressures from FDA sugar disclosure mandates are compressing development cycles for reduced-sugar variants.
- Evaporated Milk:Shelf-stable dairy with approximately 60% water removal and no added sugar, occupying mature home-cooking segments across the southeastern United States. Stable demand from institutional food service in Florida and Georgia sustains volume despite slower velocity than sweetened formats. Processors leverage existing canning infrastructure to maintain margin protection against input volatility.
- Unsweetened Condensed Milk:Reduced-water dairy base without sucrose addition, serving niche commercial applications requiring precise sweetness control. Penetration remains limited outside industrial ingredient supply chains.
- Flavored Condensed Milk:Chocolate, coffee, and dulce de leche-infused variants targeting convenience-oriented home bakers in U.S. metropolitan markets. Trial rates among younger demographics are climbing fastest in coastal urban centers.
Sweetened condensed milk anchors the volume base while flavored condensed milk gains share at the steepest rate.
Packaging Type:
Format selection tracks customer scale and operational infrastructure, with large-volume food service buyers prioritizing handling efficiency over shelf aesthetics.
- Can:Standard steel or aluminum cylindrical container with hermetic sealing, retaining manufacturing default status across North American production facilities. Legacy equipment investments and retailer familiarity sustain dominance despite higher material costs than flexible alternatives. Canning lines in Wisconsin and New York serve regional dairy cooperatives with established supermarket distribution.
- Pouch:Flexible multi-layer film packaging enabling bulk food service procurement with reduced warehouse footprint and disposal weight. Adoption is accelerating among Texas and California bakery chains seeking operational efficiency in high-volume manufacturing environments. Aseptic filling technology investments are displacing regional processors dependent on refrigerated distribution.
- Tetra Pack:Aseptic carton format with extended shelf-life stabilization, penetrating retail channels in Canadian metropolitan markets where environmental positioning influences purchase decisions. Health Canada packaging waste regulations favor fiber-based formats over metal alternatives.
- Jar:Glass container format serving premium retail positioning and gift-market applications. Higher unit economics limit penetration to specialty grocery channels in affluent U.S. urban districts.
Can formats retain the installed base while pouch packaging expands most quickly in food service procurement.
End User:
Customer scale determines pricing power and technical service intensity, with consolidated buyers extracting supply chain concessions unavailable to fragmented accounts.
- Bakery:Industrial and artisanal dessert manufacturers absorbing the largest sweetened condensed milk volumes for caramel, fudge, and filling production. Procurement centralization among multi-state bakery chains in the southeastern United States is compressing supplier margins and unbundling technical support from commodity pricing.
- Food Service:Quick-service restaurants, institutional cafeterias, and catering operations requiring shelf-stable dairy for beverage and sauce applications. Distribution through national procurement platforms is displacing direct relationships with regional dairy cooperatives.
- Retail:Supermarket and convenience store channels serving home consumers with smaller-format SKUs. Health Canada and FDA label redesign requirements are forcing portfolio rationalization for cross-border retail programs.
- Home Cooking:Episodic demand from individual consumers preparing traditional recipes, concentrated in Latin American immigrant communities across the southwestern United States and Mexican border states. Volume per transaction remains lowest among all end-user categories.
Bakery demand anchors procurement volumes while food service channels are climbing the fastest as distributor consolidation accelerates.
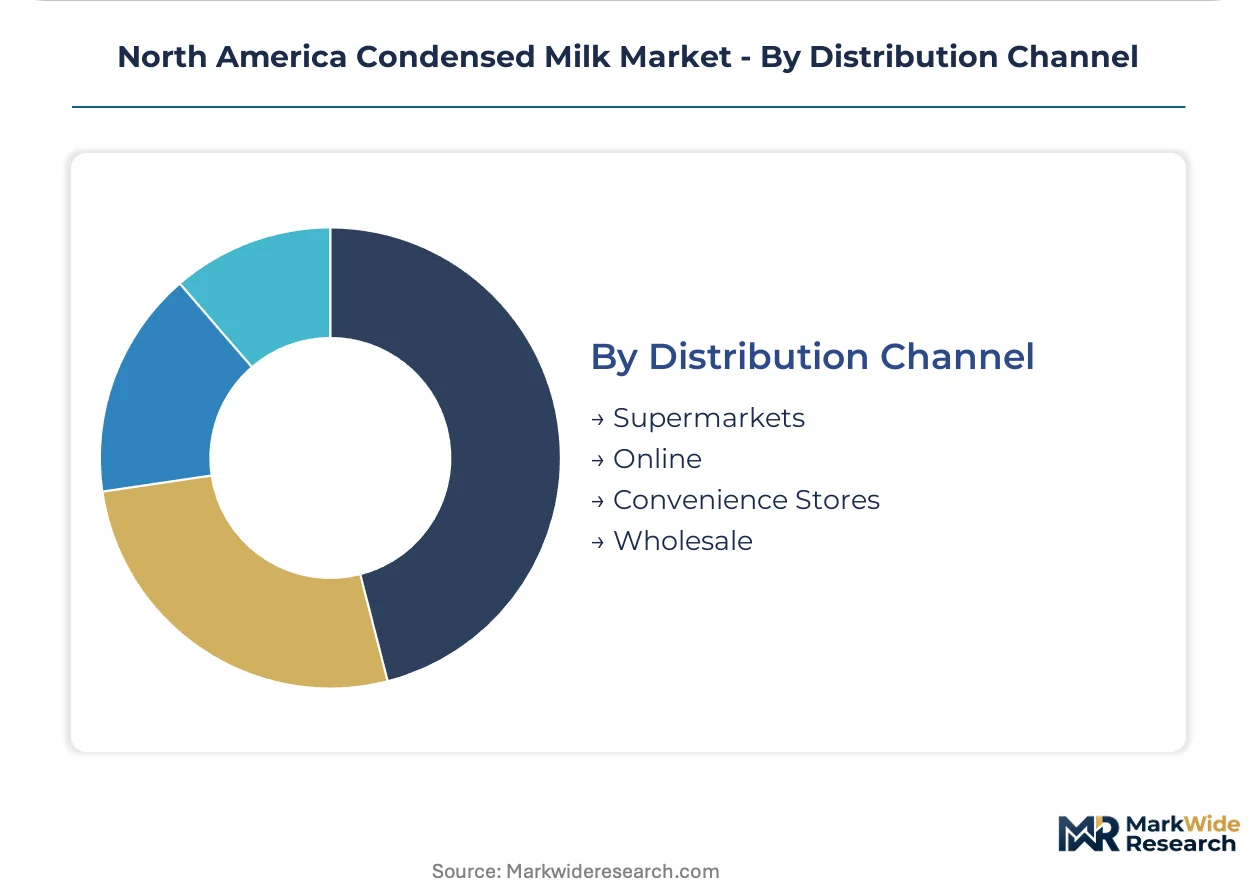
Distribution Channel:
Channel selection determines margin capture and customer data access, with direct wholesale relationships offering price protection at the cost of brand control.
- Supermarkets:Dominant retail channel for branded evaporated and sweetened condensed milk, with shelf placement determined by slotting fee negotiations and category management relationships. Southeastern U.S. grocery consolidation is reducing viable retail banners for mid-sized processors.
- Wholesale:Food service distributors and buying cooperatives serving bakery and restaurant accounts with bulk formats and technical specification support. Procurement platform centralization is compressing negotiation cycles and standardizing contract terms across multi-state networks.
- Online:E-commerce penetration for specialty and flavored variants, with subscription models gaining traction among metropolitan home bakers seeking convenience. Direct-to-consumer fulfillment bypasses traditional distributor markups but requires packaging adaptation for parcel shipping.
- Convenience Stores:Limited SKU availability in smaller-format retail, serving emergency and travel-oriented purchase occasions. Price realization exceeds supermarket channels due to reduced price sensitivity and limited competitive alternatives.
Supermarkets retain the broadest reach while wholesale channels are expanding most quickly as food service procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing capacity clusters along the southern tier of the United States and central Mexico, with cross-border raw milk corridors linking Chihuahua agricultural zones to Texas manufacturing facilities. FDA standards of identity enforcement and Health Canada labeling mandates create divergent compliance costs for integrated North American suppliers.
United States
Industrial bakery demand concentrates in Texas and California, where artisanal dessert manufacturers scale caramel and confectionery production. The FDA's updated dairy labeling standards compel reformulation of fat content claims and solids concentration disclosures. Wisconsin and New York retain legacy canning infrastructure serving regional dairy cooperatives with established supermarket distribution networks.
Mexico
Central dairy belt expansion in Jalisco and Guanajuato reconfigures continental supply dynamics through raw milk sourcing corridors. Mexico's national dairy regulator enforces sanitary certification and labeling standards that processors must satisfy for domestic market access. Mexico City Metro anchors food service procurement centralization, with distributor platforms displacing direct bakery relationships.
Canada
Metropolitan retail channels in Toronto and Vancouver drive adoption of aseptic carton formats favored by Health Canada packaging waste regulations. The PMRA administers agricultural chemical residue limits affecting cross-border trade in dairy ingredients. Quebec and Ontario dairy processing clusters negotiate primarily through wholesale distributor intermediaries rather than direct food service accounts.
Southeastern United States
Florida and Georgia institutional food service sustains evaporated milk volume despite slower inventory velocity than sweetened formats. Consolidated procurement by multi-state bakery chains compresses supplier margins and unbundles technical support from commodity pricing. Dairy processing clusters in the region now serve expanding food service networks through centralized distributor platforms.
Southwestern United States
Latin American immigrant communities across Arizona and New Mexico generate episodic home cooking demand for traditional dessert preparations. Border-state logistics infrastructure enables shelf-stable distribution into markets lacking refrigerated supply chain coverage. Regional processors leverage existing canning lines to maintain margin protection against input cost volatility.
North America Condensed Milk Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation expertise and regional dairy sourcing relationships. The vendor base spans multinational food conglomerates with cross-border processing footprints, mid-sized cooperatives anchored in specific dairy belts, and private-label specialists serving retail consolidation. Three archetypes dominate: scale-driven processors with integrated raw milk access, flavor-variant innovators targeting metropolitan convenience demand, and private-label contractors for supermarket consolidation. Competitive moves concentrate on pouch format adoption for food service efficiency and reformulation cycles responding to sugar disclosure mandates.
Among Switzerland-based conglomerates, Nestlé S.A. exemplifies the scale-driven archetype with multi-country processing footprints securing raw milk access across jurisdictions. Eagle Family Foods Group LLC and The J.M. Smucker Company represent divergent positioning strategies within the North American shelf-stable dairy tier, with the former anchoring industrial bakery supply relationships and the latter extending brand recognition through retail grocery networks. These three entities occupy positions that illustrate how integrated sourcing, specialized production focus, and channel-specific brand equity constitute distinct viable paths.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Eagle Family Foods Group LLC |
| The J.M. Smucker Company |
| Santini Foods, Inc. |
| Goya Foods Inc. |
| Meijer, Inc. |
| Meadow Gold Dairies |
| Arla Foods amba |
| O-AT-KA Milk Products Cooperative, Inc. |
| Others |
Pricing and Supply Chain Analysis
The I-35 corridor freight lanes linking Texas dairy processing clusters to southeastern U.S. distribution hubs concentrate cost dynamics for shelf-stable dairy. Elevated fuel surcharges on this route amplify price differentiation between bulk food service procurement and retail supermarket channels.
Pricing Analysis
FDA standards of identity dictate the pricing tier structure across sweetened and evaporated milk categories. Three-tier pricing structure across premium, standard, and economy levels separates aseptic pouch formats from conventional cans and private-label alternatives. Cost compression in standard-tier canned formats is intensifying because of sugar price volatility and raw milk procurement spikes. Food service distributors demonstrate the highest price sensitivity due to consolidated procurement volumes, while metropolitan retail consumers show lowest sensitivity for convenience-oriented flavored variants.
Supply Chain Analysis
Raw milk sourcing draws from Wisconsin, New York, and Jalisco dairy belt expansion zones. Sweetened condensed milk production rests on sucrose supply contracts, multi-layer flexible film packaging, and aseptic filling equipment. Single-source vulnerability concentrates in Mexican agricultural zones exposed to drought cycles. Distribution runs through national food service procurement platforms serving multi-state bakery chains and quick-service restaurant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support represent a service-attach opportunity expanding faster than commodity condensed milk volume. After-sales R&D partnerships for customized caramel and confectionery applications generate recurring revenue streams.
For Market Incumbents: Entrench position through backward integration into Jalisco and Guanajuato raw milk corridors, securing captive supply against input volatility. Expand aseptic pouch manufacturing capacity in Texas to capture food service procurement centralization. FDA reformulation timelines threaten R&D bandwidth at mid-sized competitors.
For New Entrants and Emerging Players: Pursue white-space penetration in flavored condensed milk variants targeting coastal metropolitan home bakers. Underdeveloped channels exist in direct-to-consumer subscription models for specialty dessert ingredients. Go-to-market through e-commerce platforms bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Regional dairy cooperatives with established supermarket distribution and legacy canning infrastructure represent compelling acquisition targets. Long-term viability hinges on adapting to sugar reduction mandates and plant-based substitution threats. Watch for FDA enforcement actions on standards of identity as inflection indicators for consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Format Manufacturing Scale-Up | Aseptic filling investments displace regional processors dependent on refrigerated distribution in Texas and California. |
| Backward Integration into Raw Milk Supply | Captive sourcing corridors across Chihuahua and Jalisco reduce input volatility for integrated North American suppliers. |
| Flavored Variant Portfolio Extension | Chocolate and dulce de leche formats capture convenience-seeking home bakers in metropolitan coastal markets. |
| Food Service Procurement Platform Partnership | Direct relationships with national bakery chains compress negotiation cycles and standardize contract terms. |
| Sugar Reduction Reformulation Program | Evaporated milk variants with modified solids profiles address FDA disclosure mandates and capture reformulation demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing executives, food service procurement managers, bakery chain technical directors, and retail category buyers. Secondary validation drew from FDA standards of identity filings, Health Canada nutrition fact table updates, USDA dairy production statistics, and customs trade records. Bottom-up volume triangulation across product format, packaging type, and end-user segment reconciled with top-down market sizing.
Calibration against historical volume trajectories and input cost indices anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-user category, and distribution channel. CAGRs were derived from regression analysis of demand drivers and supply capacity expansion. Forecast inputs incorporated sugar price indices, raw milk procurement cost trends, and regulatory compliance burden projections.
Macroeconomic conditions sit as an overlay; deviation in freight fuel costs and dairy commodity prices would shift the trajectory. Forecasts reflect documented assumptions on cross-border trade continuity and regulatory enforcement intensity. Material shifts in FDA standards of identity implementation or Mexican sanitary certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Europe Yogurt Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Table Butter Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
United States Yogurt Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Skimmed Milk Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Cheese Color Market