
 Organic Milk Powder Market | 2026-2036
Organic Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Milk Powder Market Analysis
Precision fermentation and enzymatic processing is rewriting how organic milk proteins are standardized for powder production. Nestlé S.A. leverages its vertically integrated dairy network across Switzerland and France to secure certified organic raw milk volumes. Arla Foods amba anchors its powder output through cooperative farmer contracts in Denmark and Sweden with strict pasture-access protocols. Fonterra Co-operative Group dominates organic skimmed powder exports from New Zealand into Asian nutritional markets.
Organic milk powder is dehydrated dairy product manufactured from heat-treated organic milk through spray-drying or roller-drying, retaining minimum protein levels while eliminating moisture to below five percent for shelf stability; it serves as a functional ingredient in infant nutrition, bakery formulations, and beverage fortification. Full cream powder captures the largest value pool due to fat-retention benefits in premium infant formula applications, while functional powder with added vitamins and minerals generates the highest per-kilogram margins. Skimmed powder competes aggressively among food producers seeking lower-fat bases for yogurt and ice cream production, whereas instant powder with enhanced solubility properties occupies the fastest-growing niche in ready-to-drink beverage premixes.
EU organic regulations enforced by EFSA and the EU Green Deal farm-to-fork strategy mandate strict feed sourcing, pasture access documentation, and processing segregation that inflate compliance costs but create defensible barriers against conventional powder substitution. USDA organic certification administered through accredited state agencies governs US export eligibility and domestic labeling claims, while China's SAMR and GB standards impose additional residue testing for cross-border shipments. Stakeholders must monitor how pending EU F-Gas Regulation amendments on refrigeration gases affect spray-drying energy economics and facility upgrade timelines.
Market Dynamics
EU Green Deal farm-to-fork traceability mandates are forcing spray-drying facilities to segregate organic and conventional processing lines, inflating capital requirements while locking in compliant suppliers against price-based substitution from standard milk powder.
Growth Catalysts
- EFSA pasture-access documentation:Mandatory EU organic feed-chain verification creates captive demand for certified Dutch and Danish cooperative supply, insulating processors from commodity volatility.
- Precision fermentation standardization:Enzymatic protein tailoring enables functional powder grades with enhanced solubility for ready-to-drink beverage premixes.
- Asian nutritional markets:Import demand for organic skimmed powder in infant formula applications pulls New Zealand export volumes into premium channel positioning.
Market Restraints
- Organic feed input costs:Non-GMO soybean and alfalfa price volatility transmits directly to farm-gate organic milk premiums, compressing processor margins.
- Spray-drying energy economics:Pending EU F-Gas Regulation amendments on refrigeration gases threaten facility upgrade timelines and operating cost structures.
- Conventional powder substitution:Standard full cream milk powder from non-certified supply chains undercuts organic positioning in price-sensitive bakery and ice cream bases.
Strategic Opportunities
- USDA-certified export channels:Accredited state agency organic certification unlocks eligibility for US domestic labeling claims and cross-border premium positioning.
- Instant powder solubility innovation:Agglomeration technology convergence with vitamin microencapsulation opens ready-to-mix beverage formulations.
- China SAMR residue testing compliance:GB standards alignment creates first-mover advantage for processors with documented supply chain segregation protocols.
Industry Challenges
- Spray-drying technician specialization:Organic processing line segregation protocols require retraining of thermal engineering personnel on contamination prevention.
- Multi-jurisdiction certification timelines:Parallel EU organic, USDA, and China SAMR approval cycles extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Milk Powder Market |
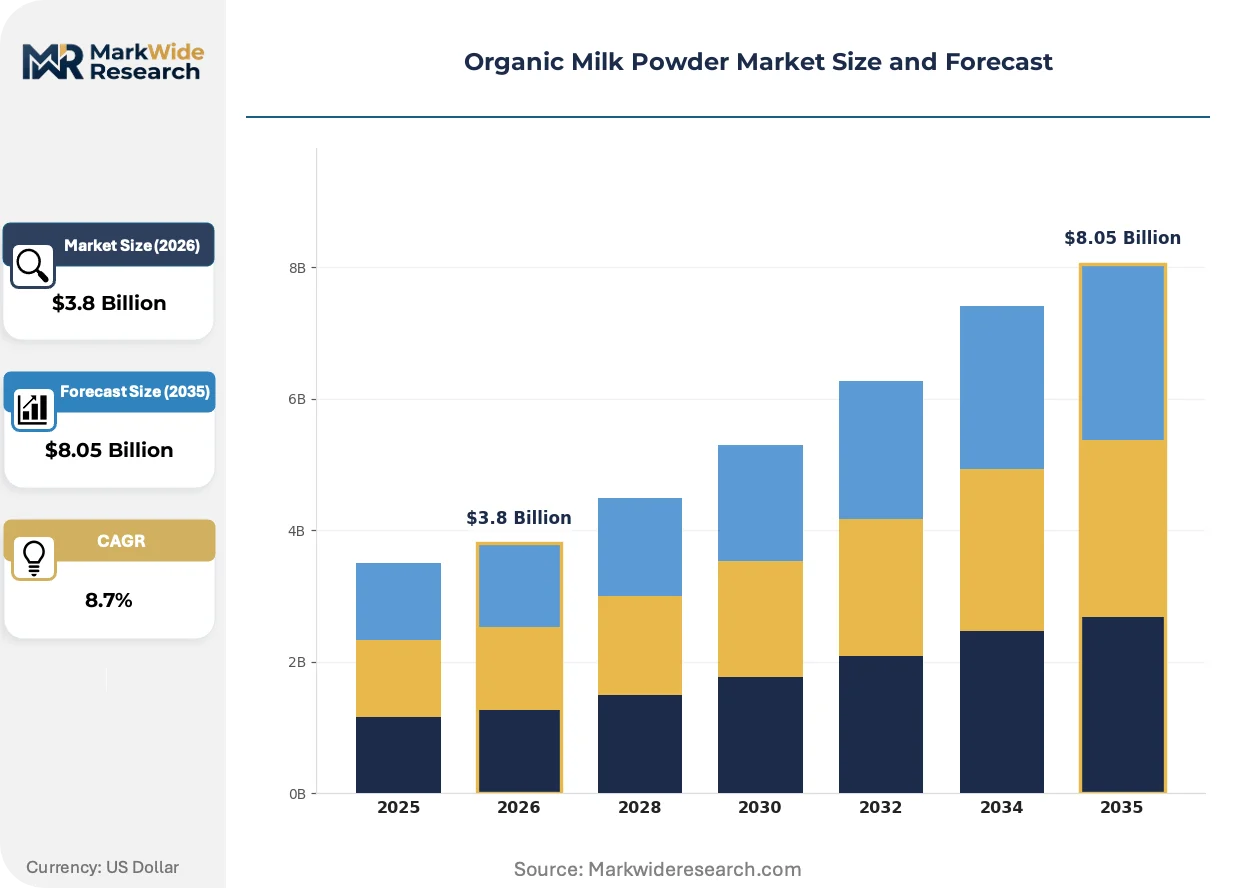
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Cream Powder, Skimmed Powder, Functional Powder, Instant Powder End User: Households, Food Producers, Nutritional Supplement Manufacturers, Bakeries Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Tins, Pouches, Bulk Packaging |
| Companies Covered | Nestlé S.A., Arla Foods amba, Fonterra Co-operative Group, Danone S.A., Organic Valley, Royal FrieslandCampina N.V., Lactalis Group, Abbott Laboratories, SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Milk Powder Market Emerging Trajectories
Dehydration technology and certification protocols are the primary axes of competitive differentiation, with enzymatic processing and energy-efficient drying systems reshaping how organic milk proteins are standardized and delivered to end-use markets.
Membrane filtration coupled with precision fermentation is hybridizing protein concentration methods for organic milk powder production. Infant formula manufacturers in Germany and the Netherlands are adopting these hybrid systems to achieve batch-to-batch consistency in protein profiles. This convergence is compressing the gap between artisan-scale organic supply and industrial-volume nutritional applications.
EU F-Gas Regulation amendments targeting hydrofluorocarbon phase-down are forcing spray-drying facilities to retrofit refrigeration-dependent moisture recovery systems. Industrial processors in the Netherlands and Denmark face compressed upgrade timelines to maintain operating permits. Full cream powder production lines with highest thermal loads are accelerating adoption of ammonia-based cooling alternatives.
Private-label procurement consolidation among European retail chains is displacing fragmented spot-market purchasing for organic milk powder. Branded infant formula manufacturers now contract directly with cooperative drying facilities in Denmark and Sweden, bypassing traditional ingredient traders. This channel compression is most visible in German and Dutch markets where Edeka, Albert Heijn, and Rewe centralize organic dairy sourcing decisions.
Organic Milk Powder Market Segmentation
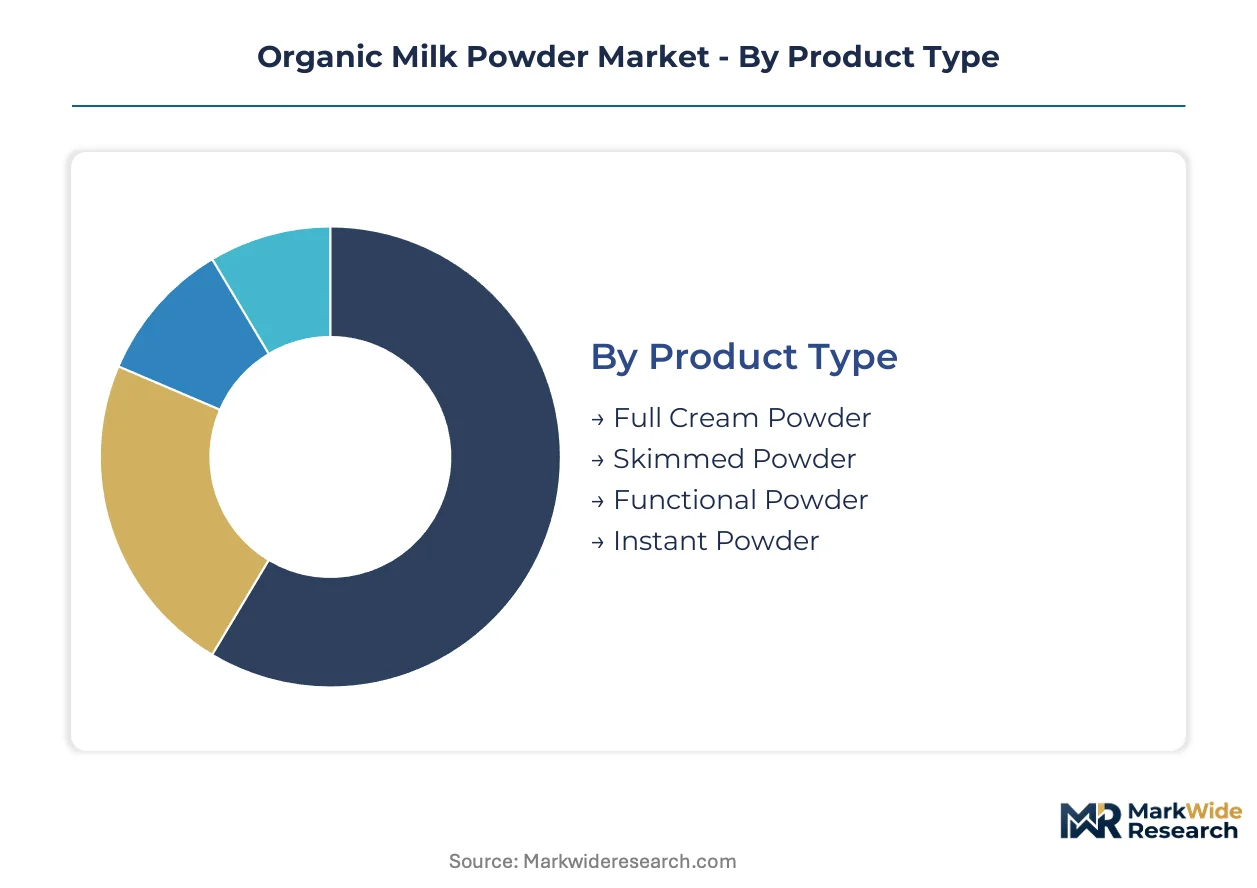
Segmentation in organic milk powder reflects divergent margin profiles across fat-retention grades, end-use certification requirements, and channel-specific packaging economics. Each dimension shapes procurement patterns and facility investment priorities differently.
Product Type:
Cost tier stratification separates commodity-grade dehydration outputs from value-added functional formulations with encapsulated micronutrients.
- Full Cream Powder:Retains natural milkfat at 26-28% concentration through low-temperature spray-drying, preserving flavor compounds for premium infant formula applications. German and Dutch manufacturers anchor procurement contracts around this grade due to EU organic pasture-access documentation requirements.
- Skimmed Powder:Fat content reduced below 1.5% via centrifugal separation before dehydration, delivering standardized protein bases for yogurt and ice cream production. Food producers in Denmark and Sweden leverage this grade for clean-label dairy alternatives where fat reduction drives formulation flexibility.
- Functional Powder:Vitamin and mineral fortification through microencapsulation during agglomeration.
- Instant Powder:Enhanced solubility via lecithin-treated particle engineering for ready-to-mix beverage applications.
Full cream powder holds installed capacity. Functional powder is rotating up the share rankings.
End User:
Application gravity concentrates in nutritional manufacturing where certification documentation commands price premiums over commodity food production.
- Nutritional Supplement Manufacturers:Infant formula producers demand batch-traceable organic protein with EFSA-compliant feed-chain verification, locking in multi-year supply agreements with Dutch cooperative dryers. This segment absorbs highest per-kilogram pricing for documented pasture-access protocols.
- Food Producers:Ice cream and yogurt manufacturers prioritize skimmed powder for fat-controlled formulations, sourcing through wholesale channels with less stringent traceability than nutritional applications.
- Households:Direct consumption through retail channels with instant-dissolve preferences.
- Bakeries:Bulk procurement of full cream powder for enriched dough applications.
Nutritional supplement manufacturers anchor volume commitments. Food producers are expanding spot-market flexibility.
Distribution Channel:
Customer type determines packaging format and certification documentation depth, with retail channels requiring consumer-facing organic labeling.
- Supermarkets:Private-label consolidation among Albert Heijn, Edeka, and Rewe chains centralizes procurement decisions, bypassing traditional ingredient traders. Shelf-ready tins and pouches dominate with dual-language labeling for cross-border EU sales.
- Wholesale:Food service and industrial manufacturers source bulk bags with minimal packaging overhead, prioritizing cost efficiency over consumer branding.
- Online Retail:Direct-to-consumer subscription models for specialty organic brands.
- Specialty Stores:Premium positioning through bio-shop channels with extended shelf-life formats.
Supermarkets hold procurement consolidation momentum. Online retail is climbing the fastest as subscription models penetrate household segments.
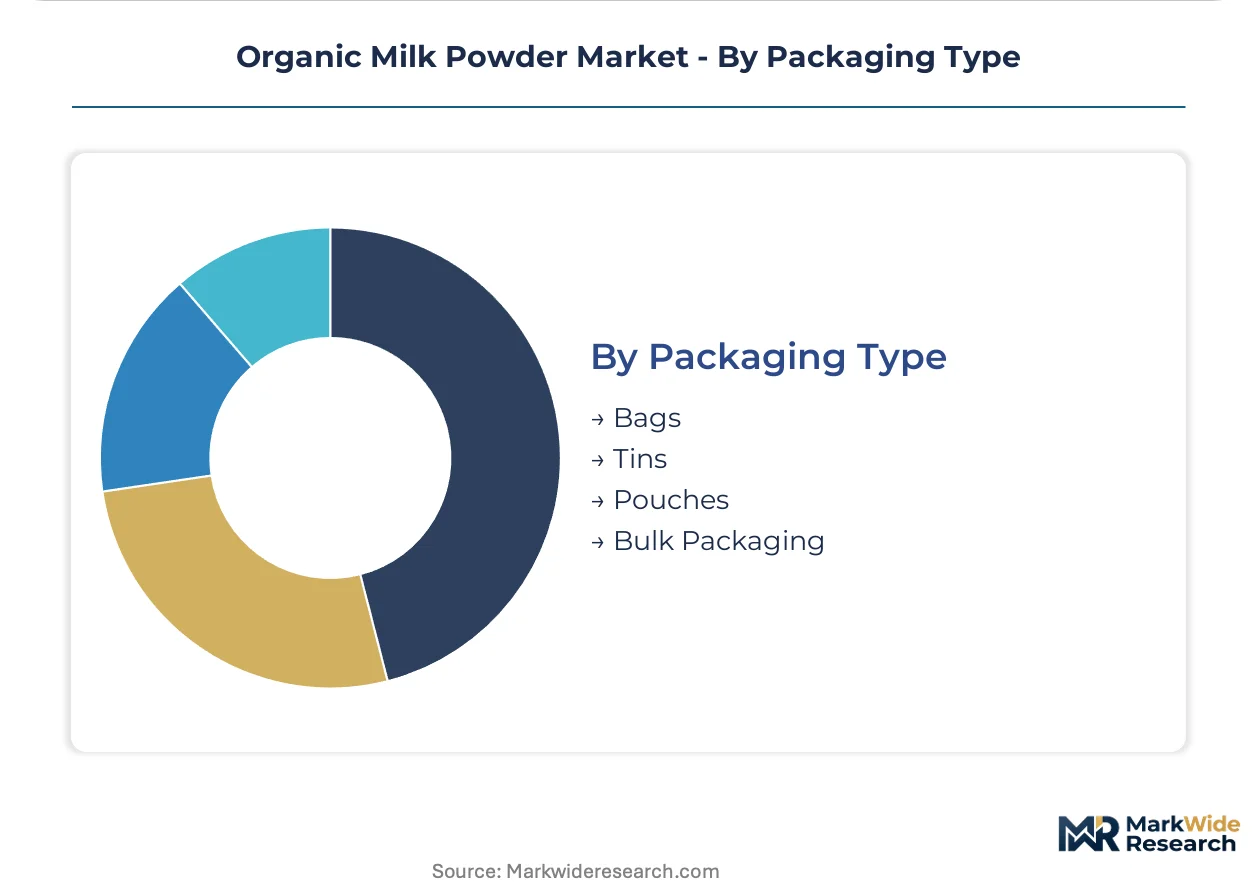
Packaging Type:
Volume scale and shelf-stability requirements differentiate industrial bulk from consumer-facing preservation formats.
- Bulk Packaging:25kg multi-ply paper sacks with nitrogen flushing serve industrial food producers and bakeries, minimizing unit economics for high-throughput manufacturing. Dutch spray-drying facilities optimize line configurations around bulk bagging throughput.
- Tins:Metal canisters with double-seamed closures preserve lipid stability in full cream powder for premium household and nutritional applications.
- Bags:Laminated flexible packaging for mid-volume food service distribution.
- Pouches:Single-serve and resealable formats targeting convenience-oriented retail channels.
Bulk packaging holds manufacturing line dominance. Pouches are gaining share fastest through convenience retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infant formula manufacturers concentrate procurement decisions in Germany and the Netherlands, where cooperative drying facilities anchor European organic milk powder supply. Asian nutritional markets pull New Zealand export volumes into premium channel positioning. US domestic demand consolidates around USDA-certified supply chains serving retail and nutritional applications.
Germany
EFSA pasture-access documentation requirements lock in multi-year supply agreements between infant formula producers and Dutch cooperative dryers. The EU Green Deal farm-to-fork strategy mandates feed-chain verification that German manufacturers leverage for premium positioning. Bavarian processing clusters coordinate with Randstad spray-drying facilities to maintain organic line segregation protocols.
Netherlands
FrieslandCampina and Arla operate major spray-drying facilities serving private-label and branded channels across Europe with strict contamination prevention standards. EFSA-enforced EU organic regulations govern feed sourcing and processing segregation that inflate compliance costs but create supplier lock-in. Randstad industrial corridors concentrate organic powder capacity for cross-border German and Belgian nutritional manufacturing.
New Zealand
Fonterra dominates organic skimmed powder exports into Asian infant formula markets through documented supply chain segregation protocols. The country's national dairy regulator enforces residue testing alignment with China SAMR GB standards for cross-border premium positioning. Canterbury and Waikato dairy cooperatives anchor pasture-based organic milk collection networks serving dehydration facilities.
United States
USDA organic certification administered through accredited state agencies governs domestic labeling claims and export eligibility for nutritional supplement manufacturers. Organic Valley cooperative structures aggregate Midwest dairy supply for powder production serving retail and household segments. Wisconsin and California dairy clusters specialize in organic full cream powder for bakery and beverage fortification applications.
China
SAMR GB standards impose additional residue testing requirements that favor processors with documented supply chain segregation protocols. Import demand for organic skimmed powder in infant formula applications creates first-mover advantages for New Zealand and European exporters with multi-jurisdiction certification. Yangtze River Delta nutritional manufacturing clusters concentrate procurement of certified organic protein for domestic formula brands.
Organic Milk Powder Market Vendor Landscape
Channel-controlling players compete with product-specialist players across cooperative, corporate, and private-label archetypes. Cooperative structures dominate European supply through farmer-owned drying facilities with captive raw milk access. Corporate integrators leverage vertically controlled dairy networks for batch-to-batch consistency. Private-label specialists serve retail chain consolidation with flexible packaging formats. Dominant competitive moves include direct procurement contracting that bypasses traditional ingredient traders, and precision fermentation technology licensing for functional powder grades.
Within the cooperative archetype, Arla Foods amba and Fonterra Co-operative Group exemplify farmer-owned structures with integrated drying capacity. Nestlé S.A. occupies a position representing corporate vertical integration across Swiss and French dairy networks. These three anchors illustrate how governance models—cooperative ownership versus corporate control—shape competitive positioning in organic milk powder procurement and processing.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Arla Foods amba |
| Fonterra Co-operative Group |
| Danone S.A. |
| Organic Valley |
| Royal FrieslandCampina N.V. |
| Lactalis Group |
| Abbott Laboratories |
| SunOpta Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Dutch spray-drying facilities is tightening supplier leverage and compressing procurement timelines for German infant formula manufacturers, while EU F-Gas Regulation retrofit costs transmit directly into organic powder premiums. This utilization squeeze rewards processors with certified line segregation against price-based substitution from conventional powder traders.
Pricing Analysis
Cost-plus contracts indexed to organic soybean and alfalfa feed prices dominate procurement between Dutch cooperative dryers and German nutritional manufacturers, insulating farm-gate premiums from commodity volatility. Three-tier pricing structure across EFSA-certified premium, EU organic standard, and conventional economy levels reflects pasture-access documentation depth. Pricing pressure stems from non-GMO feed input volatility transmitting through contract indexation clauses. Food producers sourcing skimmed powder for ice cream bases exhibit highest price sensitivity, while infant formula manufacturers absorb premiums for batch-traceable full cream grades.
Supply Chain Analysis
Contract-manufacturing concentration rests with FrieslandCampina and Arla spray-drying facilities in the Netherlands and Denmark, where cooperative structures control organic line capacity. Raw material flows draw from pasture-based dairy networks in Sweden, German Bavarian clusters, and New Zealand Canterbury cooperatives, with organic feed sourcing tethered to non-GMO soybean and alfalfa markets. Single-source vulnerability concentrates in Randstad industrial corridors where EU F-Gas retrofit timelines threaten operating permit continuity. Distribution runs through private-label retail consolidation at Albert Heijn, Edeka, and Rewe, bypassing traditional ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where EFSA pasture-access documentation and EU Green Deal traceability mandates create switching-cost barriers against conventional powder substitution. Network effects concentrate in cooperative drying facilities with captive farmer supply and multi-jurisdiction certification infrastructure.
For Market Incumbents: Harden EFSA-compliant feed-chain verification through backward integration into organic alfalfa sourcing, locking in farm-gate supply against price volatility. Expand ammonia-based cooling retrofit capacity ahead of EU F-Gas Regulation deadlines to preserve operating permits. Prioritize precision fermentation licensing for functional powder grades to defend margin position against enzymatic processing entrants.
For New Entrants and Emerging Players: Build out instant powder solubility capabilities targeting ready-to-mix beverage premixes, where agglomeration technology gaps exist among established dryers. Penetrate online retail subscription channels with specialty organic positioning, bypassing supermarket private-label consolidation. Anchor go-to-market strategy around USDA-certified export eligibility for US nutritional supplement manufacturers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative drying facilities with multi-year supply agreements to German infant formula producers. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetypes include mid-cap processors with documented China SAMR GB standards alignment. Monitor EU F-Gas Regulation amendment implementation timelines as inflection signal for facility upgrade capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Supply | Captive alfalfa sourcing secures farm-gate premiums against EFSA verification requirements. |
| Ammonia-Based Cooling Retrofit | EU F-Gas Regulation compliance preserves Randstad facility operating permits. |
| Precision Fermentation Licensing | Enzymatic protein tailoring opens functional powder grades for ready-to-drink applications. |
| China SAMR Certification Investment | GB standards alignment creates first-mover positioning in Yangtze River Delta formula manufacturing. |
| Direct-to-Consumer Subscription Launch | Bypasses Albert Heijn and Edeka private-label consolidation with specialty organic branding. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU organic certification databases, EFSA feed-chain documentation registries, and cooperative processor financial disclosures. Primary interviews engaged spray-drying facility engineers, infant formula procurement directors, organic dairy cooperative managers, and EFSA regulatory compliance officers. Secondary validation drew from EU Green Deal implementation trackers, USDA organic certification records, China SAMR GB standards filings, and customs trade data for organic dairy powder flows. Bottom-up capacity assessments across Dutch and Danish facilities were triangulated against top-down demand modeling from nutritional supplement manufacturers.
Forecast inputs incorporate fat-retention grade segmentation, end-use certification requirements, and channel-specific packaging economics across the projection horizon. Modeled dimensions span full cream versus skimmed versus functional powder grades, nutritional supplement versus food producer versus household end users, and supermarket versus wholesale versus online retail channels. CAGRs were derived from installed capacity utilization trends and import demand elasticity in Asian nutritional markets. Industry-specific inputs include EU F-Gas Regulation retrofit timelines and organic feed price indexation clauses in cooperative supply contracts.
Stress conditions across organic soybean price volatility, EU refrigeration gas phase-down schedules, and China import quota fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on pasture-access compliance rates and spray-drying capacity expansion timelines. Quarterly review of EFSA audit completion rates and Randstad facility permit statuses is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Natural Cheese Market
Dairy Products
Greek Yogurt Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Fluid Milk Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Flavored Yogurt Market
Dairy Products
North America Dairy Market
Dairy Products
Plain Yogurt Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Organic Cheese Market
Dairy Products
Goat Milk Powder Market
Dairy Products
Non-Fat Milk Market