
 Probiotic Yogurt Market | 2026-2036
Probiotic Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Yogurt Market Outlook
Specialized fermentation microbiologists and dairy process engineers is redrawing competitive boundaries in probiotic yogurt manufacturing. Danone S.A. leverages its strain libraries and clinical validation programs to anchor premium positioning across European and North American retail channels. Nestlé S.A. sustains broad portfolio depth spanning pediatric and adult gut health applications. Chobani LLC differentiates through Greek yogurt specialization and domestic U.S. production scale.
Probiotic yogurt comprises fermented milk products containing live bacterial cultures, typically Lactobacillus and Bifidobacterium strains at minimum viable counts of 10^6 to 10^9 colony-forming units per gram at consumption, produced through controlled fermentation at 37–45°C followed by cooling to arrest acidification and preserve culture viability. Its primary commercial purpose centers on delivering documented digestive and immune health benefits through daily dietary integration. Greek yogurt commands the largest value share within product type segmentation due to its protein density and premium price positioning, while drinks represent the fastest-growing format driven by convenience-oriented consumption occasions. Non-dairy bases derived from oat, coconut, and almond substrates are expanding fastest among ingredient categories as lactose-intolerant and vegan consumer pools deepen.
EFSA's health claims regulation and FDA's qualified health claims framework govern probiotic labeling and substantiation requirements across Europe and the United States, directly influencing which strains manufacturers select for commercial deployment and how products communicate benefits at point of sale. China's National Health Commission maintains an approved strain list that determines market access for imported probiotic yogurt formulations. Stakeholders must monitor evolving strain-specific approval pathways and adapt R&D pipelines to jurisdiction-by-jurisdiction compliance thresholds rather than pursuing universal formulations.
Market Dynamics
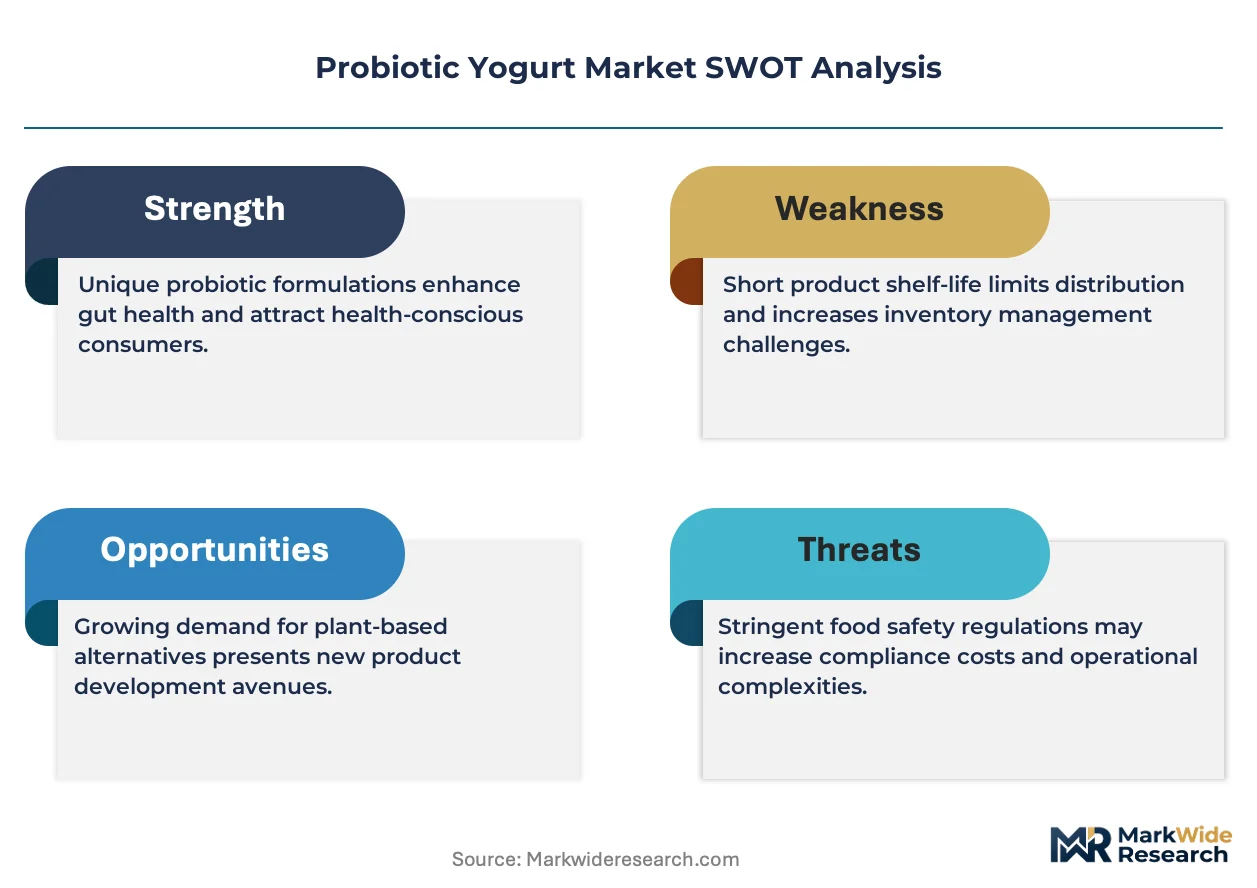
Strain-specific labeling mandates from EFSA and FDA are forcing manufacturers to rebuild R&D pipelines around clinically validated cultures rather than generic probiotic claims, compressing formulation flexibility while raising barriers to new market entrants.
Growth Catalysts
- EFSA Health Claims Regulation:Strain-specific substantiation requirements in Europe are concentrating demand toward documented cultures, rewarding manufacturers with clinical libraries and filtering out commodity suppliers.
- Greek yogurt protein density:Elevated protein positioning commands premium shelf placement in US retail channels, anchoring household penetration among fitness-oriented consumers.
- Oat substrate fermentation:Advances in enzymatic hydrolysis are unlocking viable non-dairy alternatives, expanding addressable pools beyond lactose-intolerant populations into vegan and flexitarian segments.
Market Restraints
- Live culture cold chain:Refrigerated distribution requirements constrain rural penetration and inflate logistics costs relative to ambient-stable functional foods.
- Strain approval concentration:China's National Health Commission maintains a restricted import list, creating regulatory bottlenecks for multinational manufacturers seeking market access.
- Fermentation input volatility:Organic milk and alternative base commodity prices swing with agricultural yields, compressing margin predictability for clean-label positioned products.
Strategic Opportunities
- Pediatric gut health applications:Underdeveloped positioning for children under twelve creates white space for strain-specific formulations with age-appropriate dosing protocols.
- Foodservice channel expansion:Healthcare cafeterias and corporate wellness programs represent untapped bulk consumption venues beyond conventional retail.
- Dual carbon alignment:China's national emissions targets are redirecting state support toward low-carbon fermentation infrastructure, advantaging early movers in facility retrofitting.
Industry Challenges
- Fermentation microbiologist scarcity:Specialized expertise in culture isolation and stability testing commands premium compensation, constraining mid-tier manufacturer scale-up velocity.
- Multi-jurisdiction compliance timelines:Simultaneous navigation of EFSA, FDA, and NHC approval pathways extends product launch cycles and fragments R&D resource allocation.
- Legacy dairy equipment retrofitting:Transitioning conventional yogurt lines to precision temperature-controlled probiotic fermentation requires substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Yogurt Market |
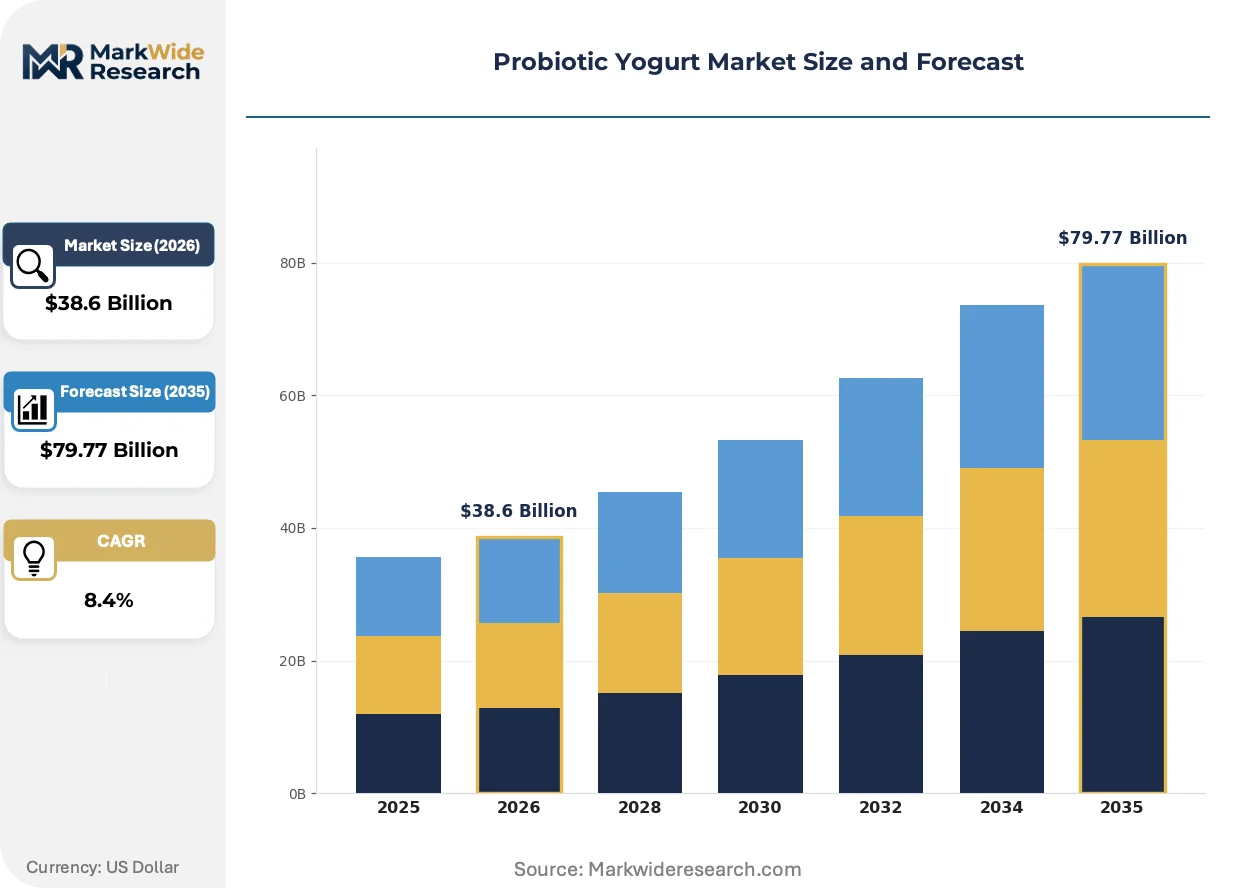
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drinks, Greek Yogurt, Frozen Yogurt, Regular Yogurt Ingredient: Fermented Milk, Non-Dairy Bases, Flavoring Agents, Sweeteners Packaging Type: Cups, Tetra Packs, Bottles, Pouches Consumer Type: Health-Conscious Individuals, Families, Fitness Enthusiasts, Children |
| Companies Covered | Danone S.A., Nestlé S.A., Chobani LLC, Yakult Honsha Co., Ltd., General Mills Inc., Arla Foods amba, FAGE International S.A., Lactalis Group, Lifeway Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Yogurt Market Strategic Shifts
Clean-label fermentation protocols and precision culture engineering are compressing the gap between artisan positioning and industrial scale, redefining how manufacturers balance viability guarantees with ingredient minimalism.
High-throughput screening of psychrotolerant strains is supplanting conventional thermophilic culture selection in premium product development. Nordic and Alpine dairy cooperatives are adopting these cold-adapted cultures to extend shelf stability without artificial preservatives. The technology is enabling longer distribution radii from centralized fermentation facilities, consolidating regional production footprints.
EFSA's 2023 updated guidance on gut microbiome health claims is tightening evidentiary standards for immune and digestive benefit communications. Manufacturers must now submit strain-specific human intervention studies rather than relying on genus-level literature reviews. German and Dutch market entrants face the steepest compliance curves given their historical reliance on legacy formulation portfolios.
Direct-to-subscription models are capturing recurring purchase commitments from urban households seeking personalized strain rotations. These platforms bypass conventional retail slotting fees while capturing consumption data that informs iterative formulation. Subscription penetration concentrates in US coastal metropolitan corridors where convenience premiums outweigh per-unit cost sensitivity.
Probiotic Yogurt Market Segmentation
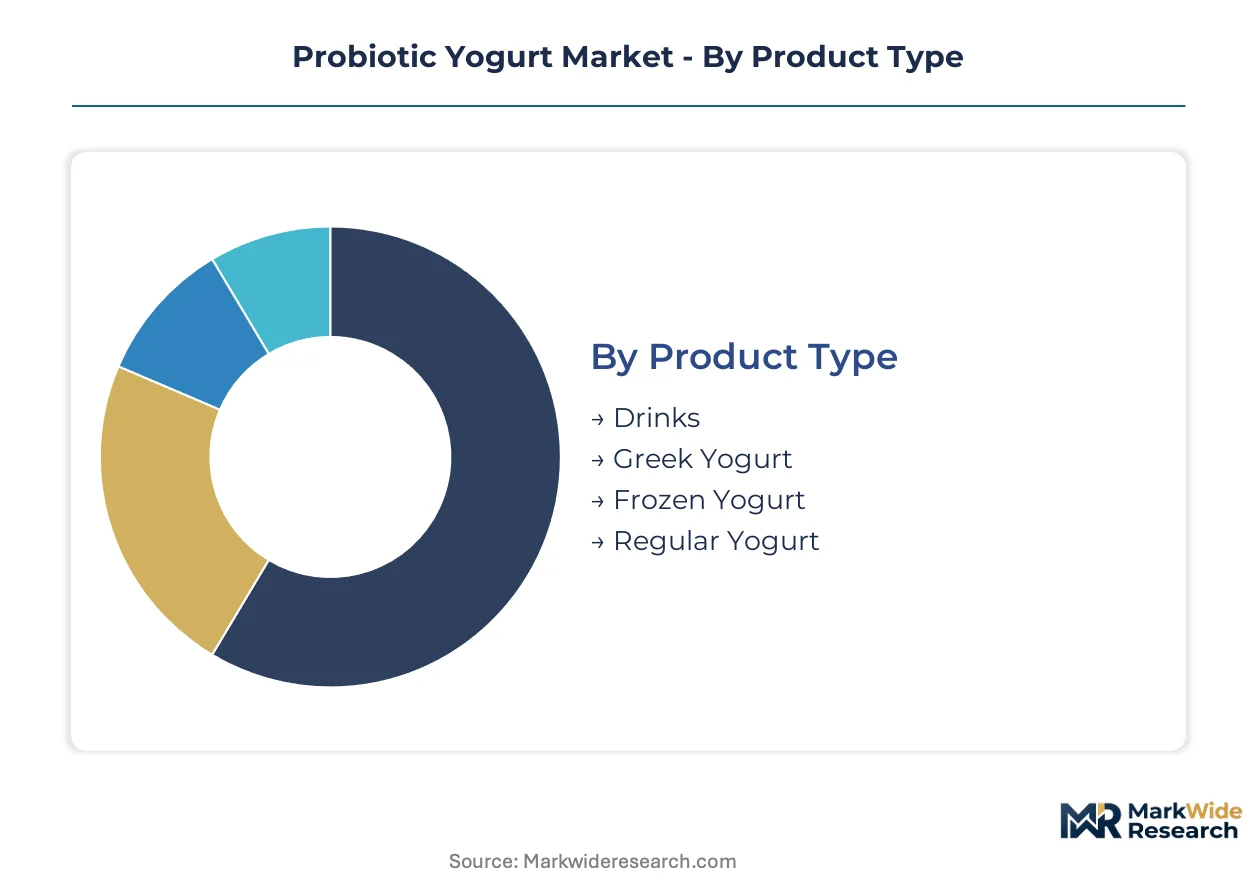
Probiotic yogurt manufacturers navigate distinct technical and commercial requirements across product formats, substrate choices, and consumption occasions. Segmentation discipline determines which strain libraries, fermentation protocols, and cold-chain investments align with specific consumer willingness-to-pay thresholds.
Product Type:
EFSA's strain-specific substantiation rules and FDA's qualified health claims framework create divergent compliance burdens across formats, with spoonable products facing stricter viability labeling than drinkable alternatives.
- Greek Yogurt:Strained fermentation yields protein concentrations of 15–20 grams per serving, creating premium positioning in US retail channels. Demand concentrates among fitness-oriented households in California and Texas, where protein density justifies price premiums over conventional yogurt.
- Drinks:Liquid format enables lower viscosity formulations with accelerated gastric emptying, suited to on-the-go consumption. Convenience-driven uptake in German urban centers and Chinese tier-one cities is displacing traditional breakfast occasions.
- Frozen Yogurt:Blast-freezing protocols preserve culture viability at sub-zero temperatures, extending shelf stability for impulse purchase channels.
- Regular Yogurt:Standard set-style fermentation maintains the broadest manufacturing equipment compatibility across legacy dairy infrastructure.
Greek yogurt handles the majority of throughput; drinks are expanding most quickly on share.
Ingredient:
Cost tier differentiation separates commodity substrates from precision-engineered alternatives, with enzymatic processing investments determining margin structure.
- Fermented Milk:Controlled lactose fermentation at 37–45°C produces lactic acid concentrations of 0.8–1.2%, establishing the baseline probiotic delivery vehicle. Organic milk sourcing in Denmark and Wisconsin commands supply premiums that filter through to shelf pricing.
- Non-Dairy Bases:Oat, coconut, and almond substrates require enzymatic hydrolysis to achieve fermentable carbohydrate profiles mimicking dairy lactose. German and Dutch manufacturers lead process innovation, capturing vegan and flexitarian demand pools beyond lactose-intolerant populations.
- Flavoring Agents:Natural fruit purees and botanical extracts replace artificial flavor systems in clean-label positioning.
- Sweeteners:Stevia and monk fruit extracts enable reduced-sugar claims without compromising culture viability during fermentation.
Fermented milk handles the majority of throughput; non-dairy bases are gaining share fastest.
Packaging Type:
Customer type determines format selection, with single-serve convenience commanding different structural requirements than household-scale purchasing.
- Cups:Polypropylene containers with foil lidding provide oxygen barrier properties essential for aerobic culture preservation. US retail channels favor 150-gram single-serve formats, while European markets accept 500-gram family sizes.
- Bottles:HDPE and PET structures enable resealable consumption across multiple occasions, suited to drinkable formulations. Chinese convenience store penetration drives demand for 300-milliliter formats with extended ambient distribution tolerance.
- Tetra Packs:Aseptic carton technology extends unrefrigerated shelf life for ambient-stable probiotic derivatives.
- Pouches:Flexible film structures reduce material weight for children's snacking occasions and foodservice portion control.
Cups handle the majority of throughput; bottles are climbing fastest on share.
Consumer Type:
Application-specific formulation requirements create distinct R&D priorities across demographic targets, with pediatric and clinical applications demanding the most stringent strain validation.
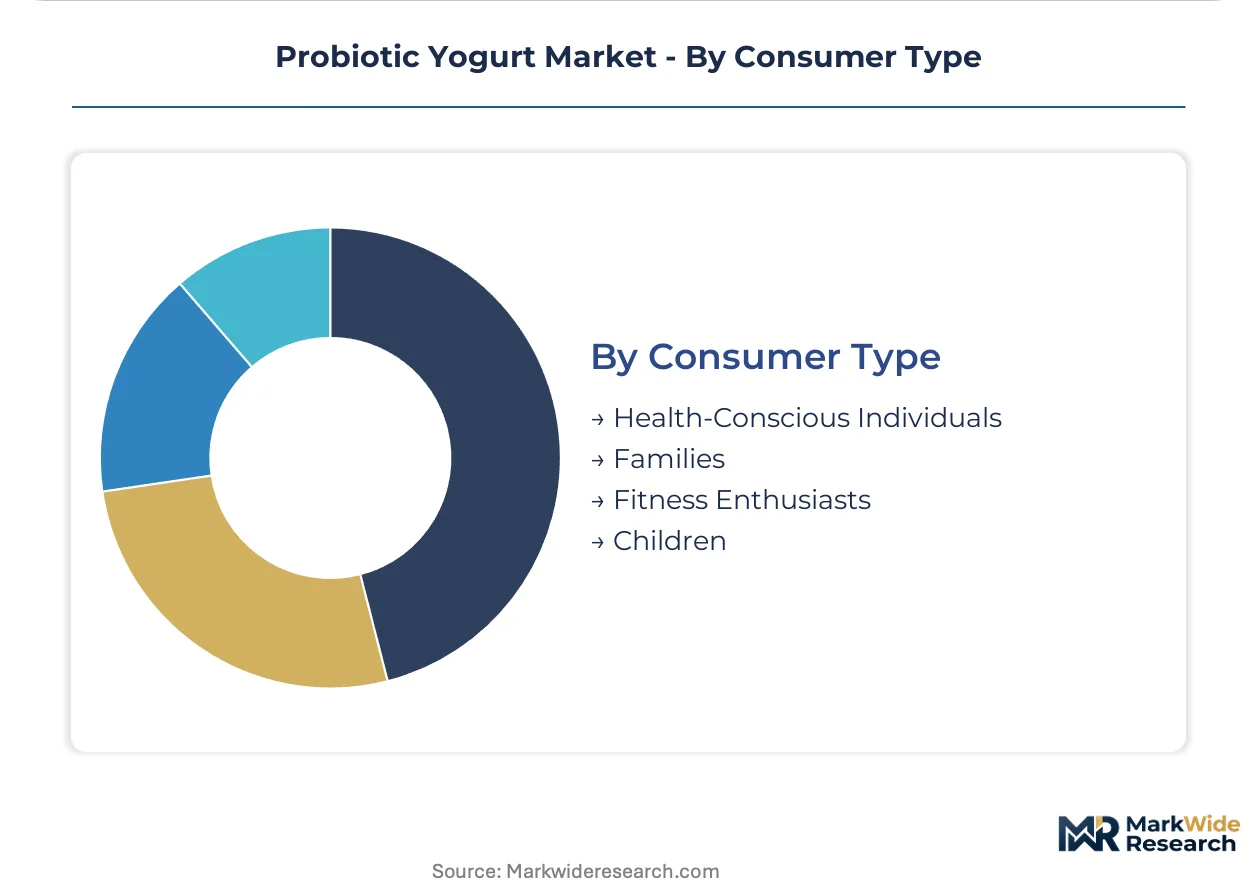
- Health-Conscious Individuals:Daily consumption habits prioritize strain diversity and documented CFU counts at expiration. US coastal metropolitan households subscribe to direct-to-consumer platforms offering personalized strain rotations based on microbiome testing.
- Fitness Enthusiasts:Protein-optimized Greek yogurt formats with 20+ gram servings anchor post-workout recovery positioning. Demand concentrates in gym-adjacent retail in Australia and UK urban centers.
- Families:Multi-serve packaging and kid-friendly flavor profiles drive household pantry stocking behavior.
- Children:Age-appropriate dosing protocols and palatability engineering for under-twelve consumption remain underdeveloped, creating white space for validated formulations.
Health-conscious individuals handle the majority of throughput; fitness enthusiasts are expanding most steeply on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's qualified health claims framework anchors US market development, while EFSA's strain-specific substantiation rules reshape European formulation priorities. China's National Health Commission approval list determines import access for multinational suppliers.
United States
Greek yogurt protein density and direct-to-subscription models drive household penetration. FDA's qualified health claims framework permits limited digestive benefit communications pending clinical validation. California and Texas concentrate fitness-oriented demand, with gym-adjacent retail commanding premium shelf placement for high-protein formats.
Germany
Oat substrate fermentation expertise and enzymatic hydrolysis innovation expand non-dairy alternatives. EFSA's 2023 updated gut microbiome guidance tightens evidentiary standards for immune claims. Bavaria and North Rhine-Westphalia host precision fermentation clusters where Dutch and German manufacturers pilot cold-adapted culture strains.
China
Convenience store penetration and tier-one urban consumption accelerate drinkable format uptake. The National Health Commission maintains a restricted import strain list, creating regulatory bottlenecks for foreign entrants. Shanghai and Beijing distribution networks prioritize 300-milliliter bottle formats with extended ambient tolerance for convenience channels.
France
Artisan dairy heritage and clean-label positioning sustain premium retail channels. EFSA health claims regulation filters commodity suppliers from documented culture providers. The Brittany and Normandy dairy basins supply organic milk feedstock for fermentation operations serving continental European markets.
Australia
Fitness enthusiast demand and gym-adjacent retail expansion drive protein-optimized formats. The country's national food regulator enforces viability labeling requirements for live culture products. Sydney and Melbourne metropolitan corridors concentrate coastal household subscription penetration for personalized strain rotation services.
Probiotic Yogurt Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with strain library depth separating premium validators from commodity fermenters. The market structure concentrates around multinational dairy conglomerates with clinical validation capabilities, mid-tier regional specialists, and emerging non-dairy pure-plays. Dominant competitive moves include portfolio diversification into pediatric and clinical applications, plus geographic expansion through jurisdiction-specific strain registration.
Within the multinational conglomerate tier, Danone S.A. and Nestlé S.A. exemplify archetypes anchored by strain libraries and broad portfolio depth. Chobani LLC occupies a position as a domestic scale specialist with Greek yogurt format concentration. These three entities represent the spectrum from global clinical validation programs to regional production scale advantages.
| Leading Market Players |
|---|
| Danone S.A. |
| Nestlé S.A. |
| Chobani LLC |
| Yakult Honsha Co., Ltd. |
| General Mills Inc. |
| Arla Foods amba |
| FAGE International S.A. |
| Lactalis Group |
| Lifeway Foods Inc. |
| Others |
Value Chain & Pricing Dynamics
Oat milk substitution for conventional dairy feedstock is redrawing procurement geography while compressing margin structures across fermentation operations. Manufacturers sourcing enzymatically hydrolyzed oat bases from German and Dutch suppliers face divergent cost trajectories compared to those anchored in organic milk contracts from Denmark and Wisconsin.
Pricing Analysis
US retail channels command 15-25% premiums over European equivalents for Greek yogurt formats, reflecting protein-density positioning and gym-adjacent distribution costs. Three-tier pricing structure across premium, standard, and economy levels separates strain-validated clinical formulations from commodity cultures. Price erosion runs through conventional spoonable segments as private-label entrants replicate basic fermentation protocols. Corporate wellness programs exhibit lowest price sensitivity, while rural household penetration faces ceiling constraints from cold-chain cost absorption.
Supply Chain Analysis
Denmark and Wisconsin anchor organic milk supply for premium fermentation feedstock, while Germany and the Netherlands dominate oat substrate enzymatic processing. Live culture propagation draws from specialized microbiology facilities in France and California, with strain banking concentrated among three multinational repositories. Single-source vulnerability concentrates in thermophilic culture supply, where two European repositories handle majority global distribution. Distribution runs through refrigerated logistics networks with 48-hour viability windows, constraining radius from production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in pediatric applications and precision strain subscription services, as health-conscious households abandon one-size-fits-all formulations. Demand-side shift toward personalized microbiome optimization creates defendable niches outside multinational scale advantages.
For Market Incumbents: Shield strain library value through accelerated EFSA-qualified health claim submissions before 2023 guidance tightens evidentiary thresholds further. Consolidate fermentation microbiologist talent pools through captive training partnerships with Alpine and Nordic dairy cooperatives. Vertical integration into cold-adapted culture propagation reduces dependency on external strain repositories facing capacity constraints. For New Entrants and Emerging Players: EFSA fast-track approval for documented pediatric strains opens white space in under-twelve formulations where dosing protocols remain undefined. Target Australian and US coastal metropolitan corridors with direct-to-subscription models bypassing retail slotting fee structures. Foodservice channel penetration through healthcare cafeteria contracts offers volume anchor without brand equity requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed non-dairy pure-plays holding enzymatic hydrolysis IP but lacking strain validation capabilities. Five-to-ten-year viability hinges on jurisdiction-specific regulatory approval moats rather than formulation differentiation alone. Watch National Health Commission strain list expansions as inflection signal for China market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Clinical validation archives from European dairy cooperatives accelerate EFSA approval timelines. |
| Precision Fermentation Scale-Up | Cold-adapted culture production in Bavaria extends distribution radius without viability loss. |
| Pediatric Formulation Development | Age-appropriate dosing protocols capture white space in family consumption occasions. |
| Direct-to-Subscription Launch | Urban coastal households generate recurring revenue bypassing retail margin extraction. |
| Foodservice Channel Expansion | Corporate wellness programs provide bulk volume with lower brand equity requirements. |
Study Parameters
A standing panel of fermentation microbiologists, dairy process engineers, retail category buyers, and regulatory affairs specialists provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with strain library curators at Danone and Nestlé with distribution channel assessments across US, German, and Chinese cold-chain operators. Secondary sources encompassed EFSA health claims registers, FDA qualified health claims databases, National Health Commission strain approval lists, and customs trade data for fermented milk concentrates. Bottom-up volume modeling triangulated against top-down category spending estimates from Nielsen retail audit data.
Consistency checks validated projected value outputs against historical dairy alternative adoption curves and functional food penetration benchmarks across the analysis window. Segmentation modeling incorporated product format, substrate type, packaging structure, and consumer archetype dimensions with jurisdiction-specific regulatory cluster overlays. CAGR derivation applied logistic diffusion curves to strain-specific approval timelines, with inputs from organic milk commodity futures and enzymatic processing capacity expansion announcements.
Underlying assumptions cover sustained cold-chain infrastructure investment, stable EFSA evidentiary standards, and National Health Commission strain list incremental expansion, with deviation risk concentrated in live culture viability regulation tightening and oat substrate supply cost volatility. Recalibration cycles align with material shifts in regulatory approval pathways and alternative protein fermentation technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low Fat Yogurt Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Dairy Foods Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Textured Butter Market
Dairy Products
Cheddar Cheese Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Savory Dairy Products Market