
 Lactose Free Butter Market | 2026-2036
Lactose Free Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Lactose Free Butter Market Analysis
Premium organic certification is unwinding conventional price ceilings in the lactose-free butter category. Valio Ltd leverages its Nordic dairy heritage to anchor clean-label positioning across European retail channels. Arla Foods amba sustains broad manufacturing scale that competes on cost efficiency in private-label supply. Green Valley Creamery specializes in small-batch organic production that controls the specialty shop segment in North America.
Lactose-free butter denotes churned fat derived from milk treated with lactase enzyme to hydrolyze lactose into glucose and galactose, yielding a spreadable product with butterfat content typically ranging from 80 percent to 82 percent by weight. Its primary commercial purpose centers on delivering authentic dairy flavor and functional baking properties to consumers with lactose malabsorption or dairy sensitivity. The organic product type commands the steepest price premiums and fastest volume growth as clean-label preferences harden among household purchasers. Block packaging dominates food manufacturer procurement for recipe consistency, while pouches gain traction in online retail channels seeking reduced shipping weight and extended shelf stability.
The FDA governs dairy identity standards and allergen disclosure requirements that shape product labeling and market access for lactose-free butter sold in the United States. EFSA and national regulators across Europe enforce compositional thresholds and health claim verification that determine which products qualify for lactose-free designation on retail shelves. Stakeholders must monitor evolving enzymatic processing patents and shifting retail channel economics to secure positioning before formulation standards tighten and shelf-space competition intensifies.
Market Dynamics
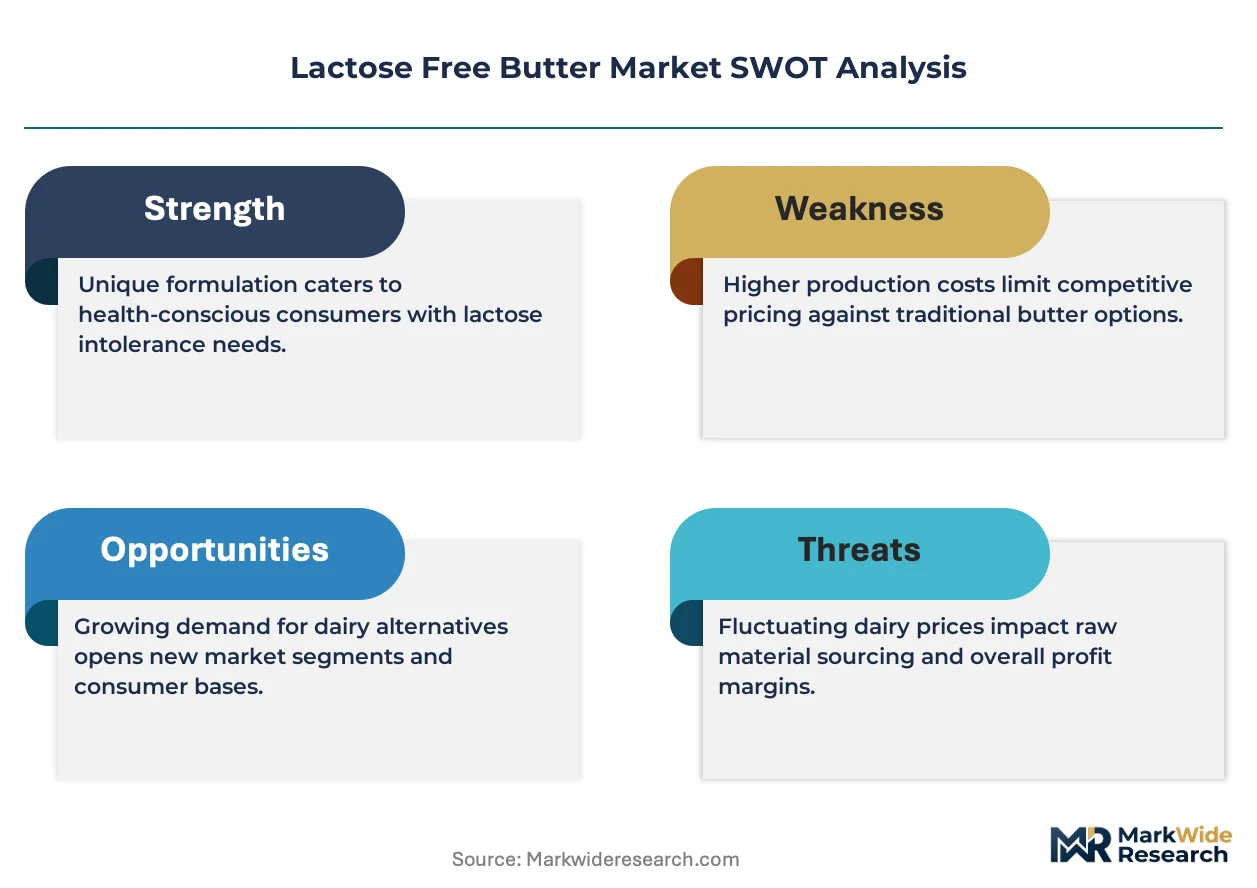
Enzymatic hydrolysis patents are concentrating manufacturing capability among processors with captive lactase supply, reshaping competitive entry barriers and procurement relationships across the value chain.
Growth Catalysts
- FDA Dairy Identity Standards:Updated allergen disclosure requirements clarify lactose-free labeling thresholds, reducing consumer confusion and expanding retail shelf eligibility for certified products.
- Bakery End-Use Expansion:Commercial bakeries now specify lactose-free butter for premium pastry lines, creating dedicated ingredient procurement channels with volume commitments.
- Direct-to-Home Channels:Specialty grocers and subscription delivery services in the United States allocate expanded cold-chain capacity to allergen-free dairy SKUs.
Market Restraints
- Organic Milk Input Costs:Certified organic cream carries 35-50% premiums over conventional, compressing margins for clean-label positioning.
- Enzyme Supplier Concentration:Three specialty biotechnology firms control 80% of food-grade lactase production, creating supply vulnerability.
- Butterfat Yield Limitations:Hydrolysis processing reduces functional stability in high-heat applications, restricting industrial baking adoption.
Strategic Opportunities
- India Urban Premium Retail:Organized grocery expansion in Mumbai and Bangalore creates first-mover positioning for imported lactose-free butter.
- EU Green Deal Agricultural Incentives:Carbon-neutral dairy processing subsidies favor enzymatic treatment over alternative dairy investments.
- Smart Packaging Convergence:Oxygen-scavenging films extend refrigerated shelf life, enabling e-commerce distribution without frozen logistics.
Industry Challenges
- Cross-Contamination Certification:Third-party allergen-free audits require 6-12 month facility validation timelines.
- Lactase Patent Licensing:Proprietary enzyme immobilization technologies create royalty stacking for new market entrants.
- Cold-Chain Integration:Last-mile temperature monitoring systems demand capital deployment beyond traditional butter distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactose Free Butter Market |
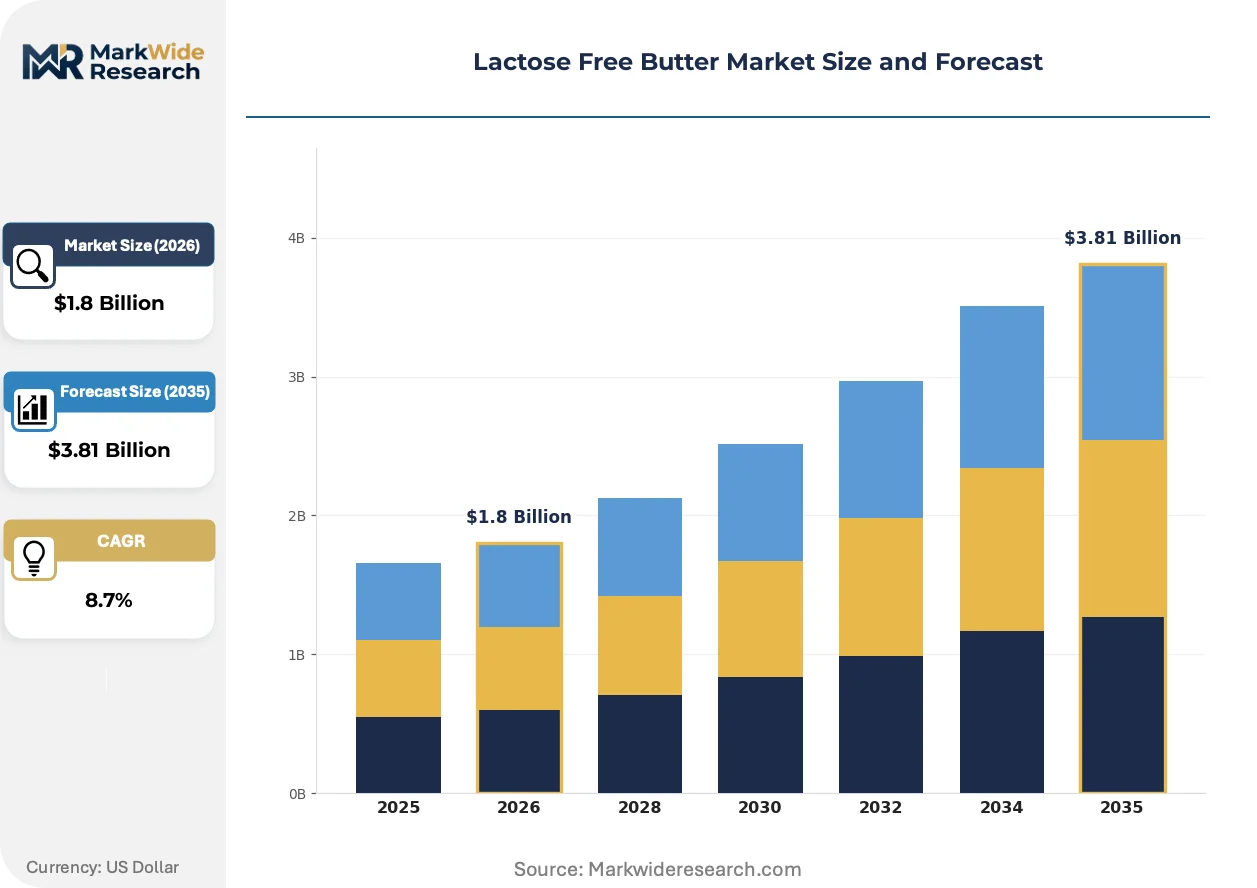
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salted, Unsalted, Organic, Whipped End User: Households, Restaurants, Bakeries, Food Manufacturers Packaging Type: Blocks, Sticks, Tubs, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Valio Ltd, Challenge Dairy Products Inc., Arla Foods amba, Lactalis Canada, California Dairies Inc., Green Valley Creamery, Upfield, Agropur cooperative, Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactose Free Butter Market Emerging Trajectories
Processing technology and retail channel evolution are fragmenting traditional supply relationships while regulatory clarity and consumer segmentation create new competitive axes.
Immobilized lactase enzyme systems enable continuous-flow hydrolysis without batch interruption. Mid-size dairy processors in Germany and the Netherlands adopt these systems to reduce enzyme consumption by 40%. This technology is fragmenting the historical advantage of large-scale batch processors by lowering minimum efficient scale.
EFSA health claim verification requirements now mandate clinical substantiation for lactose-free digestive comfort claims. Reformulation costs and documentation burdens favor established players with regulatory affairs capacity. Premium organic lines in France and Italy face the steepest compliance timelines as national regulators enforce transitional grace periods.
Specialty grocer private-label programs now specify dedicated lactose-free butter SKUs with distinct packaging formats. Traditional food-service distributors lose volume to direct-procurement relationships between processors and retail chains. This pattern concentrates most visibly in United States coastal metropolitan markets where specialty retail penetration exceeds national averages.
Lactose Free Butter Market Segmentation
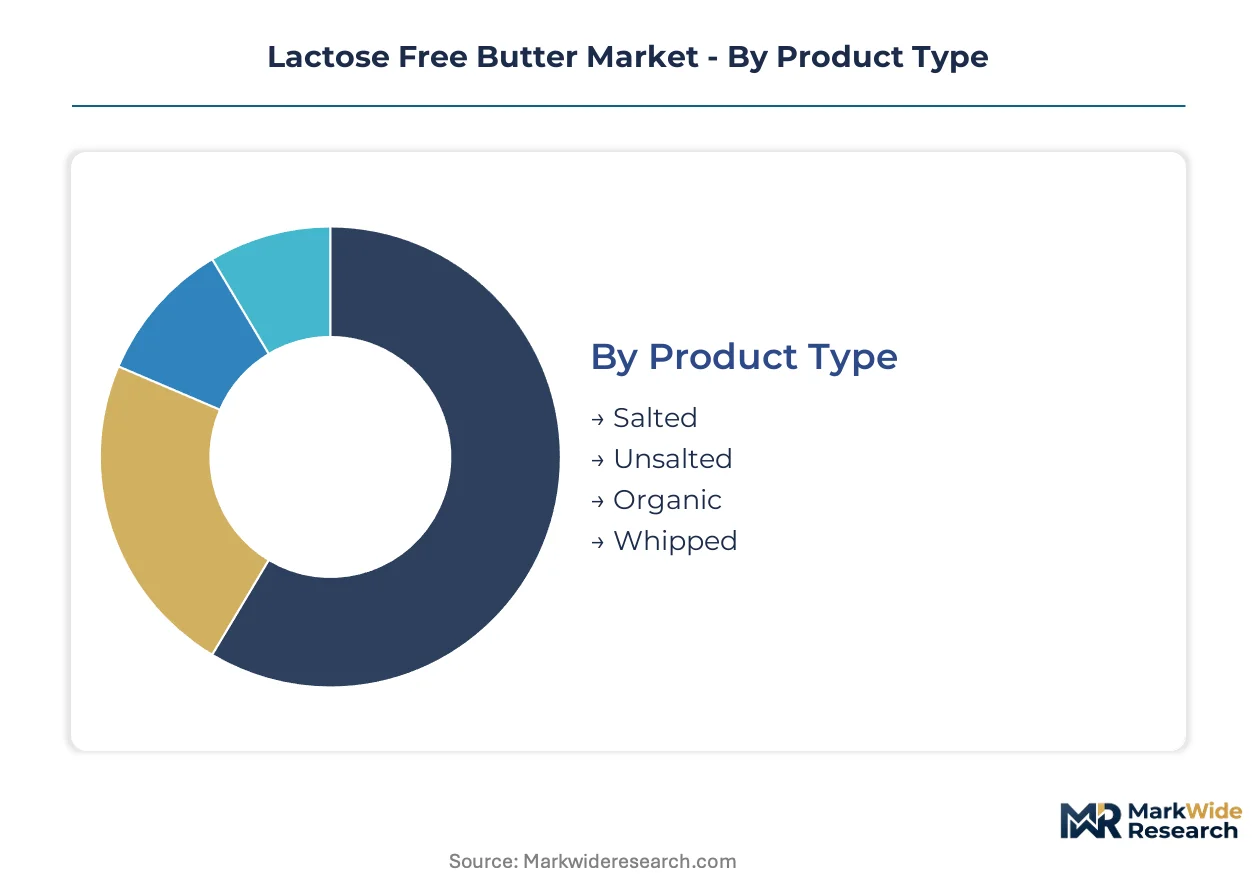
Segmentation in the lactose-free butter market reveals distinct procurement patterns across channels. Product form and packaging specifications determine whether volumes flow through retail shelves or direct commercial contracts.
Product Type:
Channel mix varies sharply by product type: organic lines concentrate in specialty shops and online retail, while conventional salted and unsalted variants dominate supermarket distribution.
- Organic:Certified organic butter carries 80-82% butterfat with full traceability documentation. Specialty grocers in the United States and France allocate dedicated shelf sets for organic SKUs, driven by clean-label premiums that offset 35-50% input cost elevations. By volume, salted leads. By growth pace, organic is ahead.
- Unsalted:Unsalted variants offer precise sodium control for recipe-critical applications. Bakeries in Germany and commercial food manufacturers specify unsalted blocks for consistent formulation, though refrigerated distribution constraints limit geographic reach.
- Salted:Standard table butter with 1.5-2% sodium chloride for direct consumption.
- Whipped:Aerated structure with 25% lower density per volume unit, suited for spreadability-focused retail.
Organic commands price premiums three to four times above conventional, yet volume growth rates in unsalted outpace salted in commercial channels.
End User:
Cost tier stratification separates household purchasers seeking small-format convenience from industrial buyers procuring bulk blocks under annual contracts.
- Bakeries:Commercial bakeries require butter with stable emulsion properties across temperature cycling. Artisan bakeries in Copenhagen and Vienna specify lactose-free butter for premium pastry lines, creating dedicated procurement channels with volume commitments and technical specification sheets. By volume, food manufacturers lead. By expansion trajectory, bakeries are climbing the fastest.
- Food Manufacturers:Industrial processors integrate lactose-free butter into frozen dough and prepared dessert formulations. Facility-level allergen segregation protocols in Canada and Australia mandate third-party certification, extending supplier qualification timelines.
- Households:Individual consumers purchasing through retail channels for home cooking and table use.
- Restaurants:Food-service establishments sourcing through distributors for menu applications.
Food manufacturers generate the largest absolute volumes, yet bakeries drive specification innovation that filters upstream to processing technology.
Packaging Type:
Volume scale and margin structure correlate inversely: bulk blocks serve high-throughput manufacturing at thin margins, while pouches capture e-commerce premiums.
- Blocks:Bulk blocks of 25kg or larger dominate food manufacturer procurement for recipe consistency and cost efficiency. German dairy processors supply blocks under private-label arrangements to industrial bakeries, with oxygen-barrier wrapping extending refrigerated shelf life. By volume, blocks lead. By margin expansion, pouches are gaining share fastest.
- Pouches:Flexible pouches reduce shipping weight by 40% versus rigid containers. Online retailers in the United Kingdom and Netherlands specify pouch formats for subscription delivery models, leveraging extended shelf stability to minimize cold-chain breakage.
- Sticks:Quarter-pound sticks for retail table butter and household measured cooking.
- Tubs:Wide-mouth containers for spreadable whipped variants in retail dairy cases.
Block packaging retains volume dominance, yet pouch adoption accelerates fastest where direct-to-home channels penetrate deepest.
Distribution Channel:
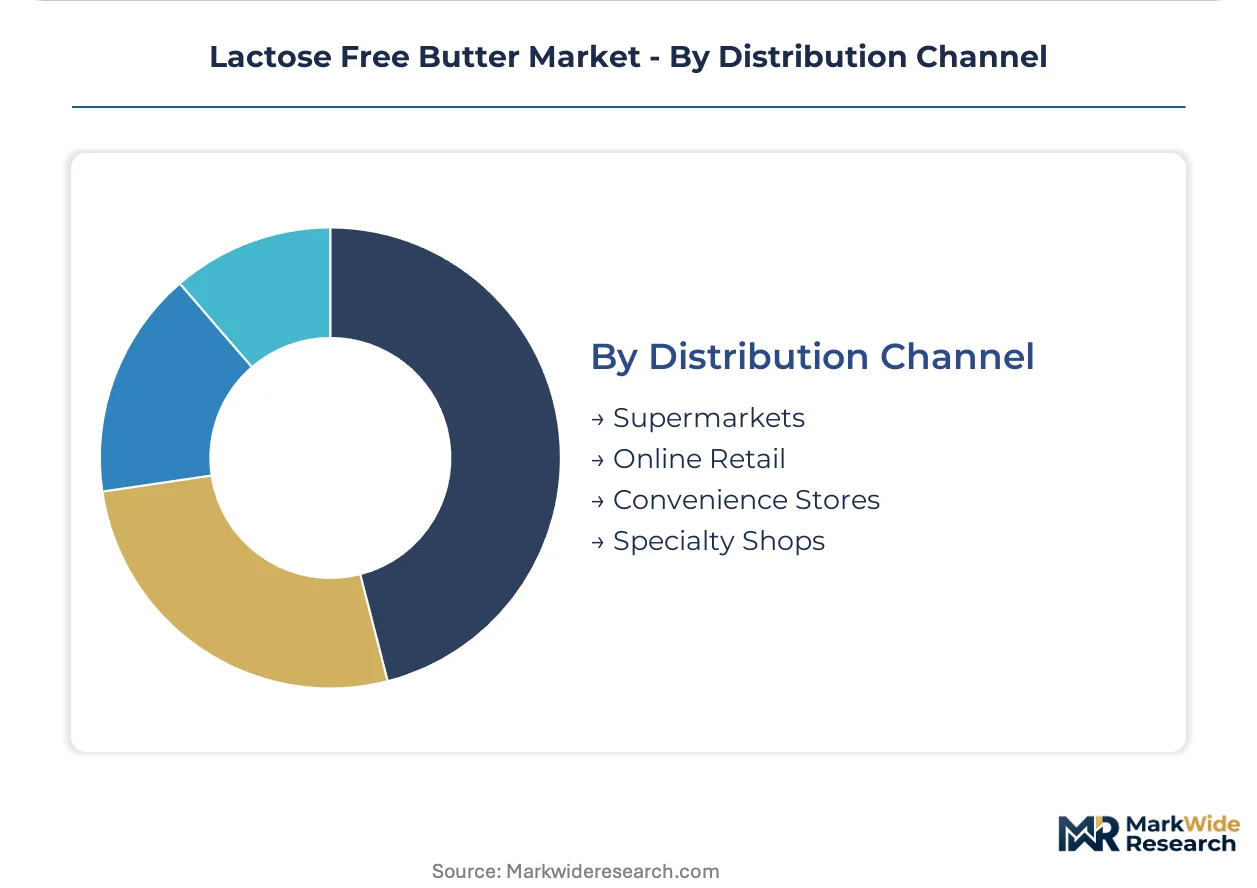
Geographic maturity determines channel composition: established markets fragment across specialty and online, while emerging markets concentrate in supermarkets.
- Online Retail:Subscription platforms and specialty grocers with digital fulfillment capture urban households seeking allergen-free assurance. Cold-chain investments by delivery services in Stockholm and Amsterdam enable temperature-monitored last-mile distribution that frozen logistics previously precluded. By volume, supermarkets lead. By channel growth velocity, online retail is expanding most quickly.
- Specialty Shops:Independent retailers and natural food stores curate premium organic assortments. Swiss and Austrian specialty shops enforce supplier audits for cross-contamination protocols, creating defensible positioning for certified processors.
- Supermarkets:Mass-market retail with broad geographic coverage and private-label programs.
- Convenience Stores:Small-format urban retail with limited cold storage capacity.
Supermarkets maintain volume supremacy through private-label penetration, though online retail and specialty shops together capture the steepest margin tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented Nordic processors supply premium lactose-free butter to deficit markets in Asia and the Middle East, while North American production gravitates toward domestic specialty retail channels. Import dependency in emerging economies creates first-mover premiums for certified suppliers with cold-chain capabilities.
United States
Specialty grocers in coastal metropolitan markets allocate expanded shelf space for allergen-free dairy SKUs, driven by household purchasing power and clean-label preferences. FDA updated dairy identity standards clarify lactose-free labeling thresholds, reducing consumer confusion and expanding retail eligibility. Direct-to-home subscription services in New York and Los Angeles deploy temperature-monitored last-mile distribution that frozen logistics previously precluded.
Germany
Industrial bakeries in Munich and Hamburg specify lactose-free butter for premium pastry lines, creating dedicated procurement channels with volume commitments and technical specification sheets. EU Green Deal agricultural incentives favor carbon-neutral dairy processing subsidies for enzymatic treatment over alternative dairy investments. Mid-size dairy processors in Bavaria adopt immobilized lactase systems to reduce enzyme consumption and fragment historical scale advantages.
France
Premium organic lines face extended EFSA health claim verification timelines as national regulators enforce transitional grace periods for digestive comfort claims. Reformulation costs and documentation burdens favor established players with regulatory affairs capacity. Artisan bakeries in Paris and Lyon drive specification innovation that filters upstream to processing technology requirements.
India
Organized grocery expansion in Mumbai and Bangalore creates first-mover positioning for imported lactose-free butter among urban premium retail consumers. FSSAI labeling requirements for dairy products shape import clearance timelines and product registration protocols. Cold-chain investments by delivery services in Delhi-NCR enable temperature-monitored distribution that frozen logistics previously precluded.
United Kingdom
Online retailers specify flexible pouch formats for subscription delivery models, leveraging extended shelf stability to minimize cold-chain breakage. Specialty grocer private-label programs demand dedicated lactose-free butter SKUs with distinct packaging formats. Direct-procurement relationships between processors and retail chains in London concentrate volume away from traditional food-service distributors.
Lactose Free Butter Market Vendor Landscape
Listed leaders compete with private specialists across enzymatic processing capability and clean-label certification depth. The vendor base spans multinational dairy cooperatives with captive lactase supply, mid-size organic processors with small-batch positioning, and private-label contractors serving retail chain programs. Three strategic archetypes dominate: heritage Nordic exporters with regulatory affairs capacity, North American organic specialists with direct-to-home channel control, and diversified food conglomerates with private-label manufacturing scale. Competitive moves concentrate on enzymatic hydrolysis patent licensing and specialty retail shelf-space allocation.
Within the heritage exporter archetype, Valio Ltd and Arla Foods amba anchor clean-label positioning across European retail channels through Nordic dairy heritage and broad manufacturing scale respectively. Green Valley Creamery occupies a position in the North American organic specialist tier, exemplifying small-batch production control over the specialty shop segment. These three entities represent the competitive spectrum from cooperative scale to private craft positioning.
| Leading Market Players |
|---|
| Valio Ltd |
| Challenge Dairy Products Inc. |
| Arla Foods amba |
| Lactalis Canada |
| California Dairies Inc. |
| Green Valley Creamery |
| Upfield |
| Agropur cooperative |
| Conagra Brands Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German industrial bakeries and Nordic dairy processors lock in both lactase enzyme supply access and eighteen-month price visibility, insulating procurement teams from spot-market volatility in organic cream inputs. These arrangements concentrate pricing power among processors with captive enzyme supply while compressing margins for buyers locked into fixed-volume commitments during input cost spikes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium organic, standard conventional, and private-label economy levels in the lactose-free butter market. Price differentiation hinges on organic certification grade and volume scale, with certified organic blocks commanding substantial premiums over conventional variants. Pricing pressure stems from concentrated lactase enzyme supply among three biotechnology firms, which tightens margins for processors without backward integration into enzyme production. Food manufacturers exhibit the highest price sensitivity due to thin margins in frozen dough applications, while specialty grocers absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of lactase enzymes and organic cream dominates inventory strategy among Nordic processors, contrasting with just-in-time preferences in North American retail channels. Supply concentrates in Finland, Denmark, and Germany, where enzymatic hydrolysis capabilities cluster around established dairy cooperatives. Raw material dependencies center on food-grade lactase, certified organic milk, and oxygen-barrier packaging films. Single-source vulnerability in enzyme supply creates systemic risk, particularly for mid-size processors without dual-sourcing arrangements. Distribution runs through cold-chain logistics networks that link production facilities to specialty retail and direct-to-home channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents in the lactose-free butter market face mounting substitution pressure from precision-fermented dairy fats and plant-based spreads, requiring defensive repositioning around enzymatic processing authenticity and clean-label certification depth.
For Market Incumbents: Secure captive lactase supply through enzyme supplier partnerships or in-house immobilization technology licensing to defend against supply disruption. Anchor retail shelf positioning through early compliance with evolving FDA dairy identity standards and EFSA health claim verification timelines, creating regulatory moats that precision-fermented substitutes cannot easily replicate. For New Entrants and Emerging Players: Differentiate on small-batch organic traceability and direct-to-home channel control rather than competing on manufacturing scale. Target urban premium retail in Mumbai and Bangalore through organized grocery partnerships, leveraging India's cold-chain investments to bypass traditional distributor relationships that incumbent processors dominate. For Investors and Strategic Acquirers: Mid-size organic processors with established specialty shop relationships and existing lactase licensing agreements represent the most defensible acquisition archetype in this market. Long-term viability rests on enzymatic hydrolysis remaining cost-competitive against precision fermentation across the next decade. Revision becomes warranted when precision-fermented dairy fats achieve price parity with enzymatically treated butter in European retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Supplier Partnership | Secures captive lactase access for processors facing biotechnology firm concentration. |
| Organic Certification Investment | Unlocks premium shelf positioning in specialty grocers across France and the United States. |
| Direct-to-Home Channel Expansion | Captures urban households through subscription models with temperature-monitored last-mile delivery. |
| Immobilized Lactase Technology Adoption | Reduces enzyme consumption by 40% for mid-size processors competing against batch-scale rivals. |
| EFSA Health Claim Documentation | Enables digestive comfort marketing that reformulation costs exclude from smaller competitors. |
Methodological Framework
Cross-validation between primary interviews with dairy procurement managers, enzymatic processing engineers, and specialty grocer category buyers anchors the qualitative findings in operational reality. Secondary validation draws from FDA dairy identity standard filings, EFSA health claim registers, customs trade data on enzyme imports, and Nordic dairy cooperative production disclosures. Bottom-up volume modeling triangulates against top-down category spend analysis to constrain estimation error.
Sensitivity analysis across enzyme cost scenarios, organic milk price volatility bands, and cold-chain logistics disruption probabilities informs the projection framework. Segmentation dimensions include product type, end-user application, packaging format, and distribution channel, with regional regulatory clusters layered as an additional modeling axis. CAGRs derive from fitted growth curves against historical volume trajectories, incorporating bakery end-use expansion rates and direct-to-home channel penetration curves as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA dairy identity standards and EFSA health claim verification regimes; material policy shifts would require re-modeling. Revision becomes warranted when precision-fermented dairy substitutes achieve commercial scale or when lactase enzyme patent expirations fragment supplier concentration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose and Derivative Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
China Milk Protein Market
Dairy Products
Gruyere Market
Dairy Products
Organic Cheese Market
Dairy Products
North America Casein Market
Dairy Products
Organic Milk Protein Market
Dairy Products
GCC Casein Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market