
 Flavoured Milk Market | 2026-2036
Flavoured Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Flavoured Milk Market Intelligence
The shift towards low-sugar and high-protein formulations is redrawing the competitive landscape for flavoured milk. Nestlé S.A. leverages its extensive global distribution network to introduce new flavour profiles across multiple price points. Danone S.A. specializes in products targeting health-conscious consumers with fortified options, including probiotics. The Hershey Company capitalizes on its powerful brand recognition within the indulgent chocolate milk category.
Flavoured milk is a ready-to-drink dairy beverage produced by adding sweeteners, flavourings, and sometimes colorants to milk. The product undergoes pasteurization and homogenization to ensure safety and a consistent texture, preventing separation of ingredients. Chocolate milk remains the dominant product type by volume, while demand for malted milk is growing among adult consumers. Supermarkets and convenience stores constitute the primary distribution channels, though online retail is gaining market share rapidly.
Regulations from bodies like the US Food and Drug Administration and the European Food Safety Authority (EFSA) mandate clear nutritional labeling, particularly on sugar and fat content. In India, the FSSAI sets standards for milk products, influencing formulation and market access. Producers must now decide whether to reformulate existing products for health-conscious segments or focus on the indulgent, premium category.
Market Dynamics
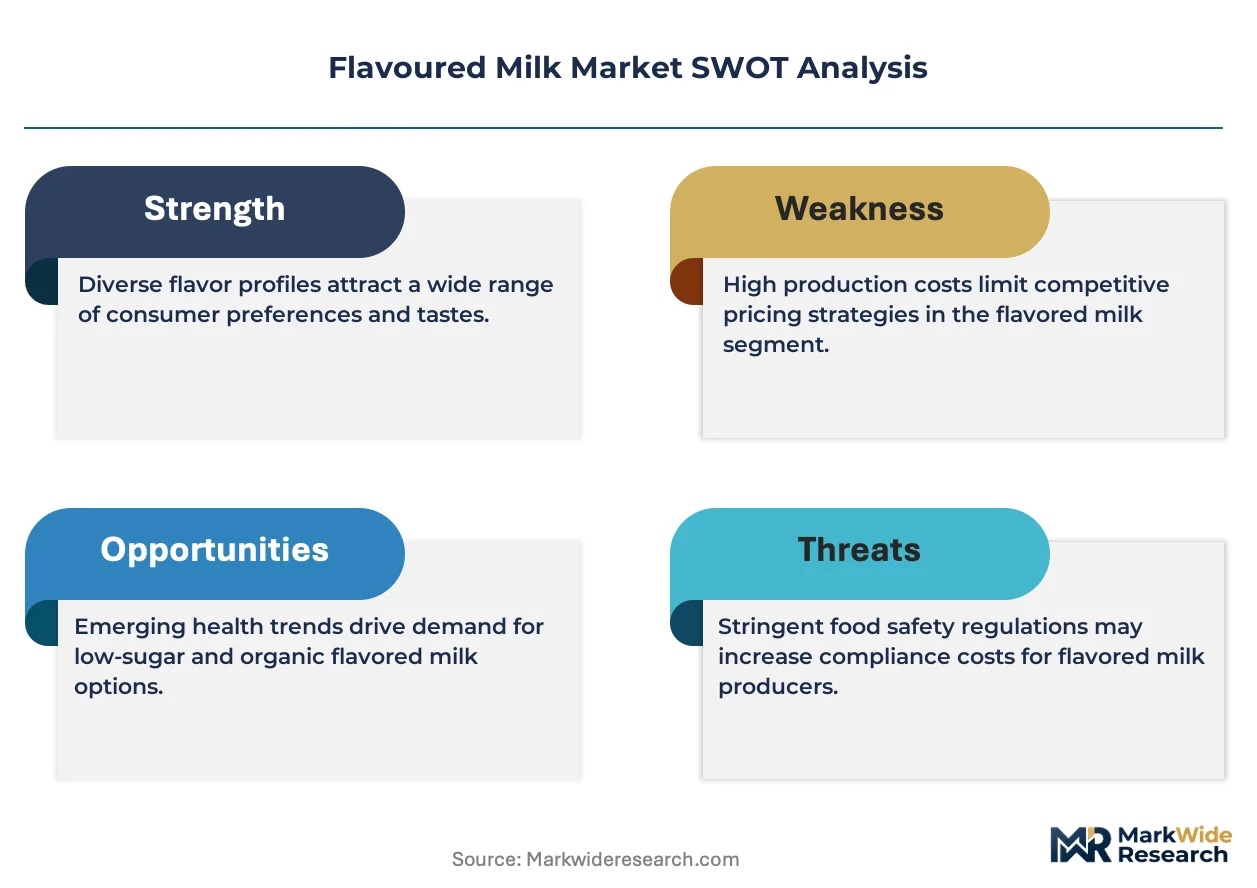
The flavoured milk market's trajectory is defined by the tension between consumer demand for indulgent treats and the public health imperative to reduce sugar intake. This dynamic is amplified by stricter nutritional labeling regulations from bodies like the US Food and Drug Administration, compelling producers to innovate.
Growth Catalysts
- Urbanization in Emerging Economies:Rapid urbanization and rising disposable incomes in countries like India and Brazil are expanding the consumer base for convenient, ready-to-drink beverages, positioning flavoured milk as an on-the-go option.
- Product Fortification:The development of formulations with added protein, vitamins, and probiotics appeals directly to health-conscious consumers and parents seeking nutritious alternatives to soft drinks for their children.
- School Nutrition Policies:Government-backed school meal programs and public health campaigns that limit sugary drinks are creating a dedicated market for lower-sugar, nutrient-dense flavoured milk products as a healthier beverage choice.
Market Restraints
- Input Price Volatility:Fluctuations in the prices of key raw materials, particularly fresh milk, sugar, and cocoa, create margin pressure and complicate production cost planning for manufacturers.
- Threat from Plant-Based Alternatives:The increasing consumer preference for dairy-free products presents a significant substitution threat, with oat, almond, and soy-based beverages competing directly for shelf space and consumer attention.
- Stringent Labeling Regulations:Mandates from the EFSA and FDA requiring clear, front-of-pack labeling of sugar and fat content increase compliance costs and can negatively influence consumer perception of traditional formulations.
Strategic Opportunities
- Expansion in Southeast Asia:Markets in countries like Vietnam and Indonesia represent significant growth potential due to a growing middle class and less market saturation compared to more developed regions.
- Functional and Exotic Flavours:There is a clear opportunity to introduce products with functional benefits, such as added fiber or probiotics, and to explore regional flavour profiles beyond conventional chocolate and strawberry.
- Direct-to-Consumer Channels:Developing online subscription models allows brands to build direct relationships with consumers, particularly for premium, organic, or specialized formulations not widely available in mass retail.
Industry Challenges
- Cold Chain Logistics:Maintaining the integrity of the cold supply chain for fresh dairy products, especially with the rise of e-commerce and last-mile delivery, presents a significant operational and cost challenge.
- Sugar Reduction without Compromise:Reformulating products to lower sugar content while preserving the expected taste and texture is a complex technical hurdle that requires substantial research and development investment.
- Compliance with Evolving Standards:Manufacturers face the challenge of adapting product formulations to meet frequently updated nutritional guidelines from national regulators like India's FSSAI, which can disrupt production schedules.
Report Scope
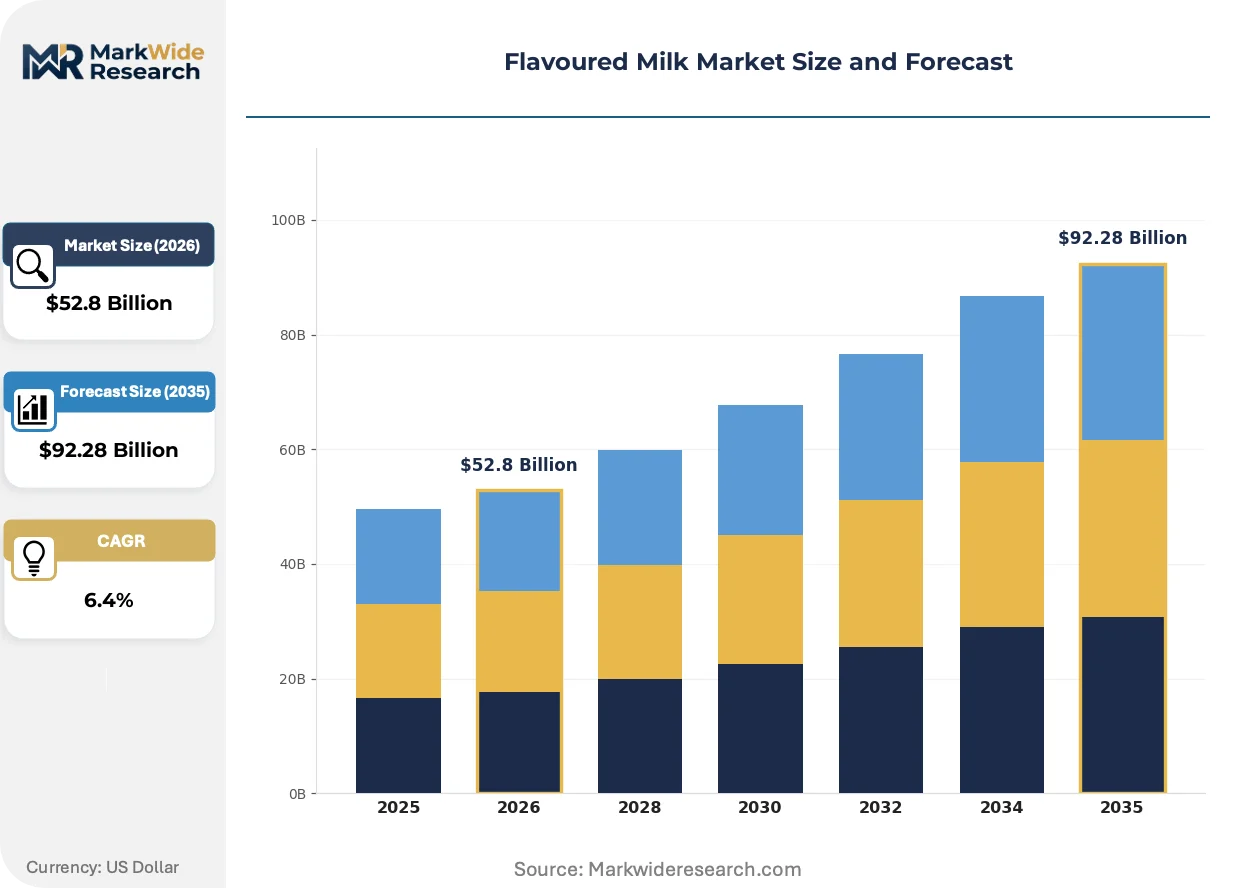
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavoured Milk Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Milk, Strawberry Milk, Vanilla Milk, Malted Milk Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Packaging Type: Cartons, Bottles, Pouches, Tetra Packs End User: Children, Adults, Athletes, Health-Conscious Consumers |
| Companies Covered | Yili Industrial Group Co., Ltd., Gujarat Cooperative Milk Marketing Federation Ltd., Nestlé S.A., Fonterra Co-operative Group Limited, Dairy Farmers of America, Inc., Danone S.A., China Mengniu Dairy Company Limited, The Hershey Company, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavoured Milk Market Strategic Shifts & Innovations
Product formulation is evolving to serve two distinct market poles: functional health beverages and classic indulgent treats. This split reflects a broader consumer desire for products that deliver either specific wellness benefits or an uncompromised, premium taste experience, forcing brands to choose a clear value proposition.
Advanced filtration technology, such as microfiltration and ultrafiltration, allows for the precise separation of milk components like protein and lactose. Health-focused consumers and athletes are rapidly adopting the resulting products for their high-protein and low-sugar content. This technology is bifurcating the market, creating a clear separation between functional, nutrient-dense beverages and traditional, full-flavour milk drinks.
European food safety regulations, particularly the push for harmonized front-of-pack labeling systems like Nutri-Score, are creating greater transparency around nutritional content. This shift compels manufacturers to reformulate products to avoid poor ratings on sugar and fat. The indulgent category is most affected, with brands either reducing sugar or repositioning their products as premium, occasional treats.
A notable behavioral shift is the move from impulse purchases in physical stores to planned buying through online grocery platforms and brand-specific subscription services. This trend disrupts the historical dominance of supermarkets and convenience stores as the primary distribution channels. This change is most pronounced in the urban centers of North America and Western Europe, where digital commerce infrastructure supports routine home delivery.
Flavoured Milk Market Segmentation
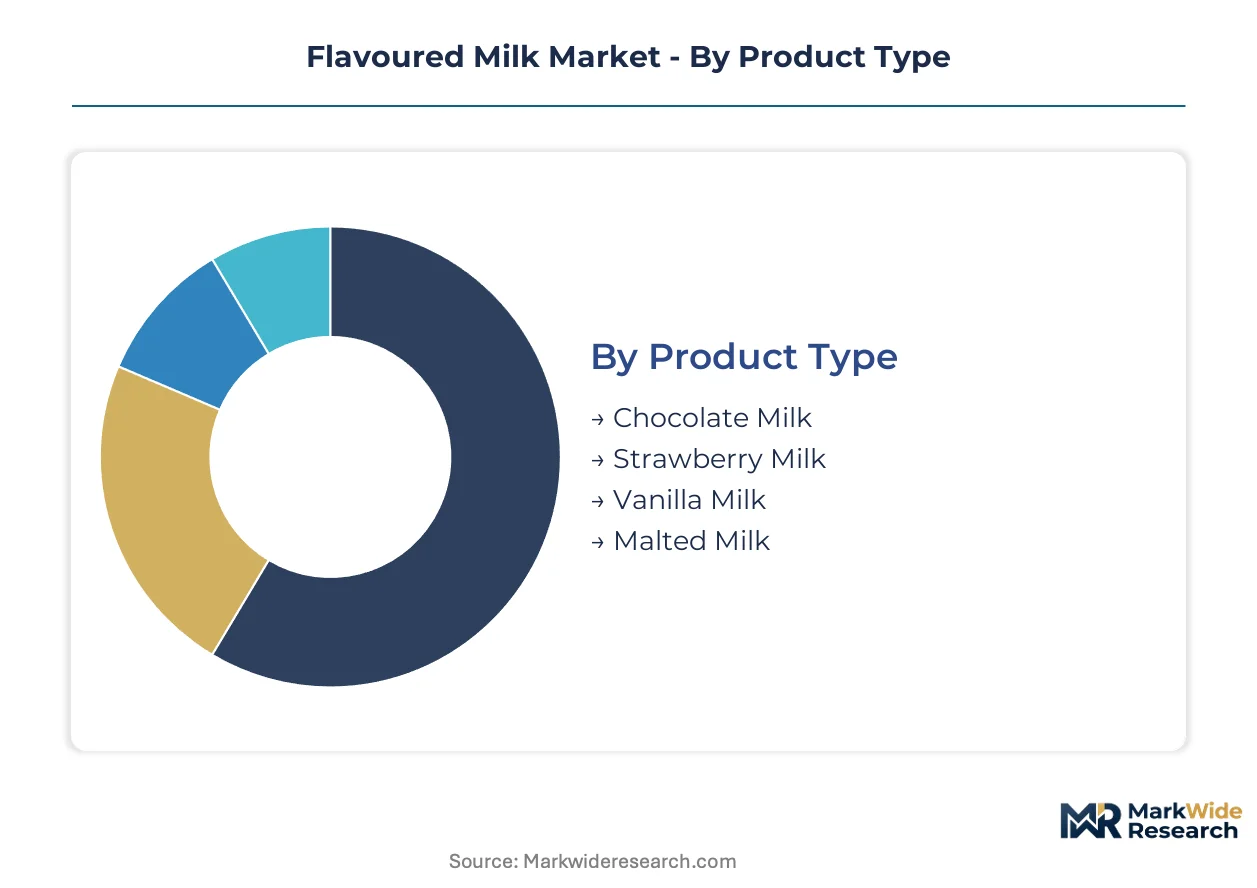
The Flavoured Milk Market exhibits diverse segmentation, driven by varying consumer preferences, nutritional requirements, and distribution strategies. Understanding these distinct segments allows producers to tailor product formulations and marketing efforts effectively. This granular view highlights areas of established demand and emerging growth opportunities.
Product Type:
Regulatory bodies like the US Food and Drug Administration and the European Food Safety Authority distinguish product types based on nutritional profiles, influencing formulation and labeling requirements.
- Chocolate Milk:This product type remains the dominant segment by volume, often formulated with varying sugar levels to cater to different consumer preferences. Demand persists strongly across all age groups, especially children, despite increasing scrutiny on sugar content from health organizations.
- Malted Milk:Characterized by its unique flavor derived from malted barley, this product is often positioned for adult consumers seeking nostalgic or less sweet dairy options. Its market is expanding among health-conscious adults in regions like India.
- Strawberry Milk:A popular fruit-flavored option, typically sweetened and often fortified with essential vitamins for children's consumption.
- Vanilla Milk:Offers a milder, versatile flavor profile, frequently used as a base for other ingredients or as a standalone, less intense beverage.
Established volume favors Chocolate Milk; emerging adoption favors Malted Milk.
Distribution Channel:
Volume concentration for flavoured milk products primarily occurs through established retail networks, reflecting diverse consumer purchasing habits.
- Supermarkets:These large format stores represent the largest distribution channel, offering extensive shelf space and competitive pricing for a wide range of brands. Supermarkets cater to bulk purchases and weekly grocery shopping across Europe and North America.
- Online Retail:This channel is gaining market share rapidly, driven by convenience and the expansion of e-commerce platforms, particularly for subscription models and specialized products. Online retail is especially prevalent in urban centers of North America and Western Europe.
- Convenience Stores:Provide quick, on-the-go access for impulse purchases, often stocking single-serve portions of popular flavored milk varieties.
- Health Food Stores:Cater to niche segments seeking organic, natural, or specialized dietary options, including fortified or low-sugar flavored milk.
Traditional physical retail channels maintain dominant sales, while online platforms are gaining share fastest.
Packaging Type:
Packaging innovation is driven by consumer convenience and product preservation, influencing cost structures for manufacturers.
- Tetra Packs:Widely utilized for aseptic packaging, extending shelf life without refrigeration until opened, and enabling broader distribution in emerging markets like India and Brazil. This format supports cost-effective, large-scale production.
- Bottles:Offer re-sealability and a premium perception, commonly used for single-serve portions and specialized formulations in developed markets. Plastic and glass bottles cater to different consumer preferences and price points.
- Cartons:A traditional and cost-effective packaging solution, often used for multi-serve family packs, requiring refrigeration for most product types.
- Pouches:Lightweight and flexible, these are gaining traction for children's portions and on-the-go consumption due to their portability and reduced material usage.
Aseptic packaging solutions facilitate wider geographic reach, while single-serve options enhance consumer convenience.
End User:
Different end-user segments exhibit distinct purchasing behaviors and preferences, impacting product formulation and marketing strategies.
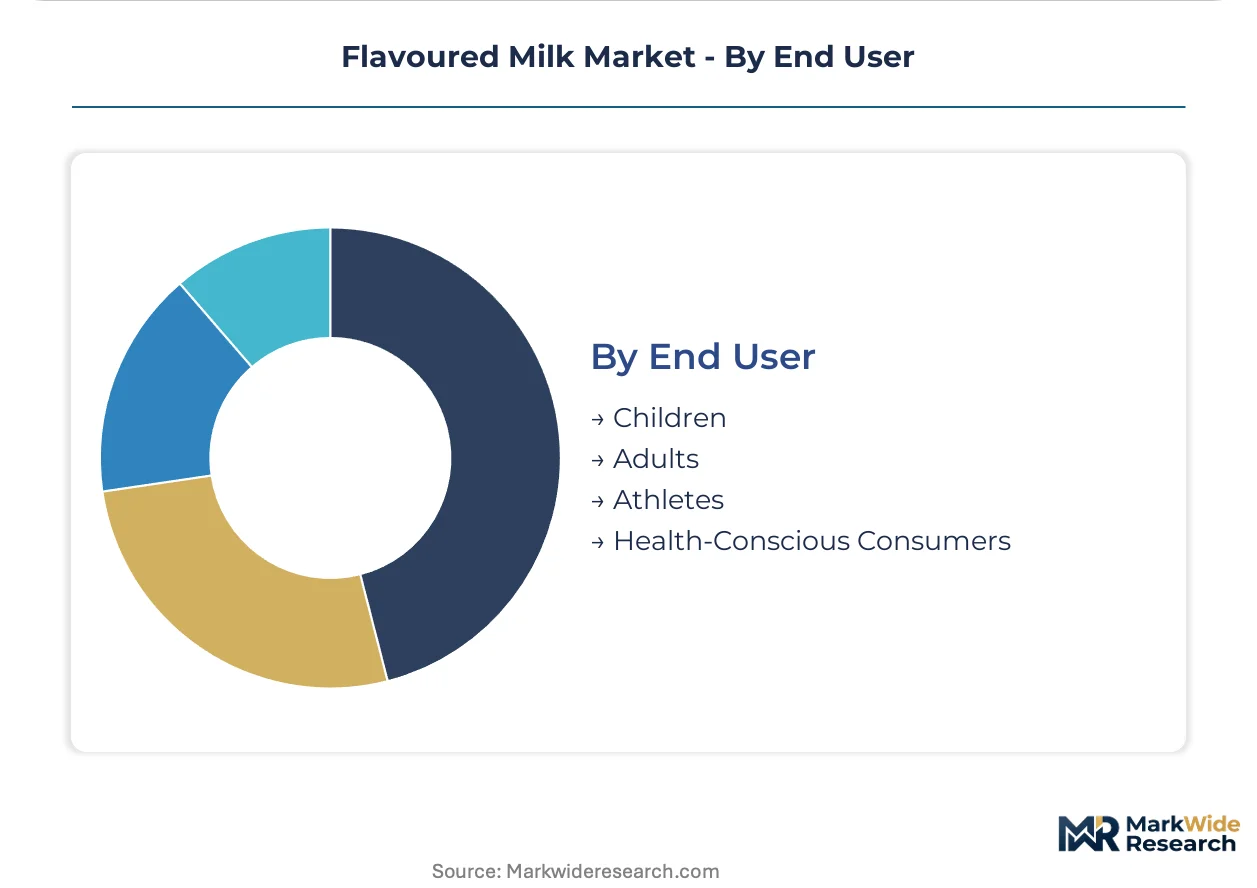
- Children:A primary consumer base, often targeted with sweeter, colorful formulations and cartoon branding, driving demand for convenient, ready-to-drink options. Nutritional fortification is a key selling point for parents in countries like the US and UK.
- Health-Conscious Consumers:These consumers seek low-sugar, high-protein, and fortified options, including probiotics and vitamins, aligning with broader wellness trends. This segment drives innovation in product reformulation across Europe and North America.
- Adults:Consume flavored milk for indulgence, convenience, or as a nostalgic treat, favoring flavors like chocolate and malted milk.
- Athletes:Utilize flavored milk, particularly chocolate milk, for post-workout recovery due to its balanced carbohydrate and protein content.
Demand from younger demographics underpins market volume, while health-focused segments fuel product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side concentration for flavored milk products often aligns with major dairy-producing regions and areas experiencing rapid urbanization. This dynamic shapes distribution networks and product innovation across diverse global markets. Producers strategically locate facilities to serve dense consumer populations and leverage local raw material availability.
India
Urbanization and rising disposable incomes in India expand the consumer base for convenient, ready-to-drink beverages. The FSSAI sets standards for milk products, influencing formulation and market access for producers. Major dairy processors in cities like Mumbai are reformulating products to meet health-conscious consumer preferences.
United States
Health-conscious consumers and athletes in the United States drive demand for low-sugar, high-protein flavored milk options. The US Food and Drug Administration mandates clear nutritional labeling, particularly for sugar and fat content. Dairy producers in California are investing in advanced filtration technologies to create functional beverage lines.
Brazil
Rapid urbanization and convenience seeking drive consumption of flavored milk across Brazilian cities. ANVISA regulations influence product formulations and labeling requirements for dairy beverages in the country. Companies in São Paulo are introducing new aseptic packaging solutions to expand distribution across the region.
Germany
German consumers seek functional flavored milk products with added protein or probiotics, reflecting wellness trends. European Food Safety Authority (EFSA) guidelines and Nutri-Score labeling push manufacturers towards healthier formulations. Dairy manufacturers in Bavaria focus on premium, organic, and specialized flavored milk offerings for discerning buyers.
China
A growing middle class in China increases demand for convenient, nutritious flavored milk options for children. The State Administration for Market Regulation (SAMR) sets food safety and labeling standards for dairy products. Major dairy companies in the Yangtze River Delta are expanding their online retail presence for flavored milk.
Flavoured Milk Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the flavored milk market. The industry structure is tiered, with global conglomerates competing against regional specialists and niche brands. Global players often pursue portfolio diversification, while regional entities prioritize M&A to consolidate local market share.
On the premium-tier vector, Nestlé S.A. and Danone S.A. exemplify companies leveraging extensive distribution networks and specialized product lines. Nestlé S.A. introduces new flavor profiles across multiple price points, while Danone S.A. targets health-conscious consumers with fortified options. The Hershey Company occupies a distinct position by capitalizing on powerful brand recognition within the indulgent chocolate milk category.
| Leading Market Players |
|---|
| Yili Industrial Group Co., Ltd. |
| Gujarat Cooperative Milk Marketing Federation Ltd. |
| Nestlé S.A. |
| Fonterra Co-operative Group Limited |
| Dairy Farmers of America, Inc. |
| Danone S.A. |
| China Mengniu Dairy Company Limited |
| The Hershey Company |
| Arla Foods amba |
| Others |
Cost & Logistics Intelligence
Plant-based alternative adoption is reshaping dairy supply chains, simultaneously influencing raw milk pricing and consumer willingness to pay for traditional flavoured milk. This shift necessitates strategic adjustments for manufacturers to maintain market competitiveness.
Pricing Analysis
European Food Safety Authority (EFSA) guidelines dictate the pricing tier structure, particularly concerning nutritional profiles. Pricing stratifies across premium-mid-economy levels, driven by product fortification, organic certifications, and brand recognition. Pricing softness reflects intense competition from plant-based alternatives and pressure to reformulate for lower sugar content. Health-conscious consumers exhibit lower price sensitivity for functional options, while parents purchasing for children often seek value in standard formulations.
Supply Chain Analysis
Maintaining cold chain integrity for fresh dairy products necessitates precise inventory management and short lead times, especially for last-mile delivery. Supply of fresh milk concentrates in major dairy regions like the United States, India, and Germany. The supply chain relies on consistent access to fresh milk, sugar, and cocoa. Commodity price volatility for these inputs presents a structural risk. Distribution runs through established supermarket networks and rapidly expanding online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flavoured milk market represents an early-cycle expansion story, driven by significant penetration potential in urbanizing emerging economies. Rising disposable incomes in countries like India and Brazil fuel this demand for convenient, ready-to-drink options.
For Market Incumbents:Consolidate market share by acquiring smaller, innovative brands specializing in fortified or low-sugar formulations. Invest heavily in advanced filtration technologies to create high-protein, functional dairy beverages, directly addressing the threat from plant-based alternatives. Expand distribution networks in Southeast Asia to leverage less saturated markets. Prioritize R&D efforts for sugar reduction without compromising taste, a key lever against regulatory scrutiny.
For New Entrants and Emerging Players:Differentiate on unique flavor profiles and functional benefits, moving beyond traditional chocolate and strawberry. Target the health-conscious adult segment with specialized formulations, such as added fiber or probiotics, especially in underpenetrated markets like Vietnam and Indonesia. Leverage direct-to-consumer online subscription models to build brand loyalty for premium, niche products. This approach avoids direct competition with established mass-market players.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors agile specialists in functional dairy and innovative packaging solutions. Long-term viability remains strong, driven by evolving consumer preferences for convenient, healthier options. Acquisition targets should include companies with proven sugar reduction technologies or strong regional distribution in emerging markets. A signal to watch is the sustained acceleration of online retail penetration across urban centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Aseptic Packaging Technology | This extends shelf life and enables wider distribution in emerging markets like Brazil. |
| Develop Low-Sugar, High-Protein Formulations | This addresses health-conscious consumer demand and regulatory mandates from the FDA. |
| Expand Direct-to-Consumer Channels | This builds direct relationships with consumers for specialized and premium product offerings. |
| Acquire Regional Flavored Milk Brands | This consolidates market share and expands geographic reach in fragmented local markets. |
| Introduce Exotic and Functional Flavors | This caters to adult consumers seeking novel taste experiences and specific wellness benefits. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from published sources. Primary fieldwork included conversations with dairy processors, R&D directors, retail buyers, and food safety regulators. Secondary sources comprised FSSAI reports, EFSA publications, industry association whitepapers, and company filings. Bottom-up and top-down triangulation ensured data consistency.
The forecast framework projects market evolution across the analysis window, utilizing a robust analytical approach. Segmentation dimensions modeled include product type, distribution channel, packaging type, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and projected market drivers. Key industry-specific forecast inputs included urbanization rates and per capita dairy consumption.
The analysis sits within stated boundaries; outcomes outside significant shifts in raw material prices or new, restrictive sugar regulations would require recalibration. Forecasts reflect documented assumptions regarding market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Camel Dairy Market
Dairy Products
Europe Dairy Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Camel Dairy Market
Dairy Products
Blue Cheese Market
Dairy Products
Milk Mineral Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Japan Dairy Market