
 Dairy Blends Market | 2026-2036
Dairy Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Blends Market Intelligence
ISO 22000 certification is unwinding competitive access across the dairy blends sector, filtering out smaller processors lacking integrated food safety management systems. Fonterra Co-operative Group leverages its New Zealand milk pool to dominate bulk powdered blend supply. Lactalis sustains European market presence through backward integration into whey fractionation. Kerry Group specializes in customized dairy lipid systems for infant nutrition clients.
Dairy blends combine milk-derived components with vegetable oils, emulsifiers, and functional proteins to replicate whole milk fat performance at reduced cost. Spray-dried powdered blends typically achieve 26-40% milk fat equivalent content through controlled lipid encapsulation, serving as drop-in replacements in bakery and confectionery formulations. Powdered blends occupy the largest margin pool due to extended shelf stability and freight economics. Infant nutrition within the application dimension commands premium positioning through stringent mineral balance and allergen control specifications. Liquid blends are accelerating in food service channels where reconstitution speed outweighs packaging cost.
FDA dairy identity standards and USDA organic certification constrain label claims and ingredient ratios in the United States. EFSA novel food assessments and EU Green Deal methane reduction targets are elevating scrutiny of dairy-derived ingredient carbon intensity. FSSAI fortification mandates in India create compliance thresholds for micronutrient premix integration. Stakeholders must monitor divergence between regional protein content regulations and emerging plant-dairy hybrid classification frameworks.
Market Dynamics
EU Green Deal methane reduction targets and F-Gas Regulation compliance costs are compressing processor margins while filtering supply base toward integrated operators with captive carbon accounting systems.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework subsidizes domestic dairy ingredient capacity expansion, attracting multinational blend manufacturers to establish localized spray-drying operations.
- Infant nutrition mineral specifications:Stringent FSSAI fortification mandates for iron, zinc, and calcium premix integration create technical barriers that favor specialized dairy lipid system suppliers.
- Spray-dried encapsulation:Controlled lipid microencapsulation technology enables 26-40% milk fat equivalent content in powdered blends, delivering drop-in functionality for bakery and confectionery reformulation.
Market Restraints
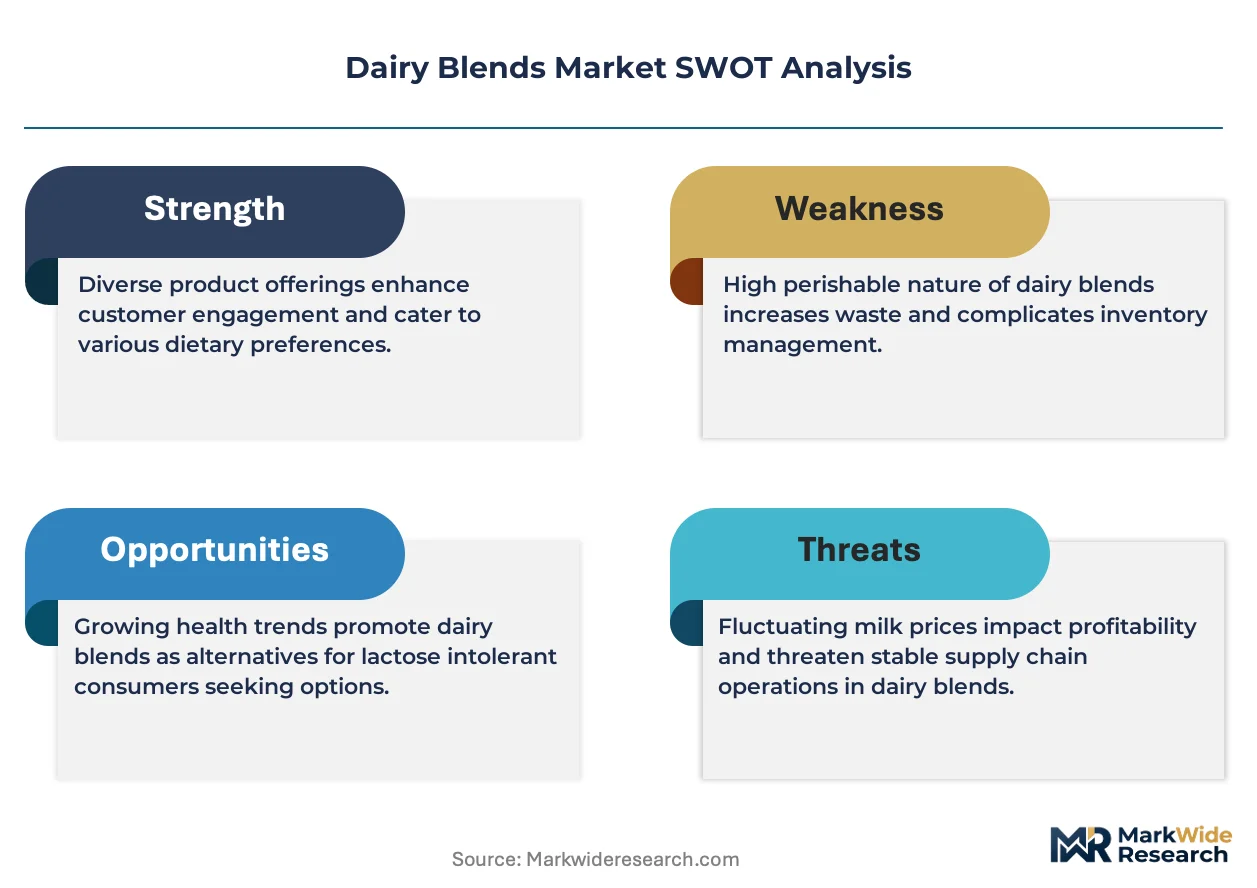
- Butterfat and vegetable oil input volatility:Palm oil price swings and dairy commodity auction cycles compress blend formulation margins unpredictably.
- New Zealand milk pool concentration:Fonterra's dominance over bulk milk powder supply creates single-source dependency risk for international blenders.
- EFSA novel food assessment timelines:Extended safety evaluation periods for new protein fractions delay product launch windows by 18-24 months.
Strategic Opportunities
- India food service liquid blends:Quick-service restaurant chains and institutional caterers demand reconstitution-speed solutions over shelf-stable powders.
- EU Green Deal carbon labeling:Methane intensity disclosure requirements create first-mover advantage for processors with verified low-carbon milk sourcing.
- Plant-dairy hybrid classification:Regulatory ambiguity around blended protein systems opens formulation space before standardization locks in.
Industry Challenges
- ISO 22000 certification timelines:Integrated food safety management system implementation requires 12-18 months for mid-scale processors lacking existing HACCP infrastructure.
- Whey fractionation capex intensity:Backward integration into protein separation demands membrane filtration and chromatography equipment investments exceeding smaller operator balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Blends Market |
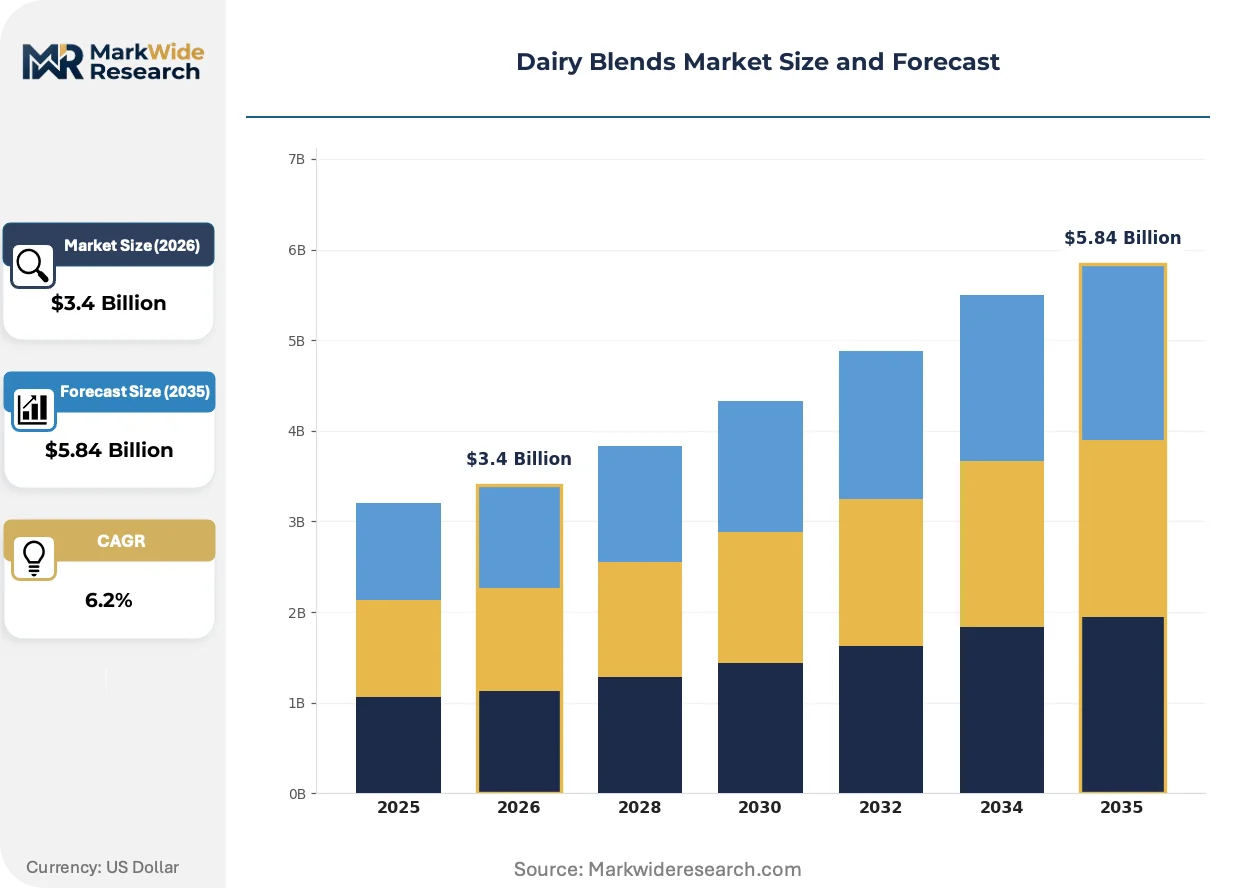
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
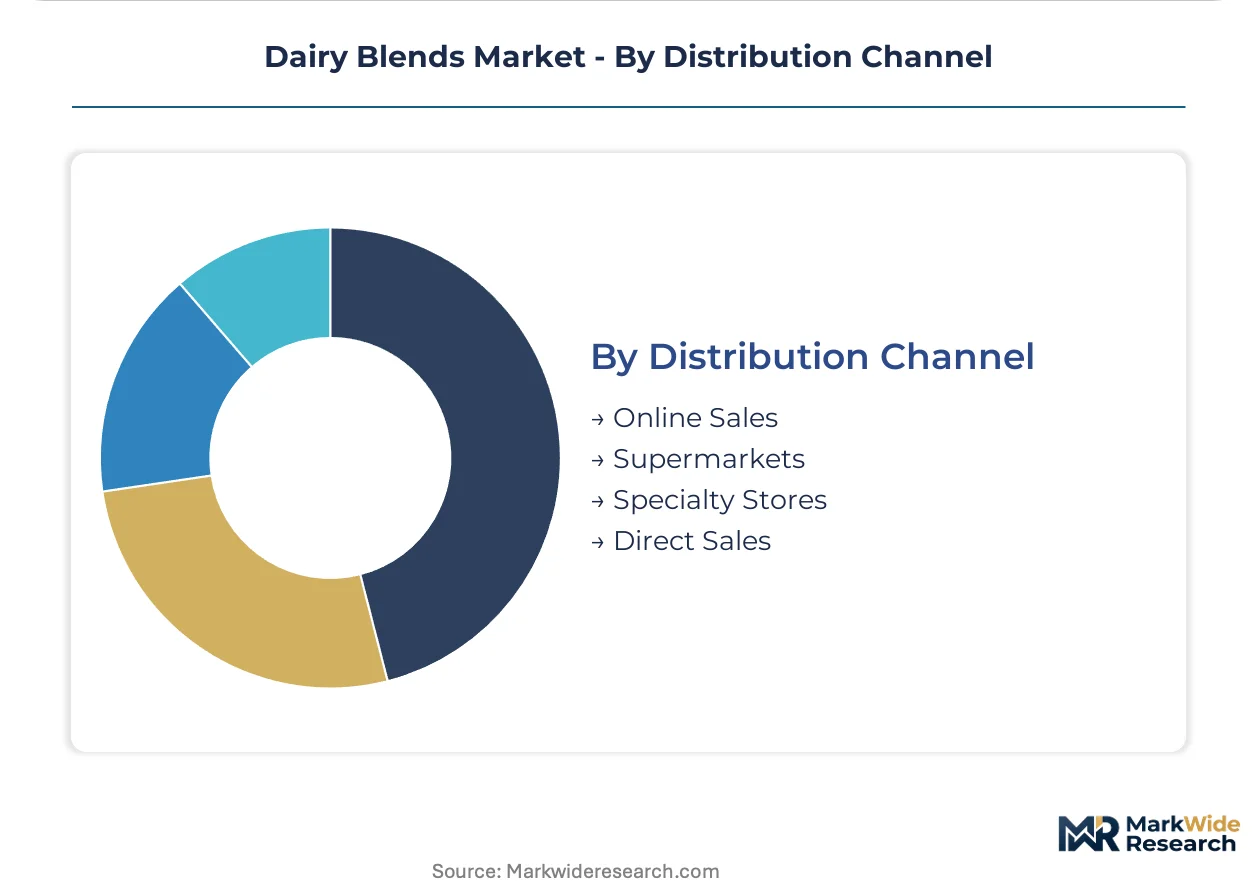
| Segmentation | Product Type: Powdered Blends, Liquid Blends, Cream Blends, Yogurt Blends Application: Food Service, Bakery Products, Confectionery, Infant Nutrition End User: Food Manufacturers, Restaurants, Retailers, Home Consumers Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Fonterra Co-operative Group, Lactalis, Nestle, Arla Foods, FrieslandCampina, Kerry Group, Agropur, Cargill, All American Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Blends Market Strategic Shifts & Innovations
Processing technology convergence and regulatory carbon accounting are rewriting competitive requirements across dairy blend manufacturing. Formulation science advances and procurement model evolution are simultaneously reshaping supplier-buyer relationships.
Precision fermentation-derived dairy proteins are fragmenting traditional milk fractionation economics. Infant nutrition manufacturers in Switzerland and the Netherlands are piloting microbial whey and casein alternatives at commercial scale. This biotechnology is fragmenting the historical link between agricultural milk supply and functional protein availability, enabling geographic decoupling of blend production from pasture-based dairying regions.
The EU F-Gas Regulation phase-down schedule is accelerating refrigeration system retrofits across European spray-drying facilities. Processors face capital allocation decisions between ammonia-based cooling infrastructure and imported powder tolling arrangements. German and Danish dairy ingredient plants are consolidating drying capacity to amortize compliance investments across larger throughput volumes.
Ingredient specification contracts are compressing from annual to quarterly price reset cycles. Food manufacturers in India and Southeast Asia are unbundling long-term supply agreements in favor of spot-indexed purchasing with quality premiums attached to FSSAI and ISO certification tiers. This volatility transfer is most visible in bakery and confectionery channels where reformulation flexibility permits rapid supplier switching.
Dairy Blends Market Segmentation

Dairy blend manufacturers configure production assets around shelf stability requirements and reconstitution speed trade-offs. Segment boundaries are blurring as infant nutrition specifications migrate into mainstream food service channels, forcing suppliers to recalibrate equipment and certification investments.
Product Type:
Powdered blends command the deepest margin pools through freight economics and extended shelf life, while liquid formats capture premium positioning in time-sensitive food service environments.
- Powdered Blends:Spray-dried formulations achieve 26-40% milk fat equivalent through controlled lipid encapsulation technology. Bakery and confectionery manufacturers in India concentrate demand here for drop-in reformulation flexibility against volatile butterfat auctions.
- Liquid Blends:Ready-to-use emulsions eliminate reconstitution steps in quick-service restaurant kitchens. Institutional caterers across European urban clusters are displacing powdered alternatives where labor cost minimization outweighs packaging premiums.
- Cream Blends:Vegetable oil-extended whipping agents serve bakery decorators seeking cost-stable alternatives to dairy cream.
- Yogurt Blends:Fermented base concentrates enable private-label yogurt production without dedicated culturing infrastructure.
Powdered blends hold installed capacity. Liquid blends are rotating up the share rankings.
Application:
Infant nutrition applications extract the steepest price premiums through mineral balance precision and allergen control protocols, while food service volumes scale through operational simplicity.
- Infant Nutrition:Iron, zinc, and calcium premix integration meets FSSAI fortification mandates with batch-level traceability. Swiss and Dutch manufacturers pilot precision fermentation proteins here, fragmenting traditional milk supply dependencies.
- Food Service:Reconstitution speed determines supplier selection for chain restaurants and institutional caterers. Indian quick-service operators are unbundling long-term supply agreements in favor of quarterly price resets with ISO certification premiums.
- Bakery Products:Powdered blends replace whole milk powder in laminated dough applications where fat functionality matters more than dairy identity.
- Confectionery:Milk fat equivalent systems enable chocolate compound coatings without cocoa butter extension.
Infant nutrition concentrates value capture. Food service is climbing the fastest on volume metrics.
End User:
Food manufacturers consolidate purchasing power through reformulation flexibility, while home consumers remain price-sensitive and brand-agnostic in emerging markets.
- Food Manufacturers:Integrated HACCP and ISO 22000 certification requirements filter supplier bases toward operators with captive food safety management systems. Procurement teams in Germany and Denmark compress contract cycles from annual to quarterly resets.
- Restaurants:Chain operators standardize liquid blend specifications across kitchen equipment footprints to minimize training variance.
- Retailers:Private-label dairy blend programs demand backward integration into whey fractionation for margin control.
- Home Consumers:Reconstituted milk powder blends serve price-conscious households in India where fresh milk distribution remains fragmented.
Food manufacturers lock in formulation partnerships. Restaurants are gaining procurement sophistication fastest.
Distribution Channel:
Direct sales relationships preserve margin for technical dairy lipid systems, while online channels expand reach for standardized powdered formats.
- Direct Sales:Technical specification contracts for infant nutrition clients require application engineering support and batch certification documentation. Kerry Group and specialized suppliers dominate this channel through customized dairy lipid system development.
- Supermarkets:Mass-market powdered blends compete on shelf price with private-label concentration in European retail consolidation.
- Specialty Stores:Organic and clean-label positioned blends serve premium home consumer segments.
- Online Sales:E-commerce penetration accelerates for standardized SKUs where technical consultation is unnecessary.
Direct sales anchors technical product distribution. Online channels are expanding addressable market coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme subsidies and FSSAI fortification mandates are redirecting multinational dairy ingredient investment toward domestic spray-drying capacity. Regulatory carbon accounting requirements in Europe and procurement flexibility demands in food service channels are simultaneously reshaping regional competitive positioning.
India
Quick-service restaurant chains and institutional caterers drive liquid blend demand where reconstitution speed outweighs packaging premiums. FSSAI fortification mandates for iron, zinc, and calcium premix integration create compliance thresholds favoring specialized suppliers. Maharashtra and Gujarat industrial corridors concentrate new spray-drying investments from multinational manufacturers seeking PLI scheme incentives.
Germany
Bakery and confectionery manufacturers compress procurement cycles from annual to quarterly price resets with ISO certification premiums attached. EU F-Gas Regulation phase-down schedules force capital allocation decisions between ammonia-based cooling retrofits and imported powder tolling arrangements. Bavaria and North Rhine-Westphalia dairy ingredient plants consolidate drying capacity to amortize compliance investments across larger throughput volumes.
United States
Food manufacturers navigate FDA dairy identity standards and USDA organic certification constraints on label claims and ingredient ratios. Infant nutrition clients demand batch-level traceability and mineral balance precision that filter supplier bases toward integrated operators. Midwest dairy processing clusters and California food manufacturing corridors anchor formulation partnerships with captive carbon accounting systems.
Switzerland
Precision fermentation-derived dairy proteins fragment traditional milk fractionation economics as infant nutrition manufacturers pilot microbial whey and casein alternatives. Swissmedic regulatory frameworks and EFSA novel food assessment timelines extend safety evaluation periods for new protein fractions. Zurich and Basel biotech corridors enable geographic decoupling of blend production from pasture-based dairying regions.
Netherlands
Ingredient specification contracts compress from annual to quarterly price reset cycles as food manufacturers unbundle long-term supply agreements. EFSA novel food assessments and EU Green Deal methane reduction targets elevate scrutiny of dairy-derived ingredient carbon intensity. Eindhoven Region and Randstad dairy lipid system suppliers specialize in customized formulations for infant nutrition clients demanding application engineering support.
Dairy Blends Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where scale-driven commodity suppliers coexist with application-engineering boutiques. The vendor base stratifies around ISO 22000 food safety management capabilities, with integrated HACCP infrastructure filtering mid-scale processors from premium contract pools. Two dominant archetypes emerge: milk pool controllers leveraging agricultural supply security, and formulation specialists delivering customized lipid systems. Competitive moves concentrate on backward integration into whey fractionation and geographic expansion through localized spray-drying joint ventures.
Within the milk pool control archetype, Fonterra Co-operative Group anchors bulk powdered blend supply through its New Zealand agricultural base, while Lactalis exemplifies European market presence via in-house production of protein separation capacity. Kerry Group occupies a position among formulation specialists, representing the customized dairy lipid system tier where application engineering and batch certification documentation preserve margin. These three entities collectively illustrate the competitive tension between agricultural supply security and technical formulation capabilities.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Lactalis |
| Nestle |
| Arla Foods |
| FrieslandCampina |
| Kerry Group |
| Agropur |
| Cargill |
| All American Foods |
| Others |
Cost & Logistics Intelligence
Spray-drying facility scale economies in India and Europe compress unit costs while concentrating supply ownership among operators with PLI scheme access or F-Gas Regulation compliance capital. This scale concentration simultaneously elevates price floors for uncertified processors and tightens margin capture for integrated blend manufacturers serving infant nutrition clients.
Pricing Analysis
Certification level creates the primary spread across dairy blend tiers, with ISO 22000 and FSSAI fortification compliance commanding 15-25% premiums over uncertified supply. Three-tier pricing structure across premium, standard, and economy levels reflects mineral specification precision and batch traceability depth. Cost compression in standard-tier powdered blends is intensifying because palm oil and butterfat auction volatility transfers unpredictably into formulation margins. Food service buyers in India exhibit highest price sensitivity through quarterly contract unbundling, while infant nutrition manufacturers in Switzerland and the Netherlands accept premium positioning for allergen-controlled lipid systems.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Mumbai elevate inbound logistics costs for whey protein concentrates and specialized emulsifiers. Supply concentrates in New Zealand through Fonterra's milk pool dominance, India via PLI-subsidized spray-drying corridors, and Germany through consolidated Bavarian drying capacity. Raw material dependencies rest on palm oil from Southeast Asian plantations, dairy commodities from Oceania auction cycles, and whey fractions from European membrane filtration facilities. Single-source vulnerability around New Zealand milk powder creates structural risk for international blenders lacking diversified sourcing. Distribution runs through direct technical sales for infant nutrition clients and spot-indexed procurement for food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation protein pilots and plant-dairy hybrid formulation ambiguity fragment incumbent control, creating white-space openings for specialized suppliers with carbon-accounting capabilities and rapid mineral premix integration.
For Market Incumbents: Consolidate drying capacity across German and Danish plants to amortize F-Gas Regulation compliance investments across larger throughput volumes. Deepen backward integration into whey fractionation to secure protein separation capabilities against precision fermentation substitution threats. Lock in multi-year infant nutrition contracts before EFSA novel food assessments validate microbial protein alternatives at commercial scale. For New Entrants and Emerging Players: Differentiate on carbon-labeled dairy sourcing to capture EU Green Deal methane disclosure premiums before standardization locks in certification requirements. Target India's food service liquid blend segment where reconstitution speed demands outpace incumbent powdered blend infrastructure. Lead with quarterly price-reset flexibility and FSSAI fortification compliance to displace legacy suppliers in quick-service restaurant procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among infant nutrition formulation specialists with captive mineral premix integration and batch certification documentation. Five-to-ten-year viability favors operators with verified low-carbon milk sourcing and spray-drying assets in PLI scheme corridors. Monitor precision fermentation protein cost curves as the inflection signal for traditional milk fractionation asset obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Fractionation | Captures protein separation margins and secures supply against Fonterra concentration risk. |
| Localized Spray-Drying Joint Ventures | Unlocks PLI scheme subsidies in Maharashtra and Gujarat industrial corridors. |
| Ammonia-Based Cooling Retrofits | Future-proofs European facilities against F-Gas Regulation phase-down penalties. |
| Precision Fermentation Protein Partnerships | Fragments traditional milk supply dependencies for Swiss infant nutrition clients. |
| Carbon Labeling Certification Programs | Creates first-mover positioning under EU Green Deal methane intensity disclosure rules. |
Research Approach
Operator-level perspectives from spray-drying plant managers, infant nutrition procurement leads, dairy commodity traders, and FSSAI compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from EU dairy processing statistics, New Zealand milk powder auction data, Indian customs import records, and SEC filings from listed ingredient suppliers. Bottom-up capacity utilization models and top-down demand segmentation triangulated volume estimates across product and application dimensions.
Sensitivity analysis tested forecast robustness against butterfat price volatility bands and precision fermentation protein cost decline scenarios across the projection horizon. Segmentation dimensions modeled include product format, application requirement, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules and infant nutrition volume elasticity assumptions. Industry-specific inputs incorporated PLI scheme subsidy phase-out trajectories and EFSA novel food approval probability weights.
Material uncertainties — palm oil supply disruptions, EU methane accounting rule finalization, and precision fermentation scale-up delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about F-Gas Regulation compliance timelines and FSSAI fortification mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Global Yogurt Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Yogurt Drink Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Latin America Cheese Market
Dairy Products
Sour Cream Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Global Milk Powder Market
Dairy Products
North America Yogurt Market
Dairy Products
Enzyme Modified Cheese Market