
 Europe Drinkable Yogurt Market | 2026-2036
Europe Drinkable Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drinkable Yogurt Market Foresight
Multi-pack bundling is repositioning household purchase patterns across European retail channels. Danone S.A. leverages its refrigerated logistics network to sustain shelf dominance in France and Spain. Arla Foods anchors its Scandinavian supply base while competing aggressively in British convenience stores. Nestlé S.A. differentiates through pediatric-positioned formats that occupy premium shelf space in German supermarkets.
Europe drinkable yogurt denotes a fermented dairy beverage containing live bacterial cultures, typically with a viscosity below spoonable yogurt and a shelf-stable or chilled distribution requirement depending on pasteurization treatment; its primary commercial purpose is to deliver convenient, portion-controlled probiotic and protein nutrition to mobile consumers. Low-fat yogurt and organic yogurt command the widest margin pools as EFSA-compliant health claims and EU organic certification create pricing power. Flavored yogurt generates the highest absolute volume, though health food stores and online retail channels are expanding fastest for unsweetened and functional variants.
EFSA nutrition and health claims regulation, EU organic certification standards, and national dairy hygiene frameworks across France, Germany, and Italy collectively determine which functional claims reach packaging and which products secure retail listing. EFSA's stringent probiotic health claim assessments force reformulation toward documented strain efficacy, while EU organic labeling rules restrict additive use and elevate input costs. Stakeholders must monitor pending EU packaging waste directives and evolving national sugar tax regimes as these will reshape formulation priorities and channel economics simultaneously.
Market Dynamics
EFSA's evolving probiotic health claim assessments are forcing manufacturers to rebuild formulation pipelines around documented strain efficacy, compressing R&D timelines and elevating clinical substantiation costs across European dairy operations.
Growth Catalysts
- Functional nutrition demand:German and French consumers prioritize gut-health positioning, pulling probiotic-rich formats into daily consumption routines and expanding household penetration rates.
- EFSA compliance frameworks:Stricter documentation requirements for live culture claims are filtering out unsubstantiated products, concentrating shelf space among scientifically validated portfolios.
- Organic certification premiums:EU organic labeling rules restrict additive use and elevate input costs, creating pricing power for certified producers in Western European retail channels.
Market Restraints
- Milk powder price volatility:Input cost swings in dairy commodities compress margin stability for mid-tier producers dependent on spot market sourcing.
- Refrigerated logistics concentration:Cold chain infrastructure bottlenecks in Southern and Eastern Europe limit distribution reach for chilled formats requiring temperature-controlled last-mile delivery.
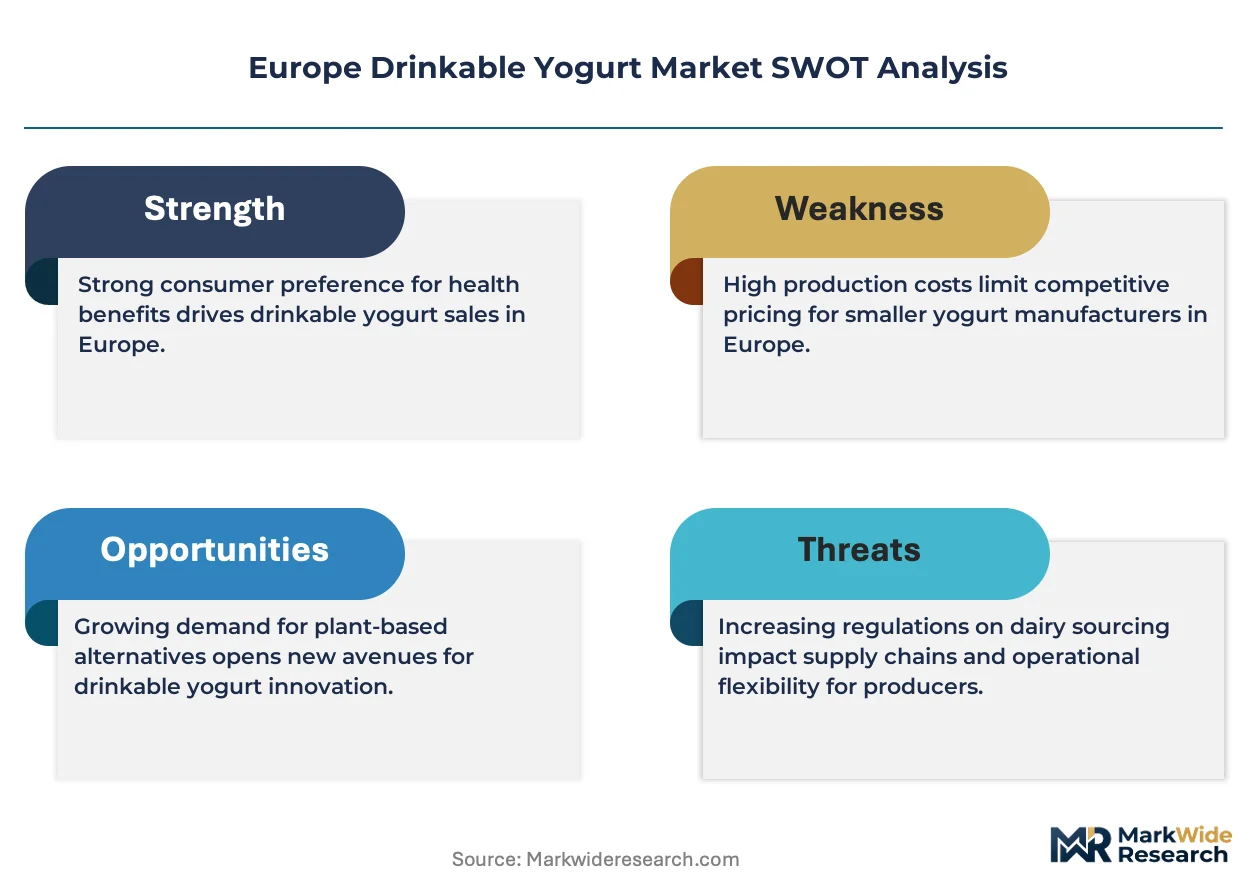
- Plant-based substitution:Oat and almond fermented beverages capture label-conscious consumers seeking dairy-free alternatives, eroding addressable base for traditional milk-derived drinkable yogurt.
Strategic Opportunities
- Pediatric functional positioning:Immunity and cognitive development claims targeted at parents of young children open premium pricing tiers in French and German pharmacy channels.
- Direct-to-subscription models:Recurring delivery platforms bypass traditional retail slotting fees and build consumer data assets for personalized formulation development.
- EU packaging waste directives:Pending regulations favoring recyclable mono-material structures reward early movers with regulatory goodwill and potential fee reductions.
Industry Challenges
- Strain-specific clinical substantiation:EFSA's case-by-case assessment approach demands bespoke trials for each probiotic culture, extending time-to-market by 18-24 months.
- Legacy dairy equipment retrofitting:Aseptic filling lines designed for spoonable yogurt require costly modification to handle lower-viscosity drinkable formats without compromising live culture viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drinkable Yogurt Market |
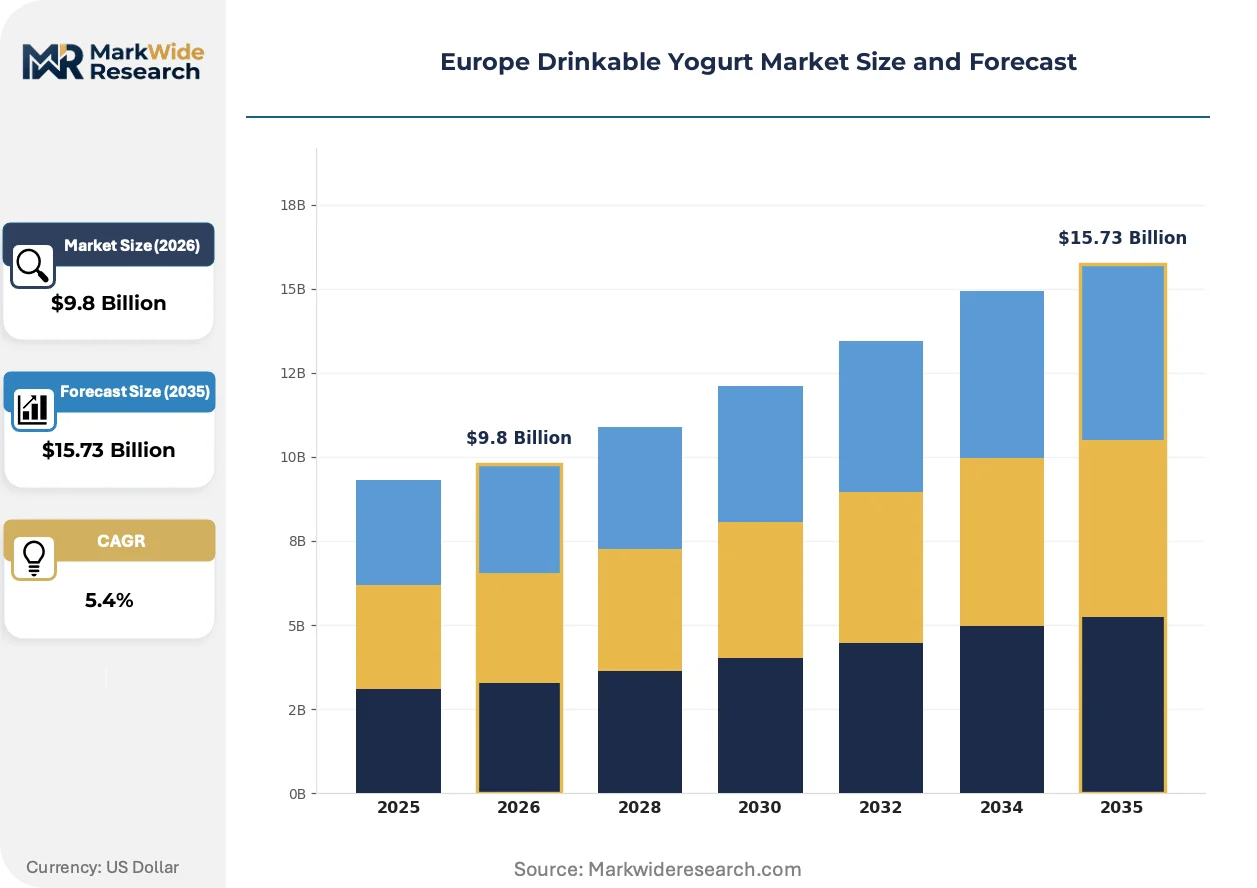
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Fat Yogurt, Whole Yogurt, Flavored Yogurt, Organic Yogurt Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores End User: Children, Young Adults, Health-Conscious Consumers, Athletes Packaging Type: Bottle, Tetra Pack, Pouch, Cup |
| Companies Covered | Danone S.A., Arla Foods, Nestlé S.A., Lactalis Group, FrieslandCampina, Müller UK & Ireland, Ehrmann AG, Materne SAS, Schreiber Foods, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drinkable Yogurt Market Shifts & Advancements
Manufacturing technology and distribution architecture are converging to reshape how drinkable yogurt reaches European consumers, with cold chain optimization and formulation science driving competitive differentiation.
Continuous fermentation systems with real-time culture monitoring are decentralizing production economics for drinkable yogurt. Mid-sized dairy cooperatives in Denmark and the Netherlands adopt these modular platforms to reduce batch-to-batch variation and cut energy intensity. Distributed manufacturing is compressing transport distances for chilled products, enabling fresher shelf dates and reduced spoilage rates in convenience retail.
REACH chemical safety protocols and pending EU packaging waste directives are accelerating material transitions across dairy packaging supply chains. Recyclable mono-material pouches and tethered caps replace multi-layer laminates, forcing converters to retool extrusion lines. German and French retailers are first-movers in demanding compliant packaging, pushing reformulation costs upstream to brand owners.
Subscription-based replenishment models are capturing recurring consumption occasions previously served by impulse supermarket purchases. British and Scandinavian consumers increasingly favor scheduled home delivery of multi-pack formats, bypassing traditional retail slotting fees. This channel shift concentrates buyer data with direct operators, enabling predictive flavor rotation and personalized probiotic blends based on individual purchase histories.
Europe Drinkable Yogurt Market Segmentation
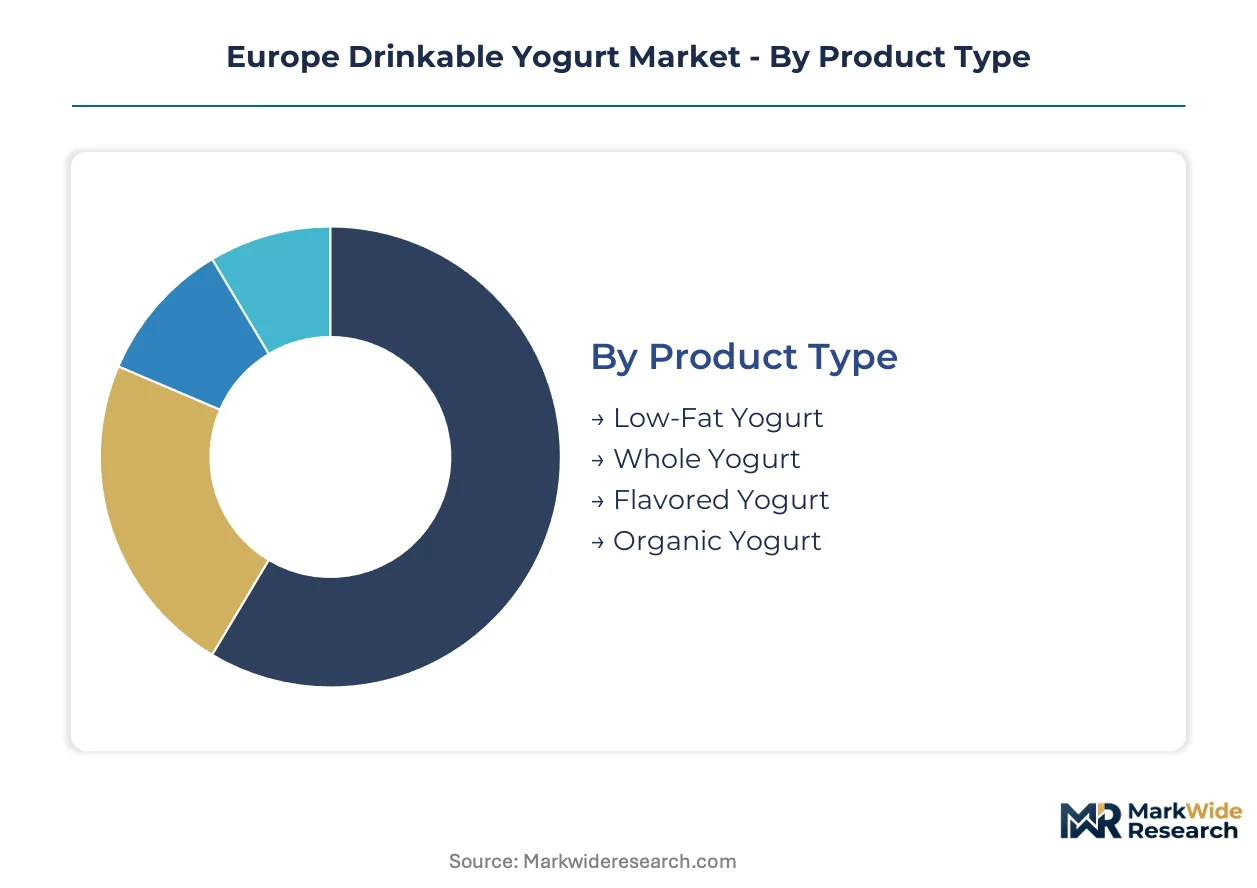
Segmentation reveals how European drinkable yogurt manufacturers align product architecture with distinct consumption moments and channel economics. Each dimension exposes divergent margin structures and regulatory exposure across the value chain.
Product Type:
Standardization dominates at the commodity end while certified and functional variants command customization premiums.
- Low-Fat Yogurt:Formulated with reduced milk fat content, typically below 1.5% fat, meeting EFSA-compliant nutrition claims for weight management positioning. German and French supermarket chains concentrate procurement for this format, driven by national dietary guidelines emphasizing saturated fat reduction.
- Organic Yogurt:Produced under EU organic certification standards restricting synthetic additives and mandating pasture-based dairy sourcing. Health food stores in Denmark and the Netherlands generate disproportionate demand, with consumers accepting substantial price premiums for verified supply chain transparency.
- Whole Yogurt:Retains natural milk fat levels above 3%, appealing to taste-focused consumers in Southern European markets.
- Flavored Yogurt:Incorporates fruit preparations, natural extracts, or sweeteners to mask fermented acidity.
Leading the category by volume: Flavored Yogurt. Growing fastest: Organic Yogurt.
Distribution Channel:
Channel selection determines cold chain investment intensity and direct consumer relationship depth.
- Supermarkets:Dominant volume channel requiring slotting fee negotiations and refrigerated display infrastructure. French and British multiples leverage private label development to capture margin from branded competitors, while EFSA labeling compliance becomes a non-negotiable listing criterion.
- Online Retail:Subscription and on-demand platforms bypass traditional retail economics, enabling temperature-controlled direct delivery. Scandinavian markets show steepest adoption curves as urban consumers prioritize convenience over immediate availability.
- Convenience Stores:Impulse-oriented channel favoring single-serve formats with extended ambient stability.
- Health Food Stores:Curated assortment emphasizing certified organic and functional probiotic strains.
Highest absolute volume flows through Supermarkets. Steepest expansion trajectory belongs to Online Retail.
End User:
Demographic targeting shapes formulation intensity and packaging communication strategy.
- Health-Conscious Consumers:Primary demand engine seeking documented probiotic efficacy and clean label credentials. German consumers in this segment drive strain-specific product development, requiring EFSA-substantiated health claims for gut microbiome benefits.
- Children:Pediatric-positioned formats with controlled sugar content and immunity-focused marketing. French pharmacy channels concentrate distribution for this segment, where parental willingness to pay premium prices supports specialized packaging and portion sizing.
- Young Adults:Mobile consumption occasions favoring grab-and-go formats with lifestyle-oriented branding.
- Athletes:Protein-fortified variants targeting recovery and performance positioning.
Health-Conscious Consumers anchor category revenue. Children segment climbs the fastest as parental functional nutrition awareness spreads.
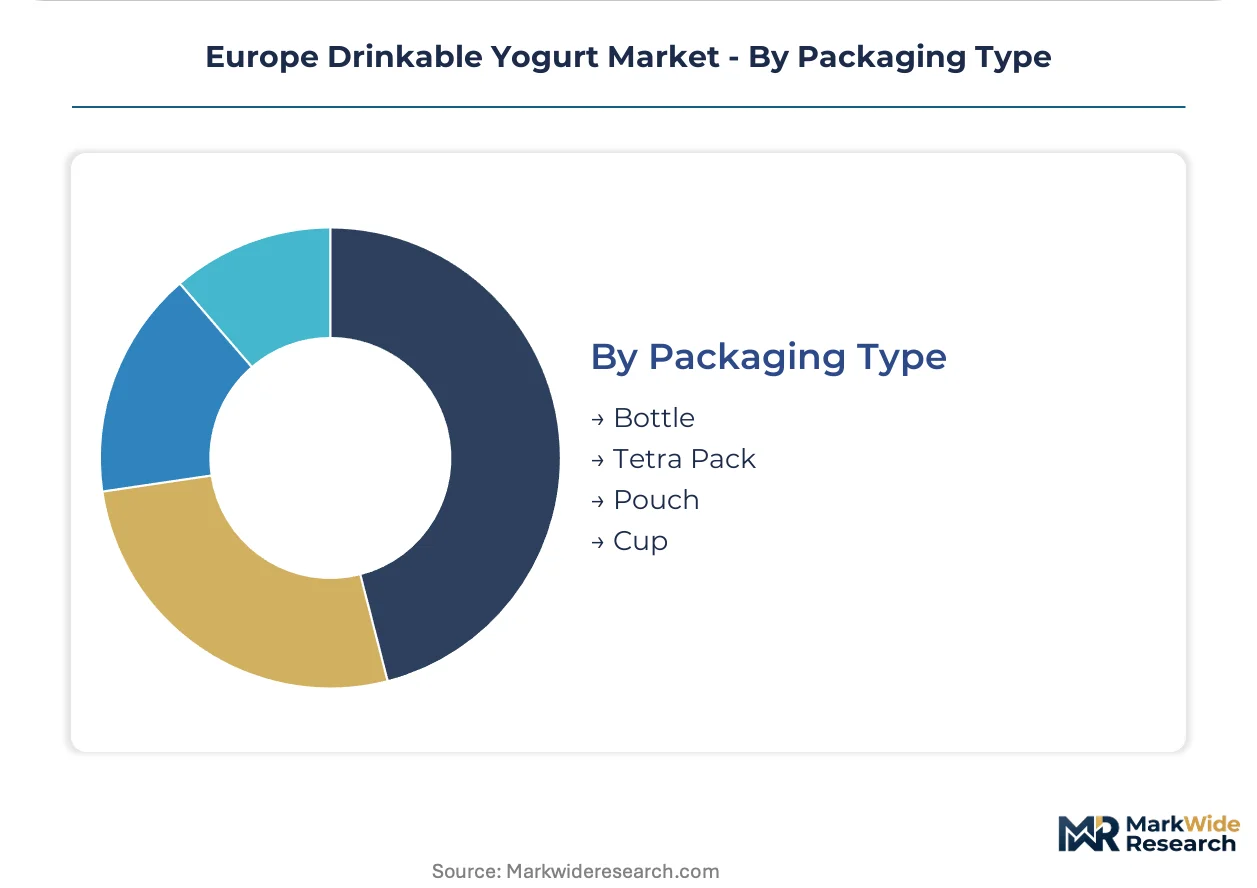
Packaging Type:
Material selection intersects with EU packaging waste directives and cold chain requirements.
- Bottle:Dominant format for chilled distribution, typically HDPE or PET with resealable closures. German retailers are first-movers in demanding tethered cap compliance under pending EU single-use plastic regulations, forcing mold redesign investments.
- Pouch:Flexible mono-material structures gaining share for ambient-stable products. Dutch dairy cooperatives lead adoption to reduce transport weight and enable direct-to-consumer subscription logistics.
- Tetra Pack:Aseptic carton technology enabling extended shelf life without refrigeration.
- Cup:Single-serve portion control format common in convenience retail.
Bottle format leads by installed capacity. Pouch format gains share fastest as sustainability mandates reshape material preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Northern Europe while consumption concentrates in Western European urban centers, creating a southward flow of refrigerated dairy products across the continent.
Germany
Health-conscious consumers in Berlin and Munich drive demand for EFSA-substantiated probiotic claims. The Federal Ministry of Food and Agriculture enforces strict dairy hygiene frameworks that filter non-compliant imports. Bavaria's dairy cooperatives anchor production, with Munich-based processors expanding aseptic filling capacity for drinkable formats.
France
Pharmacy-channel distribution for pediatric-positioned formats commands premium pricing in Paris and Lyon. ANSM and DGCCRF coordinate enforcement of nutrition labeling rules that restrict unsubstantiated gut-health claims. The Brittany dairy belt supplies raw milk to drinkable yogurt processors, with Rennes emerging as a formulation R&D hub.
United Kingdom
Subscription-based replenishment models capture recurring consumption in London and Southeast England. The Food Standards Agency applies post-Brexit divergence from EU health claim frameworks, creating dual compliance burdens. Yorkshire dairy processors retrofit legacy spoonable yogurt lines for lower-viscosity drinkable production.
Netherlands
Urban consumers in Amsterdam and Rotterdam favor mono-material pouch formats for sustainability credentials. The Netherlands Food and Consumer Product Safety Authority enforces REACH-compliant packaging transitions ahead of EU deadlines. Friesland's dairy cooperatives pioneer continuous fermentation systems that reduce batch-to-batch variation.
Spain
Convenience retail expansion in Madrid and Barcelona pulls single-serve ambient-stable formats. The Spanish Agency for Food Safety and Nutrition applies national sugar tax regimes that reshape formulation priorities. Catalonia's logistics hubs struggle with refrigerated last-mile bottlenecks for chilled distribution to Southern regions.
Europe Drinkable Yogurt Market Competitive Landscape
The competitive structure tilts toward diversified dairy conglomerates with refrigerated logistics networks. Consolidation concentrates shelf space among three to four pan-European operators, while mid-tier cooperatives defend regional niches through organic certification. Strategic archetypes include: science-validated functional specialists, private-label contract manufacturers, and direct-to-consumer subscription operators. Capacity expansion and portfolio diversification toward pediatric and organic variants dominate competitive moves.
Among France-based multinationals, Danone S.A. exemplifies the science-validated functional archetype through its refrigerated distribution dominance. Swiss-domiciled Nestlé S.A. occupies a premium-tier position with pediatric-positioned formats. Denmark-based Arla Foods anchors the cooperative model, competing aggressively in British convenience channels while maintaining Scandinavian supply base control.
| Leading Market Players |
|---|
| Danone S.A. |
| Arla Foods |
| Nestlé S.A. |
| Lactalis Group |
| FrieslandCampina |
| Müller UK & Ireland |
| Ehrmann AG |
| Materne SAS |
| Schreiber Foods |
| Others |
Supply & Pricing Matrix
Continuous fermentation system adoption across Dutch and Danish dairy cooperatives compresses unit economics while redistributing production scale advantages toward mid-tier operators with modular platform access. This technology shift simultaneously lowers barrier thresholds for regional players and erodes legacy volume-discount structures that previously anchored pricing power among refrigerated logistics incumbents.
Pricing Analysis
Cost-down pressure on organic-certified tiers accelerates as EU pasture-mandate compliance elevates raw milk procurement expenses beyond conventional sourcing baselines. Three-tier pricing structure across premium pediatric, standard functional, and economy flavored levels dominates channel economics, with EFSA-substantiated strain claims and organic certification operating as primary price differentiation drivers. Private-label concentration in British and French supermarket multiples intensifies price sensitivity among standard-tier buyers, while pharmacy-channel pediatric formats retain inelastic demand among parent segments.
Supply Chain Analysis
Live culture supply rests on specialized fermentation laboratories concentrated in Denmark, the Netherlands, and Germany, with documented strain banks and cryopreservation capabilities limiting rapid supplier switching. Raw milk procurement draws from pasture-based cooperatives in Brittany, Friesland, and Bavaria, while mono-material pouch converters cluster in German and Dutch packaging industrial zones. Single-source vulnerability around validated probiotic strain documentation creates regulatory chokepoint exposure, as EFSA case-by-case assessment requirements tether product launches to specific laboratory relationships. Distribution runs through refrigerated logistics networks anchored by Danone's French cold-chain infrastructure and Arla's Scandinavian hub-and-spoke systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's escalating clinical substantiation demands filter subscale competitors from viable shelf-space contention, compressing the addressable vendor base toward operators with dedicated R&D infrastructure and documented strain portfolios.
For Market Incumbents: Cement refrigerated logistics dominance through backward integration into cold-chain last-mile assets across Southern European expansion zones, particularly Spain and Italy where infrastructure gaps constrain chilled format penetration. Prioritize EFSA-compliant strain documentation investments to defend pharmacy-channel pediatric positioning against emerging functional specialists with clinical trial capabilities. For New Entrants and Emerging Players: Enter via direct-to-subscription platforms targeting British and Scandinavian urban consumers with personalized probiotic blending and predictive flavor rotation based on purchase history data assets. White-space concentration exists in ambient-stable mono-material pouch formats for convenience retail channels, where sustainability credentials and reduced transport weight offset incumbent refrigerated network advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by pan-European dairy conglomerates seeking EFSA-validated strain libraries and pediatric-format regulatory dossiers. Long-term viability favors operators with captive organic milk supply and continuous fermentation technology licenses. Watch EFSA probiotic health claim assessment queue velocity as inflection indicator for R&D timeline compression and portfolio valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Compliant Strain Documentation Investment | Clinical substantiation pipelines separate viable pharmacy-channel contenders from delisted products under evolving assessments. |
| Refrigerated Logistics Network Expansion | Cold-chain infrastructure buildout in Southern Europe unlocks chilled format distribution previously constrained by last-mile bottlenecks. |
| Direct-to-Subscription Platform Launch | Recurring delivery models bypass supermarket slotting fees and concentrate consumer data assets for personalized formulation development. |
| Mono-Material Packaging Transition | EU packaging waste directive compliance generates regulatory goodwill and potential fee reductions among German and French retailers. |
| Pediatric Functional Format Development | Immunity and cognitive development claims targeted at French pharmacy channels capture premium pricing tiers from parent segments. |
Research Methodology
Document review covered EFSA health claim registers, EU organic certification databases, and national dairy hygiene frameworks across France, Germany, and the Netherlands, complemented by interviews with category buyers at British and French supermarket multiples, formulation R&D directors at Danish and Dutch dairy cooperatives, and regulatory affairs specialists navigating EFSA strain assessment protocols. Secondary validation drew from customs trade data, refrigerated logistics capacity disclosures, and pharmacy-channel distribution filings. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit aggregators.
Cross-referencing historical consumption patterns against panel input from supply chain and channel stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, distribution channel economics, end-user demographic targeting, and packaging material compliance trajectory. CAGRs derived from trend extrapolation calibrated to documented EFSA regulatory timeline impacts and organic certification adoption curves. Forecast inputs incorporated milk powder commodity volatility indices and cold-chain infrastructure investment disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA probiotic claim assessment delays or accelerated EU packaging waste directive enforcement. Projections reflect assumptions around strain documentation approval velocities, organic pasture-mandate compliance costs, and refrigerated logistics capacity expansion schedules. A small set of named triggers—EFSA queue acceleration, national sugar tax regime expansion, and mono-material packaging converter capacity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Milk Mineral Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
North America Yogurt Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Goat Milk Products Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Global Milk Protein Market
Dairy Products
Organic Milk Powder Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Canada Dairy Market
Dairy Products
Green Tea Butter Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
North America A2 Milk Market
Dairy Products
Dry Whole Milk Powder Market