
 Indonesia Automotive Engine Oils Market | 2026-2036
Indonesia Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Automotive Engine Oils Market Foresight
Indonesia's motorcycle parc is repositioning lubricant demand toward SAE 10W-40 and SAE 5W-30 grades suited to tropical stop-start riding. Shell plc dominates Java's premium synthetic segment through franchised quick-lube networks. PT Pertamina anchors state-backed distribution via fuel station retail, extending reach into tier-two cities. Exxon Mobil Corporation leverages technical licensing partnerships with local blending facilities to compete in the semi-synthetic tier.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines; their viscosity index and total base number determine service interval suitability under Indonesian ambient temperatures averaging 25-30°C. Synthetic formulations command margin premiums in passenger vehicle applications where OEM drain intervals stretch beyond 10,000 kilometers. The SAE 0W-20 viscosity grade grows fastest among Japanese-brand car fleets, while conventional mineral oils retain volume leadership in motorcycle aftermarkets where price sensitivity shapes purchasing. Wholesale distributor channels capture the largest value pool by aggregating bulk procurement from fleet operators and independent workshops.
Indonesia's National Standardization Agency (BSN) enforces SNI lubricant certification, while the Ministry of Energy and Mineral Resources administers biodiesel blend mandates that alter engine oil formulation requirements to manage fuel dilution and oxidation stability. The country's national pharmaceutical regulator does not govern this sector, but BSN's technical committees are tightening NOACK volatility limits to align with ASEAN harmonization frameworks. Stakeholders must monitor BSN's adoption of API SP and ILSAC GF-6 specifications, as these standards will determine which product portfolios retain market access versus requiring reformulation investment.
Market Dynamics
Indonesia's B20 biodiesel mandate is reshaping lubricant formulation requirements as fuel dilution and oxidation stability become critical performance parameters for engine oil blenders serving the country's diesel-heavy commercial fleet.
Growth Catalysts
- BSN SNI lubricant certification tightening:Indonesia's National Standardization Agency is aligning NOACK volatility limits with ASEAN harmonization frameworks, creating upgrade demand among domestic blenders seeking market access.
- Motorcycle parc expansion in urban Java:Stop-start tropical riding patterns are accelerating adoption of lower-viscosity SAE 10W-40 and SAE 5W-30 formulations suited to air-cooled engines.
- OEM drain interval extension:Japanese-brand passenger vehicle fleets are stretching service intervals beyond 10,000 kilometers, pulling synthetic and semi-synthetic volumes into replacement cycles.
Market Restraints
- API Group I base oil supply concentration:Indonesia remains dependent on regional Group I imports for mineral oil formulations, exposing blenders to feedstock cost volatility from Singapore refining hubs.
- Price sensitivity in motorcycle aftermarket:Independent workshops and individual riders prioritize per-liter cost over total cost of ownership, compressing margin capture on premium formulations.
- Fuel dilution chemistry limitations:Higher biodiesel blends accelerate engine oil degradation, forcing more frequent drain intervals that partially offset volume gains from fleet expansion.
Strategic Opportunities
- Surabaya industrial logistics corridor penetration:East Java's freight concentration offers whitespace for bulk procurement contracts with fleet operators currently underserved by franchised networks.
- API SP and ILSAC GF-6 specification adoption:BSN's pending alignment with these international standards creates first-mover advantage for blenders with pre-certified product portfolios.
- Quick-lube channel digitization:Workshop management software integration enables predictive maintenance scheduling and direct-to-fleet subscription models in Greater Jakarta.
Industry Challenges
- Additive package formulation expertise scarcity:Local blending facilities lack in-house tribology capabilities, creating dependency on international technical licensing partnerships.
- SNI certification timeline compression:Reformulation cycles must accelerate to maintain market access as BSN tightens testing protocols, straining R&D bandwidth at mid-sized domestic blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Automotive Engine Oils Market |
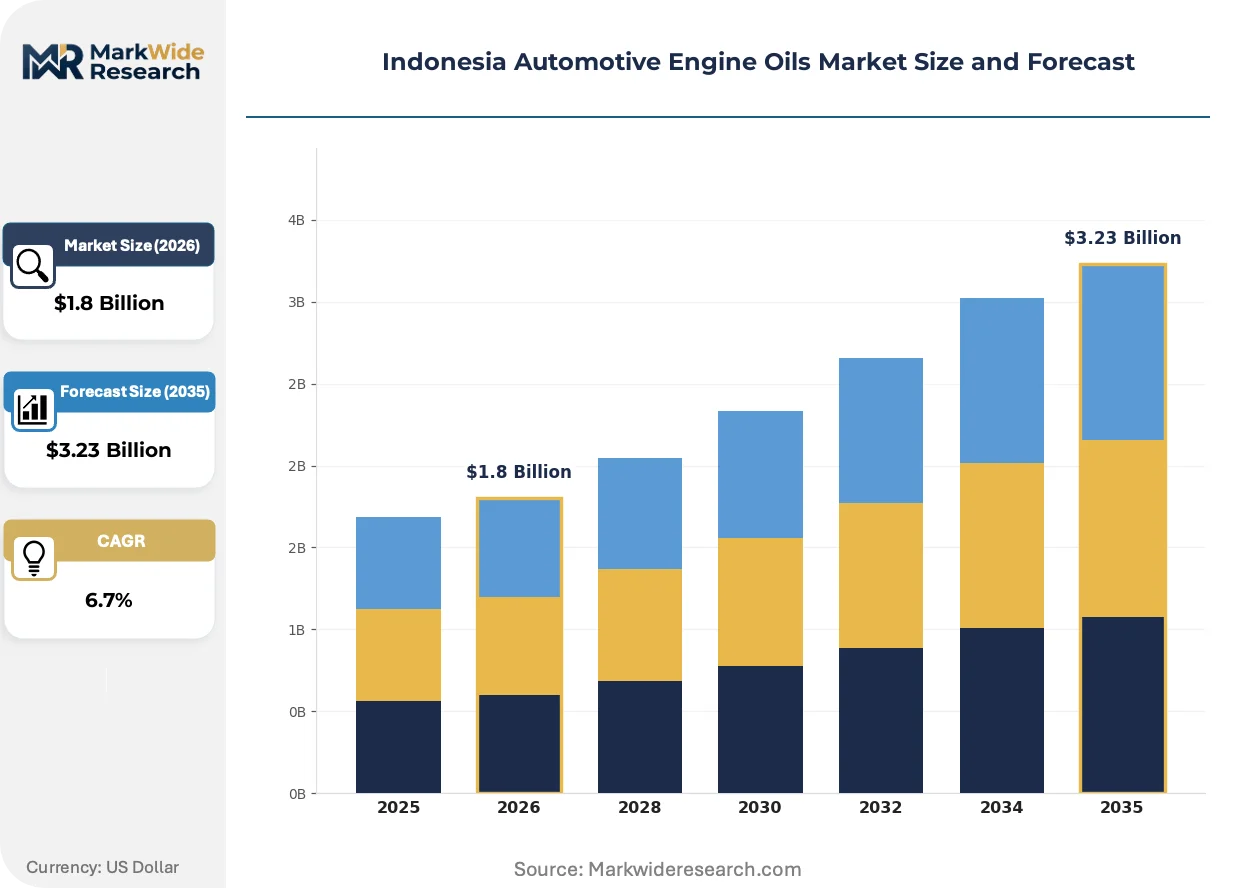
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Conventional, High-Mileage Viscosity Grade: SAE 0W-20, SAE 5W-30, SAE 10W-40, SAE 15W-50 Delivery Mode: Online, Retail, Wholesale, Distributor Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Equipment |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies, PT Pertamina, PT Wiraswasta Gemilang Indonesia (Evalube), ENEOS Corporation, Shell plc, Chevron Corporation, FUCHS, BP plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Automotive Engine Oils Market Shifts & Advancements
Electrification of Indonesia's two-wheeler fleet is beginning to alter lubricant demand composition, while regulatory alignment with international specifications and channel consolidation are restructuring how engine oils reach end-users across the archipelago.
Low-viscosity synthetic formulations are electrifying product development priorities as OEMs specify SAE 0W-20 and SAE 5W-30 grades for newer passenger vehicle platforms. Japanese-brand car fleets in Greater Jakarta and Surabaya are adopting these specifications fastest, with service intervals stretching toward 15,000 kilometers. This viscosity grade compression is electrifying margin structures away from high-volume mineral oils toward additive-intensive synthetics requiring technical marketing support.
BSN's adoption of API SP and ILSAC GF-6 specifications is forcing reformulation investment across domestic blending facilities. The technical committees are tightening NOACK volatility limits to match ASEAN harmonization frameworks, disqualifying legacy additive packages from certified product lines. Passenger vehicle applications face the steepest compliance burden, while motorcycle-specific formulations navigate a parallel SNI certification track with distinct tropical performance benchmarks.
Workshop procurement consolidation is compressing distributor margins as independent service centers in Java's urban corridors aggregate into buying cooperatives. These entities negotiate direct bulk contracts with lubricant suppliers, bypassing traditional wholesale channels that historically captured value through fragmented last-mile delivery. The shift is most visible in Greater Jakarta's commercial vehicle servicing zones, where fleet operators and multi-site workshop chains now represent the dominant volume aggregation points.
Indonesia Automotive Engine Oils Market Segmentation
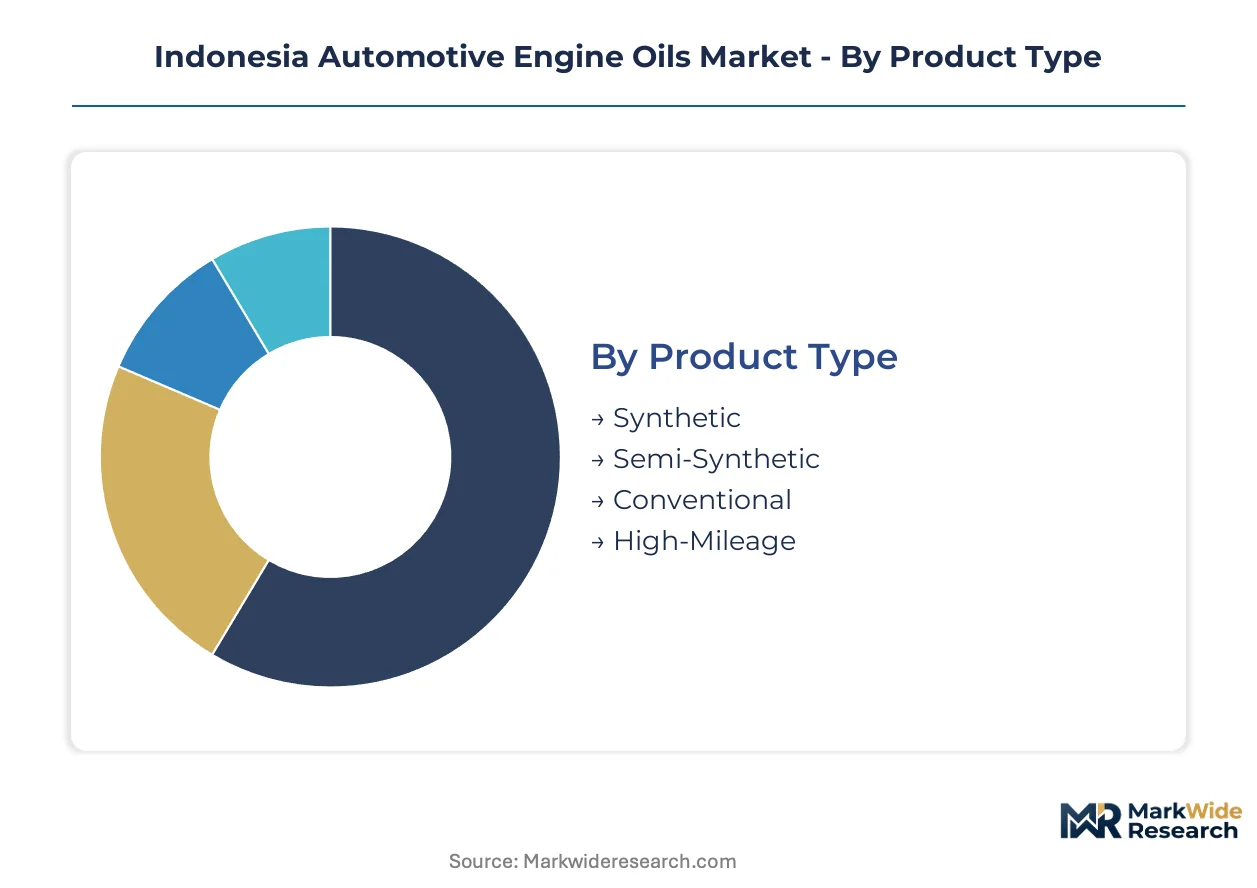
Segmentation in Indonesia's automotive engine oils market reveals how formulation chemistry, distribution economics, and vehicle fleet composition intersect. Understanding these divides exposes where margin pools concentrate and where volume expansion faces structural barriers.
Product Type:
Customization intensity spans from commodity mineral formulations to precision-engineered synthetics requiring additive package licensing.
- Synthetic:Formulated from Group III/IV base stocks with tailored additive chemistry for extended drain intervals. Demand concentrates in Greater Jakarta's Japanese-brand passenger vehicle service centers where OEM specifications mandate SAE 0W-20 and SAE 5W-30 grades. BSN's pending API SP alignment is accelerating reformulation investment among blenders seeking premium positioning.
- Semi-Synthetic:Blends Group II base oils with synthetic content to balance performance and cost. Surabaya's commercial fleet operators favor these formulations for medium-duty trucks operating under B20 biodiesel mandates, where oxidation stability requirements outpace conventional chemistry.
- Conventional:Mineral-based formulations using Group I base oils dominate Java's motorcycle aftermarket where per-liter price sensitivity overrides total cost of ownership calculations.
- High-Mileage:Seal-conditioning additive packages address aging passenger vehicle parc in tier-two Indonesian cities where vehicle retention exceeds national averages.
Most installed capacity flows through Conventional. Expansion is steepest in Synthetic.
Viscosity Grade:
Grade selection tracks thermal operating conditions and OEM warranty compliance across Indonesia's tropical climate.
- SAE 0W-20:Ultra-low viscosity synthetic formulations specified for newer Japanese passenger vehicle platforms. Greater Jakarta's premium quick-lube networks report fastest adoption curves as drain intervals stretch toward 15,000 kilometers.
- SAE 5W-30:Versatile grade spanning passenger cars and light commercial vehicles. Balances cold-start protection with high-temperature shear stability under Indonesian ambient temperatures averaging 25-30°C.
- SAE 10W-40:Workhorse grade for air-cooled motorcycle engines operating in urban Java's stop-start traffic patterns. Independent workshops specify this grade for 70% of two-wheeler servicing volume.
- SAE 15W-50:Heavy-duty protection for commercial vehicles and high-performance motorcycles operating under sustained load conditions in East Java's industrial corridors.
Volume leadership sits with SAE 10W-40. Technical specification tightening is pulling fastest growth into SAE 0W-20.
Delivery Mode:
Channel structure determines margin capture and customer relationship depth across fragmented versus consolidated demand.
- Online:Direct-to-consumer platforms and B2B procurement portals. Fleet operators in Greater Jakarta increasingly aggregate orders through digital channels for price transparency.
- Retail:Fuel station convenience stores and automotive parts shops. Pertamina's state-backed network dominates this channel with lubricant sales bundled at refueling points.
- Wholesale:Bulk procurement aggregators serving independent workshop chains. Surabaya's buying cooperatives negotiate direct blender contracts, compressing traditional distributor margins.
- Distributor:Traditional stock-and-sell intermediaries with last-mile delivery capabilities. Losing share fastest to disintermediation in Java's urban corridors.
Wholesale captures the largest value pool. Online is climbing the fastest.
Application:
Vehicle parc composition and duty cycles dictate formulation requirements and service interval economics.
- Passenger Vehicles:Japanese-brand fleets dominate, driving synthetic adoption through OEM-specified extended drain intervals. BSN's NOACK volatility limits target this segment most aggressively.
- Commercial Vehicles:Diesel-heavy freight and logistics operations face fuel dilution challenges under B20 mandates. East Java's industrial corridors concentrate fleet-scale procurement.
- Motorcycles:Air-cooled engines in tropical stop-start conditions favor SAE 10W-40 mineral formulations. Price sensitivity at independent workshops constrains premium migration.
- Heavy-Duty Equipment:Mining and construction machinery in Kalimantan and Papua require high-TBN formulations for severe service intervals.
Motorcycles represent the largest volume base. Passenger vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing blending capacity toward jurisdictions with streamlined SNI certification pathways and lower base oil import tariffs. Indonesia's B20 biodiesel mandate and tightening NOACK volatility limits are accelerating this migration as regional competitors adjust formulation standards to capture displaced volume.
Greater Jakarta
Japanese-brand passenger vehicle fleets dominate lubricant consumption, with OEM-specified SAE 0W-20 and SAE 5W-30 grades driving synthetic adoption through extended drain intervals. BSN's pending API SP alignment is forcing reformulation investment among blenders serving this corridor. Shell plc's franchised quick-lube networks concentrate in Jakarta's commercial vehicle servicing zones, capturing premium synthetic volumes from fleet operators.
Surabaya and East Java
Industrial logistics corridors anchor diesel-heavy commercial fleet operations where B20 fuel dilution challenges accelerate engine oil degradation. The Ministry of Energy and Mineral Resources administers biodiesel mandates that alter formulation requirements for oxidation stability. Buying cooperatives of independent workshops now negotiate direct bulk contracts with lubricant suppliers, bypassing traditional wholesale distributors.
Urban Java Motorcycle Corridors
Air-cooled two-wheeler engines operating in stop-start tropical traffic patterns favor SAE 10W-40 mineral formulations where per-liter price sensitivity constrains premium migration. PT Pertamina's state-backed fuel station retail network extends reach into tier-two cities, bundling lubricant sales at refueling points. Independent workshops specify this grade for approximately 70% of two-wheeler servicing volume.
Bandung and West Java Manufacturing Belt
Light commercial vehicle fleets and passenger car parc expansion are pulling semi-synthetic volumes into replacement cycles. Local blending facilities lacking in-house tribology capabilities depend on international technical licensing partnerships for additive package formulation. Exxon Mobil Corporation leverages these arrangements to compete in the semi-synthetic tier against domestic competitors.
Kalimantan and Papua Heavy-Duty Zones
Mining and construction machinery require high-TBN formulations for severe service intervals in remote operating conditions. Supply chain logistics favor bulk procurement contracts with fleet operators currently underserved by franchised quick-lube networks. API Group I base oil import dependency from Singapore refining hubs exposes blenders to feedstock cost volatility in these frontier markets.
Indonesia Automotive Engine Oils Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international majors commanding premium synthetic positioning while domestic blenders anchor volume tiers through fuel station retail and workshop networks. The market exhibits tiered concentration: three global integrated oil companies dominate the premium synthetic segment, mid-sized domestic blenders capture motorcycle aftermarket volume, and technical licensing partnerships fill capability gaps in additive formulation. Strategic moves center on quick-lube channel digitization for predictive maintenance scheduling and direct-to-fleet subscription models in Greater Jakarta, alongside SNI certification pre-positioning as BSN tightens testing protocols.
Among global integrated oil companies, Shell plc, Exxon Mobil Corporation, and BP plc occupy positions exemplifying the premium synthetic archetype through franchised network control and technical marketing investment. PT Pertamina anchors the state-backed distribution tier with fuel station retail reach into secondary cities. Domestic specialists PT Wiraswasta Gemilang Indonesia and ENEOS Corporation represent mid-scale blenders navigating SNI compliance through reformulation partnerships. TotalEnergies, Chevron Corporation, and FUCHS sit within the technical licensing tier, supplying additive packages and formulation expertise to capacity-constrained local facilities.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies |
| PT Pertamina |
| PT Wiraswasta Gemilang Indonesia (Evalube) |
| ENEOS Corporation |
| Shell plc |
| Chevron Corporation |
| FUCHS |
| BP plc |
| Others |
Supply & Pricing Matrix
Indonesia's B20 biodiesel mandate gates qualified supply and premium-tier pricing access as blenders reformulate additive packages to manage fuel dilution chemistry, while BSN's tightening NOACK volatility limits disqualify legacy formulations from certified product lines serving Japanese OEM specifications.
Pricing Analysis
Distributor margin compression dominates channel economics as Surabaya's buying cooperatives negotiate direct bulk contracts with lubricant suppliers, bypassing traditional wholesale intermediaries. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels reflects SNI certification grade and volume scale, with pricing pressure intensifying in the motorcycle aftermarket where independent workshops prioritize per-liter cost. Fleet operators in Greater Jakarta exhibit lowest price sensitivity due to total cost of ownership calculations around extended drain intervals.
Supply Chain Analysis
SNI certification gating restricts qualified supply to blenders with API SP and ILSAC GF-6 pre-certified portfolios, concentrating formulation expertise among Singapore, Malaysia, and Thailand refining hubs that feed Indonesian blending facilities. Raw material dependencies center on API Group I/II base oil imports, additive package licensing from international majors, and packaging materials from regional converters. Single-source vulnerability around Singapore refining exposure creates feedstock cost volatility, while distribution runs through Pertamina's fuel station retail network, wholesale buying cooperatives, and quick-lube franchised channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Indonesia's automotive engine oils market rests on synthetic grade migration and SNI certification pre-positioning as cost-down drivers reshape competitive economics.
For Market Incumbents: To counter buying cooperative disintermediation in Surabaya and Greater Jakarta, anchor channel control through quick-lube digitization investments enabling predictive maintenance scheduling and direct-to-fleet subscription models. Deepen backward integration into additive formulation capabilities to reduce dependency on international technical licensing partnerships as BSN accelerates testing protocol timelines. For New Entrants and Emerging Players: BSN's pending API SP alignment in Indonesia opens a window for first-mover positioning among mid-sized domestic blenders lacking reformulation bandwidth, targeting Surabaya's industrial logistics corridor with oxidation-stable semi-synthetic formulations for B20 commercial fleets. Pursue technical licensing partnerships with established additive suppliers as the go-to-market angle to bypass in-house tribology capability gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic blenders facing SNI certification timeline compression without captive additive expertise, offering consolidation plays for technical capability arbitrage. The long-term viability window favors targets with pre-certified synthetic portfolios and quick-lube channel relationships in Greater Jakarta. Watch BSN's formal adoption date for API SP specifications as the inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Lube Channel Digitization | Workshop management software integration enables predictive maintenance scheduling and fleet subscription models in Greater Jakarta. |
| SNI Certification Pre-Positioning | Early API SP and ILSAC GF-6 alignment secures market access before BSN tightens testing protocols. |
| Backward Integration into Additive Formulation | In-house tribology capabilities reduce dependency on Exxon Mobil and TotalEnergies technical licensing partnerships. |
| Direct Fleet Procurement Contracts | Bulk agreements with Surabaya logistics operators bypass wholesale distributor margin layers. |
| Low-Viscosity Synthetic Portfolio Expansion | SAE 0W-20 and SAE 5W-30 grades capture Japanese-brand passenger vehicle drain interval extension. |
Research Methodology
Bottom-up vehicle fleet modeling reconciled against top-down lubricant blending capacity tracking forms the analytical core of this study. Primary interviews with lubricant blending facility managers, quick-lube network operators, fleet procurement directors, and BSN technical committee members combined with secondary validation from SNI certification registries, Ministry of Energy biodiesel mandate documentation, and ASEAN lubricant trade flow data. Top-down supply-side assessment triangulates against bottom-up demand aggregation across passenger vehicle, commercial fleet, and motorcycle application segments.
Input-output matrices map base oil import volumes, additive package sourcing patterns, and distribution channel throughput against vehicle parc expansion and drain interval evolution across the projection horizon. Segmentation dimensions span product type, viscosity grade, delivery mode, and application, with CAGRs derived from elasticity modeling around OEM specification adoption curves and regulatory compliance timelines. Forecast inputs incorporate B20 mandate implementation pace and BSN standards alignment schedules.
Revisions become necessary when BSN accelerates SNI certification timelines or biodiesel blend mandates expand beyond B20, altering formulation chemistry requirements and qualified supplier pools. A model refresh is warranted upon material change in Japanese OEM specification adoption rates for low-viscosity synthetic grades.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Timing Gear Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Rammer Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Parts Zinc Die Casting Market