
 Automotive Air Compressor Market | 2026-2036
Automotive Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Compressor Market Outlook
The automotive air compressor landscape is restructuring around a widening split between premium electric compressor systems for EV thermal management and commodity reciprocating units serving legacy internal combustion fleets. Denso Corporation leverages its integrated thermal systems portfolio to dominate electric compressor development for battery cooling. Valeo sustains competitive pressure through specialized scroll compressor designs optimized for heat pump architectures.
An automotive air compressor is a mechanical device that pressurizes atmospheric air to between 100 and 175 psi for vehicle pneumatic and thermal systems, typically employing reciprocating pistons, rotary screws, or scroll mechanisms driven by belt, direct engine coupling, or electric motor. Its primary commercial purpose spans tire inflation, air brake actuation in commercial vehicles, and increasingly climate control and battery thermal regulation in electrified powertrains. Fixed compressors integrated into OEM assembly lines capture the largest margin pool due to long-term supply agreements and specification lock-in, while electric compressor technology within the rotary screw and scroll categories represents the fastest-expanding segment as vehicle electrification accelerates. Reciprocating technology retains volume leadership in aftermarket workshops and developing-market vehicle parc maintenance.
The EPA enforces evaporative emission and fuel economy standards that directly constrain compressor energy consumption in US vehicle certification cycles, while EMA oversees European compressor performance benchmarks through the EU Green Deal's embedded vehicle efficiency mandates. China's MIIT imposes GB standards on electric vehicle thermal management components, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and Beijing reshape product development prioritization and capital allocation for compressor platform architectures.
Market Dynamics
The automotive air compressor sector is bifurcating around electrification-driven thermal management demand, with OEM specification power concentrating margin capture toward integrated electric compressor platforms while legacy pneumatic applications commoditize.
Growth Catalysts
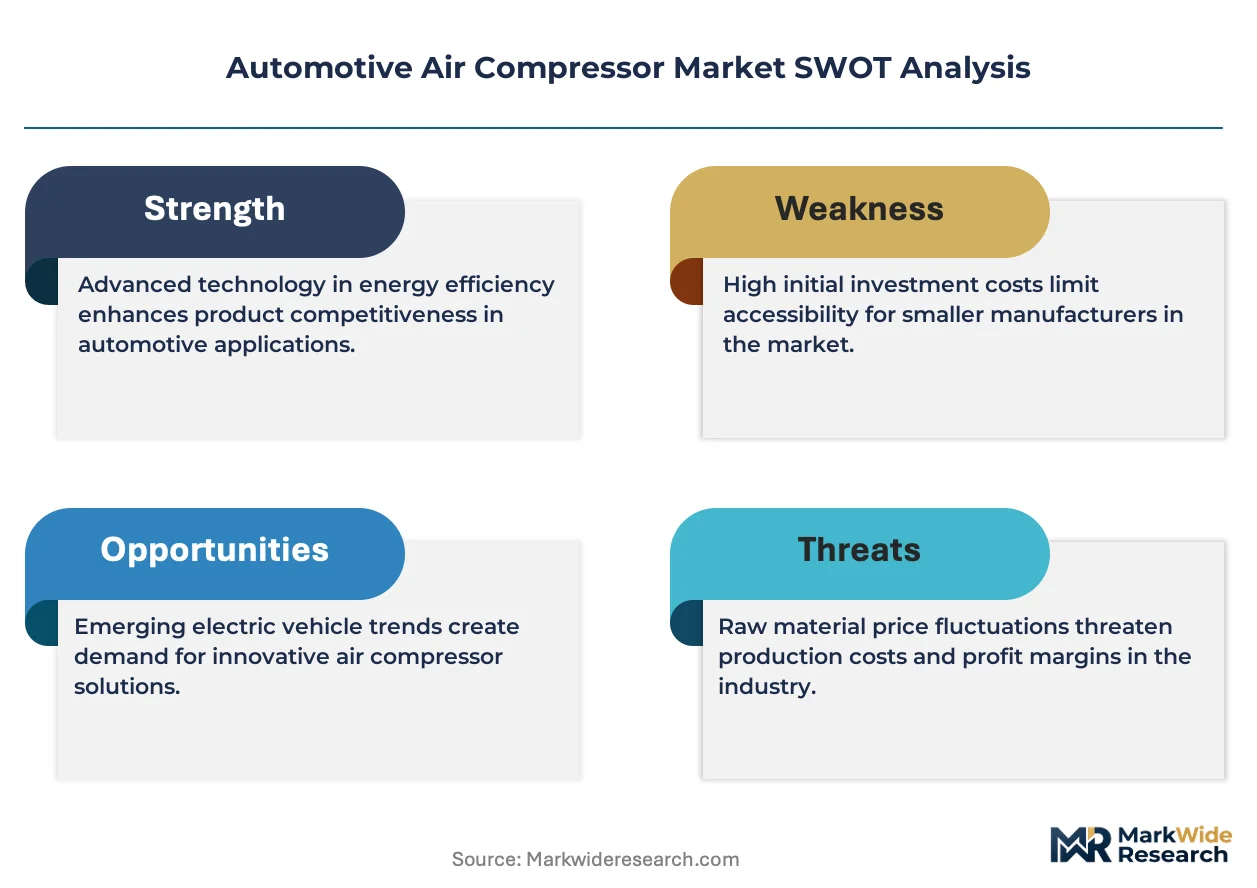
- EPA Tier 3 evaporative emission mandates:These standards force compressor energy efficiency improvements in US vehicle certification cycles, pulling advanced scroll and rotary screw designs into mainstream powertrain thermal systems.
- Heat pump architecture proliferation:EV battery conditioning and cabin climate control now require dedicated electric compressors, displacing belt-driven mechanical units in electrified vehicle segments.
- China's MIIT GB standards for EV thermal management:Domestic certification requirements accelerate local supply chain maturation for electric compressor components serving the world's largest automotive production base.
Market Restraints
- Copper and rare earth magnet cost volatility:Electric compressor motor production faces input price instability from concentrated mining operations in select geographies, compressing margins on fixed-price OEM contracts.
- Reciprocating technology lock-in:Legacy internal combustion vehicle parc maintenance sustains demand for mature piston compressor architectures, delaying full platform transition to electrified designs.
- REACH substance restrictions on refrigerants:European chemical regulations constrain working fluid choices for heat pump compressors, extending R&D timelines for compliant system validation.
Strategic Opportunities
- Commercial vehicle air brake electrification:Heavy-duty truck and bus segments in Germany and the United States present untapped demand for electrically actuated compressor systems replacing engine-driven pneumatic units.
- India's PLI scheme for automotive components:Production-linked incentives attract compressor manufacturing investment targeting domestic EV thermal management and export-oriented aftermarket supply.
- Digital twin-enabled predictive maintenance:Sensor-integrated compressor systems create recurring revenue streams through condition monitoring services bundled with OEM fleet management contracts.
Industry Challenges
- Electrified powertrain thermal modeling expertise:Compressor suppliers face acute shortages of engineers capable of integrating battery cooling loops with heat pump architectures across varying ambient operating conditions.
- Dual certification pathway complexity:Simultaneous compliance with EPA evaporative standards and MIIT GB thermal regulations demands parallel validation investments, straining mid-tier supplier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Compressor Market |
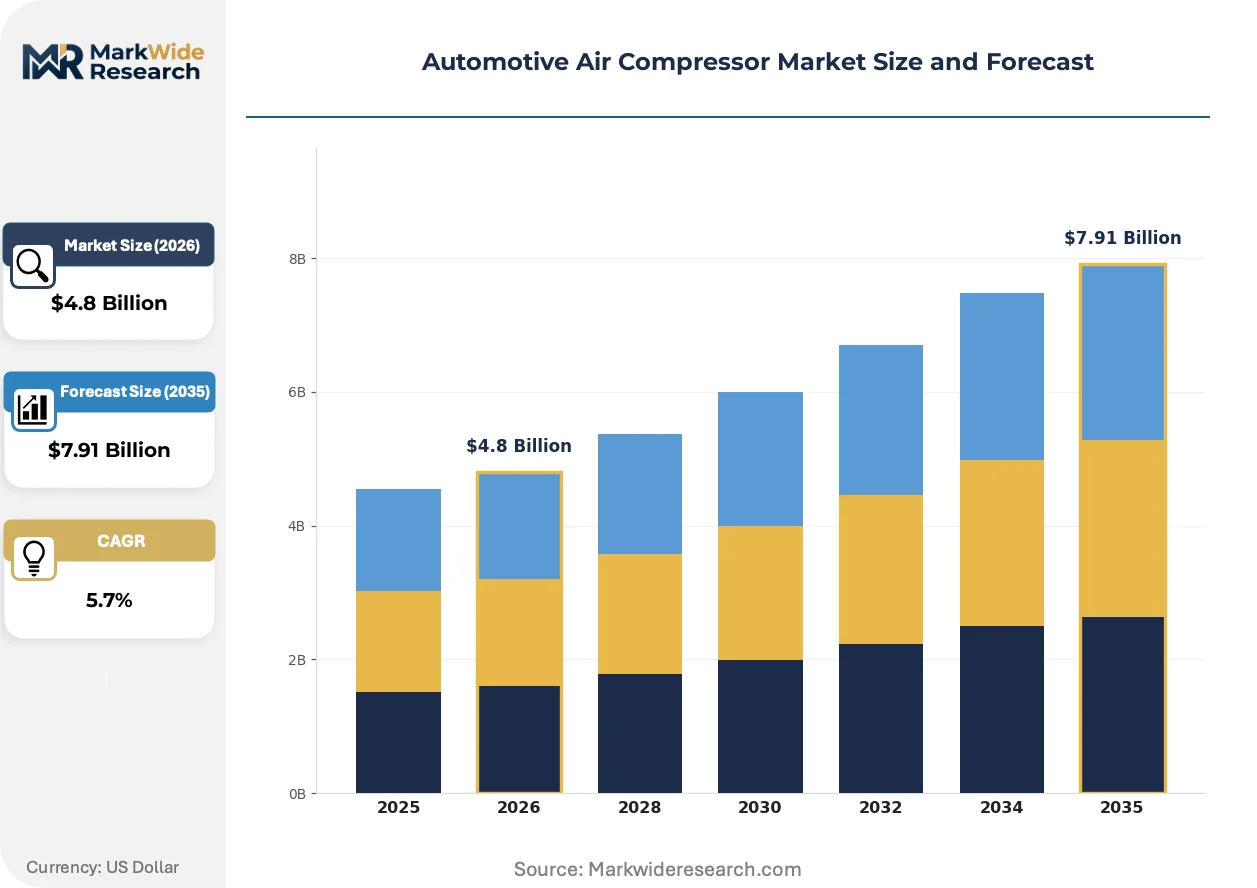
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Compressors, Fixed Compressors, Electric Compressors, Air Tools Technology: Reciprocating, Rotary Screw, Scroll, Centrifugal End User: OEMs, Aftermarket Providers, Workshops, Dealerships Application: Inflation, Pneumatic Tools, Painting, Cooling Systems |
| Companies Covered | Denso Corporation, Valeo, Sanden Corporation, Hanon Systems, MAHLE GmbH, BorgWarner, Aisin Seiki, Calsonic Kansei, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Compressor Market Strategic Shifts
Compressor technology is converging around electrification, with thermal management system integration replacing standalone pneumatic function as the primary value driver across passenger and commercial vehicle applications.
Integrated scroll-electric compressor modules are unifying battery cooling and cabin climate control functions into single packaged units. OEM thermal system architects specify these integrated designs for dedicated EV platforms, compressing supplier count per vehicle program from three discrete vendors to one integrated module provider.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential, forcing compressor manufacturers to validate alternative working fluids including CO2 and propane-based systems. European heat pump-equipped EV programs face compressed development timelines to certify low-GWP refrigerant compatibility before 2025 model year gates.
Fleet operators now specify compressor service intervals and energy consumption metrics as discrete procurement criteria separate from vehicle acquisition decisions. This unbundling of aftermarket service from initial equipment purchase concentrates buying power with large logistics providers in the United States and Germany, pressuring compressor suppliers to offer performance-guaranteed service contracts rather than component-only supply.
Automotive Air Compressor Market Segmentation
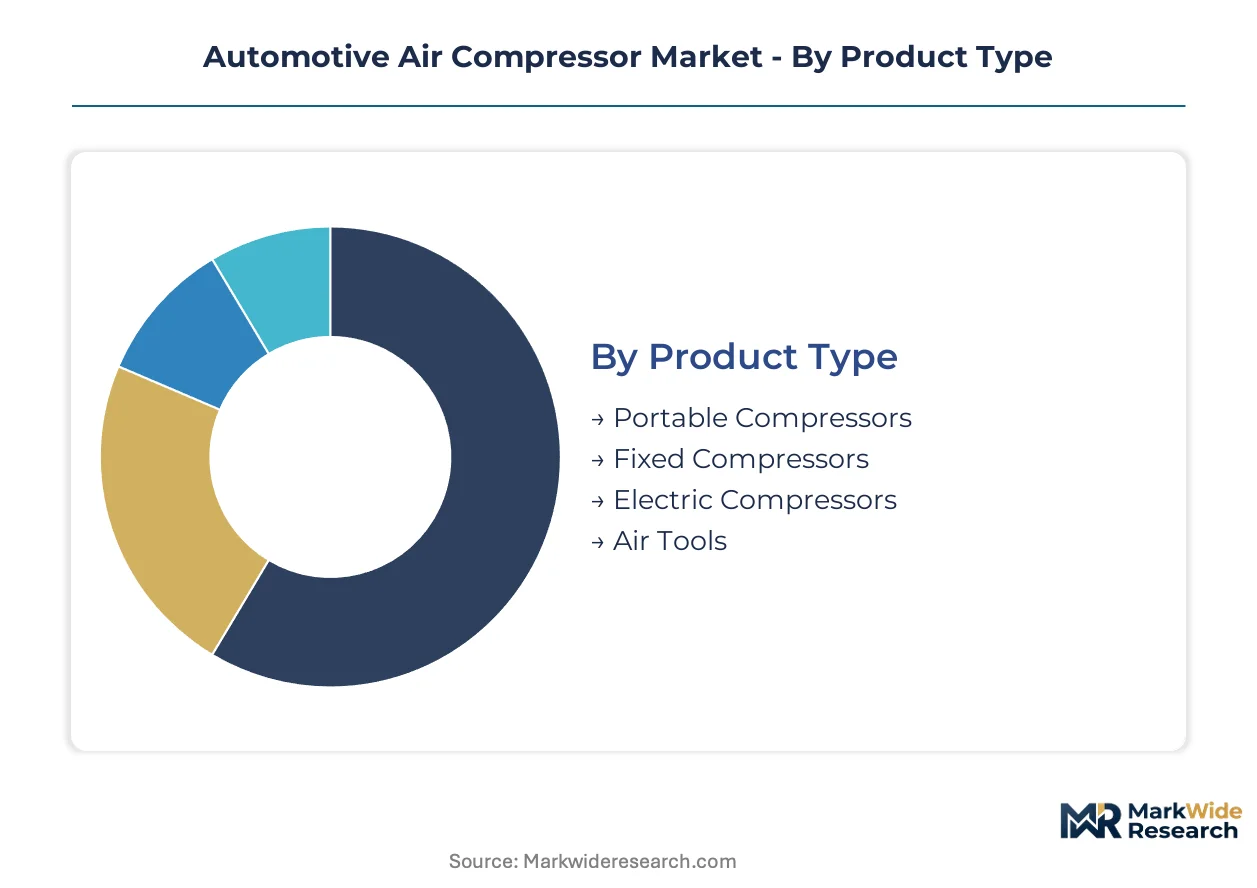
Automotive air compressor segmentation reveals divergent margin structures across electrification-driven thermal applications versus legacy pneumatic functions. Understanding these divides enables suppliers to allocate R&D capital between integrated EV platforms and commoditized aftermarket service.
Product Type:
Buyers differentiate primarily by power source integration and mobility requirements across vehicle lifecycle stages.
- Portable Compressors:Self-contained units powered by 12V vehicle outlets or onboard batteries deliver 100-150 psi for roadside tire inflation and emergency pneumatic tool operation. Demand concentrates in North American and European aftermarket channels where consumer DIY maintenance persists, constrained by lithium-ion battery cost volatility in cordless designs.
- Fixed Compressors:Permanently mounted belt-driven or direct-coupled units integrated into OEM assembly lines supply continuous compressed air for air brake systems and automated manufacturing processes. These installations lock in multi-year supply agreements with commercial vehicle manufacturers in Germany and the United States, generating the segment's highest margin pool through specification control.
- Electric Compressors:Motor-driven scroll and rotary screw architectures dedicated to EV thermal management and heat pump climate control. China's MIIT GB standards accelerate domestic certification requirements for battery cooling applications.
- Air Tools:Pneumatic wrenches, drills, and spray guns requiring regulated compressed air supply, predominantly serving professional workshop environments in mature vehicle parc regions.
Volume sits with Fixed Compressors; growth tilts toward Electric Compressors.
Technology:
Technology selection tracks powertrain electrification velocity and thermal system complexity thresholds.
- Reciprocating:Piston-driven positive displacement mechanisms dominate legacy internal combustion vehicle production and aftermarket maintenance. These mature architectures retain cost advantages for intermittent-duty tire inflation and small-scale workshop applications across India's expanding automotive service sector.
- Rotary Screw:Continuous-duty helical rotor designs deliver oil-free or oil-injected compressed air for commercial vehicle air brakes and industrial pneumatic systems. Demand clusters in heavy-duty truck manufacturing corridors of Michigan and Baden-Württemberg, where EPA Tier 3 efficiency mandates pull advanced designs into mainstream certification cycles.
- Scroll:Orbiting spiral plate compression enables precise capacity modulation for EV battery cooling and heat pump climate control. The EU F-Gas Regulation's hydrofluorocarbon phase-down forces accelerated validation of CO2 and propane-compatible scroll architectures.
- Centrifugal:Dynamic compression for high-volume, low-pressure applications in automated paint shops and large-scale manufacturing facilities serving premium vehicle assembly.
Reciprocating dominates installed base; Scroll gains share fastest on electrification tailwinds.
End User:
Procurement authority separates specification-setting vehicle manufacturers from price-sensitive maintenance channels.
- OEMs:Original equipment manufacturers command integrated thermal system sourcing for new vehicle platforms, consolidating supplier relationships around electric compressor module providers capable of dual certification to EPA and MIIT standards.
- Aftermarket Providers:Independent distributors and private-label suppliers serve fragmented workshop demand across mature vehicle parc regions, competing on inventory availability and replacement part compatibility.
- Workshops:Service facilities prioritize compressor reliability metrics and service interval predictability, particularly in Germany's TÜV-certified maintenance networks where downtime costs dominate procurement criteria.
- Dealerships:Authorized service channels tied to specific marques source proprietary compressor configurations through captive parts distribution systems.
Specification power concentrates with OEMs; margin pressure weighs most heavily on Aftermarket Providers.
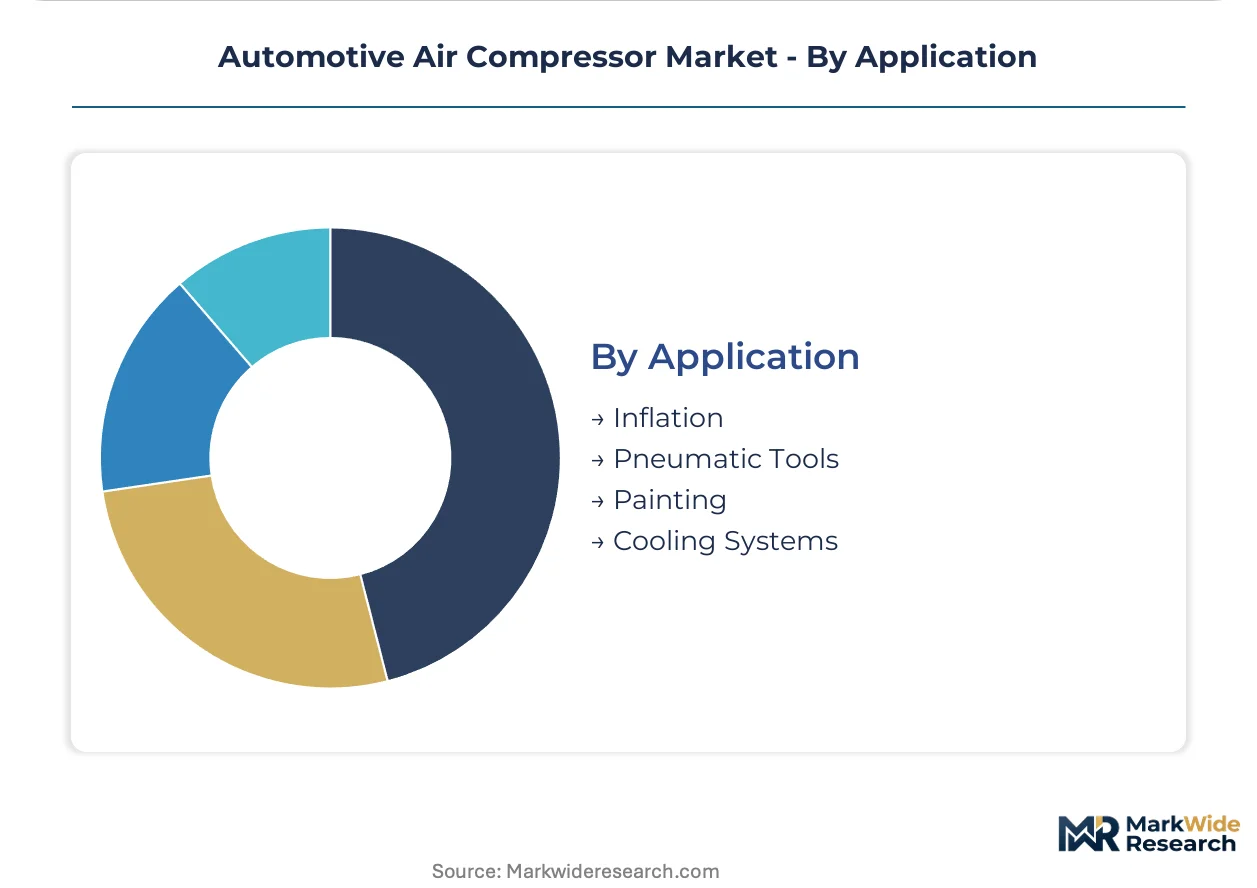
Application:
Functional purpose determines pressure, flow, and duty cycle requirements across vehicle operating environments.
- Inflation:Tire pressure maintenance for passenger and commercial vehicles represents the most price-elastic application, with portable and fixed reciprocating units competing on initial acquisition cost in emerging market service sectors.
- Pneumatic Tools:Continuous compressed air supply for impact wrenches, grinders, and riveting equipment in assembly and repair operations, requiring moisture separation and pressure regulation infrastructure.
- Painting:Oil-free compressed air for automotive refinishing and OEM coating applications, where particulate contamination tolerance approaches zero in premium vehicle segments.
- Cooling Systems:Refrigerant compression for cabin climate control and battery thermal regulation in electrified powertrains, displacing mechanical belt-driven units with dedicated electric motor architectures.
Inflation commands unit volume; Cooling Systems follow the steepest expansion trajectory on EV thermal management adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive compressor engineering density, with supplier engineering centers clustering along the Neckar-Alb industrial corridor where thermal system integration expertise concentrates.
United States
Commercial vehicle air brake electrification and EV thermal management adoption drive specification changes. EPA Tier 3 evaporative emission mandates force compressor energy efficiency improvements into vehicle certification cycles. Michigan's automotive manufacturing corridor hosts engineering centers where integrated electric compressor modules undergo validation for battery cooling applications.
Germany
Heat pump architecture proliferation in premium EV platforms and heavy-duty truck electrification create dual demand channels. EU F-Gas Regulation refrigerant phase-down accelerates CO2-compatible scroll compressor development timelines. Baden-Württemberg's supplier ecosystem concentrates validation facilities for low-GWP refrigerant systems serving domestic OEM thermal programs.
China
Domestic EV production scale and battery thermal management localization reshape supply chain geography. MIIT GB standards for electric vehicle thermal management components create divergent certification pathways. Yangtze River Delta manufacturing zones attract compressor component investment targeting both domestic integration and export supply.
Japan
Heat pump climate control adoption in domestic EV platforms and precision manufacturing heritage sustain technology leadership. METI energy efficiency guidelines shape compressor motor performance benchmarks. Kanto region engineering centers develop integrated thermal system architectures for next-generation electrified powertrains.
India
Expanding vehicle parc maintenance and emerging EV thermal management demand bifurcate market development. PLI scheme production-linked incentives attract automotive component manufacturing investment. Tamil Nadu and Gujarat automotive clusters host emerging compressor assembly capacity targeting domestic aftermarket and regional export.
Automotive Air Compressor Market Competitive Environment
Premium-margin players sit above commodity-margin players across thermal system integration capability, with specification-setting power concentrating toward integrated module providers while legacy pneumatic suppliers face procurement unbundling. The vendor base stratifies into three tiers: multinational thermal system integrators commanding OEM platform specification, regional specialists capturing aftermarket service contracts, and emerging Asian manufacturers scaling electric compressor component supply. Dominant competitive moves include strategic partnerships for refrigerant system co-development and geographic expansion through local assembly joint ventures.
Within the multinational integrator tier, Denso Corporation and Valeo occupy positions exemplifying thermal system consolidation, while MAHLE GmbH represents the European engineering-centric archetype. These entities anchor the specification-setting layer where long-term OEM supply agreements lock in platform-level integration. Zhengzhou-based specialists and other regional fabricators sit within the component supply tier, serving validation and manufacturing partnerships for multinational thermal system architects. The competitive dynamic centers on engineering resource concentration for dual certification to EPA and MIIT standards rather than price-based displacement.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo |
| Sanden Corporation |
| Hanon Systems |
| MAHLE GmbH |
| BorgWarner |
| Aisin Seiki |
| Calsonic Kansei |
| Delphi Technologies |
| Others |
Value Chain & Pricing Dynamics
OEM specification power for integrated electric compressor modules is compressing supplier margins on fixed-price contracts while forcing tier-2 fabricators toward commodity aftermarket channels. This demand-side concentration reshapes supply chain investment toward dual-certification capacity and captive component production.
Pricing Analysis
Performance-guaranteed service contracts now anchor value-based pricing for fleet operators in Germany and the United States who unbundle compressor procurement from vehicle acquisition. Three-tier pricing structure across premium, standard, and economy levels separates integrated thermal module providers from standalone electric compressor suppliers and legacy reciprocating vendors. Pricing pressure stems from copper and rare earth magnet cost volatility on electric motor production. Aftermarket workshop distributors exhibit highest price sensitivity; OEM platform engineers prioritize thermal integration performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated electric compressor modules serving dedicated EV platforms in China, Germany, and the United States. Manufacturing concentration draws from Yangtze River Delta zones for component fabrication, Baden-Württemberg for validation facilities, and Michigan for engineering integration. Critical inputs span copper windings, neodymium permanent magnets, and precision-machined scroll housings. Single-source vulnerability on rare earth magnet supply from concentrated mining geographies threatens production continuity. Distribution runs through captive Tier 1 supplier networks into OEM assembly plants, with aftermarket channels serving fragmented workshop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over refrigerant system co-development and electric motor winding capacity determines margin capture. Players are pursuing backward integration into rare earth magnet sourcing and scroll housing machining to defend specification-setting positions.
For Market Incumbents: Extend thermal system integration depth by acquiring scroll compressor specialists with MIIT GB certification capabilities, countering emerging Asian manufacturers scaling electric component supply. Lock in long-term rare earth magnet offtake agreements to insulate fixed-price OEM contracts from input cost volatility. Prioritize dual-validation investments for EPA Tier 3 and EU F-Gas Regulation compliance to maintain platform specification authority. For New Entrants and Emerging Players: Enter via India's PLI scheme production-linked incentives to establish compressor assembly capacity serving domestic EV thermal management demand and regional aftermarket export. Target commercial vehicle air brake electrification in Germany and the United States where specification standards remain unsettled and incumbent lock-in is weakest. Pursue joint venture structures with established refrigerant system developers to accelerate heat pump architecture validation. For Investors and Strategic Acquirers: The window for entry favors component specialists with captive electric motor production and MIIT GB certification pathways already initiated. Long-term viability hinges on exposure to EV platform thermal management rather than legacy pneumatic applications. Monitor copper and rare earth price correlation as the inflection signal for margin compression severity across supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant System Co-Development Partnership | Accelerates CO2-compatible scroll validation ahead of EU F-Gas Regulation phase-down deadlines. |
| Rare Earth Magnet Supply Agreement | Secures input cost stability for electric compressor motor production under fixed-price OEM contracts. |
| MIIT GB Certification Investment | Unlocks platform specification access for China's domestic EV production base. |
| Digital Twin Predictive Maintenance Platform | Creates recurring revenue streams through sensor-integrated compressor condition monitoring services. |
| Local Assembly Joint Venture | Positions manufacturing capacity within India's PLI incentive zones for domestic and export supply. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive air compressor market assessment. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and thermal system R&D directors combined with bottom-up production database analysis and top-down vehicle parc modeling. Secondary sources encompassed EPA certification filings, MIIT GB standard documentation, EU F-Gas Regulation implementation reports, and vehicle registration databases from IHS Markit.
Data-stream reconciliation across production volume estimates, content-per-vehicle assumptions, and regional EV adoption curves generated consistent trajectory outputs across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, compressor technology type, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of year-over-year segment growth rates applied to base-year sizing. Industry-specific forecast inputs included battery thermal management adoption curves and heat pump penetration rates by OEM platform.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt rare earth export restriction scenarios or accelerated refrigerant phase-down timelines. Forecasts reflect assumptions on EV production scaling, regulatory harmonization pace, and input material cost stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Spring Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market