
 South Africa Automotive Parts Aluminium Die Casting Market | 2026-2036
South Africa Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Parts Aluminium Die Casting Market Analytics
Aluminium is recalibrating product economics across South African automotive supply chains as OEMs replace cast iron in powertrain and structural assemblies. Rheinmetall Automotive leverages its European engineering heritage to anchor high-pressure die casting operations serving local vehicle assemblers. Martinrea Honsel sustains competitive positioning through specialized vacuum die casting capabilities for complex transmission housings. Georg Fischer dominates precision aluminium component supply to premium passenger vehicle programs manufactured in the Eastern Cape.
Automotive parts aluminium die casting involves injecting molten aluminium alloys—typically A380, A383, or AlSi10Mg—into hardened steel molds under pressures ranging from 1,000 to 20,000 psi, producing near-net-shape components with wall thicknesses below 3mm. Engine blocks and transmission housings command the largest volume share, reflecting established internal combustion vehicle architectures still prevalent in South African production. Electric vehicle heat sinks represent the fastest-growing application segment, driven by thermal management demands in battery and power electronics assemblies. High pressure die casting captures the dominant technology position, though vacuum die casting gains traction where porosity-sensitive structural integrity is required.
South Africa's National Regulator for Compulsory Specifications enforces automotive component quality benchmarks, while Department of Trade and Industry automotive production and development programme incentives mandate progressive local content thresholds. The South African Bureau of Standards coordinates aluminium alloy specifications with ISO standards to ensure export compatibility with European and Asian vehicle manufacturer requirements. Stakeholders must monitor evolving EV production commitments from domestic assemblers and corresponding shifts in die casting capacity allocation between traditional powertrain and electrification components.
Market Dynamics
South Africa's automotive aluminium die casting sector is recalibrating around the Department of Trade and Industry's Automotive Production and Development Programme, which tightens local content thresholds while assemblers accelerate electrification roadmaps. This dual pressure compresses supplier transition timelines.
Growth Catalysts
- APDP Incentive Structure:The Department of Trade and Industry's production rebates reward progressive localisation, compelling OEMs to deepen domestic sourcing of transmission housings and structural castings.
- Powertrain Lightweighting Mandates:Fuel efficiency regulations targeting CO₂ reductions are accelerating aluminium substitution for cast iron in engine blocks across Gauteng assembly plants.
- EV Thermal Management Demand:Battery and power electronics cooling requirements are generating new die casting capacity for heat sinks and liquid cooling plates in Eastern Cape manufacturing corridors.
Market Restraints
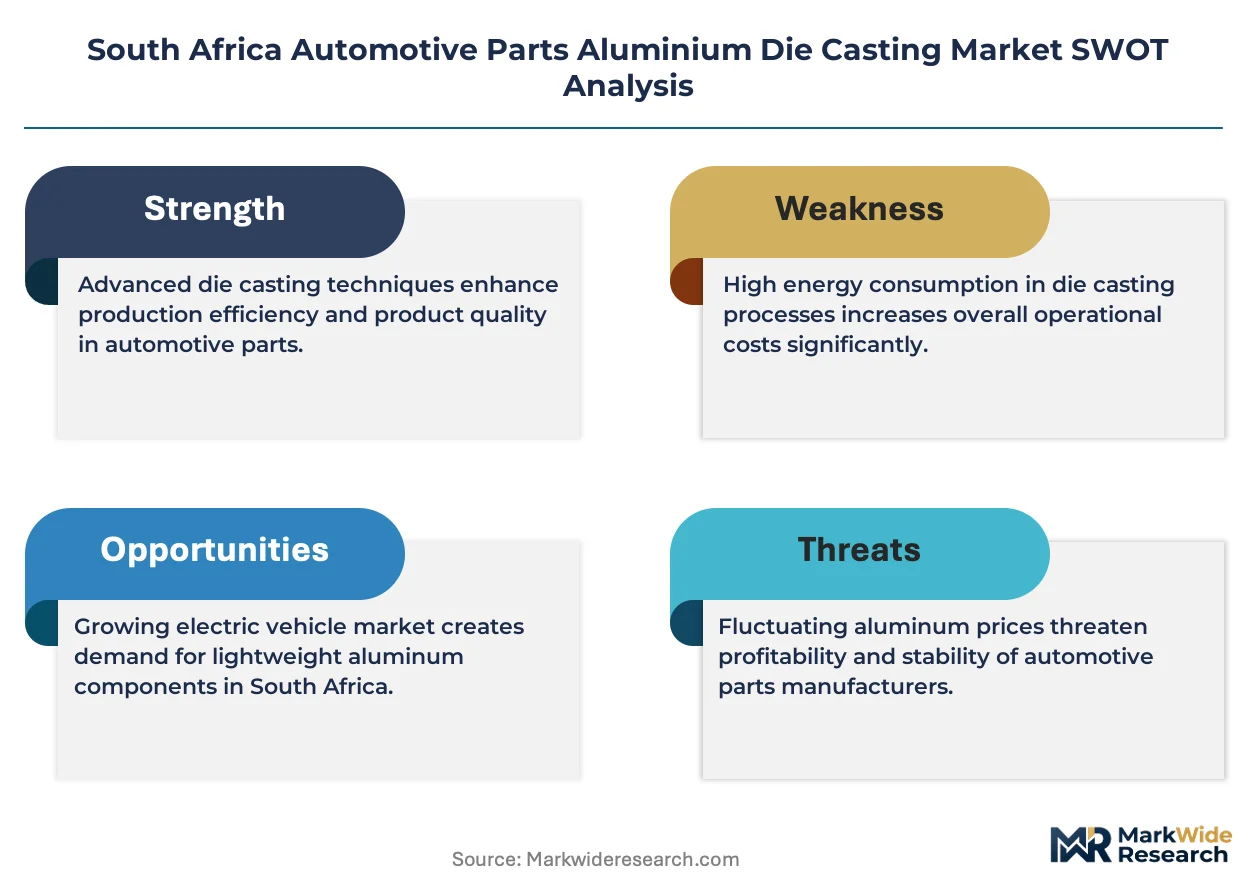
- Primary Aluminium Input Volatility:Die casters remain exposed to LME aluminium price swings and Rand/dollar exchange rate instability, compressing margin visibility on long-term OEM supply agreements.
- Smelter Concentration Risk:Domestic primary metal supply hinges on Hillside Aluminium and Mozal operations, creating geographic single-point vulnerability for A380 and AlSi10Mg alloy feedstock.
- Structural Substitution Pressure:Magnesium die casting and carbon fibre reinforced polymers are encroaching on non-structural aluminium applications in premium vehicle programs.
Strategic Opportunities
- Eastern Cape EV Supply Chain Formation:Volkswagen Group's ID.4 assembly commitment at Kariega is creating first-mover white space for localised battery housing and motor enclosure die casting.
- Vacuum Die Casting Technology Convergence:Porosity-sensitive structural applications are opening as vacuum-assisted high-pressure die casting merges with real-time X-ray quality verification systems.
- Recycled Alloy Certification Pathways:The South African Bureau of Standards' alignment with ISO 14021 environmental claims standards enables premium positioning for post-consumer scrap-fed die casting operations.
Industry Challenges
- Tooling Engineer Scarcity:Hardened steel mold design and flow simulation expertise is concentrating among retiring European-trained specialists, constraining new product introduction velocity.
- Dual-Process Capex Burden:Suppliers must simultaneously maintain high-pressure die casting lines for ICE components and commission vacuum-capable cells for EV structural parts without volume certainty.
- ISO/TS 16949 Transition Friction:IATF 16949 certification timelines and audit backlogs are delaying supplier qualification for new EV platform awards from domestic assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Parts Aluminium Die Casting Market |
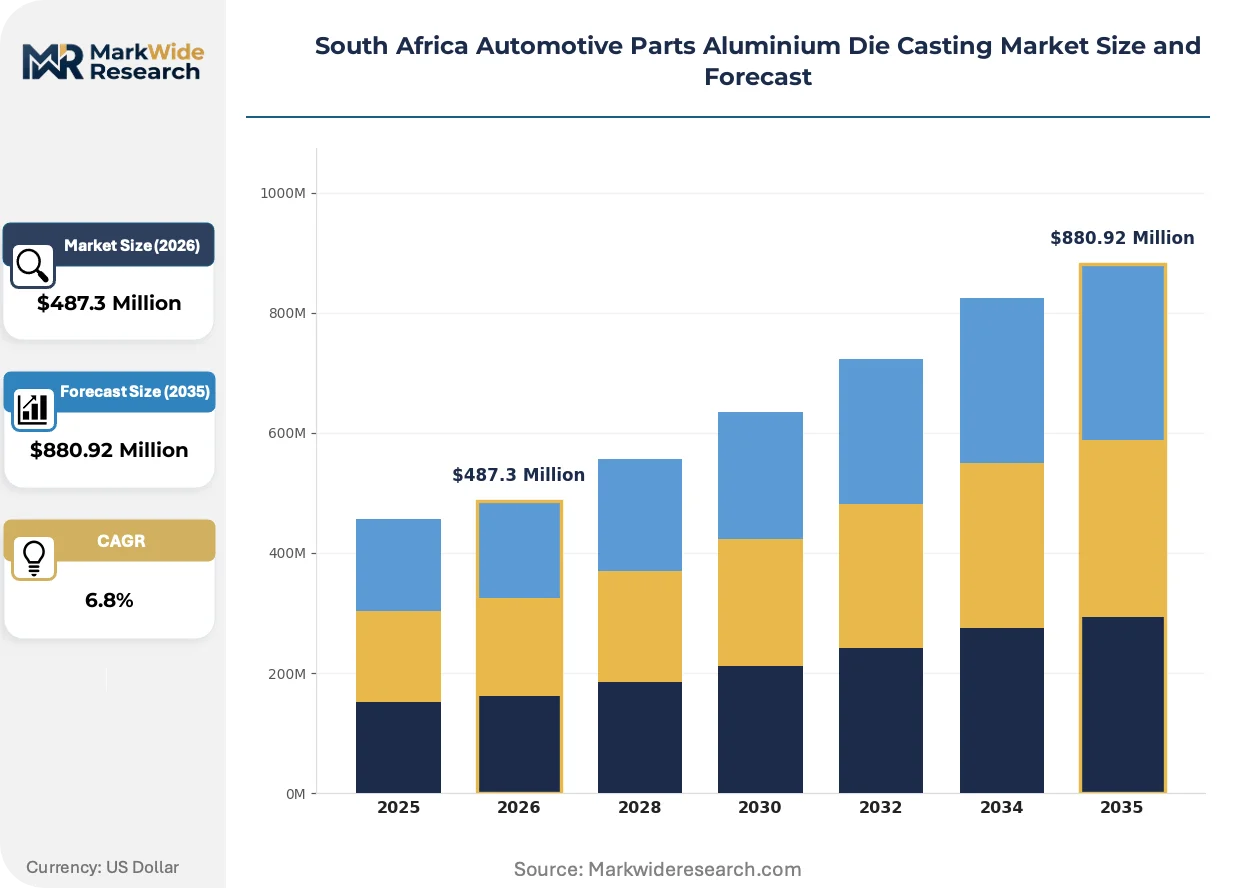
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Wheel Rims, Heat Sinks End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Personal Vehicles, Commercial Vehicles, Electric Vehicles, Heavy-Duty Trucks Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Steel Best Automotive, Lupton and Place, Kemlows Diecasting Products Ltd, Rheinmetall Automotive, Martinrea Honsel, Ryobi Die Casting, Georg Fischer, Buhler Group, Renuka Auto Components, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Parts Aluminium Die Casting Market Evolving Landscape
Process digitisation and alloy formulation advances are compressing development cycles for complex automotive castings. South African suppliers are retrofitting legacy equipment with sensor arrays while experimenting with secondary alloy blends to meet sustainability benchmarks.
Real-time cavity pressure monitoring is converging with machine learning defect prediction to enable closed-loop process control in high-pressure die casting cells. Tier-1 suppliers serving the Eastern Cape are piloting these systems to reduce porosity-related scrap rates. The technology is converging with automated sorting robotics to compress final inspection bottlenecks.
The South African Bureau of Standards' progressive harmonisation with ISO 14001 and IATF 16949 is tightening traceability requirements across the aluminium supply chain. Casting operations must now document alloy provenance and heat treatment parameters for OEM audit compliance. Vacuum die casting specialists are responding fastest, leveraging inherent quality advantages to secure structural component qualifications.
OEM technical sourcing teams are consolidating supplier panels and demanding integrated design-to-die capabilities. Long-term agreements now bundle simulation, rapid prototyping, and serial production under single-source accountability. Gauteng-based vehicle assemblers are driving this consolidation most aggressively, reducing qualified supplier pools for transmission housing programs by half over the past qualification cycle.
South Africa Automotive Parts Aluminium Die Casting Market Segmentation
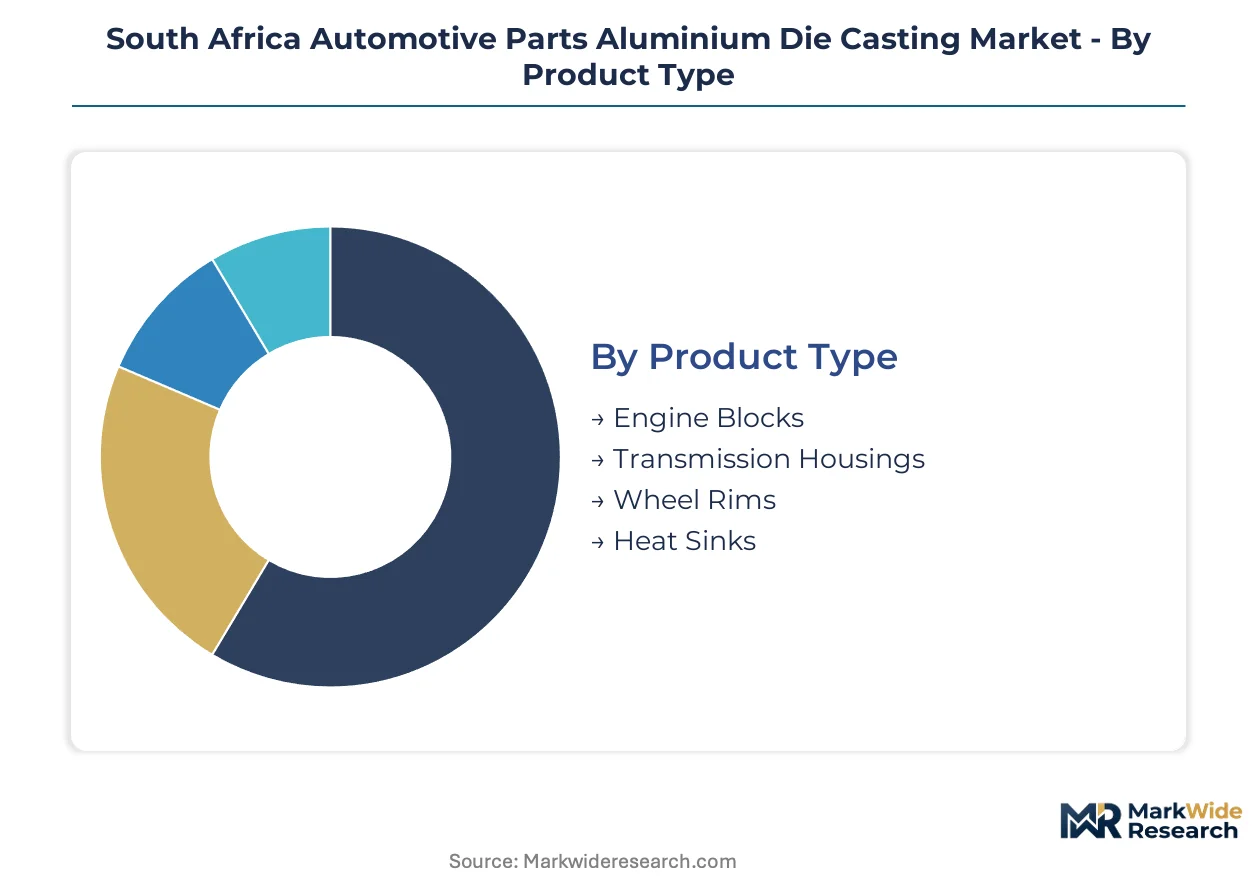
Segmentation reveals how South African die casters allocate capital across divergent technology platforms and customer tiers. Product mix decisions determine exposure to ICE decline versus EV growth curves.
Product Type:
Standalone structural castings dominate capital allocation, while embedded thermal components require tighter integration with customer design cycles.
- Engine Blocks:These A380 alloy castings incorporate water jacket cores and main bearing bulkheads, serving Gauteng-based internal combustion assembly lines. Demand concentrates at Ford Silverton and Toyota Prospecton plants as local content rules tighten, though electrification timelines threaten long-term volume commitments.
- Transmission Housings:Complex multi-slide tooling produces clutch bell housings and gear carrier assemblies with wall thickness tolerances below 0.5mm. Eastern Cape suppliers capture Volkswagen and Mercedes-Benz program awards where vacuum-assisted casting meets structural integrity specifications.
- Wheel Rims:Gravity and low-pressure variants supply aftermarket replacement channels and premium OE fitments.
- Heat Sinks:EV battery module cooling plates and inverter thermal management components represent the steepest expansion trajectory.
Engine blocks lead volumes today; heat sinks are gaining share fastest.
End User:
Customer concentration varies sharply by contract duration and design control, with assemblers dictating specifications while Tier-1s manage supplier panels.
- OEMs:Original equipment manufacturers specify alloy grades and cavity pressure parameters directly, sourcing transmission housings and structural nodes through captive foundry arrangements or tightly qualified external suppliers.
- Aftermarket Providers:Independent distributors and remanufacturers procure replacement engine blocks and wheel rims with relaxed certification requirements.
- Tier-1 Suppliers:System integrators like driveline specialists consolidate die casting procurement under long-term platform agreements, qualifying multiple foundries per component family.
- Vehicle Assemblers:Final assembly operations in Rosslyn, Uitenhage, and Durban source completed powertrain modules with die cast housings pre-integrated.
Tier-1 suppliers concentrate procurement spend; vehicle assemblers are consolidating supplier panels most aggressively.
Application:
Vehicle architecture determines casting complexity and thermal performance requirements, with electrification shifting demand toward heat-dissipating geometries.
- Personal Vehicles:Passenger car programs at Toyota, Volkswagen, and Ford drive high-volume transmission housing demand with stringent porosity limits.
- Commercial Vehicles:Medium-duty truck engine blocks require thicker sections and enhanced fatigue resistance for extended duty cycles.
- Electric Vehicles:Battery enclosures, motor housings, and power electronics cooling plates command premium vacuum die casting capacity.
- Heavy-Duty Trucks:Mining and logistics fleet operators specify reinforced structural castings for chassis and suspension components.
Personal vehicles anchor current output; electric vehicles are climbing the fastest.
Technology:
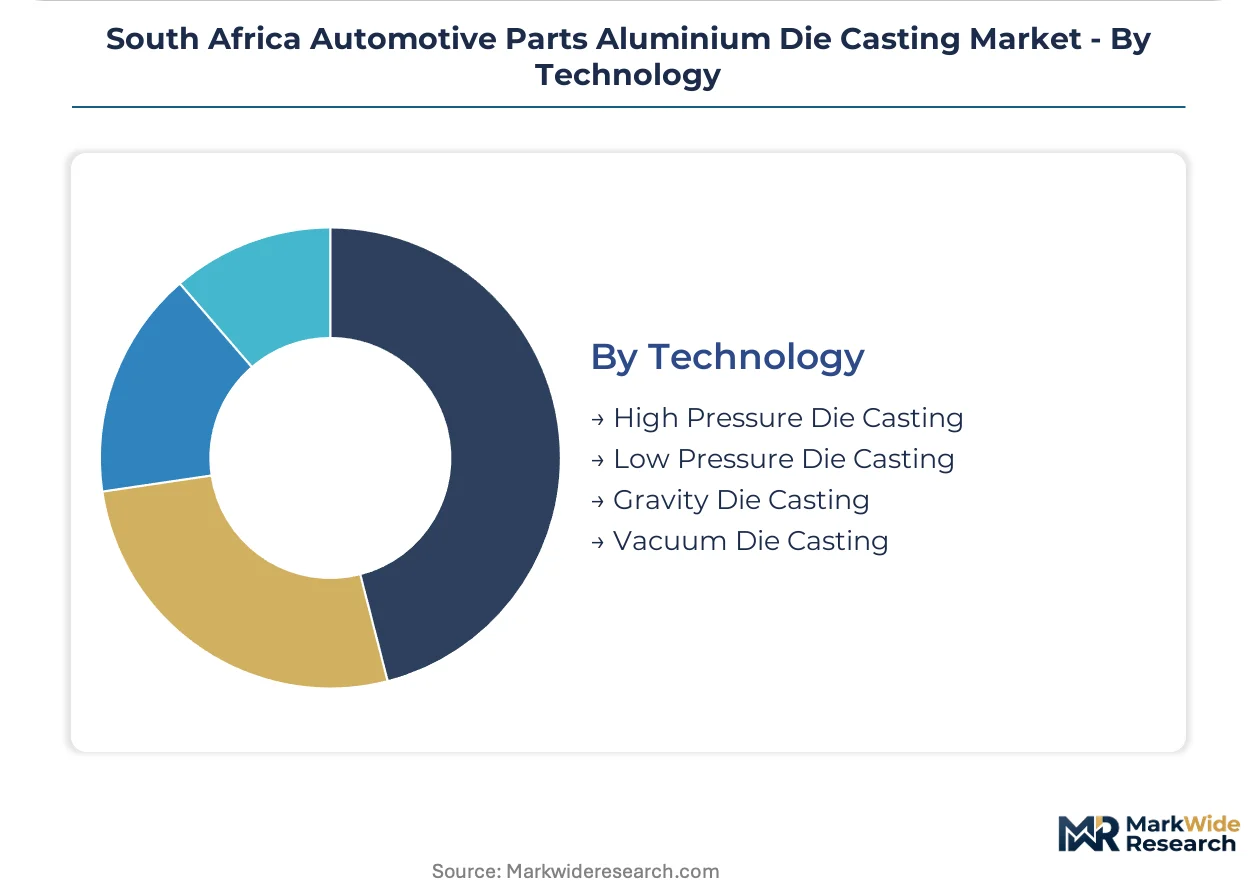
Process selection trades cycle time against porosity control, with traditional high-pressure lines facing displacement by vacuum-capable cells for structural EV applications.
- High Pressure Die Casting:Conventional HPDC lines dominate engine block and transmission housing production with cycle times below 90 seconds, though porosity limitations restrict structural qualification.
- Vacuum Die Casting:Evacuated cavity systems enable heat-treated structural castings for EV battery trays and motor enclosures, commanding 40-60% capital cost premiums over standard cells.
- Low Pressure Die Casting:Wheel rim and chassis component specialists favor LPDC for superior surface finish and mechanical properties.
- Gravity Die Casting:Low-volume prototyping and aftermarket wheel production utilize permanent mold gravity pouring.
High pressure die casting retains installed base dominance; vacuum die casting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province anchors South African automotive die casting capacity, with Rosslyn and Silverton assembly corridors driving demand for powertrain housings and structural components. Eastern Cape manufacturing zones around Gqeberha are pivoting toward EV thermal management as Volkswagen scales battery-electric assembly. Provincial industrial policy divergence is reshaping supplier location decisions across the value chain.
Gauteng Province
Ford Silverton and Toyota Prospecton plants sustain high-volume transmission housing demand through APDP-linked local content mandates. The Department of Trade and Industry administers production rebates that deepen domestic sourcing thresholds for Tier-1 suppliers. Die casters cluster in Rosslyn Industrial Park, where Rheinmetall Automotive and Martinrea Honsel operate high-pressure lines serving internal combustion programs.
Eastern Cape
Volkswagen Group's ID.4 assembly commitment at Kariega is generating first-mover demand for battery tray and motor enclosure castings. Provincial development agencies coordinate with the national automotive production incentive framework to attract vacuum die casting investment. Suppliers concentrate in Coega Industrial Development Zone, where port access supports export-oriented component qualification for European OEMs.
KwaZulu-Natal
Toyota's Prospecton expansion sustains engine block demand while suppliers evaluate thermal component diversification for hybrid platforms. The provincial economic development department aligns infrastructure investment with national automotive master plan targets. Durban automotive supplier parks host gravity and low-pressure specialists serving aftermarket wheel rim channels.
Western Cape
Mercedes-Benz East London operations drive precision structural casting requirements for premium passenger vehicle architectures. The provincial government competes for APDP-linked investment through specialized tooling skills programs at Cape Peninsula University of Technology. Atlantis Industrial Park attracts smaller vacuum die casting operations targeting aerospace crossover qualifications.
Mpumalanga
Hillside Aluminium smelter at Richards Bay supplies primary A380 and AlSi10Mg alloy feedstock to downstream die casters across all provinces. The national Department of Mineral Resources and Energy oversees energy security frameworks affecting smelter operations. Supplier logistics corridors connect Richards Bay port facilities to Gauteng and Eastern Cape manufacturing zones via N3 highway freight networks.
South Africa Automotive Parts Aluminium Die Casting Market Competitive Landscape
Technology licensing dominates the current landscape as European engineering heritage transfers to local operations through joint ventures and knowledge partnerships. The supplier base concentrates around three to five integrated Tier-1 systems houses with captive foundry relationships, while mid-scale independents compete on aftermarket and niche OE fitments. Two strategic archetypes prevail: European-heritage technology licensors with vacuum die casting capabilities, and scale-focused high-pressure operators serving legacy powertrain programs. Competitive moves center on dual-process capacity expansion and IATF 16949 certification acceleration to qualify for EV platform awards.
Among European-heritage operators, Rheinmetall Automotive and Georg Fischer exemplify technology-transfer positioning, leveraging German engineering standards to anchor structural component qualifications for premium OEM programs. Martinrea Honsel occupies a specialized tier focused on porosity-sensitive transmission applications. These three entities represent the dominant competitive anchors within Gauteng and Eastern Cape supply corridors, with their positioning reflecting divergent bets between internal combustion sustainment and electrification pivot strategies.
| Leading Market Players |
|---|
| Steel Best Automotive |
| Lupton and Place |
| Kemlows Diecasting Products Ltd |
| Rheinmetall Automotive |
| Martinrea Honsel |
| Ryobi Die Casting |
| Georg Fischer |
| Buhler Group |
| Renuka Auto Components |
| Others |
Value Network & Pricing Analysis
OEM consolidation of supplier panels under single-source accountability is forcing die casters to absorb tooling amortization costs while competing on total program lifecycle pricing. This procurement compression cascades through raw material hedging strategies and alloy sourcing decisions across Gauteng and Eastern Cape manufacturing corridors.
Pricing Analysis
Input-cost pass-through from LME aluminium volatility and Rand/dollar exchange rate swings governs contract structures. Three-tier pricing structure across premium vacuum-certified, standard high-pressure, and economy gravity-cast levels reflects IATF 16949 certification status and porosity control capabilities. Pricing pressure stems from dual-process capex burdens as suppliers maintain ICE lines while commissioning EV-capable cells. Aftermarket distributors exhibit highest price sensitivity; premium OEM programs tolerate cost premiums for vacuum die casting quality.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale transmission housing demand from Ford Silverton and Toyota Prospecton, while Tier-1 system integrators consolidate procurement for battery enclosure programs. Primary aluminium supply draws from Hillside Aluminium and Mozal smelters in Richards Bay, with A380 and AlSi10Mg alloy feedstock distribution running through N3 highway freight networks to Gauteng and Eastern Cape manufacturing zones. Single-source smelter concentration creates geographic vulnerability. Component logistics hinge on Durban and Coega port access for European OEM qualification exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's automotive die casting market functions as a regulatory compounder, with the Department of Trade and Industry's Automotive Production and Development Programme tightening local content thresholds that deepen domestic sourcing mandates and accelerate supplier consolidation.
For Market Incumbents: Acquire vacuum die casting technology licenses and real-time X-ray quality verification systems to defend structural EV component qualifications against European-heritage technology licensors. Consolidate captive foundry relationships with Eastern Cape vehicle assemblers before Volkswagen Group's ID.4 platform awards finalize supplier panels. Prioritize IATF 16949 certification acceleration to maintain qualification status amid audit backlogs. For New Entrants and Emerging Players: Independent aftermarket distributors serving wheel rim replacement channels represent the most penetrable buyer archetype, with relaxed certification requirements and fragmented procurement. Target Coega Industrial Development Zone for vacuum die casting investment to capture Volkswagen Kariega battery tray demand. Enter through recycled alloy certification pathways aligned with South African Bureau of Standards environmental claims standards. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale vacuum die casting specialists possessing Eastern Cape logistics access and European engineering partnerships. Long-term viability hinges on electrification pivot completion within the analysis window. Acquisition targets should demonstrate dual-process capability or secured EV platform qualifications. Monitor Volkswagen Group battery-electric production commitments as inflection indicator for heat sink and battery enclosure demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Capacity Expansion | Enables structural EV battery tray qualifications for Volkswagen Kariega assembly. |
| Recycled Alloy Certification Investment | Positions suppliers for South African Bureau of Standards environmental claims compliance. |
| IATF 16949 Certification Acceleration | Resolves audit backlog delays blocking new EV platform supplier qualifications. |
| Dual-Process Manufacturing Footprint | Balances high-pressure ICE lines with vacuum-capable EV cells without volume certainty. |
| Coega Industrial Development Zone Establishment | Secures port access for European OEM export qualification and Eastern Cape EV supply chain proximity. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and die casting operations directors grounded qualitative findings. Secondary validation drew from South African Bureau of Standards alloy specifications, Department of Trade and Industry APDP framework documentation, vehicle production databases, and customs trade records. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with national automotive production incentive targets.
Bottom-up modeling aggregated individual die casting cell capacity, product mix, and utilization rates across Gauteng and Eastern Cape manufacturing corridors. Top-down validation cross-checked against national aluminium consumption patterns and OEM local content compliance reporting. Segmentation dimensions spanned product type, propulsion architecture, technology platform, and regional production cluster. CAGRs derived from weighted average of historical production trajectories and electrification roadmap commitments across the analysis window. Forecast inputs incorporated Hillside Aluminium smelter output stability and Rand/dollar exchange rate sensitivity bands.
Underlying measurement precision varies by segment; vacuum die casting and EV thermal component categories carry tighter precision than legacy engine block volumes given certification transparency and platform award visibility. Forecasts reflect documented assumptions regarding Volkswagen Group electrification timelines and APDP incentive continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
North America Gear Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market