
 Automotive Die Casting Market | 2026-2036
Automotive Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Die Casting Market Analysis
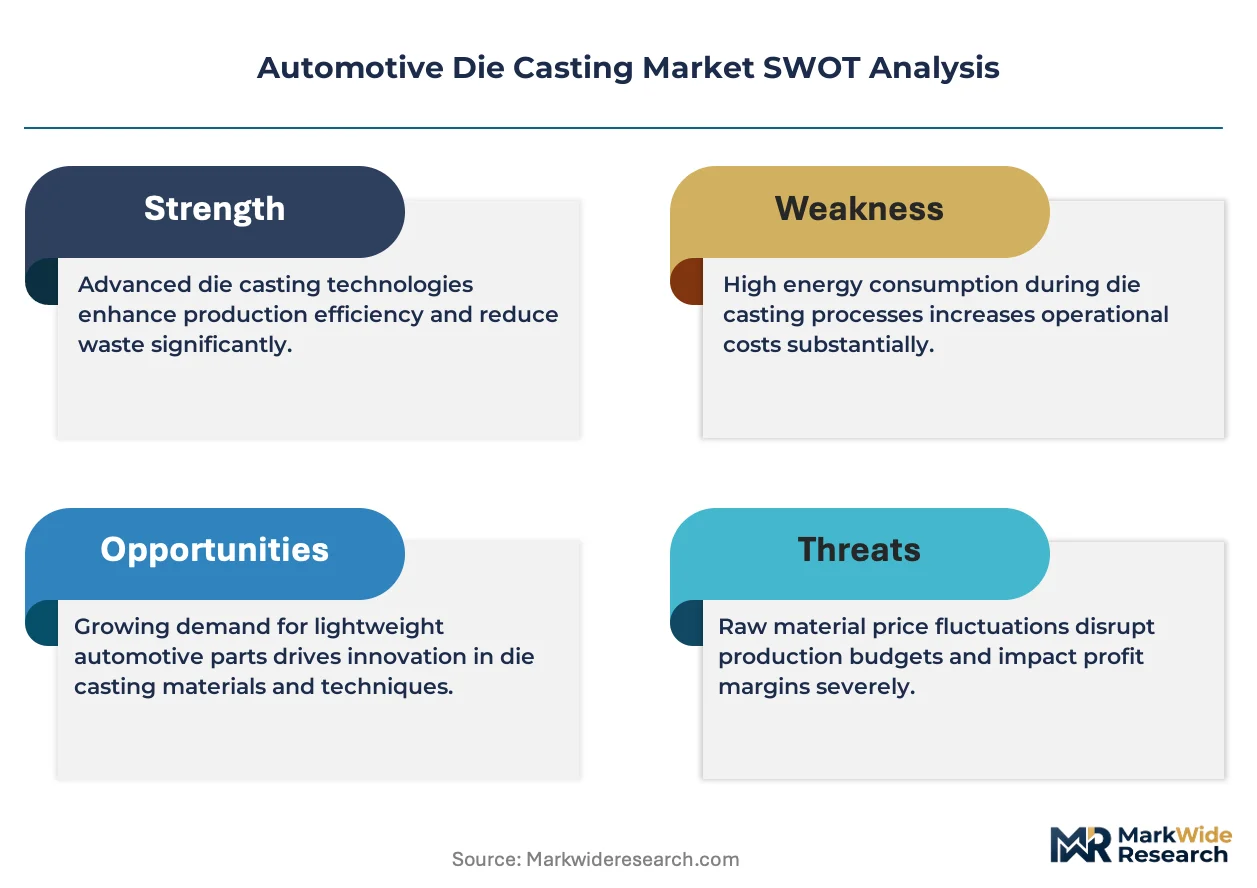
The EU's F-Gas Regulation is rebalancing the cost-of-entry calculus for European die casters by restricting fluorinated gas use in melt protection, compelling investments in alternative shielding technologies. Nemak leverages its integrated aluminum casting and machining footprint across Mexico and Europe to serve EV platform contracts. GF Casting Solutions anchors its competitive position through specialized high-pressure die casting expertise in structural battery housing components. Rheinmetall Automotive differentiates via its dominance in magnesium transmission cases for premium German OEMs.
Automotive die casting is a metal-forming process wherein molten non-ferrous alloys—typically aluminum with 7-12% silicon content for fluidity—are injected into hardened steel molds at pressures exceeding 1,000 bar to produce near-net-shape components with wall thicknesses down to 2 millimeters. Its primary industrial purpose is to manufacture lightweight, dimensionally precise powertrain and chassis parts that reduce vehicle mass while maintaining structural integrity under cyclic thermal and mechanical loads. Aluminum die casting occupies the largest value share given its strength-to-weight ratio and recyclability, while magnesium die casting represents the fastest-growing product category as OEMs pursue aggressive mass reduction targets for electric vehicle range extension. Structural parts, particularly battery enclosures and megacasting subframes, command the highest margin pools within the application spectrum as they require specialized vacuum-assisted high-pressure technology and downstream CNC finishing.
The EPA enforces Corporate Average Fuel Economy standards that directly dictate aluminum content targets in US vehicle platforms, while China's MIIT administers dual carbon goals that mandate lightweight material penetration in domestic new energy vehicle production. REACH compliance in Europe restricts certain alloying additives, reshaping supplier qualification protocols for casters exporting into the EU. Stakeholders must monitor how regional carbon border adjustments and evolving battery safety standards reshape alloy specification requirements and foundry location decisions.
Market Dynamics
The automotive die casting sector is undergoing fundamental restructuring as electric vehicle architectures displace traditional powertrain designs, forcing foundries to retool for structural battery housings and megacast subframes that demand vacuum-assisted high-pressure equipment and precision CNC finishing capabilities.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated gas use in aluminum melt protection are accelerating capital deployment into alternative shielding technologies across European foundries.
- Structural battery enclosures:OEM redesign of EV platforms is generating dedicated demand for high-pressure die cast battery trays with integrated thermal management channels.
- China MIIT dual carbon goals:Mandatory lightweight material penetration in domestic new energy vehicle production is pulling aluminum and magnesium casting capacity expansion.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting costs and LME price swings compress margin predictability for independent foundries without captive metal supply.
- Tooling lead times:Hardened steel mold fabrication cycles of 16-24 weeks constrain rapid scaling for new EV platform launches.
- REACH compliance friction:Restrictions on certain alloying additives in Europe are forcing reformulation of established alloy specifications and requalification of supplier protocols.
Strategic Opportunities
- Magnesium transmission cases:Premium German OEMs are expanding magnesium adoption for mass-critical powertrain components, creating specialty casting demand beyond aluminum dominance.
- Mexico nearshoring:North American OEMs are relocating die casting capacity to serve regional EV assembly hubs with reduced logistics exposure.
- Closed-loop recycling:In-house remelt of machining swarf and gate scrap is reducing virgin aluminum dependence and Scope 3 emissions reporting burdens.
Industry Challenges
- Vacuum-assisted HPDC technician scarcity:Specialized process engineering expertise for structural part production remains concentrated among a limited pool of experienced practitioners.
- Megacasting integration complexity:Single-piece subframe castings require downstream assembly line reconfiguration and welding process elimination that disrupts established body shop workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Die Casting Market |
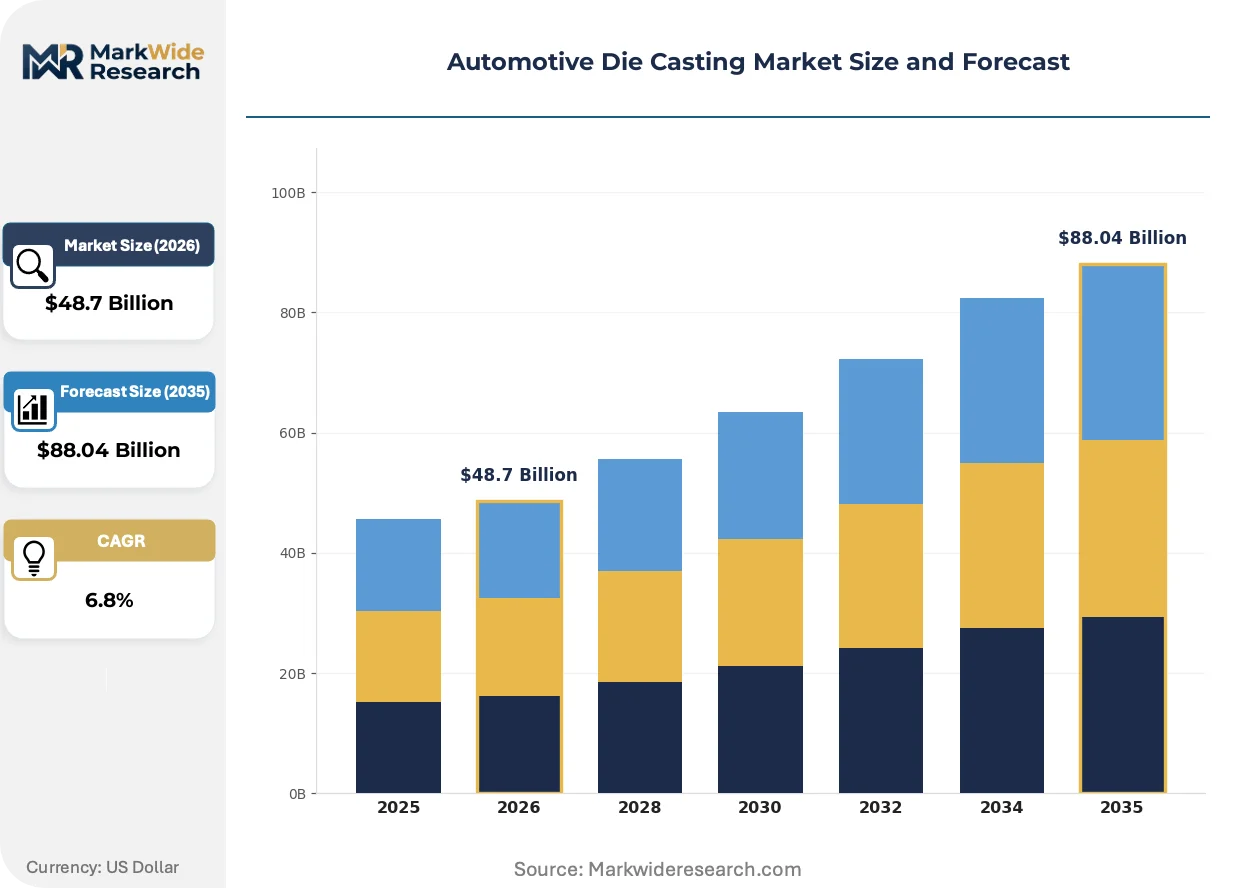
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Die Casting, Zinc Die Casting, Magnesium Die Casting, Copper Die Casting Application: Transmission Cases, Engine Blocks, Structural Parts, Brake Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Nemak, Ryobi Die Casting, GF Casting Solutions, Dynacast, Shiloh Industries, Rheinmetall Automotive, Linamar Corporation, Endurance Technologies, Martinrea Honsel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Die Casting Market Emerging Trajectories
Process innovation in automotive die casting is concentrating around three vectors: equipment scale-up for single-piece structural castings, regulatory-driven chemistry reformulation, and evolving procurement relationships between OEMs and tier suppliers.
Megacasting technology is absorbing the structural assembly functions previously performed by dozens of stamped and welded steel components. OEMs including Tesla and Volvo are adopting 6,000-9,000 ton clamping force machines to produce rear floor subframes in single aluminum shots. This consolidation is compressing supplier tiers and displacing traditional stamping and assembly operations from the value chain.
EPA Corporate Average Fuel Economy standards are tightening aluminum content mandates for US vehicle platforms, directly influencing powertrain and chassis design specifications. The regulation is forcing domestic OEMs to substitute cast aluminum for steel in engine blocks, transmission cases, and suspension knuckles. Powertrain applications remain the most affected segment, with foundries expanding machining capacity to meet downstream finishing requirements.
OEM sourcing departments are consolidating supplier panels and demanding dedicated cell capacity for structural EV components. Long-term take-or-pay agreements are displacing spot purchasing for battery enclosure programs. This concentration is most visible in Germany and China, where foundries are accepting capital contribution arrangements from vehicle manufacturers to secure platform exclusivity.
Automotive Die Casting Market Segmentation
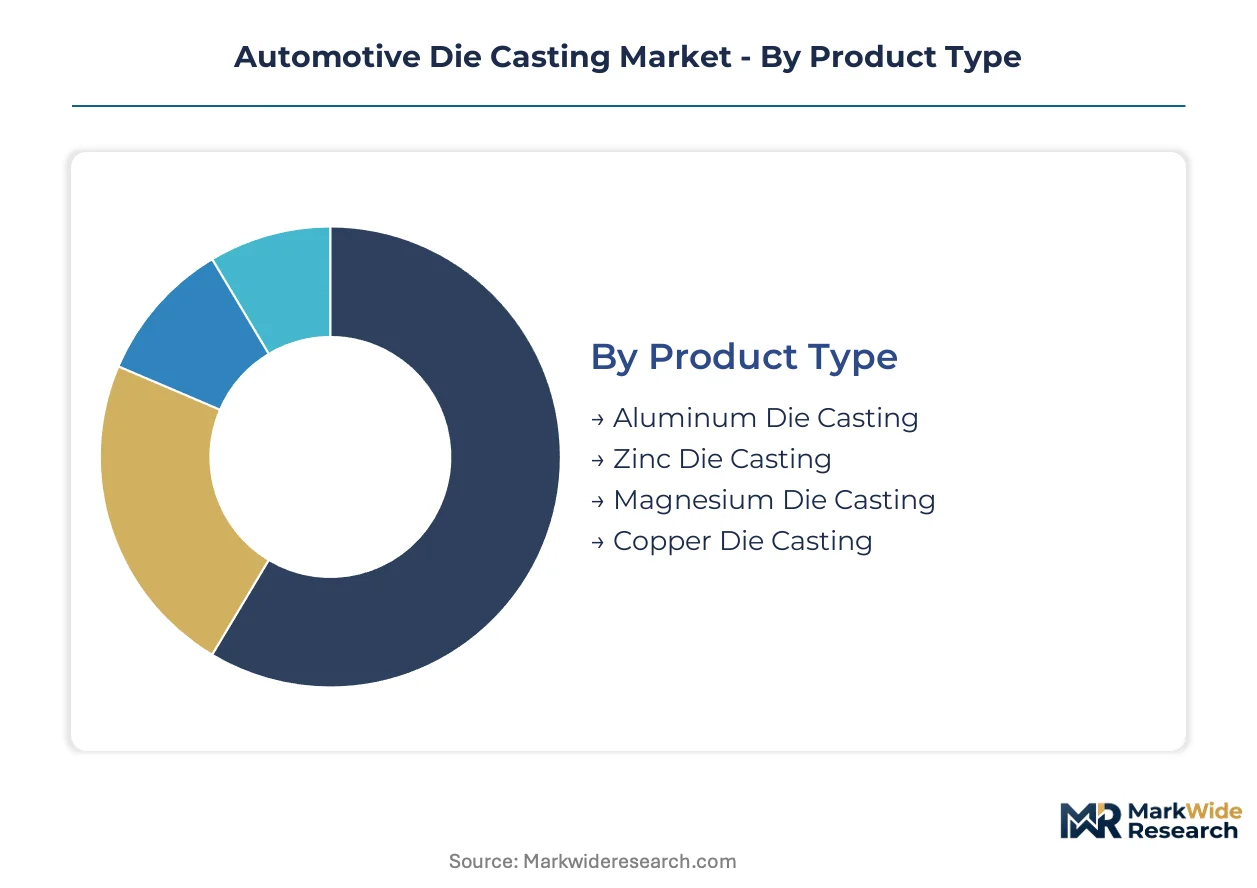
Automotive die casting segmentation reveals how material chemistry, application requirements, and process technology intersect to determine supplier capabilities and margin structures. Buyers select segments based on weight reduction targets, thermal performance needs, and downstream finishing complexity.
Product Type:
Material selection hinges on strength-to-weight ratio requirements and recyclability mandates across OEM platform specifications.
- Aluminum Die Casting:Alloys with 7-12% silicon content deliver optimal fluidity for thin-wall casting down to 2 millimeters. Demand concentrates in powertrain housings and structural battery enclosures where Tesla and Volvo specify aluminum megacast subframes to displace welded steel assemblies.
- Magnesium Die Casting:Premium German OEMs specify AZ91D and AM60B alloys for transmission cases and steering column brackets where mass reduction directly extends electric vehicle range. Rheinmetall Automotive dominates this segment through specialized hot-chamber process expertise.
- Zinc Die Casting:Zamak alloys serve interior trim mechanisms and small electrical housings where dimensional stability and surface finish quality outweigh weight considerations.
- Copper Die Casting:High-conductivity applications in electric motor housings and busbar connectors require oxygen-free copper casting with specialized thermal management properties.
Aluminum leads on scale; magnesium leads on momentum.
Application:
Component function determines whether castings require vacuum-assisted integrity or standard pressure specifications.
- Structural Parts:Battery enclosures and megacast subframes command specialized vacuum-assisted high-pressure equipment and downstream CNC finishing. GF Casting Solutions anchors capacity in Germany and China to serve dedicated EV platform contracts with integrated thermal management channels.
- Transmission Cases:Magnesium and aluminum housings for multi-speed electric vehicle gearboxes require pressure-tight integrity and complex internal core geometries. Nemak leverages integrated casting and machining footprints across Mexico and Europe for these programs.
- Engine Blocks:Cylinder block castings for hybrid powertrains maintain aluminum content despite declining ICE volumes in Europe and North America.
- Brake Components:Caliper housings and master cylinders specify high-strength aluminum alloys with corrosion-resistant surface treatments for safety-critical performance.
Structural parts capture margin concentration; transmission cases retain volume stability.
End User:
Procurement authority varies by vehicle program phase and component integration depth.
- OEMs:Direct sourcing of megacast structural components with long-term take-or-pay agreements displaces traditional tiered supply arrangements. OEMs in Germany and China contribute capital to secure dedicated cell capacity and platform exclusivity.
- Tier-1 Suppliers:System integrators aggregate die cast subcomponents into powertrain modules, managing qualification protocols and REACH compliance documentation for European vehicle programs.
- Vehicle Assemblers:Contract manufacturers in Mexico and Eastern Europe source regionally from nearshored foundry clusters to minimize logistics exposure for North American EV assembly hubs.
- Aftermarket Providers:Replacement transmission cases and brake components serve aging vehicle fleets with shorter lead time requirements and less stringent alloy traceability.
OEMs lead on contract value; Tier-1 suppliers lead on relationship density.
Technology:
Process selection determines achievable wall thickness, porosity levels, and capital intensity per production cell.
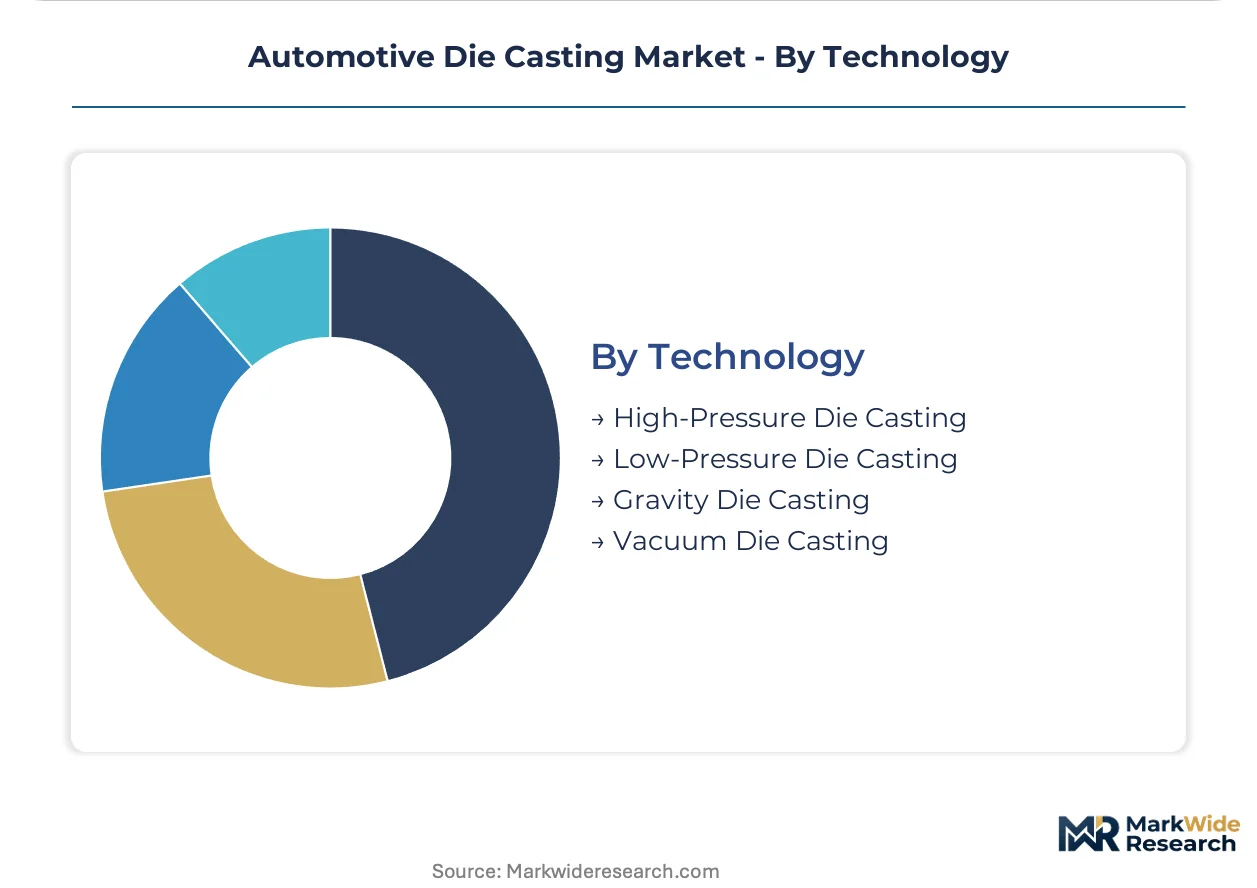
- High-Pressure Die Casting:Clamping forces of 6,000-9,000 tons enable single-shot rear floor subframes that eliminate dozens of stamped and welded components. Tesla and Volvo have adopted this technology for megacasting integration.
- Vacuum Die Casting:Evacuated die cavities prior to metal injection produce heat-treatable structural castings with porosity below 1% for safety-critical battery enclosures requiring weldability and leak-tight integrity.
- Low-Pressure Die Casting:Controlled metal rise velocity suits thick-walled engine blocks and transmission housings where directional solidification prevents shrinkage defects.
- Gravity Die Casting:Permanent mold processes serve lower-volume premium applications and prototype development with reduced tooling cost and faster mold fabrication cycles.
High-pressure dominates volume throughput; vacuum technology expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry engineering talent concentrates in Germany's precision metalworking belt, China's Yangtze industrial corridor, and Mexico's northern manufacturing clusters, anchoring regional supply networks for EV platform production.
China
MIIT dual carbon mandates are pulling aluminum casting capacity expansion for domestic new energy vehicle programs. The regulator enforces mandatory lightweight material penetration targets that reshape supplier qualification protocols. Foundry clusters in Shanghai, Suzhou, and Ningbo serve BYD and NIO assembly plants with vacuum-assisted high-pressure equipment for battery enclosure production.
Germany
Premium OEMs from BMW and Mercedes-Benz specify magnesium transmission cases and megacast aluminum subframes for electric architectures. The EU F-Gas Regulation restricts fluorinated gas use in melt protection, compelling foundry investments in alternative shielding technologies. Industrial concentration in Bavaria and Baden-Württemberg hosts specialized structural casting capacity for dedicated EV platform contracts.
United States
EPA Corporate Average Fuel Economy standards dictate aluminum content targets across powertrain and chassis applications. The regulation forces domestic OEMs to substitute cast aluminum for steel in engine blocks and suspension components. Foundry operations in Michigan, Ohio, and Kentucky supply Ford and GM assembly plants with high-pressure die cast transmission housings.
Mexico
North American OEMs are relocating die casting capacity to serve regional EV assembly hubs with reduced logistics exposure. Nuevo León and Baja California foundry clusters leverage proximity to Texas and California vehicle plants. The country's manufacturing workforce supports integrated casting and machining operations for battery tray programs.
Japan
METI industrial policy promotes lightweight material adoption in hybrid and electric powertrain designs. Domestic OEMs from Toyota and Honda specify aluminum engine blocks and transmission cases despite declining ICE volumes in export markets. Foundry concentration in Aichi and Shizuoka prefectures maintains precision high-pressure capacity for powertrain component supply.
Automotive Die Casting Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the automotive die casting sector. The vendor base separates into three strategic tiers: integrated aluminum-magnesium specialists with captive machining capacity, diversified metalformers serving multiple industrial end-uses, and regional foundry operators supplying domestic assembly hubs. Competitive positioning depends on vacuum-assisted high-pressure equipment access, long-term OEM platform contracts, and geographic proximity to EV production centers. Consolidation pressure is accelerating through dedicated cell capacity investments and take-or-pay agreement structures.
Among integrated specialists, Nemak and GF Casting Solutions exemplify the archetype of foundry-to-finishing operators securing multi-year EV platform exclusivity. Rheinmetall Automotive occupies a differentiated position within the magnesium transmission case segment serving premium German OEM specifications. These three companies represent distinct competitive vectors: aluminum structural casting dominance, integrated thermal management component supply, and magnesium alloy process specialization.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Die Casting |
| GF Casting Solutions |
| Dynacast |
| Shiloh Industries |
| Rheinmetall Automotive |
| Linamar Corporation |
| Endurance Technologies |
| Martinrea Honsel |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between vacuum-assisted high-pressure structural castings and standard pressure die castings manifests in divergent margin pools and supply chain configurations across the automotive die casting sector. Premium battery enclosure programs command dedicated cell capacity with long-term take-or-pay agreements, while commodity powertrain components trade on spot aluminum pricing with compressed logistics buffers.
Pricing Analysis
Bundled machining-finishing services versus unbundled raw casting supply splits the pricing architecture across OEM procurement desks. Three-tier pricing structure across premium structural, standard powertrain, and economy aftermarket levels reflects differentiation by vacuum integrity certification and thermal management integration. Cost compression in standard aluminum powertrain castings is intensifying because primary aluminum price volatility transfers directly to independent foundries without captive metal supply. Tier-1 system integrators exhibit highest price sensitivity due to fixed OEM contract pass-through mechanics, while OEM direct sourcing of megacast subframes shows lowest sensitivity given platform exclusivity premiums.
Supply Chain Analysis
Domestic-content mandates in China's MIIT dual carbon framework and US EPA localization incentives are reshaping sourcing patterns toward regional foundry clusters. Supply concentrates in Germany, China, and Mexico where hardened steel mold fabrication and precision machining capacity co-locate with vehicle assembly hubs. The supply chain draws from primary aluminum smelters, specialized magnesium alloy producers, and hardened tool steel fabricators. Single-source vulnerability in 6,000-9,000 ton clamping force equipment creates bottleneck risk for megacasting scale-up. Distribution runs through OEM direct procurement channels for structural programs and Tier-1 aggregator networks for powertrain components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive die casting market functions as a regulatory compounder where EU F-Gas restrictions and EPA Corporate Average Fuel Economy standards mechanically pull aluminum and magnesium content into vehicle platforms.
For Market Incumbents: Deepen captive machining integration to defend margin position against pure-play foundries lacking downstream finishing capacity. Add dedicated vacuum-assisted high-pressure cell capacity in Mexico to capture North American EV nearshoring demand. Secure long-term primary aluminum offtake agreements to insulate against LME price volatility compressing independent foundry profitability. For New Entrants and Emerging Players: Enter via magnesium transmission case specialization for premium German OEMs where Rheinmetall Automotive's dominance leaves niche white space for qualified secondary suppliers. Target aftermarket brake component replacement demand with shorter qualification cycles and less stringent alloy traceability requirements. Pursue joint development agreements with battery enclosure startups lacking in-house casting expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where vacuum-assisted HPDC technician scarcity concentrates specialized process knowledge among limited practitioner pools. Five-to-ten year viability favors integrated casting-machining operators with secured OEM platform exclusivity over commodity powertrain suppliers exposed to ICE volume decline. Watch for inflection in OEM capital contribution arrangements for dedicated cell capacity as signal of supplier panel consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Assisted HPDC Capacity Expansion | Enables heat-treatable structural castings for Tesla and Volvo megacasting programs. |
| Backward Integration into Primary Aluminum | Reduces Scope 3 emissions reporting burdens and virgin metal cost exposure. |
| Magnesium Alloy Process Specialization | Captures premium German OEM transmission case demand beyond aluminum dominance. |
| Mexico Manufacturing Footprint Establishment | Serves North American EV assembly hubs with reduced logistics exposure. |
| Closed-Loop Scrap Remelt Systems | Lowers virgin aluminum dependence and supports EU carbon border adjustment compliance. |
Methodological Framework
Bottom-up vehicle platform modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, foundry operations managers, and aftermarket distributors combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed suppliers, and EU ECHA regulatory filings. Triangulation between demand-side content-per-vehicle assumptions and supply-side installed clamping force capacity ensures cross-verified output integrity.
Historical trendline analysis of aluminum intensity per vehicle class established baseline penetration rates across powertrain and structural applications. Segmentation dimensions modeled include propulsion architecture, component function, material chemistry, process technology, and regional production cluster. CAGRs derive from slope analysis of content growth curves applied across the projection horizon. Forecast inputs incorporate MIIT dual carbon mandate enforcement timelines and EPA rulemaking trajectory for fuel economy standards.
Inputs from OEM platform engineering disclosures and foundry equipment order backlogs were available through the study window; gaps in proprietary alloy formulation data introduce uncertainty bands around magnesium adoption speed assumptions. Forecasts reflect documented assumptions regarding EV platform launch timing and regulatory enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Constant Velocity Joint Market