
 Automotive Parts Zinc Die Casting Market | 2026-2036
Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Parts Zinc Die Casting Market Analysis
The gap between premium precision casting and commodity-grade zinc die casting is repositioning supplier relationships across the automotive value chain. Eastern Alloys Inc. leverages its specialized alloy formulations to dominate high-performance transmission case applications for North American OEMs. DyCast Specialties Corporation anchors its competitive stance through deep vertical integration in the Great Lakes industrial corridor, controlling raw material sourcing through finished component delivery. Zetwerk competes aggressively on digital manufacturing platforms, connecting fragmented Indian and Southeast Asian foundries to consolidated European buyer networks.
Automotive parts zinc die casting involves injecting molten zinc alloys—typically Zamak compositions with aluminum, magnesium, and copper additions—into hardened steel molds at pressures exceeding 10,000 psi to produce net-shape components with dimensional tolerances of ±0.001 inches. This process delivers corrosion-resistant, electrically conductive parts suited to under-hood thermal environments and electromagnetic shielding applications. Transmission cases and pump housings represent mature, high-volume segments where margin pools have compressed amid tooling amortization pressures. Electric vehicle applications within the industry vertical dimension represent the fastest-expanding demand node, as zinc's castability enables complex geometries for battery tray brackets and inverter housings that aluminum struggles to replicate at equivalent cost points.
The US EPA and NHTSA coordinate fuel economy and emissions standards that directly incentivize lightweight zinc substitution for heavier ferrous castings in structural components. China's MIIT administers dual carbon goals and GB standards for automotive material recycling that shape alloy composition requirements and closed-loop foundry mandates. REACH and RoHS frameworks in Europe restrict cadmium and lead content in zinc alloys, forcing reformulation investments across export-oriented suppliers. Stakeholders must monitor evolving battery platform architectures and regional carbon border adjustment mechanisms to align capacity investments with the next generation of electrified vehicle chassis designs.
Market Dynamics
China's MIIT fuel consumption standards and the EU's F-Gas Regulation are compressing allowable casting weights and thermal management footprints, forcing zinc die casters to redesign legacy component geometries for battery-electric powertrains.
Growth Catalysts
- EV battery enclosure lightweighting:Zinc's castability enables complex tray bracket geometries that aluminum cannot replicate at equivalent tooling cost, accelerating adoption by electric vehicle manufacturers.
- REACH and RoHS compliance:European alloy reformulation mandates are filtering non-compliant suppliers from export channels, consolidating procurement toward certified foundries.
- Pearl River Delta concentration:Integrated die casting ecosystems in China's Guangdong province serve both domestic EV brands and Tier 1 export suppliers with compressed lead times.
Market Restraints
- Zamak alloy input volatility:Aluminum and copper price swings in London Metal Exchange contracts compress margin predictability for high-volume transmission case producers.
- Tooling amortization pressure:Hardened steel mold investments exceeding $500,000 per cavity configuration lock smaller foundries out of precision transmission applications.
- Aluminum substitution in structural castings:High-pressure aluminum die casting advances in Germany and Japan threaten zinc's position in non-thermal automotive housings.
Strategic Opportunities
- Indian domestic EV supply chain:Underdeveloped zinc die casting infrastructure for two-wheeler and three-wheeler electrification creates first-mover positioning for integrated manufacturers.
- US Inflation Reduction Act domestic content:Battery component assembly incentives favor North American zinc casting capacity for thermal management modules serving Detroit-area OEMs.
- Digital manufacturing platforms:Cloud-based foundry-to-buyer matching systems connect fragmented Southeast Asian suppliers to consolidated European procurement networks.
Industry Challenges
- GD&T and simulation expertise scarcity:Shortages of engineers proficient in Magma or ProCAST thermal flow modeling delay new product qualification cycles.
- Multi-material joining certification:Zinc-to-aluminum laser welding and adhesive bonding protocols lack unified SAE or ISO standards, complicating mixed-material chassis integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Parts Zinc Die Casting Market |
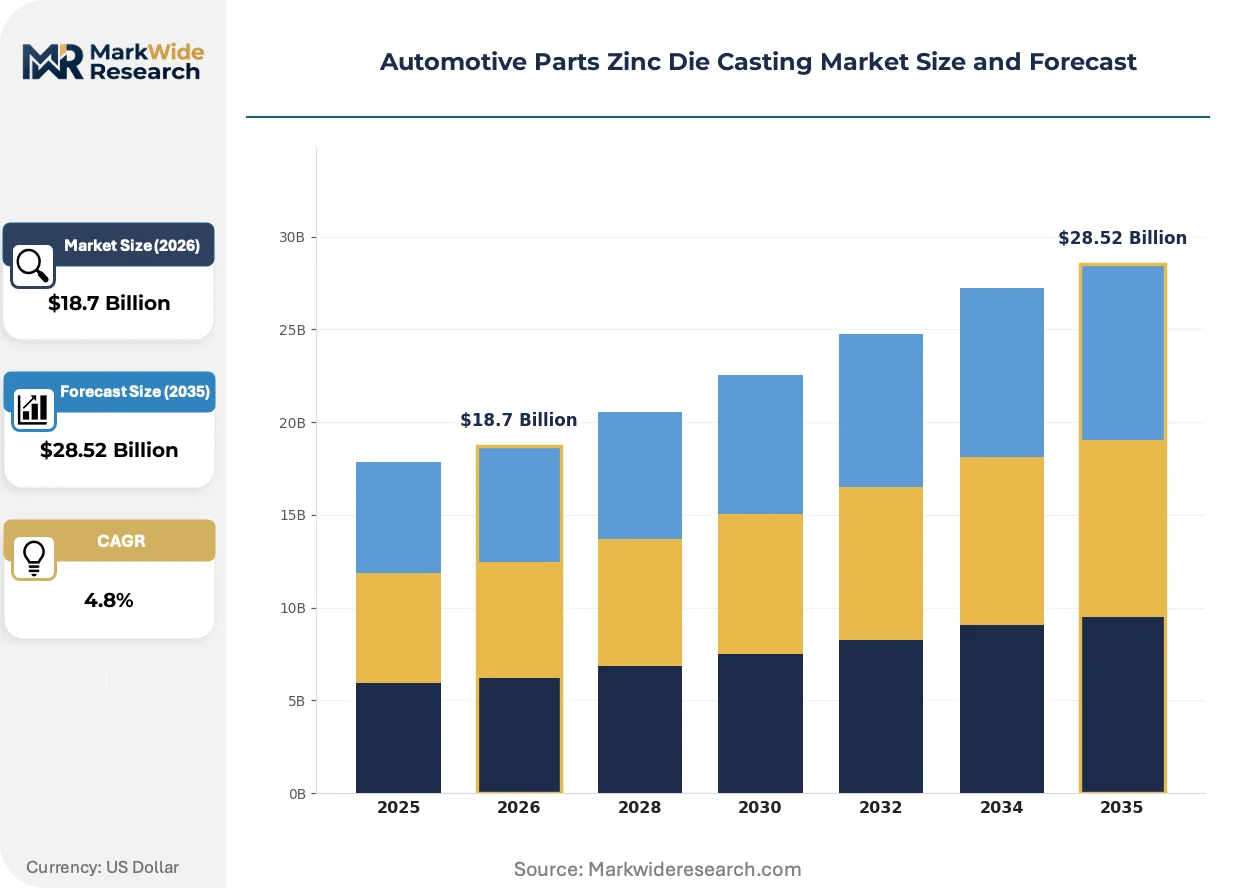
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Cases, Engine Blocks, Oil Pans, Pump Housings Industry Vertical: Passenger Vehicles, Commercial Vehicles, Motorcycles, Electric Vehicles Manufacturing Stage: Primary, Secondary, Tertiary, Aftermarket Application: Structural Components, Decorative Parts, Performance Parts, Safety Components |
| Companies Covered | Eastern Alloys Inc., DyCast Specialties Corporation, Dongguan Sincere Tech Co., Ltd, Northwest Die Casting, SDC Incorporated, GC Precision Mold Co., Ltd., Zetwerk, Lakeside Casting Solutions, LLC, CNM Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Parts Zinc Die Casting Market Emerging Trajectories
Process digitization, regulatory chemistry restrictions, and procurement platform consolidation are restructuring how zinc die cast components move from foundry floor to vehicle assembly.
Thin-wall zinc die casting with wall thickness below 0.8 millimeters is overtaking conventional aluminum extrusion for inverter housing applications. EV power electronics suppliers in South Korea and Germany are qualifying these geometries for 800-volt architectures. The shift is compressing part counts and assembly labor in thermal management modules.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in die casting cooling systems, forcing foundries to retrofit closed-loop water chillers or adopt CO2-based alternatives. The compliance burden falls heaviest on mid-volume producers serving HVAC-integrated battery thermal systems. German and Czech suppliers are consolidating to share retrofit capital costs.
Consolidated procurement through OEM-direct foundry contracts is displacing traditional distributor networks for precision transmission cases. Tier 1 suppliers in Michigan and Ontario are negotiating multi-year zinc casting agreements with locked alloy pricing. The model is most advanced in North American heavy-duty truck transmission programs.
Automotive Parts Zinc Die Casting Market Segmentation
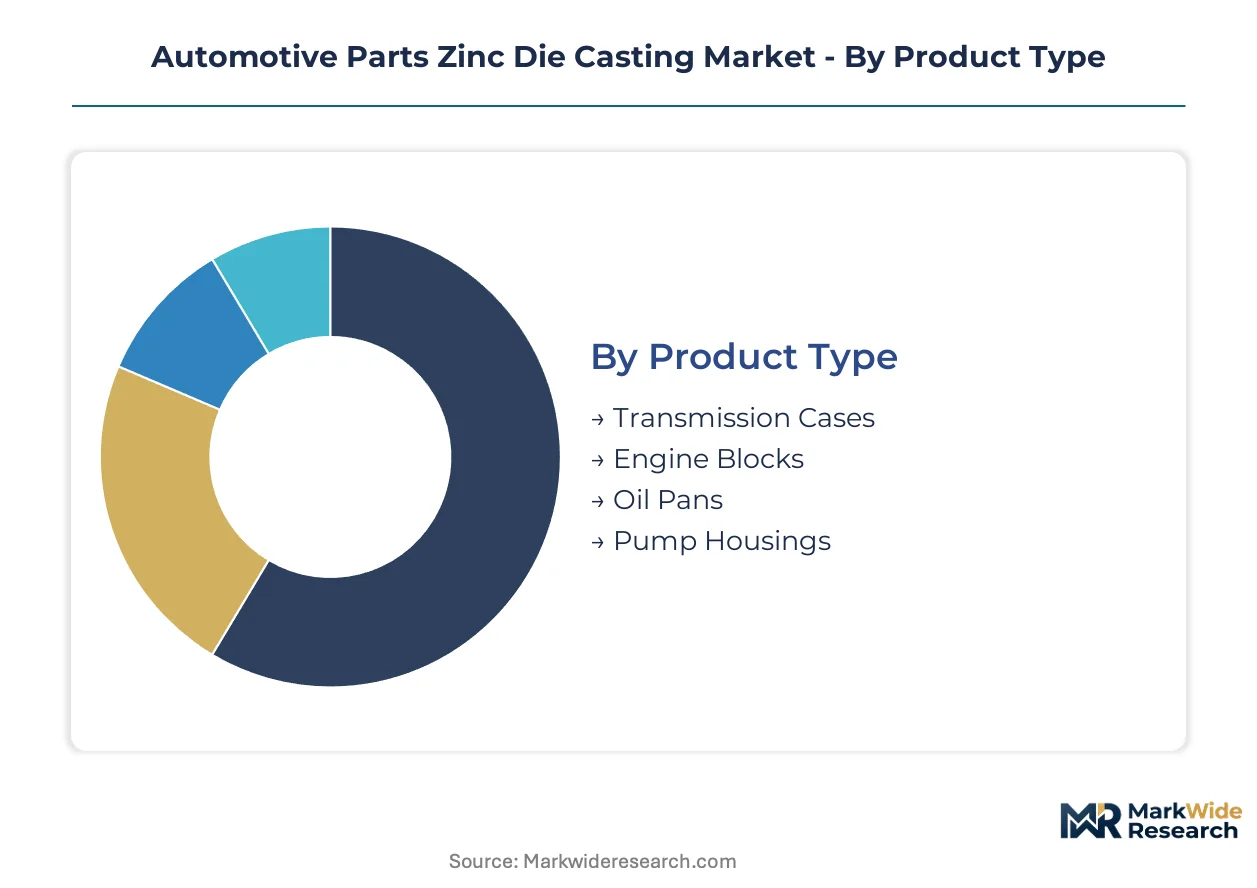
Zinc die casting serves heterogeneous automotive applications where alloy specifications, dimensional tolerances, and thermal performance requirements vary sharply across powertrain architectures. Segmentation reveals how foundries allocate capacity between mature internal combustion programs and emerging electric vehicle platforms.
Product Type:
Volume production concentrates in transmission and fluid management components where tooling amortization spreads across decades of platform continuity, while premium margins attach to structural castings requiring tighter GD&T compliance.
- Transmission Cases:Zamak 5 alloy dominates these high-pressure castings with 4% copper content for tensile strength above 55,000 psi. Demand clusters in Michigan and Ontario heavy-duty truck assembly corridors where Detroit-area OEMs specify legacy automatic transmission architectures. Tooling investments exceeding $500,000 per cavity configuration lock out smaller competitors.
- Engine Blocks:Thin-wall zinc formulations with 0.8-millimeter wall thickness enable net-shape casting of small-displacement engine components for Asian motorcycle manufacturers. Thailand and Vietnam assembly plants source these from Pearl River Delta foundries with compressed lead times.
- Oil Pans:Corrosion-resistant Zamak 3 compositions serve under-hood thermal cycling requirements for European passenger car producers.
- Pump Housings:Complex internal geometries for water and fuel pumps leverage zinc's castability versus aluminum alternatives.
Mature deployment sits with Transmission Cases. Newer deployment is concentrated in Engine Blocks.
Industry Vertical:
Passenger vehicle applications anchor current revenue, but electrification timelines are redistributing foundry qualification efforts toward battery-integrated platforms with distinct thermal management specifications.
- Passenger Vehicles:Conventional zinc die casting for HVAC control modules and interior trim brackets maintains volume through German and Japanese OEM supply chains. REACH-compliant alloy reformulations filter non-certified suppliers from export channels.
- Electric Vehicles:Battery tray brackets and inverter housings demand thin-wall geometries below 0.8 millimeters that aluminum struggles to replicate at equivalent tooling cost. South Korean 800-volt architecture suppliers are accelerating qualification timelines.
- Commercial Vehicles:Heavy-duty transmission cases for North American truck fleets specify Zamak 5 for durability under sustained torque loads.
- Motorcycles:Two-wheeler electrification in India creates underdeveloped zinc casting infrastructure for battery enclosure components.
Established revenue concentrates in Passenger Vehicles. Steepest expansion trajectory attaches to Electric Vehicles.
Manufacturing Stage:
Primary production captures alloy margin while aftermarket segments compete on inventory velocity and reverse logistics capabilities across fragmented distributor networks.
- Primary:Raw Zamak alloy production and initial casting operations concentrate in China's Guangdong province where integrated die casting ecosystems serve domestic EV brands and Tier 1 export suppliers.
- Secondary:Machining, surface finishing, and coating operations add dimensional precision for transmission case applications requiring ±0.001 inch tolerances.
- Tertiary:Sub-assembly and module integration for thermal management systems occurs at Tier 1 suppliers in Michigan and Ontario.
- Aftermarket:Replacement transmission cases and pump housings move through traditional distributor networks being displaced by OEM-direct foundry contracts.
Capital intensity peaks in Primary. Margin compression is most severe in Aftermarket.
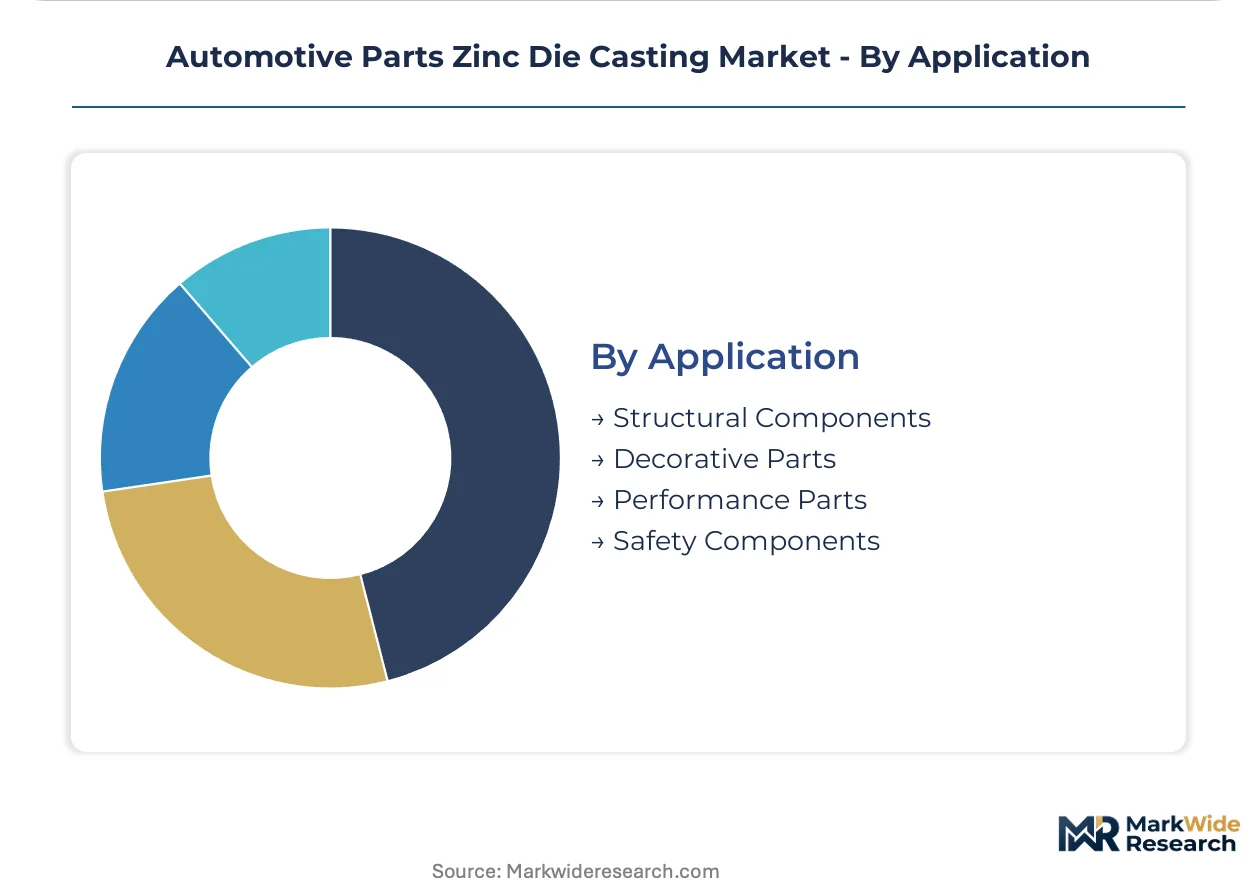
Application:
Functional requirements separate structural load-bearing castings from cosmetic components where surface finish and plating compatibility determine supplier selection.
- Structural Components:Load-bearing battery tray brackets for electric vehicles require finite element analysis validation under crash loading scenarios specified by NHTSA and MIIT protocols.
- Safety Components:Pedestrian impact-compliant bumper beams and door reinforcements specify zinc's energy absorption characteristics versus steel alternatives.
- Performance Parts:High-strength Zamak formulations serve turbocharger housings and exhaust system brackets in European performance vehicle segments.
- Decorative Parts:Interior trim and emblem bases prioritize surface finish quality and chrome plating adhesion for premium passenger vehicle lines.
Regulatory certification burden concentrates in Structural Components. Fastest design refresh cycles attach to Decorative Parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta manufacturing cluster anchors global zinc die casting capacity, with Guangdong province foundries serving both domestic electric vehicle brands and export-oriented Tier 1 suppliers through integrated production ecosystems.
China
MIIT fuel consumption standards and dual carbon goals are compressing allowable casting weights for battery-electric powertrains, forcing redesigns of legacy transmission geometries. GB standards for automotive material recycling mandate closed-loop foundry operations across Guangdong and Jiangsu provinces. Shenzhen and Dongguan facilities dominate thin-wall inverter housing production for South Korean 800-volt architecture suppliers.
United States
EPA and NHTSA coordinated standards incentivize lightweight zinc substitution for ferrous castings in structural components serving Detroit-area OEMs. The Inflation Reduction Act's domestic content requirements favor North American casting capacity for battery thermal management modules. Michigan and Ontario heavy-duty truck assembly corridors concentrate Zamak 5 transmission case demand.
Germany
REACH and RoHS frameworks restrict cadmium and lead content in zinc alloys, filtering non-compliant suppliers from export channels and consolidating procurement toward certified foundries. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in die casting cooling systems, forcing retrofit investments. Bavarian and Czech suppliers share capital costs for closed-loop water chiller adoption.
India
Underdeveloped zinc die casting infrastructure for two-wheeler and three-wheeler electrification creates first-mover positioning opportunities for integrated manufacturers. PLI scheme incentives for advanced automotive components attract capacity investments into domestic EV supply chains. Maharashtra and Tamil Nadu industrial corridors lack qualified foundry capacity for battery enclosure lightweighting programs.
South Korea
800-volt battery architecture suppliers accelerate qualification timelines for thin-wall zinc geometries below 0.8 millimeters that aluminum cannot replicate at equivalent tooling cost. MFDS automotive material standards align with EU REACH compliance requirements for export-oriented production. Gyeonggi-do and Busan-Ulsan manufacturing zones specialize in precision thermal management module sub-assemblies.
Automotive Parts Zinc Die Casting Market Vendor Landscape
Premium-margin players sit above commodity-margin players across alloy formulation specialization and tooling investment thresholds. The vendor base stratifies between vertically integrated alloy producers, precision transmission case specialists, and digital platform intermediaries connecting fragmented foundries to consolidated buyer networks. Three archetypes dominate: proprietary alloy formulators controlling high-performance applications, regionally anchored integrated manufacturers, and cloud-based procurement platforms. Competitive moves concentrate on multi-year OEM-direct contract negotiation and shared retrofit capital pooling for F-Gas compliance.
Within the alloy formulation tier, Eastern Alloys Inc. exemplifies specialized Zamak composition expertise for North American transmission applications. DyCast Specialties Corporation occupies a position among Great Lakes corridor integrated manufacturers with captive raw material through finished component control. Zetwerk represents the digital platform archetype, connecting Indian and Southeast Asian foundries to European procurement networks through cloud-based matching systems.
| Leading Market Players |
|---|
| Eastern Alloys Inc. |
| DyCast Specialties Corporation |
| Dongguan Sincere Tech Co., Ltd |
| Northwest Die Casting |
| SDC Incorporated |
| GC Precision Mold Co., Ltd. |
| Zetwerk |
| Lakeside Casting Solutions, LLC |
| CNM Tech |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance mandates are gating both qualified foundry supply and premium-tier pricing access for thermal management module producers, as retrofit capital requirements for closed-loop cooling systems filter mid-volume competitors from certified procurement channels.
Pricing Analysis
Tooling throughput guarantees anchor value-based pricing for precision transmission case contracts, with Zamak 5 alloy formulations commanding premiums over commodity Zamak 3 grades based on MIIT carbon intensity certifications and locked multi-year offtake volumes. Cost compression in high-volume pump housing segments is intensifying because aluminum substitution threats from German and Japanese suppliers erode zinc's cost advantage in non-thermal applications. Tier 1 procurement teams in Michigan exhibit highest price sensitivity for legacy internal combustion components, while South Korean 800-volt architecture suppliers show lowest sensitivity for thin-wall inverter housing qualifications.
Supply Chain Analysis
Closed-loop alloy recycling flows and remanufactured die cavity refurbishment are tightening material circularity across Guangdong province foundries serving Pearl River Delta EV assembly clusters. Raw material sourcing draws from Australian zinc concentrate, Chilean copper cathode, and domestic Chinese aluminum ingot flows. Single-source vulnerability concentrates in specialized Zamak alloy formulation IP held by North American proprietary suppliers. Distribution runs through OEM-direct foundry contracts displacing traditional aftermarket distributor networks for precision transmission applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive parts zinc die casting market sits in a technology-transition phase where thin-wall geometries below 0.8 millimeters are displacing conventional aluminum extrusion for battery-integrated thermal management modules.
For Market Incumbents: Extend proprietary alloy formulation advantages into South Korean 800-volt qualification pipelines before aluminum high-pressure casting advances close the geometry gap. Consolidate backward integration into Australian zinc concentrate offtake to buffer London Metal Exchange volatility threatening transmission case margins. Prioritize F-Gas retrofit capital pooling with Bavarian and Czech suppliers to share compliance burden for HVAC-integrated battery thermal systems. For New Entrants and Emerging Players: Digital manufacturing platforms offer the most penetrable channel architecture for connecting fragmented Indian and Southeast Asian foundries to consolidated European procurement networks. Target Maharashtra and Tamil Nadu industrial corridors for two-wheeler electrification casting capacity before domestic PLI scheme incentives attract incumbent relocation. Qualify thin-wall inverter housing geometries for South Korean battery architecture suppliers as the fastest qualification pathway. For Investors and Strategic Acquirers: OEM-direct contract announcements for multi-year transmission case agreements with locked alloy pricing are the leading indicator that margin stability is returning to heavy-duty truck casting segments. Five-to-ten year viability favors vertically integrated Great Lakes corridor manufacturers with captive raw material through finished component control. Monitor GB standard updates for automotive material recycling mandates as the signal for closed-loop foundry valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Alloy Formulation Patent Expansion | Proprietary Zamak 5 compositions lock out competitors from Michigan heavy-duty transmission contracts. |
| F-Gas Compliance Retrofit Partnership | Shared capital pooling reduces burden for mid-volume German and Czech thermal management suppliers. |
| Digital Platform Integration | Cloud-based foundry-to-buyer matching consolidates fragmented Southeast Asian supplier access. |
| Thin-Wall Qualification Acceleration | South Korean 800-volt architecture approvals open premium inverter housing margin pools. |
| Closed-Loop Recycling Infrastructure | GB standard-compliant material circularity secures domestic Chinese EV brand procurement preference. |
Methodological Framework
Trade databases, SEC filings, and MIIT regulatory submissions formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution heads. Bottom-up capacity assessments across Guangdong, Michigan, and Bavarian production clusters were triangulated against top-down vehicle production forecasts from registration databases.
Historical trendline analysis of alloy input costs, tooling amortization schedules, and platform qualification cycles established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from weighted capacity expansion announcements and OEM sourcing commitment timelines, with specific inputs from thermal management module design refresh frequencies and REACH compliance cost pass-through assumptions.
Several conditions sit outside the modeled scope, including unannounced aluminum alloy breakthroughs in high-pressure die casting and potential suspension of EU carbon border adjustment mechanisms. Forecasts reflect assumptions about sustained EV penetration rates and stable alloy chemistry regulatory frameworks. Practitioners should monitor South Korean 800-volt architecture supplier qualification announcements and MIIT dual carbon goal enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Automotive Oil and Air Filters Market