
 Operational Digital Oilfield Solution Market | 2026-2036
Operational Digital Oilfield Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Operational Digital Oilfield Solution Market Outlook
The capability gap between full-stack platform providers and point-solution vendors is reorganizing competitive tiers in the operational digital oilfield solution landscape. Schlumberger Limited leverages its subsurface-to-surface integration to anchor premium positioning across integrated production contracts. Halliburton Company competes through specialized drilling optimization modules that extend its historical wireline dominance into digital workflows. Baker Hughes Company differentiates via its turbomachinery data layers, sustaining aftermarket attachment rates through predictive analytics.
Operational digital oilfield solutions encompass sensor networks, edge computing nodes, and cloud-native analytics platforms that process real-time wellbore telemetry at latency thresholds below 50 milliseconds for closed-loop production control. These systems integrate SCADA historians with machine learning models to automate choke adjustments and artificial lift optimization across dispersed assets. IoT Solutions and Big Data Analytics command the largest current revenue pools, though Cloud Computing segments exhibit the steepest growth trajectory as operators migrate off on-premise infrastructure. Production Optimization applications generate the highest margin concentration due to their direct linkage to barrel economics and operator willingness to pay for proven uplift.
The US Bureau of Safety and Environmental Enforcement mandates real-time monitoring for offshore blowout preventer systems, while API RP 1164 cybersecurity standards shape onshore pipeline control network procurement. Norway's Petroleum Safety Authority and Brazil's ANP impose analogous data-integrity requirements that elevate vendor qualification barriers. Stakeholders must weigh capital deployment between proprietary platform builds and vendor-agnostic interoperability architectures as regulatory fragmentation intensifies.
Market Dynamics
Edge computing architectures are compressing latency thresholds for closed-loop production control, forcing vendors to requalify around sub-50-millisecond telemetry processing rather than batch-analytics compatibility.
Growth Catalysts
- API RP 1164:Pipeline operators in the United States face mandatory cybersecurity hardening for SCADA control networks, expanding procurement scope for encrypted edge nodes.
- Real-time blowout preventer mandates:The US Bureau of Safety and Environmental Enforcement requires continuous offshore monitoring, locking in sensor deployment cycles for Gulf of Mexico assets.
- Permian Basin density:Pad drilling concentration in West Texas and New Mexico creates network-effect economies for shared digital infrastructure across adjacent leases.
Market Restraints
- Silicon carbide supply choke:Power electronics for edge computing nodes depend on constrained substrate fabrication, with qualification timelines stretching 18-24 months.
- Norwegian content requirements:Petroleum Safety Authority local-presence rules elevate vendor establishment costs for North Sea deployments.
- Optical fiber fragility:Subsea cable cuts in offshore Brazil disrupt real-time data backhaul, forcing redundant radio-frequency backup systems.
Strategic Opportunities
- Pre-salt cluster digitization:Brazil's ANP production-sharing frameworks incentivize integrated digital twin adoption across Santos Basin megaprojects.
- Digital-native independents:Private-equity-backed Permian operators lack legacy SCADA debt, enabling greenfield platform selection without migration costs.
- AI-actuated choke control:Machine learning models trained on multi-asset production histories enable autonomous well management beyond rules-based automation.
Industry Challenges
- Petroleum data science scarcity:Reservoir engineering expertise decouples from software engineering fluency, inflating compensation for hybrid practitioners.
- OEM protocol fragmentation:Proprietary data formats from artificial lift manufacturers impede cross-vendor analytics aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operational Digital Oilfield Solution Market |
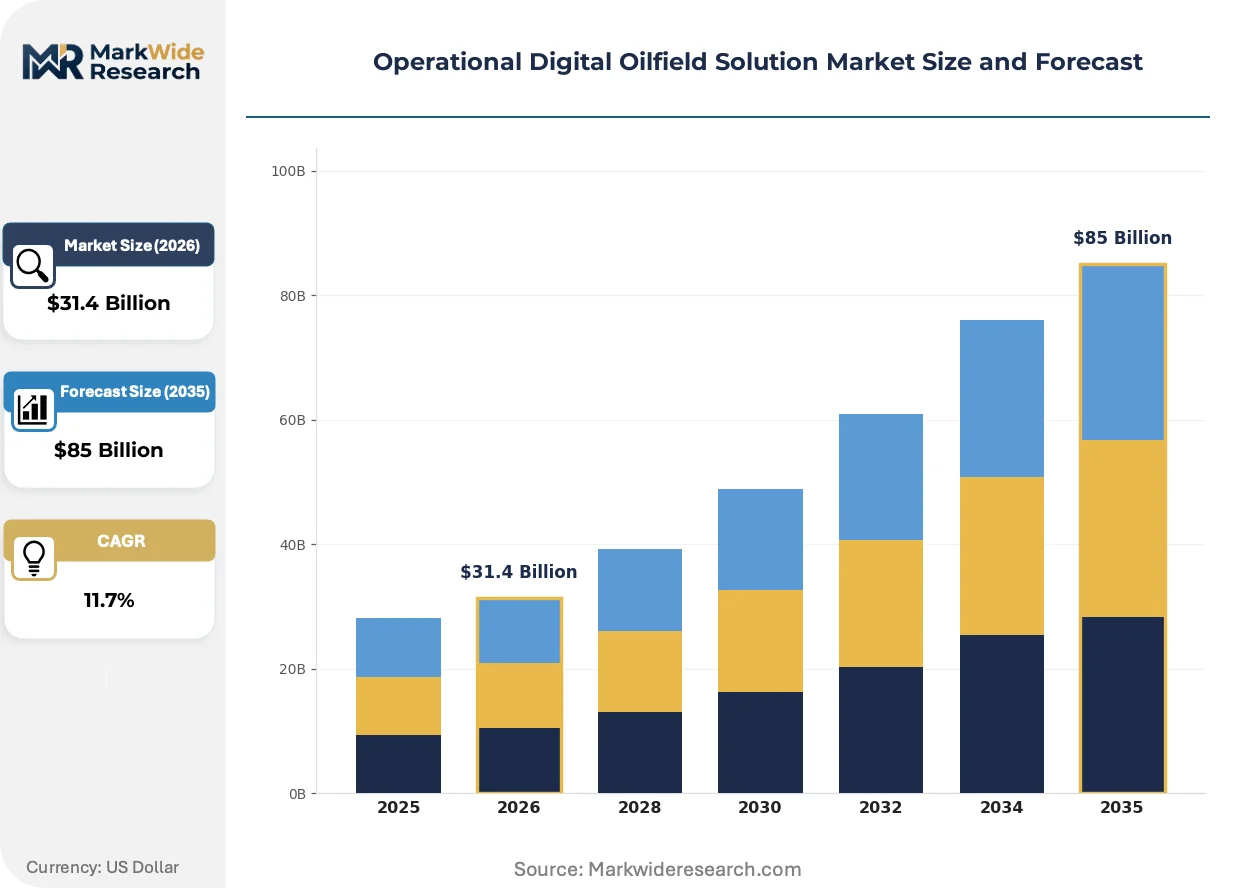
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Software Development, Data Management, System Integration Technology: IoT Solutions, Cloud Computing, Big Data Analytics, Automation Systems End User: Oil Producers, Service Companies, Pipeline Operators, Equipment Manufacturers Application: Production Optimization, Asset Management, Risk Assessment, Environmental Monitoring |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, ABB Ltd, Siemens AG, Schneider Electric SE, NOV Inc., Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operational Digital Oilfield Solution Market Strategic Shifts
Latency-sensitive processing is migrating from centralized cloud stacks to ruggedized edge nodes, rewiring vendor competitive advantage around hardware-software co-design rather than pure analytics licensing.
Time-sensitive networking over Ethernet is supplanting legacy Modbus and Profibus fieldbus protocols in artificial lift control loops. Independent operators in the Permian Basin are deploying TSN-enabled variable frequency drives at scale. This shift is compressing vendor qualification cycles for interoperability-certified hardware.
The EU Cyber Resilience Act imposes mandatory security update obligations on connected industrial equipment. European offshore operators now require vendor roadmaps for decade-long patch support. North Sea platform procurement specifications are being rewritten to exclude suppliers lacking CRL-compliant certification paths.
Integrated service contracts are unbundling hardware ownership from analytics subscriptions. Majors in the Gulf of Mexico now lease edge infrastructure as operational expenditure rather than capital deployment. This shift favors vendors with balance-sheet capacity to carry asset-heavy revenue models.
Operational Digital Oilfield Solution Market Segmentation
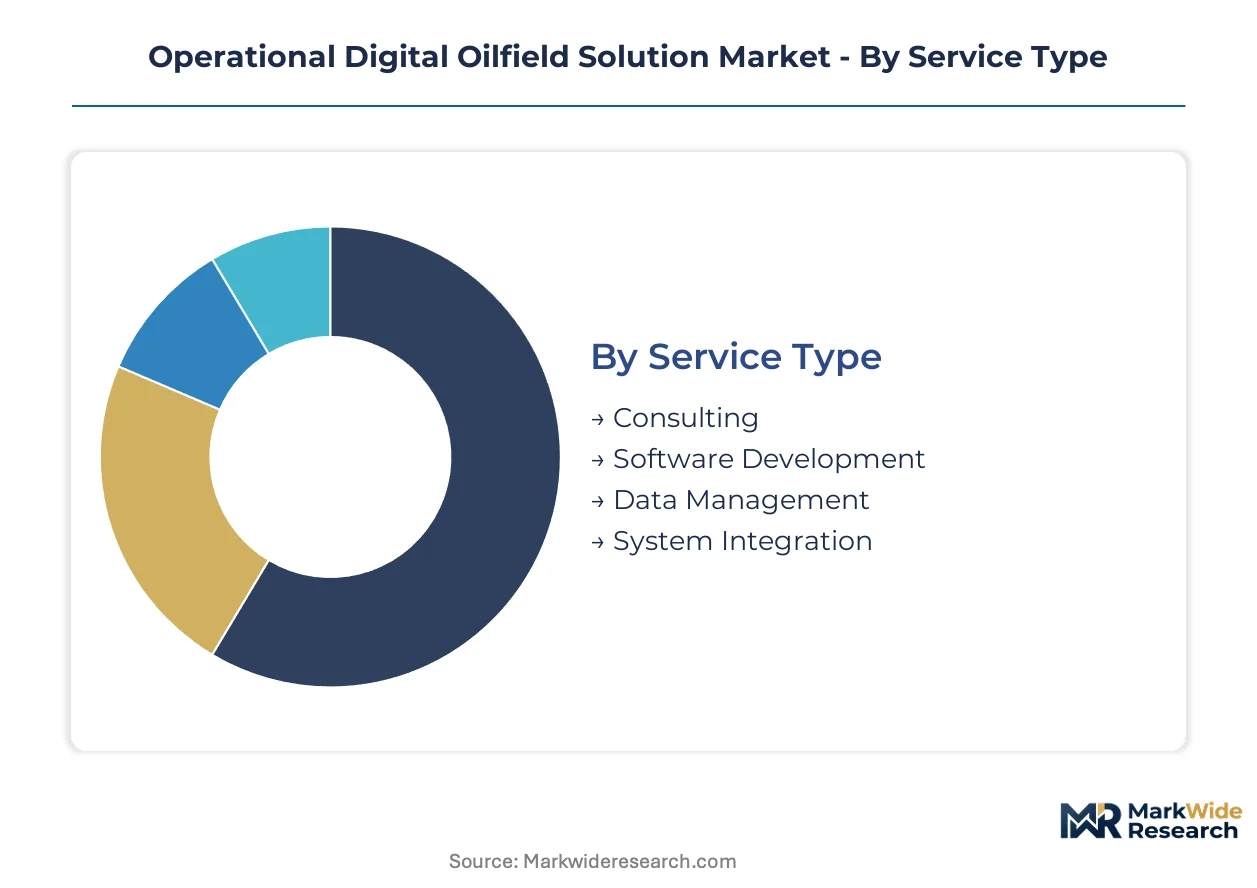
Segmentation in the operational digital oilfield solution market reveals distinct procurement patterns across technology layers and buyer archetypes. Understanding these divisions exposes where vendor substitution pressure concentrates and where integration complexity creates defensive moats.
Service Type:
Consulting faces acute substitution pressure from in-house petroleum data science teams, while system integration maintains defensive positioning through legacy SCADA entanglement.
- Consulting:Reservoir engineering advisory and digital transformation roadmapping services. Permian Basin independents increasingly bypass external consultants for direct platform vendor relationships, compressing day rates.
- Software Development:Custom application builds for wellhead automation and production accounting. North Sea operators demand Norwegian-content-compliant development centers, elevating local vendor preference.
- Data Management:Master data governance and historian migration services. Brazil's ANP data-integrity mandates sustain demand for regulatory-compliant data stewardship.
- System Integration:Edge-to-cloud architecture deployment and OT-IT convergence. Gulf of Mexico offshore platforms require BSEE-certified integration partners, creating qualification barriers that protect incumbent positions.
System integration anchors the volume base while software development gains share at the steepest rate.
Technology:
Technology segments stratify by margin structure, with hardware-dependent layers facing commodity pressure and software-centric categories defending pricing power.
- IoT Solutions:Sensor networks, edge nodes, and field device telemetry for wellbore monitoring. Silicon carbide supply constraints stretch lead times for power electronics in Gulf of Mexico deployments.
- Cloud Computing:Cloud-native analytics platforms and elastic compute for reservoir simulation. Offshore Brazil operators accelerate migration as subsea fiber redundancy costs force centralized processing tradeoffs.
- Big Data Analytics:Machine learning models for production forecasting and choke optimization. Norway's Petroleum Safety Authority real-time monitoring rules expand qualified analytics procurement scope.
- Automation Systems:Closed-loop control systems for artificial lift and surface facilities. Time-sensitive networking adoption in Permian Basin pad drilling compresses legacy protocol maintenance revenue.
IoT solutions command the largest revenue pool while cloud computing expands most quickly as operators retire on-premise infrastructure.
End User:
End user segmentation reflects divergent digital maturity, with national oil companies lagging independents in platform refresh cycles.
- Oil Producers:Integrated majors and independents deploying full-stack digital oilfield platforms. US independents in the Permian Basin lead greenfield adoption without legacy SCADA migration burden.
- Service Companies:Drilling contractors and well intervention specialists procuring drilling optimization modules. Real-time telemetry requirements for BSEE blowout preventer compliance lock in sensor deployment.
- Pipeline Operators:Midstream entities hardening SCADA networks per API RP 1164 cybersecurity mandates. Encrypted edge node procurement expands across US interstate pipeline systems.
- Equipment Manufacturers:OEMs embedding predictive analytics into turbomachinery and artificial lift systems. Proprietary data formats impede cross-vendor analytics aggregation, fragmenting addressable market.
Oil producers drive the majority of platform investment while pipeline operators accelerate procurement fastest under regulatory compulsion.
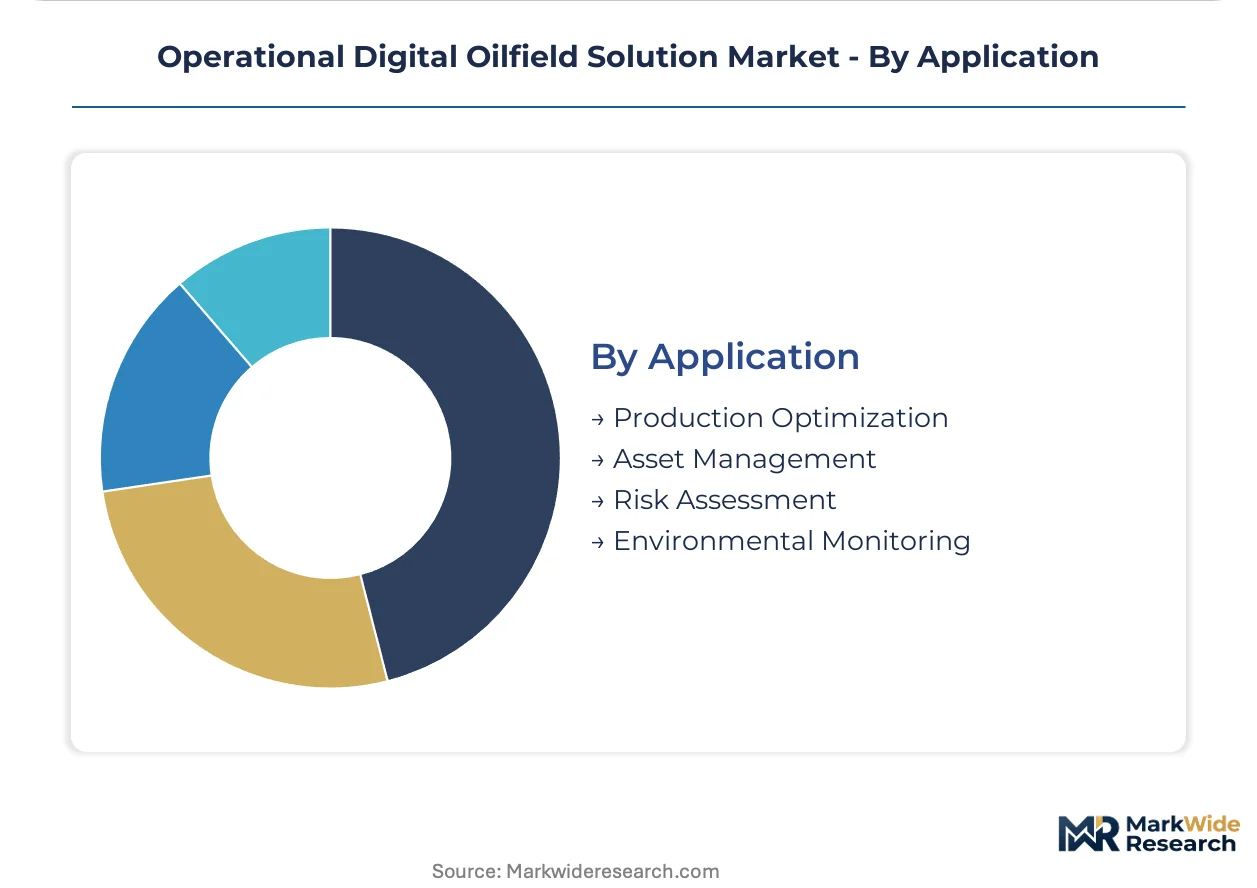
Application:
Application segments concentrate margin in barrel-linked outcomes, with environmental monitoring trailing as a cost-center rather than revenue-linked investment.
- Production Optimization:Real-time choke control and artificial lift automation tied directly to production uplift economics. Gulf of Mexico majors lease edge infrastructure as operational expenditure, favoring vendors with balance-sheet capacity for asset-heavy models.
- Asset Management:Digital twin deployment for facility integrity and maintenance scheduling. Brazil's ANP production-sharing frameworks incentivize integrated twin adoption across Santos Basin pre-salt clusters.
- Risk Assessment:Predictive models for wellbore stability and equipment failure. EU Cyber Resilience Act patch-support mandates reshape North Sea platform procurement specifications.
- Environmental Monitoring:Emissions tracking and regulatory compliance reporting. US EPA methane rules and Norway's carbon intensity standards elevate sensor deployment for flaring and venting detection.
Production optimization captures the highest margin concentration while asset management climbs fastest on digital twin standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin independents exhibit the highest price elasticity, squeezing vendor margins through competitive bidding for pad-scale digital infrastructure, while Gulf of Mexico majors absorb premium pricing for BSEE-certified integration without material procurement friction.
United States
Pad drilling density in West Texas and New Mexico generates network-effect economies for shared edge infrastructure across adjacent leases. The Bureau of Safety and Environmental Enforcement mandates real-time blowout preventer monitoring, locking Gulf of Mexico operators into sensor deployment cycles. Houston anchors the vendor ecosystem, with system integrators clustering around BSEE certification pathways.
Norway
North Sea platform electrification and carbon intensity targets accelerate digital twin procurement for facility integrity management. The Petroleum Safety Authority imposes local-presence rules that elevate vendor establishment costs and reshape qualification barriers. Stavanger concentrates operator headquarters and integration specialist capacity for subsea asset monitoring.
Brazil
Pre-salt cluster development in the Santos Basin drives integrated production platform adoption under ANP production-sharing frameworks. Subsea fiber cable fragility forces redundant radio-frequency backup systems for real-time data backhaul. Rio de Janeiro hosts national oil company procurement functions and vendor technical centers.
United Kingdom
North Sea decommissioning schedules and late-life asset optimization sustain demand for predictive maintenance analytics. The EU Cyber Resilience Act reshapes platform procurement specifications through mandatory decade-long security update obligations. Aberdeen retains specialist integration capacity despite contracting offshore installation activity.
China
State-directed shale gas development in Sichuan Basin deploys automated wellhead control for tight gas reservoirs. National data sovereignty requirements mandate domestic cloud infrastructure for subsurface telemetry processing. Chengdu anchors regional digital oilfield R&D centers serving onshore unconventional plays.
Operational Digital Oilfield Solution Market Competitive Environment
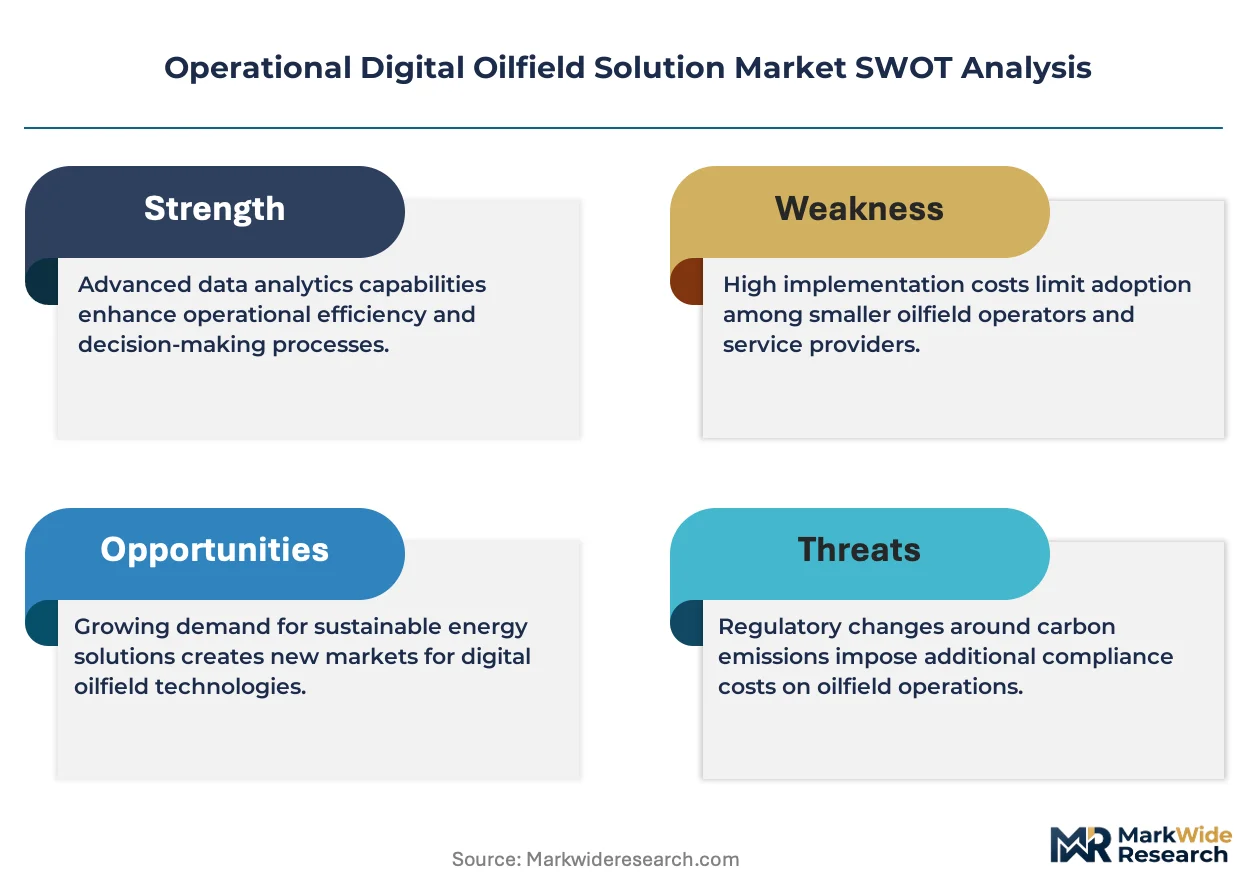
Technology leadership and cost leadership are held by different player archetypes, with full-stack platform providers commanding premium positioning through subsurface-to-surface integration while modular specialists compete on deployment velocity and point-solution pricing. The market structure concentrates around three strategic tiers: integrated energy technology conglomerates with captive hardware-software stacks, industrial automation multinationals leveraging cross-sector control system expertise, and emerging pure-play analytics vendors. Dominant competitive moves include unbundling hardware ownership from analytics subscriptions to shift revenue toward operational expenditure models, and geographic certification investments to satisfy local-content mandates in Norway and Brazil.
Among integrated energy technology providers, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the full-stack archetype, each anchoring competitive positioning through distinct technical heritage—subsurface integration, drilling optimization, and turbomachinery analytics respectively. These entities occupy positions where proprietary data layers and long-standing operator relationships create defensive moats against modular competitors, though their asset-heavy balance sheets face pressure as majors accelerate leasing-based procurement preferences.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| NOV Inc. |
| Emerson Electric Co. |
| Others |
Value Chain & Pricing Dynamics
Integrated production contracts with decade-long analytics subscription terms lock in Gulf of Mexico operators to predictable cost structures while securing silicon carbide allocation for edge node power electronics. These arrangements bundle hardware leasing with software maintenance, insulating vendors from spot-market volatility in critical semiconductor substrates.
Pricing Analysis
Aftermarket service contracts and predictive analytics subscriptions generate lifetime value multiples exceeding initial edge hardware deployment. Three-tier pricing structure across premium certified integration, standard interoperability modules, and economy sensor-only configurations stratifies the vendor base. Cost compression in economy-tier hardware is intensifying as Permian Basin independents consolidate pad-scale procurement through competitive bidding. National oil companies in Brazil exhibit lowest price sensitivity due to ANP production-sharing framework cost recovery mechanisms, while US independents squeeze margins aggressively.
Supply Chain Analysis
Silicon carbide substrate fabrication in Germany, Japan, and the United States creates chokepoints for edge computing power electronics qualification. Supply chains for ruggedized edge nodes draw from constrained semiconductor foundry capacity, rare earth magnet sources for motor drives, and optical fiber cable production. Single-source vulnerability in subsea fiber backhaul for offshore Brazil forces redundant RF backup system costs into project economics. Distribution runs through BSEE-certified system integrators clustered in Houston for Gulf of Mexico deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates where regulatory divergence between BSEE, Norway's Petroleum Safety Authority, and Brazil's ANP creates compliance-specialist niches that modular vendors can occupy without challenging full-stack incumbents head-on.
For Market Incumbents: Fortify subsurface-to-surface data integration moats by embedding proprietary machine learning models deeper into artificial lift control loops. Acquire edge hardware leasing capabilities to match Gulf of Mexico operator preference for operational expenditure models. Threat substitution from pure-play analytics vendors demands certification investments in EU Cyber Resilience Act compliance pathways. For New Entrants and Emerging Players: Lead with API RP 1164 cybersecurity hardening modules for midstream pipeline operators facing mandatory SCADA network upgrades. Target Permian Basin digital-native independents lacking legacy SCADA migration burdens for greenfield platform adoption. Go-to-market angle emphasizes rapid deployment velocity against incumbent integration timelines. For Investors and Strategic Acquirers: Petroleum data science boutiques with hybrid reservoir engineering and software engineering teams represent prime acquisition targets as compensation inflation signals structural talent scarcity. Long-term viability hinges on vendor ability to bridge operational technology and information technology domains without incumbency drag. Signal to monitor: BSEE certification pathway expansion or contraction for non-traditional system integrators.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 1164 Compliance Certification | Unlocks midstream pipeline procurement cycles under mandatory US cybersecurity mandates. |
| Edge Hardware Leasing Model | Aligns vendor revenue with Gulf of Mexico operator capital-to-operational expenditure preferences. |
| Silicon Carbide Supply Agreement | Secures 18-24 month qualification timelines for power electronics in constrained substrate markets. |
| Pre-salt Digital Twin Deployment | Captures Brazil ANP production-sharing framework incentives across Santos Basin megaprojects. |
| Time-Sensitive Networking Migration | Displaces legacy Modbus protocols in Permian Basin pad drilling automation control loops. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with reservoir engineers, SCADA integration specialists, petroleum data scientists, and procurement officers at national oil companies and independents. Secondary validation drew from BSEE regulatory filings, ANP production-sharing contract disclosures, API standards documentation, and edge computing hardware qualification records. Bottom-up deployment counts across Permian Basin, North Sea, and offshore Brazil assets were triangulated against top-down vendor revenue segmentation.
Across the analysis window, the forecasting framework models technology adoption by deployment architecture, buyer digital maturity tier, and regulatory compliance cluster. CAGRs were derived from elasticity-adjusted penetration curves calibrated to historical SCADA replacement cycles and cloud migration patterns. Industry-specific inputs include subsea fiber redundancy cost trajectories and silicon carbide substrate allocation forecasts from power electronics supply chains.
The analysis sits within stated boundaries; outcomes outside sustained offshore drilling activity levels, stable API cybersecurity mandate enforcement, and resolved semiconductor supply constraints would require recalibration. Practitioners should keep alternative scenarios live as regulatory fragmentation intensity and edge computing hardware availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Oman Directional Drilling Market