
 Canada Oil and Gas Pipeline Services Market | 2026-2036
Canada Oil and Gas Pipeline Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Oil and Gas Pipeline Services Market Outlook
Composite materials are displacing conventional steel in select pipeline rehabilitation applications and is recalibrating lifecycle cost calculations for Canadian operators. Baker Hughes leverages advanced inspection technologies to sustain its position across Western Canada's gathering systems. Enbridge anchors its service portfolio around integrity management for cross-border transmission routes. TC Energy competes through specialized expertise in high-pressure natural gas pipeline construction across the Montney and Duvernay formations.
Canada oil and gas pipeline services encompass the engineering, construction, inspection, maintenance, and operational support required to transport hydrocarbons through pressurized tubular systems, typically operating at pressures ranging from 200 to 1,440 psi depending on product classification and terrain. These services ensure continuous flow assurance, structural integrity, and regulatory compliance across gathering, transmission, and distribution networks. Inspection services command premium margins as operators face escalating regulatory scrutiny over methane emissions and crack detection in aging steel infrastructure. Construction activity concentrates in natural gas applications where LNG export commitments from British Columbia drive new gathering line deployment. Transportation services remain the revenue backbone, though maintenance spending accelerates as post-2010 pipeline vintage enters peak replacement cycles.
Health Canada and PMRA oversee environmental protection protocols affecting pipeline corridor permitting, while provincial regulators including the Alberta Energy Regulator and BC Oil and Gas Commission enforce construction standards and integrity management requirements. The Canadian Standards Association Z662 code shapes material specifications and welding protocols that dictate supplier qualification and market access. Stakeholders must monitor evolving federal methane reduction mandates and their cascading implications for leak detection technology procurement and service contractor certification requirements.
Market Dynamics
PHMSA-aligned integrity mandates and provincial leak detection standards are forcing midstream operators across Alberta and British Columbia to accelerate rehabilitation spending on aging oil sands corridors. This regulatory compression is restructuring contractor procurement toward specialized inspection and continuous monitoring capabilities.
Growth Catalysts
- Alberta Energy Regulator construction standards:Tightened welding protocol requirements under CSA Z662 are mandating third-party certification for pipeline rehabilitation contractors, expanding addressable market for qualified service providers.
- Methane reduction frameworks:Federal mandates for leak detection technology deployment are driving procurement of advanced inspection systems across Montney formation gathering networks.
- Composite material rehabilitation:Fiber-reinforced polymer liners are penetrating crack repair applications in high-pressure natural gas transmission, extending asset life without full replacement.
Market Restraints
- Specialized welding consumables:Nickel-alloy electrodes and automated welding wire for sour service applications face supply concentration from limited North American producers, creating input cost volatility.
- Seasonal construction windows:Permafrost terrain and winter access restrictions in northern Alberta and BC constrain executable construction days to 180-200 annually, compressing project throughput.
- Regulatory duplication:Overlapping federal methane rules and provincial spill response requirements create compliance friction without proportional risk reduction.
Strategic Opportunities
- Underpenetrated subsea inspection:Offshore Atlantic Canada pipeline infrastructure lacks dedicated ROV-based integrity contractors, presenting first-mover positioning for specialized service entrants.
- Carbon capture integration:CO2 transportation pipeline construction for Alberta's sequestration hubs requires corrosion-resistant materials and pressure-rated welding expertise distinct from hydrocarbon service.
- Real-time monitoring convergence:Fiber optic sensing fused with satellite telemetry enables continuous leak detection across remote northern corridors without manned patrol infrastructure.
Industry Challenges
- Certified inspector scarcity:CSA Z662-qualified ultrasonic testing technicians and phased-array specialists command premium wages, constraining inspection capacity expansion.
- Legacy SCADA integration:New digital twin platforms must interface with 1980s-era control systems in established oil sands pipelines, extending deployment timelines and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Oil and Gas Pipeline Services Market |
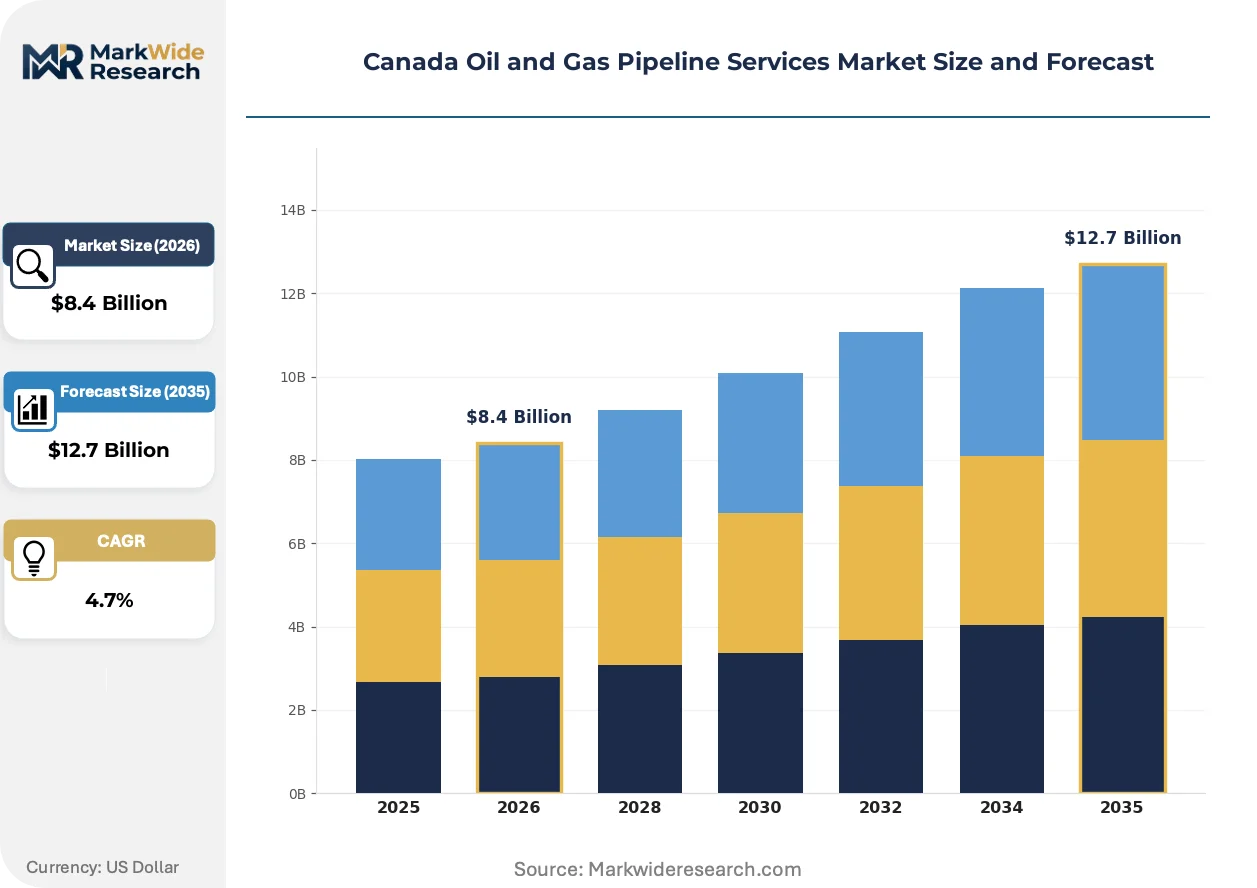
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Maintenance, Inspection, Construction Pump Type: Centrifugal, Positive Displacement, Screw, Diaphragm Material: Steel, Polyethylene, PVC, Composite Application: Crude Oil, Natural Gas, Water, Chemicals |
| Companies Covered | Tenaris SA, Mistras Group Inc, Enbridge, Baker Hughes, Trican Well Service Ltd, TC Energy, Tetra Tech Inc, Schlumberger, Kinder Morgan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Oil and Gas Pipeline Services Market Strategic Shifts
Digital inspection technologies and material science advances are compressing traditional maintenance cycles while expanding predictive capabilities across Western Canada's pipeline networks. These shifts are redrawing contractor specialization boundaries and equipment investment priorities.
Phased-array ultrasonic testing is overtaking conventional radiographic inspection for crack detection in sour gas pipelines. Enbridge and TC Energy are standardizing this technology across their cross-border transmission systems, eliminating film processing delays and enabling same-day repair decisions. The structural consequence is collapsing inspection-to-repair timelines from weeks to hours, compressing contractor revenue recognition cycles while demanding higher equipment capital intensity.
Health Canada and PMRA environmental protection protocols are tightening corridor permitting requirements for watercourse crossings in British Columbia. Industrial consequence includes extended environmental assessment timelines and mandatory fish habitat compensation, particularly affecting new gathering line deployment in the Montney. LNG export project operators are responding by front-loading regulatory submissions and pre-positioning environmental consultants within engineering teams.
Service unbundling is fragmenting traditional EPC contracts into discrete inspection, maintenance, and integrity management awards. Midstream operators in Alberta are disaggregating multi-year master service agreements into single-project procurements, forcing contractors to rebid repeatedly. This pattern concentrates in oil sands transportation corridors where operator procurement functions have centralized under cost-reduction mandates, privileging specialized niche providers over full-service generalists.
Canada Oil and Gas Pipeline Services Market Segmentation
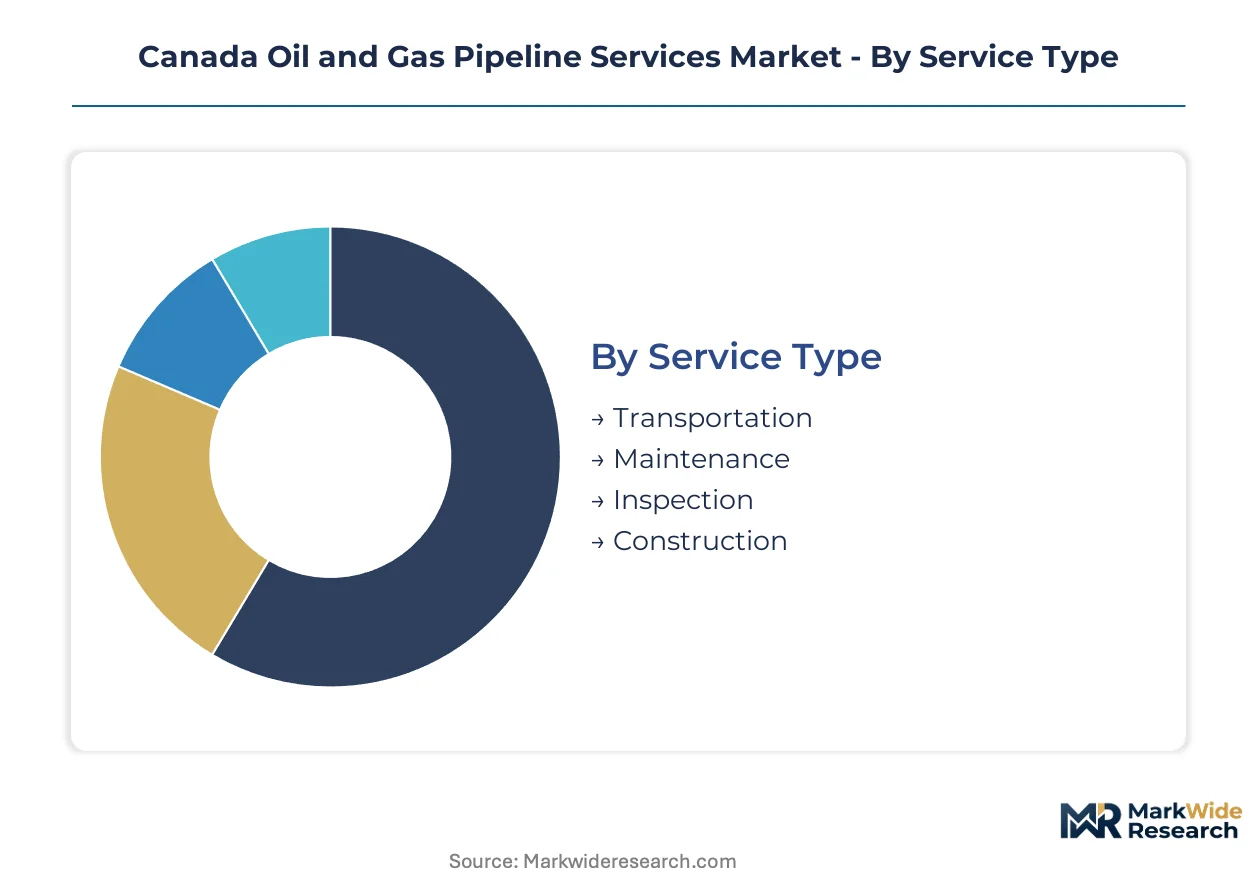
Service specialization across Canadian pipeline networks reflects diverging asset ages and regulatory pressure points. Segment boundaries are hardening as operators unbundle contracts and demand discrete capabilities for inspection versus construction versus maintenance.
Service Type:
Replacement cycles and integrity mandates are redistributing procurement budgets across the four core service categories, with inspection and maintenance capturing incremental share as construction normalizes.
- Transportation:Pressure-rated logistics and batch scheduling for crude and natural gas movements through trunk lines and gathering systems. Flow assurance contracts dominate in Alberta's oil sands corridors where bitumen diluent blending requires continuous operational oversight.
- Maintenance:Scheduled rehabilitation, cathodic protection renewal, and valve replacement programs. Demand concentrates in British Columbia's Montney formation where sour gas degradation accelerates metal fatigue in high-pressure gathering lines.
- Inspection:In-line tool runs, ultrasonic testing, and regulatory compliance reporting. Federal methane reduction frameworks are expanding procurement of continuous monitoring systems across aging transmission infrastructure.
- Construction:Greenfield pipeline installation, station upgrades, and tie-in welding. Activity clusters in LNG export corridor expansions where BC Oil and Gas Commission permitting drives project phasing.
Transportation sits at the top of the volume ranking, with Inspection climbing the fastest as regulatory deadlines compress procurement timelines.
Pump Type:
Fluid handling requirements vary sharply by product viscosity and pressure specifications, with cost tier differentiation separating standard crude service from specialized sour gas applications.
- Centrifugal:High-volume, low-viscosity applications for refined products and light crude transmission. Standardized procurement dominates in Alberta's established pipeline corridors where operators prioritize capital efficiency over customization.
- Positive Displacement:Viscous fluid handling for heavy crude and bitumen blends. Specifications tighten in oil sands transportation where diluent ratios and temperature maintenance dictate pump selection.
- Screw:Multi-phase flow applications with entrained gas tolerance. Deployments concentrate in Montney gas gathering where slug flow conditions stress conventional pump designs.
- Diaphragm:Zero-emission chemical injection and small-volume metering service. Methane reduction mandates are expanding procurement for leak-proof seal designs in remote wellpad applications.
Centrifugal pumps retain the largest installed base, though Positive Displacement systems are expanding most quickly as heavy crude volumes rise.
Material:
Material selection tracks pressure rating requirements and corrosion exposure, with geography influencing availability of specialized grades and welding consumables.
- Steel:High-pressure transmission and sour service applications requiring CSA Z662-compliant metallurgy. Dominates cross-border routes where Enbridge and TC Energy specify enhanced toughness grades for fracture control.
- Polyethylene:Flexible gathering lines and medium-pressure distribution with corrosion immunity. Adoption accelerates in BC watercourse crossings where trenchless installation reduces environmental assessment timelines.
- PVC:Low-pressure utility and secondary containment applications. Specifications limit deployment to non-hydrocarbon service in municipal water and industrial cooling systems.
- Composite:Fiber-reinforced polymer liners and full-composite spoolable pipe for rehabilitation. Crack repair applications in natural gas transmission are extending asset life without full replacement shutdowns.
Steel commands the dominant share by installed length, with Composite materials gaining share fastest as rehabilitation budgets outpace greenfield construction.
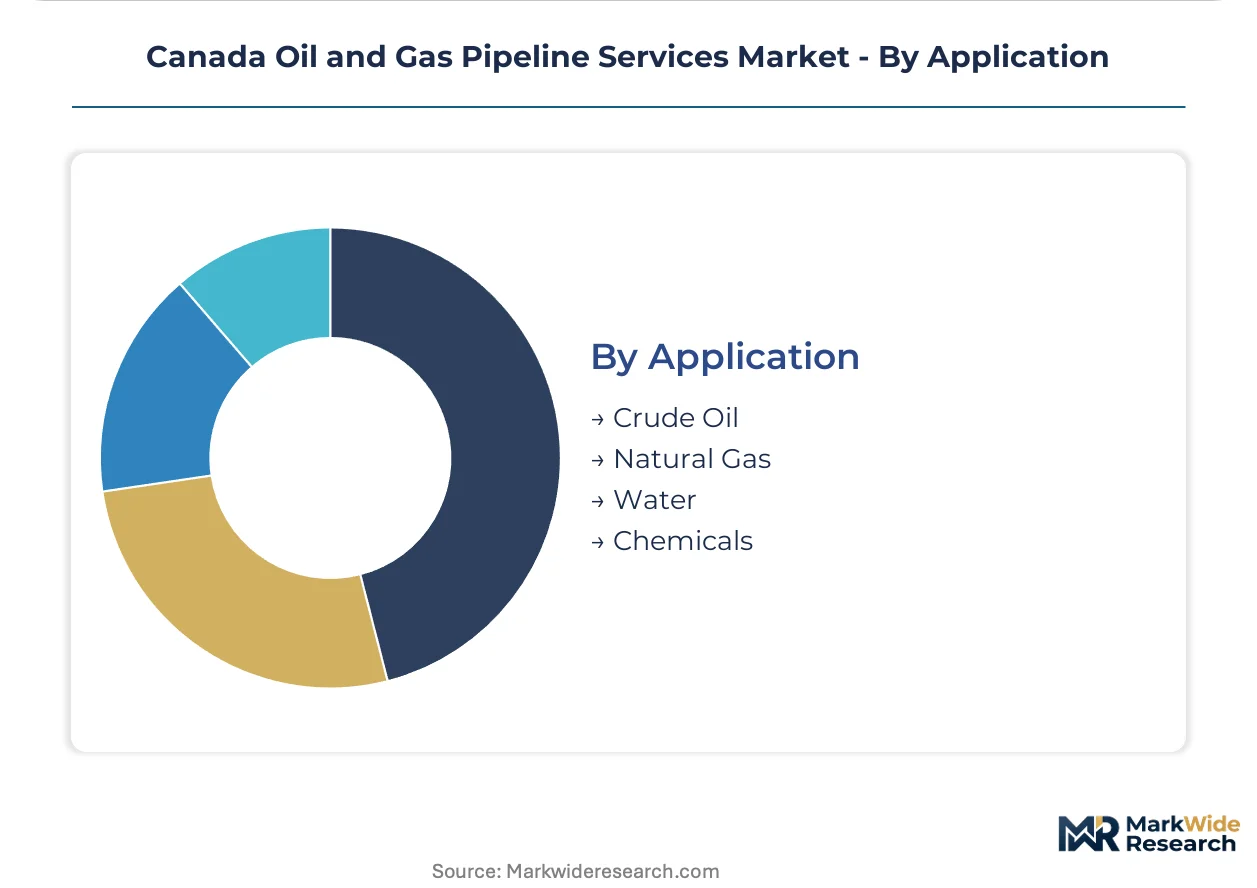
Application:
End-use demand splits between hydrocarbon transport and utility service, with customer type differentiation separating regulated transmission from discretionary gathering investments.
- Crude Oil:Diluted bitumen, synthetic crude, and light oil pipeline transport. Volumes concentrate in Alberta's oil sands corridors where aging infrastructure requires continuous integrity management.
- Natural Gas:Dry gas, liquids-rich, and sour gas gathering and transmission. LNG export commitments from British Columbia are driving new gathering line deployment and compressor station expansion.
- Water:Produced water disposal, fresh water supply, and hydrotest fluid management. Regulatory tightening on aquifer protection is expanding treatment and containment specifications.
- Chemicals:Corrosion inhibitors, methanol, and specialty injection fluids. Batch scheduling complexity limits this to niche applications in sour gas processing facilities.
Natural gas applications lead by current project backlog, with Crude Oil service maintaining the deepest installed base requiring ongoing rehabilitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta's oil sands corridors anchor Canadian pipeline services demand, with integrity mandates and LNG export commitments driving activity across provincial boundaries. Provincial regulators enforce divergent construction standards and environmental protocols that reshape contractor procurement patterns.
Alberta
Oil sands transportation corridors and Montney formation gathering networks concentrate rehabilitation spending. The Alberta Energy Regulator enforces CSA Z662 welding protocols that mandate third-party certification for pipeline contractors. Calgary hosts the headquarters of Enbridge and TC Energy, where procurement centralization under cost-reduction mandates privileges specialized niche providers.
British Columbia
LNG export commitments from Kitimat and Prince Rupert drive new gathering line deployment and compressor station expansion. The BC Oil and Gas Commission tightens watercourse crossing permits with mandatory fish habitat compensation requirements. The Montney formation spans northeastern BC where sour gas degradation accelerates metal fatigue in high-pressure gathering infrastructure.
Ontario
Cross-border transmission corridors and Great Lakes refinery connections sustain maintenance contracting for aging steel infrastructure. Federal methane reduction frameworks cascade into provincial procurement specifications for leak detection technology. Sarnia's petrochemical cluster generates demand for corrosion-resistant materials in chemical injection and specialty fluid handling applications.
Saskatchewan
Bakken formation light oil gathering and Bakken-to-market pipeline connections support regional construction activity. Provincial regulators align with federal integrity mandates while maintaining distinct spill response requirements that create compliance friction. The Regina-Weyburn corridor concentrates carbon capture transportation pipeline planning for sequestration hub development.
Atlantic Canada
Offshore Nova Scotia and Newfoundland pipeline infrastructure lacks dedicated ROV-based integrity contractors, presenting first-mover positioning opportunities. Health Canada and PMRA environmental protection protocols affect subsea corridor permitting timelines. The Jeanne d'Arc Basin and Scotian Shelf contain aging subsea infrastructure requiring specialized inspection capabilities absent from regional vendor bases.
Canada Oil and Gas Pipeline Services Market Competitive Environment
Capacity expansion dominates the current landscape as contractors position for LNG-related construction cycles and integrity mandate compliance. The vendor base stratifies across three tiers: integrated midstream operators with captive service arms, specialized inspection and maintenance contractors holding CSA Z662 certifications, and regional construction firms competing on project-specific bids. Two competitive moves define positioning: geographic expansion into underpenetrated Atlantic Canada subsea markets, and technology licensing partnerships for fiber optic sensing and phased-array ultrasonic inspection systems.
Among North American integrated service providers, Baker Hughes and Schlumberger occupy positions spanning inspection technology and construction capability across Western Canada. TC Energy exemplifies the midstream-operator-as-contractor archetype through its specialized expertise in high-pressure natural gas pipeline construction. Enbridge anchors the integrity management segment with cross-border transmission route portfolios. Trican Well Service Ltd represents Canadian-founded specialists competing against global diversified players.
| Leading Market Players |
|---|
| Tenaris SA |
| Mistras Group Inc |
| Enbridge |
| Baker Hughes |
| Trican Well Service Ltd |
| TC Energy |
| Tetra Tech Inc |
| Schlumberger |
| Kinder Morgan |
| Others |
Value Chain & Pricing Dynamics
Federal methane reduction mandates gate qualified supply and premium-tier pricing access for Canadian pipeline service contractors, as compliance certification requirements concentrate procurement among CSA Z662-qualified providers capable of commanding rate premiums for inspection and continuous monitoring deployments.
Pricing Analysis
Input-cost pass-through from nickel-alloy welding consumables and phased-array ultrasonic equipment shapes contractor rate structures across Alberta and British Columbia. Project-based pricing dominates, with differentiation anchored in CSA Z662 certification tier and equipment capital intensity. Cost compression in standard inspection services intensifies as procurement centralization under midstream operator cost mandates squeezes margins. Small regional contractors exhibit highest price sensitivity, while integrated providers with captive technology platforms maintain pricing power.
Supply Chain Analysis
Domestic-content requirements under the Canadian Standards Association Z662 code reshape sourcing toward North American steel mills and qualified welding consumable producers. The supply chain draws from the United States, Canada, and limited European sources for specialized sour-service metallurgy. Nickel-alloy electrodes and automated welding wire constitute critical input dependencies. Single-source vulnerability concentrates in high-grade steel plate for cross-border transmission projects. Distribution runs through direct contractor-procurement relationships with midstream operators, supplemented by distributor networks for maintenance consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with PHMSA-aligned integrity mandates and provincial leak detection standards generating sustained demand for specialized inspection and rehabilitation services across Western Canada's aging infrastructure corridors.
For Market Incumbents: Deepen CSA Z662 certification coverage across phased-array ultrasonic testing and fiber optic sensing technologies to defend against emerging digital-native inspection entrants. Prioritize backward integration into specialized welding consumable supply to offset nickel-alloy electrode cost volatility. Calgary and Edmonton procurement centralization at Enbridge and TC Energy demands direct relationship investment over distributor intermediation.
For New Entrants and Emerging Players: Enter via Atlantic Canada subsea inspection white space, where ROV-based integrity capabilities remain absent despite aging Jeanne d'Arc Basin infrastructure. Target carbon capture transportation pipeline construction in Alberta's sequestration hubs, where corrosion-resistant material expertise creates differentiation from established hydrocarbon contractors. Lead with technology licensing partnerships for real-time monitoring convergence rather than capital-intensive equipment ownership.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional construction firms lacking CSA Z662 certification depth, presenting consolidation targets for capability accretion. Long-term viability hinges on regulatory enforcement durability rather than commodity cycle exposure. Watch federal methane reduction mandate implementation pace as the key inflection signal for inspection technology procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CSA Z662 Certification Expansion | Third-party welding protocol certification under AER standards unlocks midstream operator procurement eligibility. |
| Fiber Optic Sensing Deployment | Real-time leak detection convergence with satellite telemetry enables unmanned northern corridor monitoring. |
| Composite Material Rehabilitation | Fiber-reinforced polymer liner installation extends sour gas transmission asset life without full replacement. |
| Atlantic Canada Subsea Entry | ROV-based integrity capabilities address unmet demand in Nova Scotia and Newfoundland offshore basins. |
| Carbon Capture Pipeline Construction | CO2 transportation expertise for Alberta sequestration hubs requires distinct corrosion-resistant welding protocols. |
Study Parameters
Bottom-up midstream operator spending modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with integrity management directors, procurement leads at Enbridge and TC Energy, CSA Z662 certification auditors, and welding consumable distributors combined with secondary validation from Alberta Energy Regulator construction permit databases, BC Oil and Gas Commission environmental assessment filings, and CSA standards documentation. Triangulation across these sources ensures segment-level precision.
Input-output matrix framing connects pipeline mileage under integrity mandate, rehabilitation spending per kilometer, and service contractor utilization rates across the projection horizon. Segmentation dimensions modeled include service type, pump category, material specification, and application end-use, with provincial regulatory cluster as an additional industry-specific dimension. CAGRs derive from regression analysis against historical spending patterns and regulatory deadline scheduling, incorporating LNG export commitment timelines and carbon capture hub development pace as forecast inputs.
Inputs from provincial regulator filings and midstream operator procurement disclosures were available through the study window; gaps in private contractor financial performance introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Pipeline age distribution data, federal methane rule implementation sequencing, and nickel-alloy supply availability constitute the small set of named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Liner Hanger System Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Copper Mining Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Iran Oil and Gas Market