
 Oil and Gas Infrastructure Market | 2026-2036
Oil and Gas Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Infrastructure Market Analysis
Midstream logistics channels is rewriting competitive dynamics across oil and gas infrastructure. Schlumberger NV leverages its integrated digital subsurface platforms to anchor deepwater project economics. Bechtel Corporation sustains its position through megaproject execution capability in LNG liquefaction. Saipem SpA specializes in subsea installation vessels that dominate frontier basin development.
Oil and gas infrastructure encompasses the physical systems, equipment, and integrated networks required to extract, transport, process, and refine hydrocarbons, including steel pipelines rated for pressures exceeding 1,440 psi, modular compression stations, and atmospheric distillation columns operating at temperatures above 350°C. Its primary purpose is to bridge the gap between reservoir extraction and refined product delivery to wholesale and retail markets. Upstream drilling technologies command substantial capital allocation as operators target deeper pre-salt and unconventional reservoirs. Pipeline systems within the midstream category generate stable tariff-based revenue streams that attract infrastructure fund investment. Downstream refining technologies face margin pressure from renewable fuel mandates but retain strategic value in high-complexity conversion units.
The US EPA enforces methane performance standards under the Clean Air Act that compel leak detection and repair programs across transmission pipelines. The EU F-Gas Regulation and EU Green Deal methane strategy impose import standards on fossil fuel suppliers seeking European market access. ISO 13628 and API RP 2SK govern subsea production system design, creating compliance barriers for non-certified equipment vendors. Stakeholders must monitor regulatory divergence between jurisdictions that fragment equipment certification requirements and capital deployment timelines.
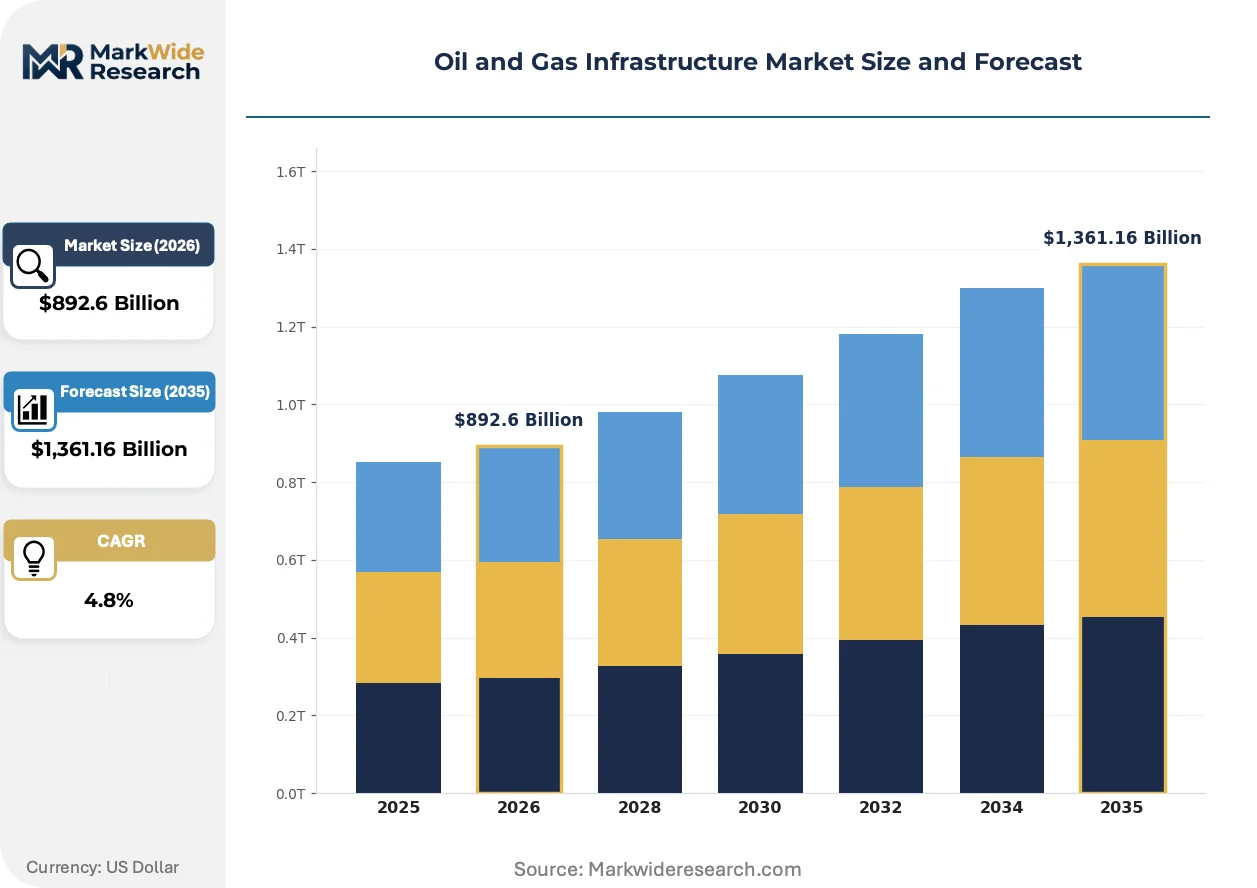
Market Dynamics
Integrated energy buyers are redirecting capital toward LNG export terminals along the US Gulf Coast, compressing project timelines and reshaping contractor selection criteria for liquefaction capacity.
Growth Catalysts
- EU methane import standards:The EU Green Deal methane strategy mandates emission disclosures for fossil fuel suppliers, accelerating leak detection technology deployment across European-bound supply chains.
- Pre-salt reservoir development:Deepwater drilling technologies targeting pre-salt formations in Brazil and West Africa are expanding subsea production system demand.
- US Gulf Coast concentration:Petrochemical corridor expansions in Texas and Louisiana are driving pipeline interconnectivity investments for ethane and NGL feedstocks.
Market Restraints
- Specialized steel supply concentration:High-pressure pipeline grade steel production concentrates in a limited set of integrated mills, exposing project timelines to raw material allocation bottlenecks.
- Fugitive emission compliance costs:US EPA methane performance standards under the Clean Air Act impose continuous monitoring obligations that elevate operational expenditure baselines for transmission operators.
- Renewable fuel substitution:Biofuel blending mandates and electrification targets in transport sectors are compressing long-term demand visibility for conventional refined product infrastructure.
Strategic Opportunities
- Carbon capture retrofit integration:Post-combustion capture systems on existing gas processing trains offer pathway to low-carbon hydrogen production for industrial offtakers.
- Modular liquefaction units:Small-scale LNG solutions are opening stranded gas monetization in East Africa and Southeast Asia where megaproject economics fail.
- US Inflation Reduction Act incentives:Section 45Q tax credits for carbon oxide sequestration are improving project returns for blue hydrogen and enhanced oil recovery schemes.
Industry Challenges
- Subsea welding certification scarcity:Qualified hyperbaric welders and saturation divers for deepwater installation work command premium rates that compress contractor margins.
- Legacy SCADA integration complexity:Digital twin deployments for predictive maintenance require protocol translation layers that extend commissioning timelines for brownfield automation retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Infrastructure Market |
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,361.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Oilfield Services Technology: Drilling Technologies, Pipeline Systems, Refining Technologies, Transportation Solutions End User: Exploration Companies, Production Firms, Processors, Distributors Service Type: Maintenance Services, Engineering Services, Consulting Services, Installation Services |
| Companies Covered | Technip Energies NV, Saipem SpA, Schlumberger NV, Halliburton Co, Baker Hughes Company, McDermott International Ltd, TechnipFMC plc, Bechtel Corporation, Enbridge Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Infrastructure Market Emerging Trajectories
Digitalization of asset integrity management is compressing inspection cycles and enabling condition-based maintenance models that displace time-based regulatory compliance approaches.
Composite reinforced pipelines are migrating from niche gathering applications to high-pressure transmission service. Appalachian shale operators are piloting spoolable reinforced thermoplastic pipe for gas gathering networks. This technology is migrating from onshore flowlines to subsea jumpers, challenging conventional steel installation economics in shallow water developments.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration systems across LNG liquefaction plants. Industrial gas suppliers are retrofitting turbine inlet cooling systems with ammonia-based alternatives. Baseload liquefaction facilities in Qatar and Australia face accelerated compressor overhaul schedules to maintain cooling duty under refrigerant constraints.
Long-term tolling agreements are displacing merchant risk exposure for midstream investors. Infrastructure funds are prioritizing take-or-pay contracted pipelines over speculative capacity expansions. This preference shift concentrates capital deployment in the Permian Basin and Bakken formation where producer consolidation has improved counterparty credit quality.
Oil and Gas Infrastructure Market Segmentation
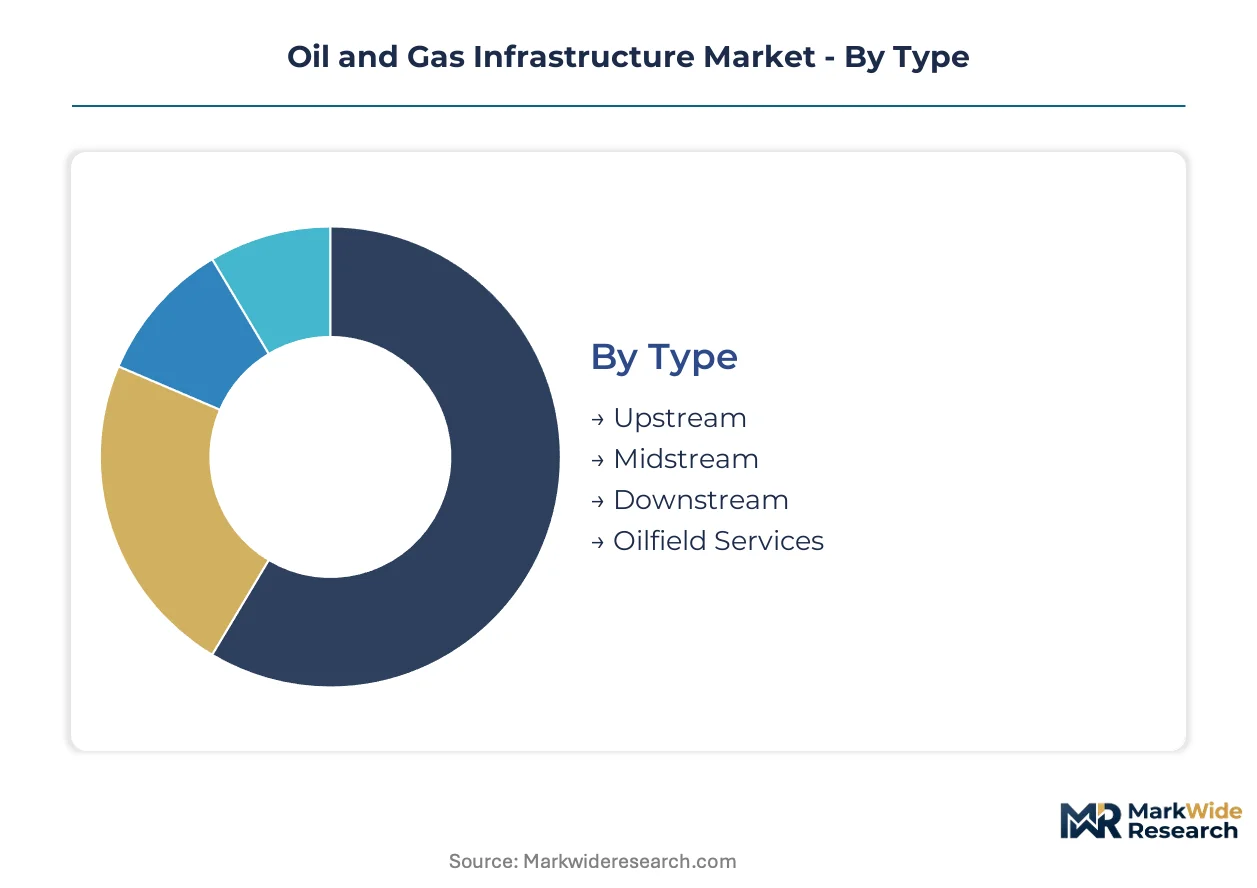
Oil and gas infrastructure segmentation reveals stark capital turnover disparities. Upstream drilling assets depreciate over 15-25 years while midstream pipelines stretch to 40-50 years, creating fundamentally different investment horizons and stakeholder profiles across categories.
Type:
Upstream assets turn over fastest as reservoir depletion forces continuous capital redeployment, while downstream refineries operate on the longest replacement cycles in the sector.
- Upstream:Exploration and production infrastructure encompasses subsea trees, floating production platforms, and onshore drilling rigs rated for high-pressure formations. Demand concentrates in Brazil's pre-salt basins and West African deepwater blocks where reservoir complexity drives subsea system procurement. National oil companies in these jurisdictions prioritize local content requirements that reshape contractor selection.
- Midstream:Pipeline networks, storage terminals, and compression stations form the connective tissue between production and consumption centers. Investment gravity centers on the US Gulf Coast petrochemical corridor where ethane and NGL feedstock pipelines command premium tariff structures. FERC interstate rate case procedures create regulatory latency that extends project sanction timelines.
- Downstream:Refining and petrochemical complexes with atmospheric distillation, hydrocracking, and catalytic reforming units. Complex conversion capacity in Texas and Louisiana retains margin advantage over simpler configurations facing renewable fuel mandate pressure.
- Oilfield Services:Contracted technical capabilities spanning directional drilling, wireline logging, and hydraulic fracturing fleets. Shale producers in the Permian Basin and Bakken formation drive utilization cycles that track commodity price volatility.
Midstream infrastructure anchors the volume base while upstream subsea systems gain share at the steepest rate.
Technology:
Technology segmentation stratifies by engineering intensity and proprietary differentiation, with drilling systems commanding the highest R&D allocation and transportation solutions operating as mature, cost-competitive categories.
- Drilling Technologies:Directional drilling assemblies, managed pressure systems, and rotary steerable tools for extended-reach laterals. Pre-salt formations in Brazil and West Africa demand high-temperature, high-pressure rated equipment that filters out non-specialized vendors. Petrobras technical specifications create de facto certification barriers for equipment suppliers.
- Pipeline Systems:Steel transmission lines, compressor stations, and metering facilities operating under tariff-regulated frameworks. Appalachian shale operators are piloting spoolable reinforced thermoplastic pipe for gathering networks, challenging conventional steel economics in onshore applications.
- Refining Technologies:Catalytic crackers, alkylation units, and hydroprocessing trains for sulfur removal. US Gulf Coast complex refineries leverage coking and hydrocracking capacity to process heavy sour crudes at margin advantage.
- Transportation Solutions:LNG carriers, rail tank car fleets, and marine loading systems. QatarEnergy shipping requirements for North Field expansion volumes are reshaping vessel contracting structures toward long-term charter commitments.
Pipeline systems anchor the volume base while drilling technologies expand most quickly.
End User:
End user segmentation reflects position in the value chain and corresponding risk tolerance, with exploration companies accepting the highest technical uncertainty and distributors prioritizing contracted revenue stability.
- Exploration Companies:Operators targeting frontier basins with unproven reserves, deploying seismic acquisition and exploratory drilling programs. Namibia's Orange Basin and Guyana's Stabroek Block attract independent explorers with favorable fiscal terms.
- Production Firms:Established operators managing decline curves and reserve replacement in mature fields. Saudi Aramco and ADNOC are expanding maximum sustainable capacity targets that drive artificial lift and enhanced oil recovery procurement.
- Processors:Gas treatment and fractionation facilities removing contaminants and separating NGL streams. US Gulf Coast gas processors are expanding cryogenic capacity to handle associated gas growth from Permian oil production.
- Distributors:Wholesale marketers and retail network operators managing product logistics to end consumers. Colonial Pipeline's operational disruption demonstrated concentration risk in East Coast refined product distribution.
Production firms anchor the volume base while exploration companies gain share fastest.
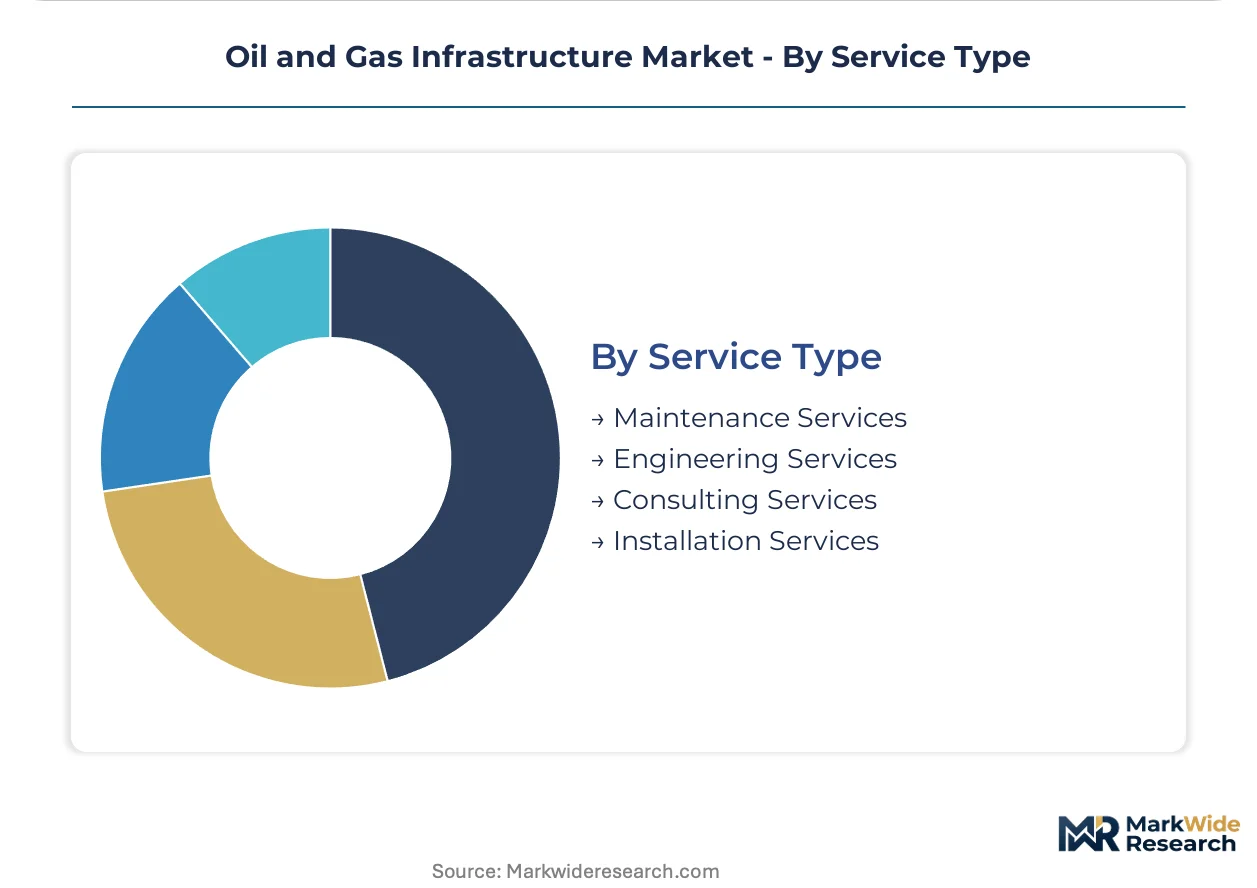
Service Type:
Service segmentation distinguishes between recurring operational expenditure and discrete capital project delivery, with maintenance services generating the most predictable revenue streams and installation services exhibiting the highest cyclical amplitude.
- Maintenance Services:Inspection, repair, and asset integrity programs sustaining operational availability. API 653 tank inspection intervals and DOT pipeline integrity management requirements create mandated demand visibility.
- Engineering Services:Front-end engineering design, project management, and construction oversight for greenfield developments. Bechtel and Fluor compete for LNG liquefaction EPC contracts where execution certainty determines award outcomes.
- Consulting Services:Reservoir characterization, regulatory compliance advisory, and digital transformation strategy. EU methane import disclosure requirements are expanding emissions accounting advisory mandates.
- Installation Services:Subsea construction, platform integration, and pipeline laying for capital projects. Saipem and TechnipFMC vessel fleets face utilization pressure from deepwater project sanction delays.
Maintenance services anchor the volume base while installation services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast pipeline network anchors North American hydrocarbon logistics, moving Permian production to export terminals and petrochemical complexes. European LNG import capacity expansion reshapes Atlantic basin gas flows. Middle Eastern liquefaction megaprojects concentrate engineering procurement contracts.
United States
Permian Basin takeaway capacity constraints drive pipeline reversals and greenfield builds toward Corpus Christi and Houston. EPA methane performance standards under the Clean Air Act mandate LDAR programs across Texas and Louisiana transmission networks. The Houston Ship Channel petrochemical corridor absorbs record ethane volumes from Appalachian and Permian shale plays.
Brazil
Pre-salt field development in the Santos Basin sustains subsea production system demand. Petrobras local content requirements reshape contractor supply chains for floating production units. The Rio de Janeiro technology cluster houses specialized engineering centers serving Campos and Santos basin developments.
Qatar
North Field expansion phases drive liquefaction train procurement and offshore compression platform awards. QatarEnergy shipping requirements reshape LNG carrier contracting toward long-term charter structures. Ras Laffan Industrial City concentrates megaproject execution for 126 mtpa of additional export capacity.
Germany
Industrial gas demand and phase-out of Russian pipeline imports accelerate LNG terminal deployment at Wilhelmshaven and Brunsbüttel. EU methane import standards under the Green Deal impose disclosure obligations on suppliers seeking German market access. The Ruhr industrial corridor evaluates hydrogen pipeline retrofits for steel and chemical sector decarbonization.
Australia
Scarborough and Barossa gas developments sustain offshore construction demand despite capital discipline pressures. Baseload liquefaction facilities face refrigerant constraints under F-Gas Regulation phase-down schedules. The Karratha gas hub processes Northwest Shelf and Pluto train volumes for Asian LNG offtake.
Oil and Gas Infrastructure Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies between full-cycle engineering procurement construction houses and discrete equipment fabricators. Three archetypes dominate: integrated project developers, subsea installation specialists, and digital subsurface platform providers. Competitive moves concentrate on liquefaction execution partnerships and carbon capture integration capabilities.
Among European-based EPC contractors, Technip Energies NV and Saipem SpA occupy positions at the liquefaction and subsea installation poles respectively. Schlumberger NV anchors the digital subsurface tier through integrated reservoir characterization platforms. These three entities exemplify the divergence between project execution scale and technology-enabled service delivery.
| Leading Market Players |
|---|
| Technip Energies NV |
| Saipem SpA |
| Schlumberger NV |
| Halliburton Co |
| Baker Hughes Company |
| McDermott International Ltd |
| TechnipFMC plc |
| Bechtel Corporation |
| Enbridge Inc |
| Others |
Supply Flow & Price Mechanics
Houston Ship Channel freight corridors compress delivered equipment costs for Gulf Coast LNG terminals while amplifying price spreads between integrated EPC providers and specialized component fabricators. Supply concentration in Japanese and Korean shipyards for offshore construction vessels tightens charter rate negotiations, forcing project developers to accept premium pricing or absorb schedule risk through early commitment deposits.
Pricing Analysis
Volume-discount tiering structures separate full-cycle EPC contractors from modular equipment suppliers and maintenance service providers. Pricing stratifies across premium, standard, and economy tiers based on certification grade (API 2SK, ISO 13628) and after-sales service bundling. Cost compression in standard-tier pipeline steel is intensifying because integrated mill capacity allocation favors higher-margin aerospace and automotive grades. Exploration companies exhibit the highest price sensitivity due to commodity-linked capital budgets, while national oil companies prioritize execution certainty over unit cost minimization.
Supply Chain Analysis
Export-control regimes limiting subsea production system technology flows constrain vendor qualification for frontier basin developments. Manufacturing concentrates in South Korea, Singapore, and Norway for high-specification offshore vessels and subsea trees. Supply chains draw from German and Japanese steel mills for high-pressure pipeline grades, Italian valve and compressor specialists, and Chinese fabrication yards for structural modules. Single-source vulnerability persists for hyperbaric welding certification capacity. Distribution runs through EPC prime contractors that aggregate discrete equipment packages into integrated project deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture retrofit mandates and EU methane import standards are disrupting conventional infrastructure economics, creating asymmetric opportunity windows for technology-enabled service providers and low-carbon equipment specialists.
For Market Incumbents: Insulate core liquefaction and subsea installation franchises through backward integration into modular fabrication capacity and exclusive teaming agreements with national oil companies. Lock in long-term charter commitments for specialized vessel fleets before shipyard slot scarcity intensifies. Prioritize API and ISO certification maintenance as regulatory divergence fragments equipment acceptance criteria across Atlantic and Pacific basin markets. For New Entrants and Emerging Players: Pursue stranded gas monetization opportunities in East Africa and Southeast Asia through small-scale LNG and modular gas-to-power solutions where megaproject economics fail. Target carbon capture integration services for existing gas processing trains in the US Gulf Coast petrochemical corridor. Lead with 45Q tax credit structuring expertise as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated energy majors divesting non-core midstream and oilfield services assets to focus on low-carbon hydrogen and renewables portfolios. Position for infrastructure fund consolidation plays where take-or-pay contracted pipelines offer yield stability. Watch EPA methane rule enforcement intensity and EU carbon border adjustment mechanism coverage expansion as inflection indicators for capital rotation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Post-combustion capture on gas processing trains unlocks 45Q credits for blue hydrogen offtakers. |
| Modular Liquefaction Deployment | Small-scale LNG solutions monetize stranded reserves in East Africa where megaproject economics fail. |
| Subsea Digital Twin Implementation | Predictive maintenance platforms displace time-based inspection cycles for Santos Basin pre-salt assets. |
| Methane LDAR Technology Scale-Up | Continuous monitoring systems satisfy EPA Clean Air Act obligations across Texas transmission networks. |
| Long-Term Vessel Charter Structuring | QatarEnergy shipping requirements reshape LNG carrier contracting toward 20-year charter commitments. |
Methodological Framework
A spread of perspectives from EPC project directors, national oil company procurement leads, infrastructure fund investment officers, and subsea equipment engineering managers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through FERC rate case filings, EIA pipeline capacity databases, SEC 10-K disclosures from listed contractors, and IEA LNG trade flow statistics. Bottom-up project sanction tracking triangulated against top-down capital expenditure forecasts from integrated energy company guidance.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning upstream-midstream-downstream categories, drilling-pipeline-refining-transportation technologies, and maintenance-engineering-consulting-installation service types. CAGRs derived from project-level capital commitment timelines and equipment procurement cycle analysis. Forecast inputs incorporated EPA methane rule implementation schedules and EU Green Deal methane import standard phase-in assumptions.
Sensitivities concentrate around commodity price volatility, shipyard slot availability for specialized vessels, and regulatory enforcement intensity divergence between US and EU jurisdictions. Forecasts reflect documented assumptions on project sanction rates and contractor capacity utilization. Material shifts in LNG demand destruction from European industrial load loss or accelerated transport electrification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Well Completion Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Planned LNG Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Dissolvable Frac Plug Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Well Cementing Market
Oil & Gas
Seismic Survey Equipment Market