
 Digital Oilfield Market | 2026-2036
Digital Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Oilfield Market Analysis
EPA methane performance standards for new and modified oil and gas facilities is hardening compliance costs for operators without continuous monitoring infrastructure. SLB leverages its integrated drilling and production software portfolio to anchor digital transformation contracts across Permian Basin assets. Halliburton sustains competitive position through proprietary edge-computing platforms that process subsurface data at the wellsite. Baker Hughes Company differentiates via turbine-to-tip digital twins that span LNG and upstream applications.
Digital oilfield denotes the application of advanced instrumentation, real-time data acquisition systems, and predictive analytics to hydrocarbon exploration and production operations, typically integrating distributed sensor networks sampling at millisecond intervals with centralized visualization platforms. The primary purpose is maximizing recovery rates while minimizing non-productive time and operational safety incidents. IoT sensor networks and AI-based predictive maintenance represent the fastest-expanding technology layers, with cloud computing migration accelerating as operators seek to reduce on-premises infrastructure capital. Production optimization applications currently command the largest share of deployed capital, though environmental monitoring is gaining share as regulatory disclosure obligations expand.
EPA rules, EU Methane Regulation, and BSEE well control standards collectively mandate emissions transparency and real-time pressure monitoring that only digital architectures can deliver cost-effectively. OSHA process safety management requirements further reinforce demand for automated anomaly detection in hazardous production environments. Stakeholders must weigh cloud dependency risks against the operational agility that hybrid deployment models offer as geopolitical data-localization pressures intensify.
Market Dynamics
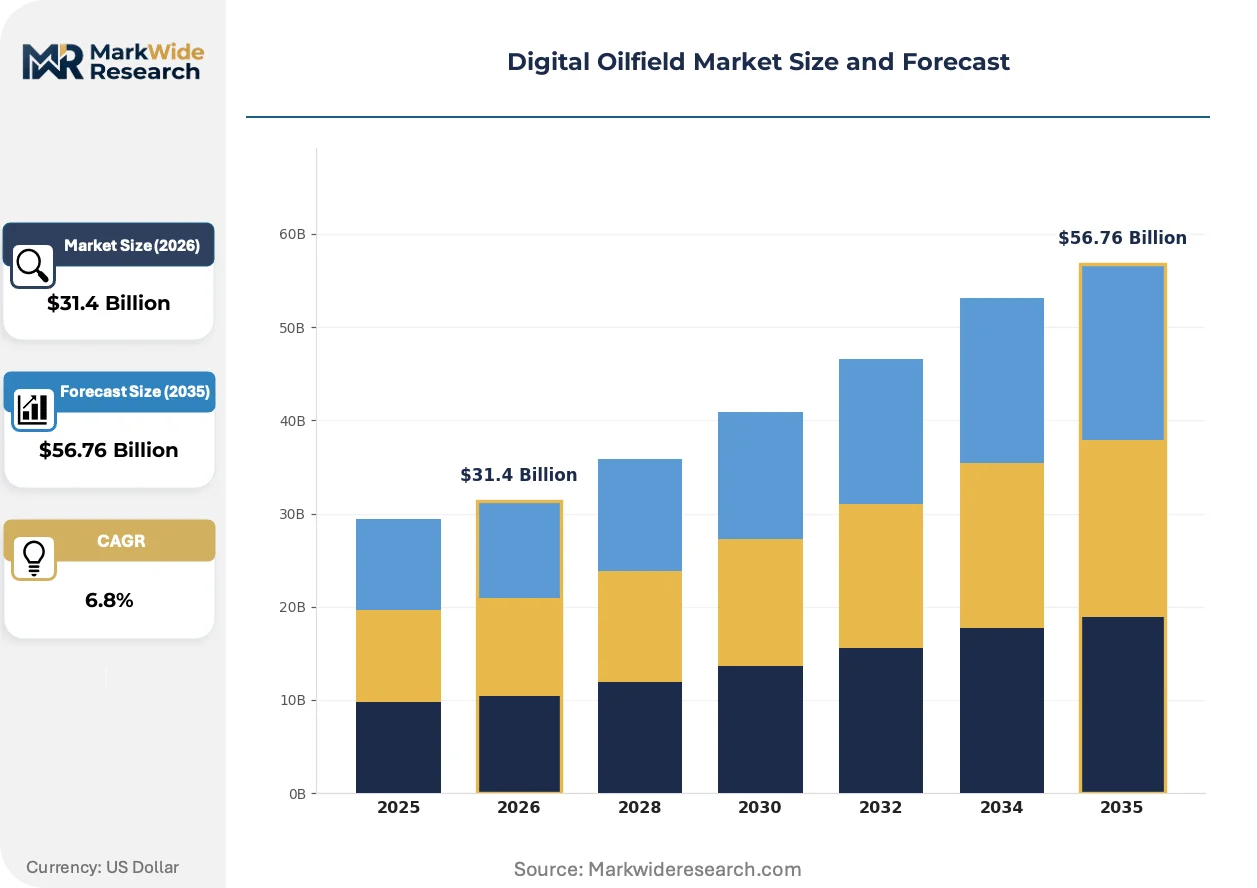
Cloud migration is compressing capital requirements for real-time reservoir monitoring while EPA methane rules and EU Methane Regulation harden compliance architectures that only continuous sensor networks can satisfy cost-effectively.
Growth Catalysts
- EPA Methane Performance Standards:Mandates for new and modified facilities drive continuous emissions monitoring deployment across Permian Basin and Gulf of Mexico assets.
- Edge computing platforms:Wellsite data processing capabilities eliminate latency for directional drilling corrections and pressure management decisions.
- Norway's North Sea cluster:Integrated operations centers standardize vendor specifications, creating template demand for unified SCADA and visualization layers.
Market Restraints
- Specialized sensor supply concentration:High-temperature downhole pressure transducers rely on limited semiconductor foundry capacity concentrated in East Asia.
- Cyber insurance cost escalation:Ransomware exposure on connected OT networks pushes premiums beyond mid-tier operator opex tolerance.
- Legacy SCADA protocol fragmentation:Proprietary Modbus and OPC-DA implementations resist seamless cloud integration without expensive middleware layers.
Strategic Opportunities
- Brazil pre-salt developments:Deepwater projects lack mature digital infrastructure, creating first-mover advantage for integrated platform providers.
- AI-driven predictive maintenance:Convergence of physics-based models with machine learning anomaly detection opens subscription revenue streams.
- EU CSRD disclosure mandates:Scope 3 emissions tracking requirements force supply chain visibility investments that digital oilfield architectures uniquely address.
Industry Challenges
- Petroleum data science talent scarcity:Hybrid skill sets combining subsurface engineering with Python and cloud architecture command premium compensation that strains operator budgets.
- OT-IT security boundary management:Segregating process control networks from corporate IT while enabling bi-directional data flows requires architectural complexity that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Oilfield Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Data Analytics Application: Asset Management, Production Optimization, Drilling Automation, Environmental Monitoring End User: Oil & Gas Companies, Service Providers, Equipment Manufacturers, Consultants Deployment Model: On-Premises, Cloud-Based, Hybrid Solution, Managed Services |
| Companies Covered | SLB, Halliburton, Baker Hughes Company, Weatherford, NOV Inc., Emerson Electric Co., Siemens, Schneider Electric SE, Pason Systems Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Oilfield Market Emerging Trajectories
Digital twin architectures are migrating from equipment-centric models to full-field reservoir simulations, compressing the feedback loop between geological interpretation and production engineering decisions.
Digital twin technology is expanding into full-asset lifecycle management, integrating subsurface models with surface facility performance data. Supermajors and national oil companies in the North Sea and Gulf of Mexico deploy these unified environments for scenario planning and debottlenecking. The technology is expanding into procurement specifications, with integrated operations tenders now requiring vendor interoperability with operator-specific twin platforms.
EU Methane Regulation enforcement timelines are hardening measurement, reporting, and verification obligations for upstream methane leaks. Satellite-based detection mandates and quarterly facility-level disclosure requirements force continuous monitoring retrofits on legacy infrastructure. Offshore operators in Norwegian and UK waters face the steepest compliance ramps due to remote platform access constraints and harsh environment sensor reliability demands.
Integrated service contracts are displacing discrete software licensing as the dominant commercial model. Operators bundle drilling analytics, production optimization, and emissions monitoring under single-vendor accountability frameworks with uptime guarantees. This restructuring concentrates most visibly in US unconventional plays where capital efficiency pressures favor operational expenditure models over perpetual license purchases.
Digital Oilfield Market Segmentation
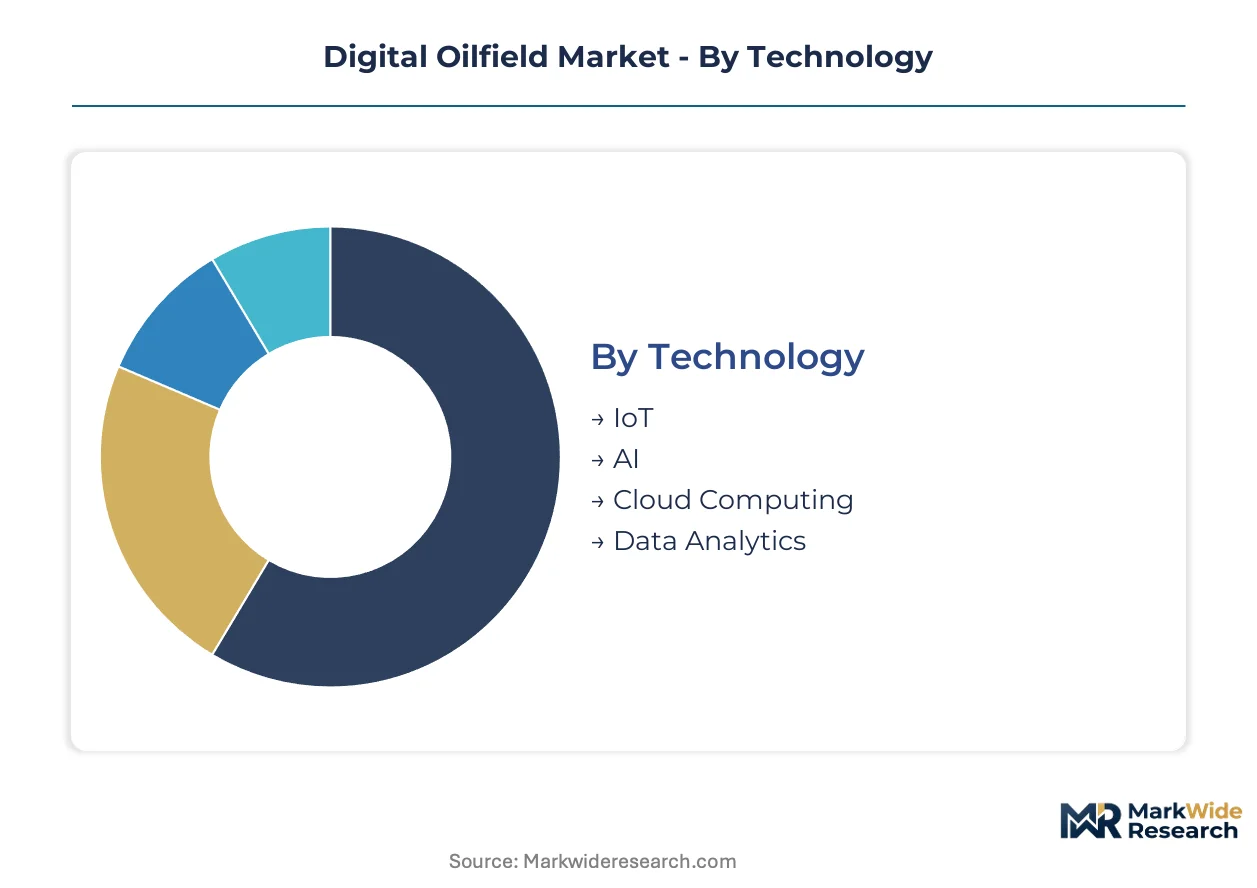
Segmentation in digital oilfield markets reveals how technology investment priorities diverge between capital-constrained independents and integrated majors with centralized innovation budgets. Deployment architecture choices increasingly separate operators capable of cloud migration from those tethered to legacy SCADA infrastructure.
Technology:
Investment intensity varies sharply by whether operators prioritize real-time latency reduction or long-cycle predictive capability.
- IoT:Distributed sensor networks sampling at millisecond intervals feed centralized visualization platforms. Permian Basin operators deploy these most aggressively to satisfy EPA methane performance standards for continuous emissions monitoring.
- AI:Machine learning models trained on historical drilling data predict stuck-pipe incidents and optimize rate-of-penetration. North Sea integrated operations centers standardize AI procurement specifications, creating template demand across Norway's offshore cluster.
- Cloud Computing:Migration from on-premises infrastructure reduces capital requirements for real-time reservoir monitoring. Mid-tier operators face cloud dependency risks as geopolitical data-localization pressures intensify.
- Data Analytics:Physics-based models combined with statistical anomaly detection compress feedback loops between geological interpretation and production engineering decisions.
IoT leads volumes today; AI is gaining share fastest.
Application:
Regulatory exposure determines whether operators fund environmental layers or prioritize production-centric systems first.
- Asset Management:Digital twin architectures integrate subsurface models with surface facility performance data for scenario planning. Gulf of Mexico supermajors deploy unified environments for debottlenecking across turbine-to-tip operations.
- Production Optimization:Real-time drilling analytics and reservoir simulation software command the largest deployed capital share. SLB anchors transformation contracts across Permian Basin assets with integrated drilling and production portfolios.
- Drilling Automation:Edge-computing platforms process directional drilling corrections at the wellsite without latency penalties. Halliburton sustains position through proprietary wellsite data processing capabilities.
- Environmental Monitoring:Continuous sensor networks satisfy EU Methane Regulation measurement, reporting, and verification obligations. Satellite-based detection mandates force retrofits on legacy offshore infrastructure with harsh-environment reliability demands.
Production Optimization dominates capital allocation currently; Environmental Monitoring is expanding most quickly.
End User:
Procurement authority concentrates differently depending on whether digital transformation is driven from engineering, IT, or procurement functions.
- Oil & Gas Companies:Integrated service contracts displace discrete software licensing as capital efficiency pressures favor operational expenditure models. Operators bundle drilling analytics, production optimization, and emissions monitoring under single-vendor accountability frameworks.
- Service Providers:Edge-computing and wellsite data processing capabilities differentiate competitive positioning in directional drilling markets. Proprietary platforms command premium pricing where latency elimination justifies investment.
- Equipment Manufacturers:Turbine-to-tip digital twins span LNG and upstream applications, with procurement specifications increasingly requiring vendor interoperability with operator-specific twin platforms.
- Consultants:Petroleum data science talent scarcity strains budgets as hybrid skill sets combining subsurface engineering with Python and cloud architecture command premium compensation.
Oil & Gas Companies represent the dominant procurement authority; Service Providers are capturing share fastest through integrated contracting models.
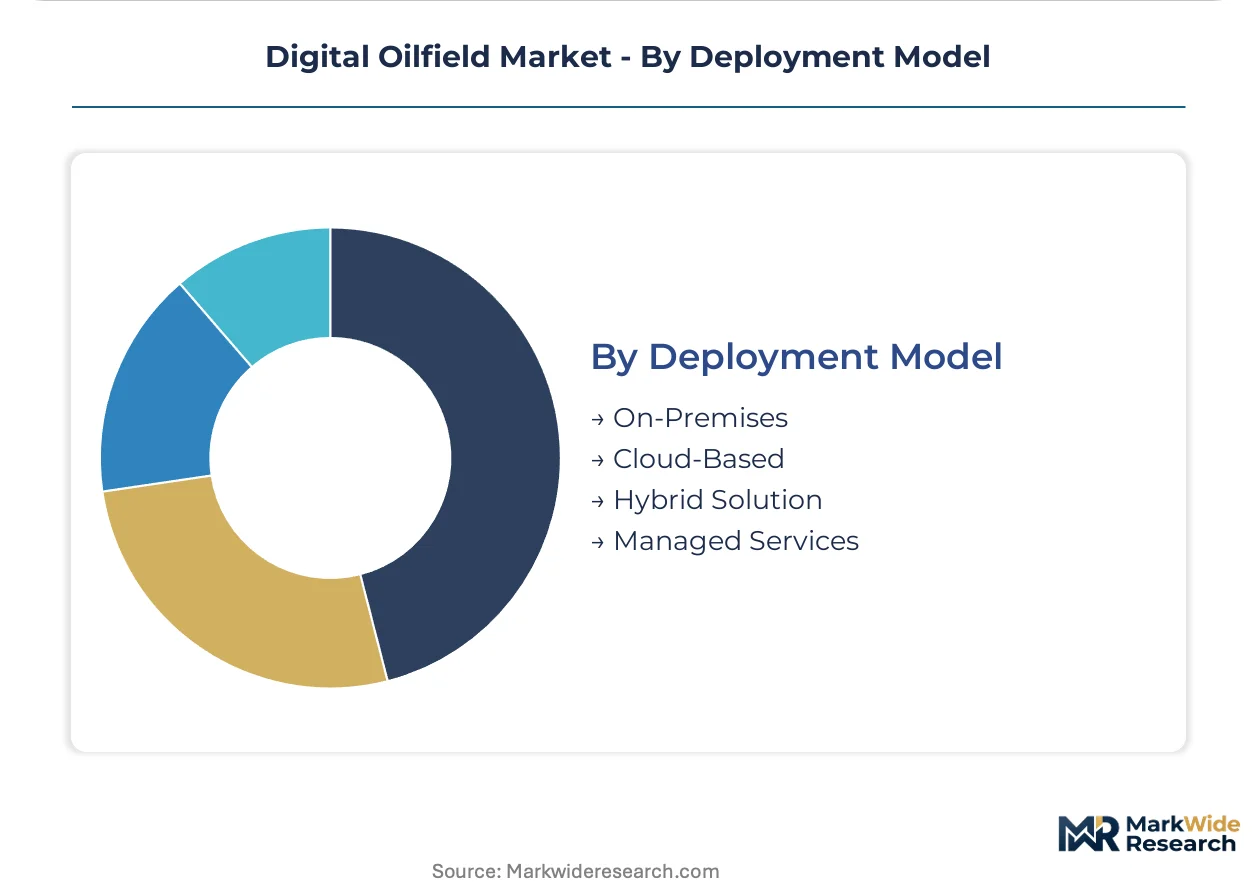
Deployment Model:
Security architecture requirements separate operators with mature OT-IT boundary management from those delaying cloud migration due to ransomware exposure.
- On-Premises:Legacy SCADA protocol fragmentation resists seamless integration without expensive middleware layers. Proprietary Modbus and OPC-DA implementations persist where air-gapped security remains non-negotiable.
- Cloud-Based:Migration accelerates as operators seek infrastructure capital reduction, though cyber insurance cost escalation on connected OT networks pushes premiums beyond mid-tier operator tolerance.
- Hybrid Solution:Segregating process control networks from corporate IT while enabling bi-directional data flows requires architectural complexity that delays deployment timelines but satisfies security-conscious majors.
- Managed Services:Uptime guarantees and single-vendor accountability frameworks concentrate in US unconventional plays where operational expenditure models displace perpetual license purchases.
On-Premises retains installed base dominance; Hybrid Solution is climbing the fastest as security-conscious operators seek middle ground.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital oilfield architectures first achieved commercial scale in North Sea integrated operations centers during the early 2000s, establishing templates later exported to Gulf of Mexico deepwater assets and Middle East megaprojects. This historical lineage shapes current procurement patterns and regulatory compliance frameworks across producing regions.
United States
EPA methane performance standards for new and modified facilities mandate continuous emissions monitoring across Permian Basin unconventional assets. OSHA process safety management requirements reinforce demand for automated anomaly detection in hazardous production environments. Houston anchors vendor ecosystem concentration, with integrated service contracts displacing discrete software licensing as capital efficiency pressures favor operational expenditure models.
Norway
Integrated operations centers standardize vendor specifications across the North Sea cluster, creating template demand for unified SCADA and visualization layers. EU Methane Regulation enforcement timelines harden measurement, reporting, and verification obligations for upstream methane leaks. Stavanger and Bergen host supermajor digital transformation procurement headquarters, with satellite-based detection mandates forcing retrofits on legacy offshore infrastructure.
United Kingdom
North Sea decommissioning timelines accelerate digital twin deployment for asset lifecycle optimization and scenario planning. BSEE well control standards influence UK Continental Shelf regulatory alignment through technical cooperation frameworks. Aberdeen concentrates petroleum data science talent scarcity strains, where hybrid skill sets combining subsurface engineering with Python and cloud architecture command premium compensation.
Brazil
Pre-salt deepwater developments lack mature digital infrastructure, creating first-mover advantage for integrated platform providers in directional drilling and production optimization. ANVISA regulatory frameworks for offshore equipment certification intersect with national content requirements shaping vendor selection. Rio de Janeiro anchors national oil company procurement authority, with integrated service contracts bundling drilling analytics and emissions monitoring under single-vendor accountability frameworks.
Saudi Arabia
Aramco megaproject specifications drive turbine-to-tip digital twin adoption across LNG and upstream applications, with procurement increasingly requiring vendor interoperability with operator-specific twin platforms. SFDA regulatory alignment with international standards facilitates technology import from North Sea and Gulf of Mexico templates. Dhahran concentrates equipment manufacturer regional headquarters, where cloud migration accelerates despite geopolitical data-localization pressures.
Digital Oilfield Market Vendor Landscape
The competitive structure tilts toward integrated technology-service hybrids rather than pure-play software vendors. Three tiers separate full-field solution providers from equipment-centric specialists and emerging AI-native entrants. Dominant competitive moves include integrated service contract restructuring with uptime guarantees and edge-computing platform development to eliminate latency for wellsite decisions.
Within the integrated technology-service tier, SLB, Halliburton, and Baker Hughes Company anchor competitive positioning through differentiated proprietary architectures. SLB occupies a position exemplifying integrated drilling and production software portfolio consolidation. Halliburton represents the edge-computing specialist archetype with wellsite data processing capabilities. Baker Hughes Company anchors the turbine-to-tip digital twin segment spanning LNG and upstream applications.
| Leading Market Players |
|---|
| SLB |
| Halliburton |
| Baker Hughes Company |
| Weatherford |
| NOV Inc. |
| Emerson Electric Co. |
| Siemens |
| Schneider Electric SE |
| Pason Systems Corp. |
| Others |
Supply Flow & Price Mechanics
Captive sensor manufacturing in East Asian foundries anchors both supply security and pricing leverage for high-temperature downhole transducers, while integrated service bundling in the Permian Basin compresses margins for discrete software vendors competing against SLB and Halliburton's operational expenditure models.
Pricing Analysis
Service bundling versus unbundled software licensing splits the market into two distinct pricing architectures. Subscription-based integrated service contracts dominate US unconventional plays, with price differentiation driven by uptime guarantee tiers and edge-computing latency specifications. Cost compression in environmental monitoring tiers intensifies as EU Methane Regulation deadlines force rapid deployment of satellite-verified sensor networks. Mid-tier independents exhibit highest price sensitivity, while supermajors prioritize performance guarantees over per-unit costs.
Supply Chain Analysis
Regional distribution centers in Houston, Stavanger, and Singapore coordinate hub-and-spoke patterns for critical sensing equipment. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan for high-temperature pressure transducers. Raw material dependencies span silicon carbide substrates, specialty ceramics, and fiber-optic cabling. Single-source vulnerability in East Asian foundry capacity exposes lead times to geopolitical disruption. Distribution runs through oilfield service company logistics networks rather than independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital oilfield functions as a geographic-arbitrage play where EPA methane compliance costs in US unconventional basins run substantially higher than Norway's integrated operations center efficiencies, creating divergent vendor margin structures across the Atlantic.
For Market Incumbents: Anticipate margin compression from AI-native entrants targeting predictive maintenance subscriptions by hardening proprietary edge-computing platforms and securing captive semiconductor supply through foundry partnerships. Vertical integration into high-temperature sensor manufacturing reduces exposure to East Asian supply concentration risks. For New Entrants and Emerging Players: Capture white-space in Brazil pre-salt digital infrastructure where integrated platform providers lack entrenched relationships, and in mid-tier operator environmental monitoring retrofits where cyber insurance costs have driven incumbents toward managed service models. A cloud-native, API-first architecture with rapid deployment timelines offers the strongest go-to-market angle against legacy SCADA integration burdens. For Investors and Strategic Acquirers: Roll-up economics work for petroleum data science consultancies because talent scarcity has fragmented the market into sub-scale regional players unable to compete for integrated operations center contracts. The five-to-ten year viability window favors platforms with proven OT-IT security boundary architectures. Watch for inflection when EU CSRD Scope 3 disclosure mandates force supply chain visibility investments that digital oilfield architectures uniquely address.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Platform Development | Halliburton's proprietary wellsite processing eliminates latency for directional drilling corrections. |
| Digital Twin Integration | Baker Hughes spans turbine-to-tip LNG and upstream applications through unified simulation environments. |
| Integrated Service Contract Restructuring | SLB anchors Permian Basin transformation contracts with bundled drilling and production portfolios. |
| Emissions Monitoring Retrofit Programs | EU Methane Regulation deadlines force continuous sensor deployment on legacy offshore infrastructure. |
| Petroleum Data Science Talent Acquisition | Hybrid subsurface engineering and Python skill sets command premium compensation that strains operator budgets. |
Methodological Framework
Bottom-up operator deployment modeling reconciled against top-down vendor contract tracking forms the analytical core of this study. Primary interviews with drilling engineers, IT/OT integration specialists, procurement officers at national oil companies, and emissions compliance managers combined with secondary validation from SEC filings, BSEE well control incident databases, EPA enforcement records, and EU Methane Regulation implementation guidance. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map technology adoption rates against regulatory compliance timelines and capital expenditure cycles across the projection horizon. Segmentation dimensions include deployment architecture, application layer, end-user procurement authority, and regional regulatory framework. CAGRs derive from fitted adoption curves weighted by operator size distribution and project backlog visibility. Forecast inputs incorporate sensor network deployment density and cloud migration velocity specific to offshore versus onshore asset profiles.
Regulatory enforcement delays, semiconductor supply disruptions, and cyber insurance market contraction are the dominant revision risks that could alter trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
Gold Mining Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Unconventional Gas Market
Oil & Gas
Coal Bed Methane Market