
 Romania Oil and Gas Upstream Market | 2026-2036
Romania Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Oil and Gas Upstream Market Analytics
Modular well completion packages are broadening operator choice across Romania's offshore and onshore fields. OMV Petrom SA leverages its integrated upstream-downstream footprint to sustain drilling activity across mature onshore concessions. Black Sea Oil & Gas anchors the Neptun Deep development, positioning Romania as a net gas exporter in the Black Sea region. Romgaz SA competes through its dominant position in conventional onshore production, extending operational reach into new deepwater partnerships.
Romania oil and gas upstream encompasses the exploration, drilling, and production of hydrocarbon reserves from onshore and offshore geological formations, utilizing directional drilling, hydraulic fracturing, and subsea tieback systems to extract crude oil, natural gas, and associated liquids for refining and power generation. Natural gas production testing commands priority investment as operators validate flow rates from high-pressure Black Sea reservoirs before committing full field development. Seismic survey technology leads capital allocation among exploration service segments, while drilling services capture the largest recurring revenue pool across the service type dimension as operators work through Romania's multi-year well backlog.
Romania's National Agency for Mineral Resources (NAMR) governs concession licensing and production-sharing agreements, while the National Regulatory Authority for Energy (ANRE) sets grid access and tariff frameworks that shape gas offtake economics for upstream producers. EU methane emissions regulations and the F-Gas Directive impose monitoring and leak detection standards that elevate compliance costs for offshore platform operations. Stakeholders must weigh the trade-off between Black Sea development timelines and onshore reserve rehabilitation as financing conditions and carbon pricing mechanisms reshape project economics.
Market Dynamics
Romania's upstream sector confronts tightening environmental compliance layered atop maturing onshore reserves and capital-intensive offshore development timelines. The National Agency for Mineral Resources has sharpened permitting scrutiny for Black Sea drilling, compressing operator margins while forcing faster adoption of emissions-monitoring infrastructure.
Growth Catalysts
- EU methane emissions regulations:Mandatory leak detection and repair protocols are accelerating investment in automated monitoring systems across offshore platforms, creating pull-through demand for sensor and analytics providers.
- Domestic power generation utilities:Grid-connected gas plants are absorbing larger contracted volumes as coal retirement schedules advance, anchoring offtake certainty for upstream producers.
- Directional drilling advances:Extended-reach horizontal wells are unlocking bypassed pay zones in mature Carpathian foreland basins, stretching economic field life without new concession awards.
Market Restraints
- Specialized offshore rig supply:Harsh-environment jack-up and semisubmersible availability concentrates among North Sea and Mediterranean contractors, inflating day rates for Black Sea campaigns.
- F-Gas Directive phase-down:Restrictions on high-global-warming-potential refrigerants and insulating gases are forcing platform HVAC and electrical system redesigns, extending engineering timelines.
- Carbon pricing exposure:EU ETS allowance costs are embedding into project economics, disadvantaging gas developments against lower-carbon alternatives in power sector procurement.
Strategic Opportunities
- Subsea tieback architectures:Satellite field developments linked to existing platform infrastructure are reducing standalone capex for marginal Black Sea discoveries, expanding the commercial reserve base.
- Decommissioning liability management:Stranded asset obligations on mature onshore concessions are creating service market openings for plug-and-abandonment specialists and site remediation contractors.
- Cross-border pipeline interconnectors:Bulgaria-Romania-Hungary corridor expansions are improving route-to-market flexibility, enabling producers to arbitrage regional hub price differentials.
Industry Challenges
- Deepwater geoscience expertise:High-pressure high-temperature reservoir characterization demands specialized petrophysical and geomechanical skill sets scarce in the domestic labor pool.
- Legacy onshore infrastructure integration:New digital wellsite automation systems must interface with decades-old SCADA architectures, multiplying commissioning complexity and cybersecurity exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Oil and Gas Upstream Market |
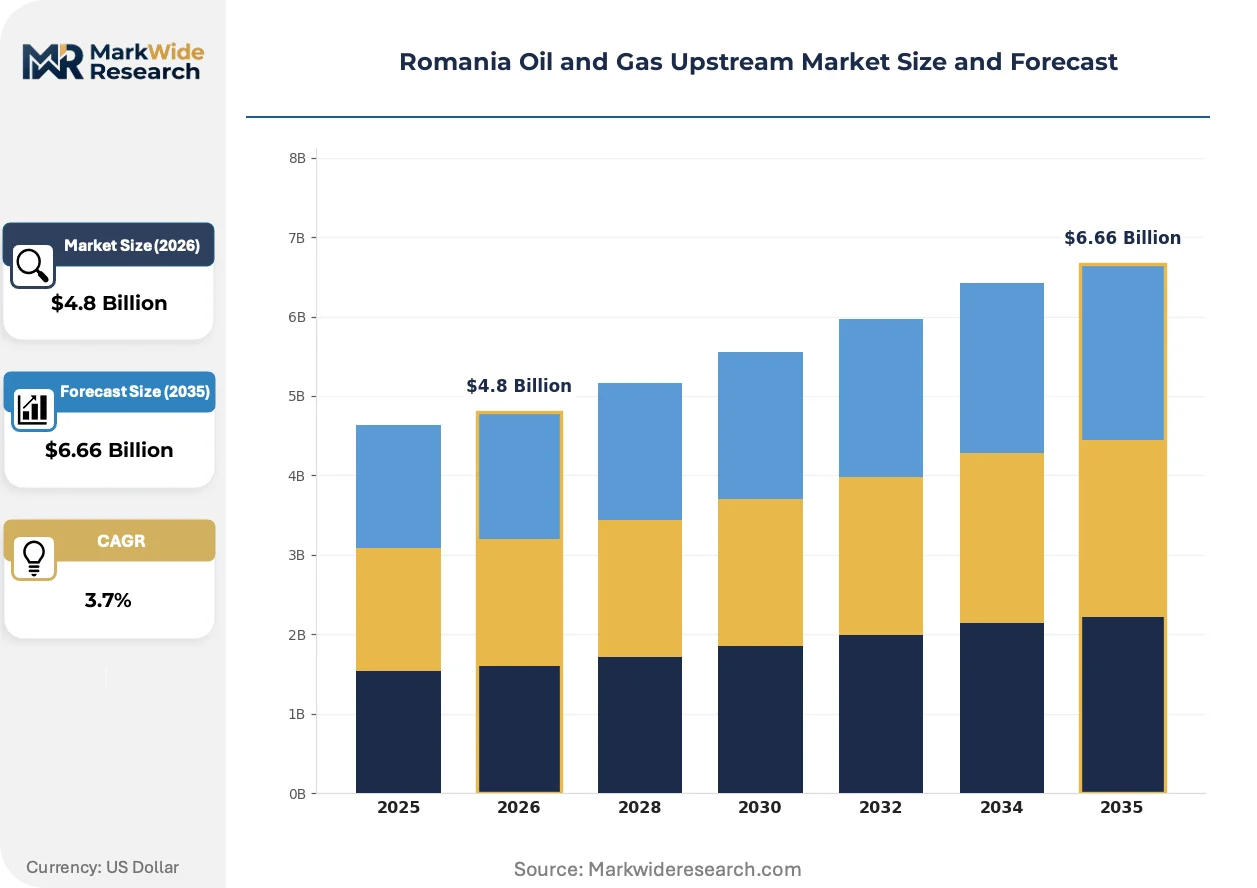
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Natural Gas Liquids, Refinery Feedstocks End User: Exploration Companies, Production Operators, Service Providers, Government Entities Technology: Seismic Survey, Drilling, Well Completion, Production Testing Service Type: Drilling Services, Engineering Services, Transportation Services, Maintenance Services |
| Companies Covered | Black Sea Oil & Gas, TotalEnergies, OMV Petrom SA, Petromar, Foraj Sonde SA Videle, Romgaz SA, Repsol, Sterling Resources, ExxonMobil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Oil and Gas Upstream Market Evolving Landscape
Digitalization and modular system architectures are compressing development timelines while regulatory stringency forces step-change improvements in emissions transparency. These forces are restructuring how operators contract services and deploy capital across Romania's offshore and onshore domains.
Subsea processing equipment is modularizing field development economics for marginal Black Sea discoveries. Operators are deploying standardized skid-mounted separation and compression units that slash fabrication lead times and enable batch procurement across multiple prospects. This approach is compressing the threshold reserve size required for commercial sanction, expanding the inventory of developable resources.
Romania's transposition of EU methane emissions regulations is imposing continuous monitoring mandates on offshore production facilities. The National Regulatory Authority for Energy is aligning grid access tariffs with certified low-leakage performance, creating direct revenue linkages to emissions intensity. Offshore platform operators are responding by retrofitting infrared camera networks and automated valve diagnostic systems to maintain tariff eligibility.
Integrated service contracting is displacing discrete equipment procurement as the dominant commercial model for drilling campaigns. Exploration and production companies are bundling directional drilling, logging-while-drilling, and managed pressure services under single-provider frameworks to transfer operational risk and compress management overhead. This pattern is most pronounced in Black Sea deepwater programs where technical complexity demands tighter contractor alignment.
Romania Oil and Gas Upstream Market Segmentation
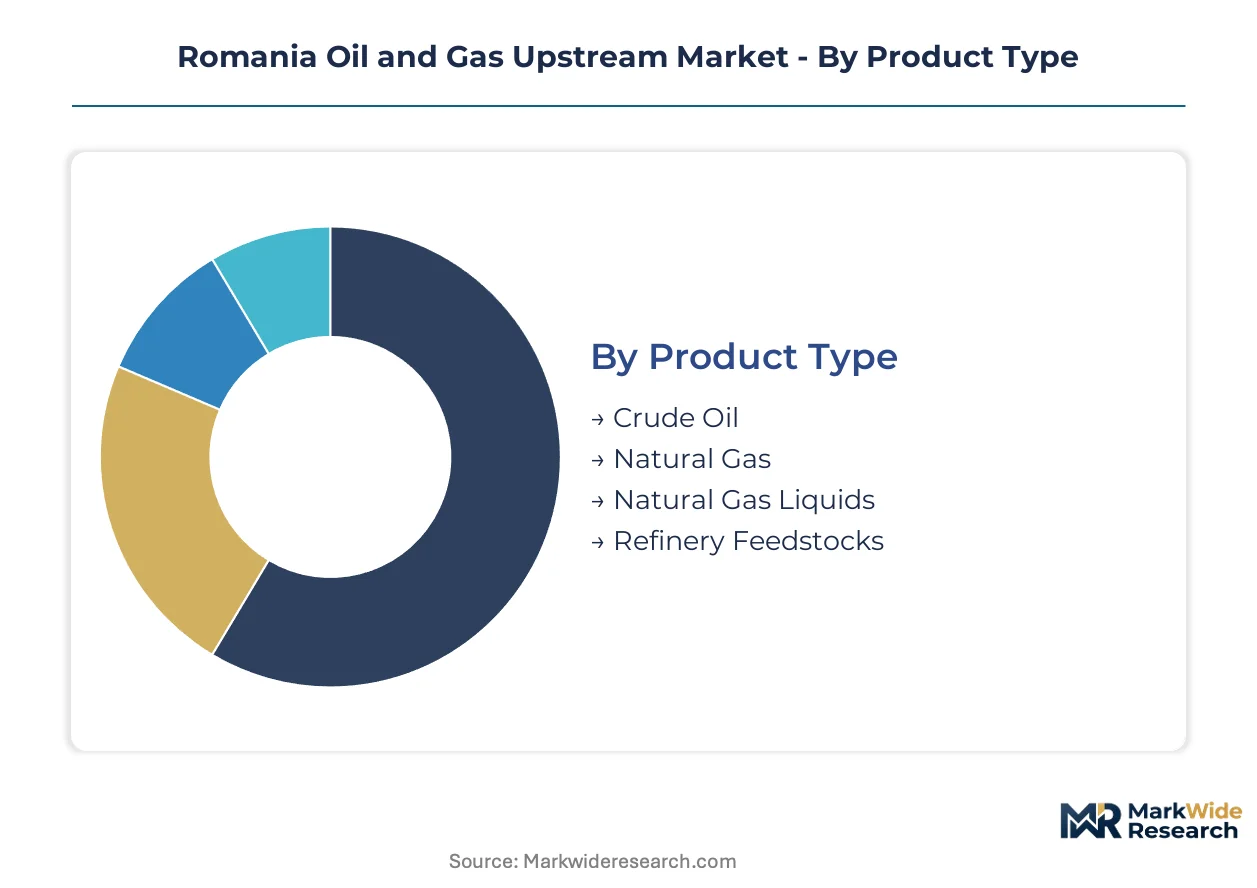
Romania's upstream market segments reflect divergent capital intensity and regulatory exposure across hydrocarbon types, operator categories, and technical service layers. Understanding these divisions clarifies where investment concentrates and which contracting models dominate procurement decisions.
Product Type:
Buyers differentiate by calorific value, sulfur content, and pipeline specification requirements that determine offtake routing and tariff treatment under ANRE frameworks.
- Crude Oil:Medium-sweet crude from onshore Ploiești and offshore Black Sea fields requires desulfurization before refining. Domestic refineries absorb most volumes, though export capacity via Constanta terminal is expanding. Carbon intensity tracking under EU ETS is elevating low-sulfur premiums.
- Natural Gas:High-calorific Black Sea gas dominates new production, with Neptune Deep and Ana-Doina fields feeding grid-connected power plants. Methane leakage certification now conditions grid access tariffs, forcing investment in continuous monitoring infrastructure.
- Natural Gas Liquids:Condensate and LPG fractions from wet gas processing serve petrochemical feedstock demand. Separation infrastructure at Midia terminal handles most volumes.
- Refinery Feedstocks:Heavy residues and naphtha streams bridge upstream production with OMV Petrom's Petrobrazi complex. Quality consistency determines term contract pricing.
Natural Gas leads volumes today; Natural Gas Liquids is gaining share fastest.
End User:
Procurement sophistication varies sharply by balance sheet depth and technical capability, dictating service contracting models and risk allocation terms.
- Exploration Companies:Junior operators and farm-in partners license blocks from NAMR, relying on seismic contractors and drilling management firms. Capital constraints favor turnkey exploration contracts over in-house technical teams.
- Production Operators:OMV Petrom, Romgaz, and Black Sea Oil & Gas control producing assets, absorbing the largest service procurement volumes. Integrated operators self-perform workovers while outsourcing directional drilling and subsea interventions.
- Service Providers:Schlumberger, Halliburton, and local drilling contractors purchase consumables, equipment leases, and logistics support. Their procurement aggregates demand across multiple operator clients.
- Government Entities:NAMR and state equity vehicles acquire technical advisory services and environmental monitoring systems. Public procurement rules extend tender timelines but anchor standards compliance.
Production Operators command the largest contract values; Exploration Companies show the steepest expansion trajectory as new Black Sea blocks advance to drill-ready status.
Technology:
Technology selection tracks reservoir depth, pressure regime, and environmental sensitivity, with offshore complexity driving premium service rates.
- Seismic Survey:3D and 4D ocean-bottom node acquisition dominates Black Sea exploration, with PGS and TGS vessels contracting for multi-client programs. Romania's transposition of EU environmental noise directives is lengthening permit timelines for marine seismic.
- Drilling:Extended-reach horizontal wells unlock Carpathian foreland bypassed pay, while high-pressure high-temperature drilling from jack-up rigs anchors Black Sea development. Rig availability constraints from North Sea competition inflate day rates.
- Well Completion:Modular intelligent completions with downhole pressure monitoring are standard for Black Sea producers. Sand control and hydraulic fracturing dominate onshore tight gas applications.
- Production Testing:Extended well tests validate flow rates and reservoir boundaries before field development sanction. High-rate gas testing commands priority investment given Black Sea reservoir uncertainties.
Drilling captures the largest recurring revenue pool; Production Testing is expanding most quickly as Neptune Deep validation campaigns accelerate.
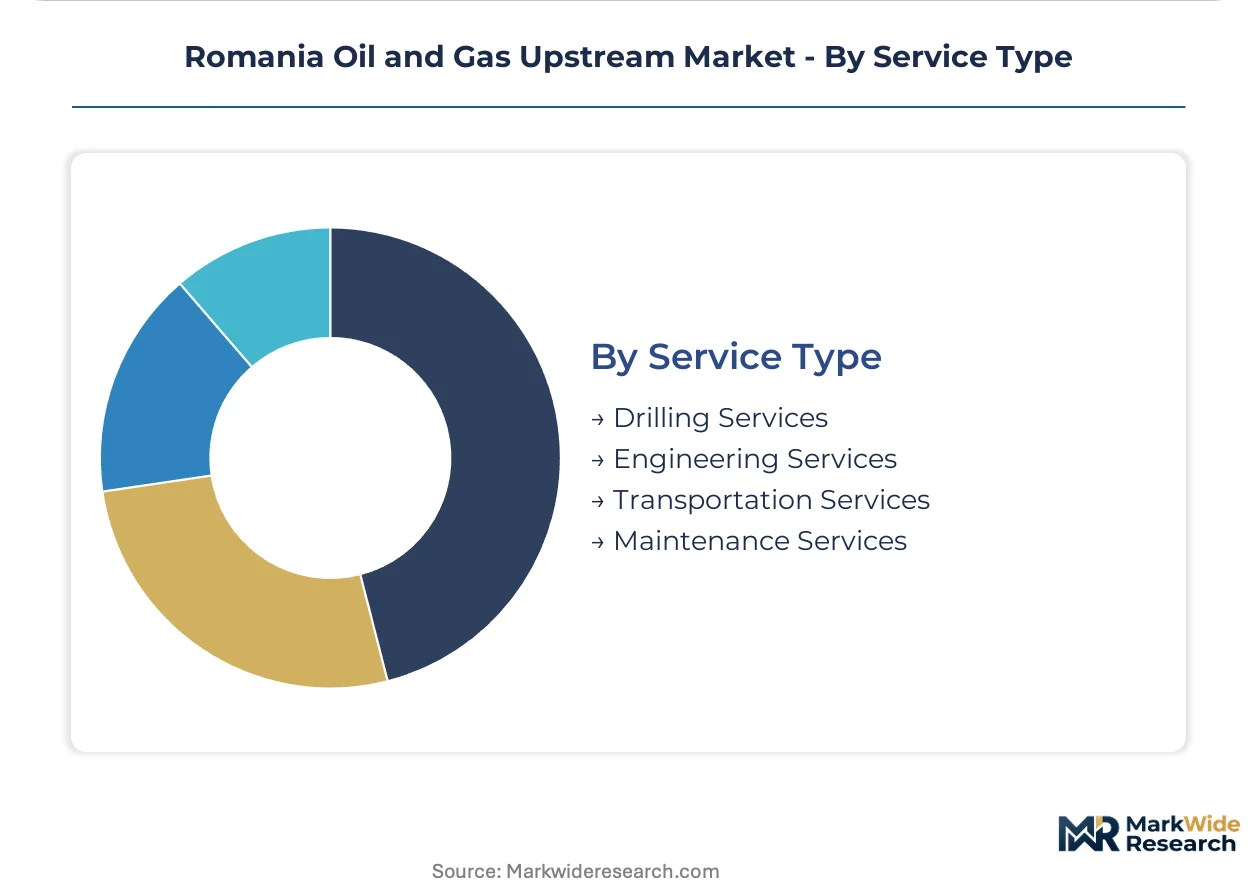
Service Type:
Service procurement is consolidating under integrated frameworks as operators transfer operational risk and compress management overhead.
- Drilling Services:Directional drilling, logging-while-drilling, and managed pressure drilling bundle under single-provider contracts. Black Sea deepwater programs demand tighter contractor alignment than onshore campaigns.
- Engineering Services:Subsea architecture design, platform modifications, and regulatory compliance documentation flow to Romanian engineering consultancies and international EPC firms. F-Gas Directive HVAC redesigns are extending project timelines.
- Transportation Services:Offshore supply vessel chartering, helicopter logistics, and pipeline pigging operations support production continuity. Constanta port infrastructure constraints limit heavy-lift mobilization capacity.
- Maintenance Services:Platform inspection, subsea intervention, and well workover programs sustain field productivity. EU methane monitoring mandates are retrofitting infrared camera networks and automated valve diagnostics.
Drilling Services dominates contract value; Maintenance Services is climbing the fastest as emissions compliance retrofits multiply service call volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania's oil and gas upstream sector traces its modern foundations to the Ploiești fields developed in the late 19th century, establishing one of Europe's earliest petroleum industries before Black Sea offshore exploration shifted investment gravity eastward toward deepwater frontiers.
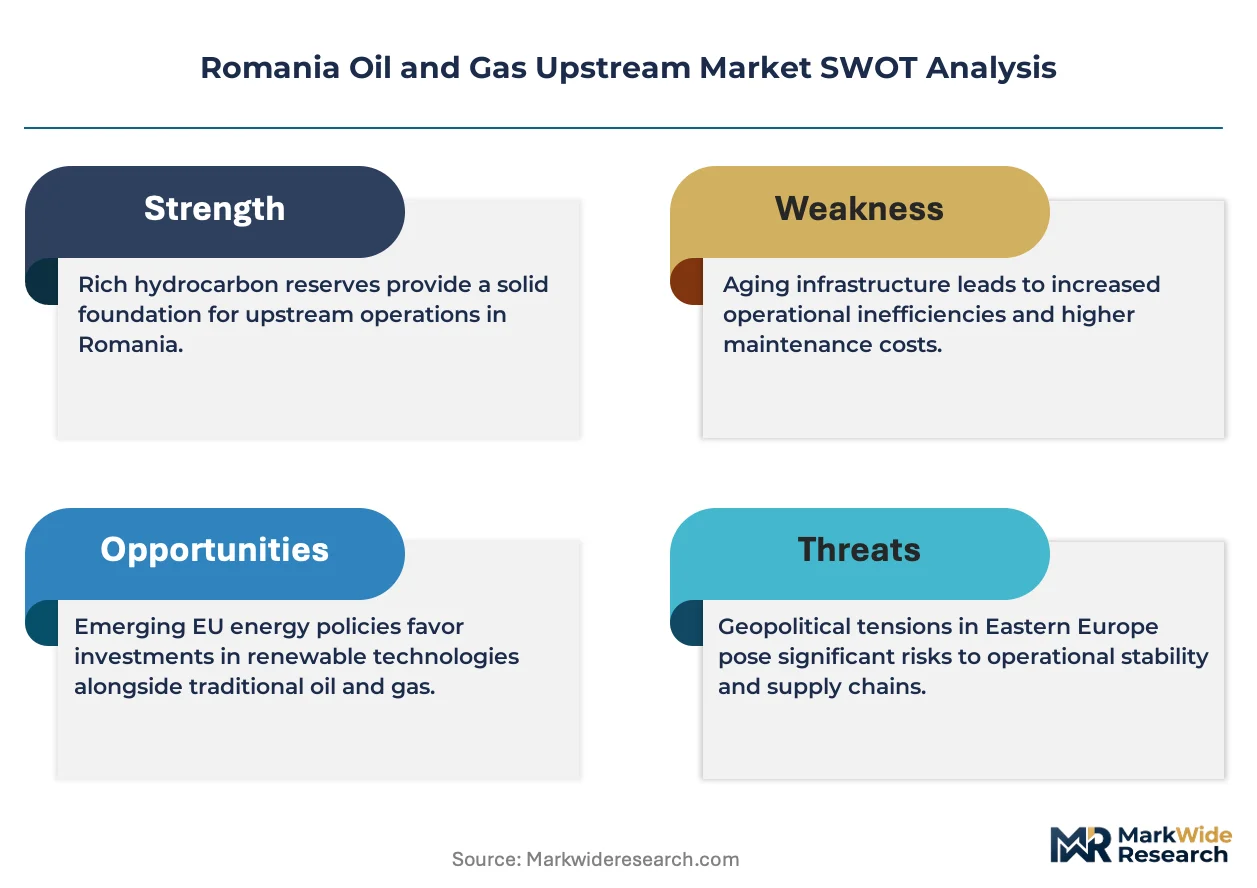
Black Sea Offshore Basin
Neptune Deep and Ana-Doina developments anchor production growth as domestic power utilities absorb larger contracted gas volumes. The National Agency for Mineral Resources has sharpened environmental permitting scrutiny, compressing operator margins while mandating faster emissions-monitoring infrastructure deployment. Midia terminal infrastructure handles separation and processing for wet gas streams feeding grid-connected plants.
Carpathian Foreland Onshore
Extended-reach horizontal wells unlock bypassed pay zones in mature Ploiești and Buzău concessions, stretching economic field life without new concession awards. OMV Petrom SA leverages integrated upstream-downstream footprints to sustain drilling activity across these legacy assets. Directional drilling advances are stretching wellbore lengths to access previously uneconomic reservoir compartments.
Western Moldavian Platform
Tight gas sandstone formations in this eastern province require hydraulic fracturing and sand control completions to sustain production rates. Romgaz SA maintains dominant conventional production positions here while extending operational reach into new deepwater partnerships. Well workover programs and artificial lift installations dominate service procurement in this mature basin.
Transylvanian Basin
Shallow oil and gas fields around Mediaș and Târgu Mureș face accelerating decommissioning liabilities as reserves deplete. Plug-and-abandonment specialists and site remediation contractors are capturing growing service volumes as operators retire marginal wells. The basin's pipeline network feeds regional refineries and petrochemical complexes.
Romania Oil and Gas Upstream Market Competitive Landscape
The competitive structure tilts toward integrated national champions with state equity participation and deep concession portfolios. Market concentration reflects high barriers to entry through NAMR licensing requirements and capital-intensive offshore development timelines. Two strategic archetypes dominate: vertically integrated operators controlling full value chains, and specialized offshore developers leveraging farm-in arrangements to share geological risk. Competitive moves center on portfolio diversification into Black Sea deepwater and strategic partnerships to spread development capex across multiple stakeholders.
Within the integrated operator tier, OMV Petrom SA and Romgaz SA anchor conventional onshore production while positioning for offshore growth through consortium structures. Black Sea Oil & Gas exemplifies the specialized developer archetype, concentrating capital on single-basin deepwater execution without downstream integration burdens. These three entities collectively shape service procurement patterns, drilling campaign scheduling, and infrastructure access negotiations across Romania's upstream value chain.
| Leading Market Players |
|---|
| Black Sea Oil & Gas |
| TotalEnergies |
| OMV Petrom SA |
| Petromar |
| Foraj Sonde SA Videle |
| Romgaz SA |
| Repsol |
| Sterling Resources |
| ExxonMobil |
| Others |
Value Network & Pricing Analysis
Platts JKM spot LNG benchmarks cascade through Romanian gas procurement contracts, compressing margins for offshore producers when European hub prices soften while amplifying pricing power for integrated operators with term offtake arrangements to domestic power utilities.
Pricing Analysis
Long-term take-or-pay contracts indexed to TTF and CEGH hubs dominate procurement between Black Sea producers and grid-connected utilities. Price differentiation hinges on methane intensity certification tiers under ANRE frameworks and delivery flexibility clauses. Cost compression in standard-grade supply intensifies as EU ETS allowance costs embed deeper into project economics. Exploration companies exhibit highest price sensitivity due to capital constraints, while integrated production operators absorb volatility through downstream refining margins.
Supply Chain Analysis
Freight costs for heavy-lift jack-up rigs from North Sea and Mediterranean yards inflate day rates for Black Sea drilling campaigns by 15-25% versus North Sea benchmarks. Equipment fabrication concentrates in Norway, Singapore, and UAE yards, while specialized HPHT drilling consumables draw from Houston and Aberdeen supply bases. Single-source vulnerability sits with harsh-environment semisubmersible availability, where global fleet utilization above 90% creates booking bottlenecks. Distribution runs through Constanta port infrastructure with pipeline interconnectors feeding Hungarian and Bulgarian offtake points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's upstream sector compounds steadily as Black Sea gas production anchors regional supply security, with domestic power generation utilities providing demand visibility that smooths investment cycles across volatile European energy markets.
For Market Incumbents: Deepen subsea tieback engineering capabilities to capture marginal field developments that expand commercial reserve bases without standalone platform capex. Secure early-mover positions in methane monitoring retrofit services as EU emissions regulations tighten tariff eligibility criteria. Consolidate directional drilling contractor relationships to lock in rig availability ahead of Neptune Deep expansion campaigns. For New Entrants and Emerging Players: EU methane emissions regulations in Romania open a window for specialized emissions monitoring and automated leak detection technology providers to penetrate offshore platform retrofit cycles. Target decommissioning liability management services in the Transylvanian Basin where well retirement obligations outstrip incumbent capacity. Pursue farm-in arrangements with NAMR license holders lacking deepwater execution experience as the lowest-friction entry path. For Investors and Strategic Acquirers: Asymmetric upside sits with subsea equipment specialists and emissions technology providers serving Black Sea development timelines. Long-term viability favors service companies with contracted visibility across multi-year drilling programs rather than speculative exploration exposure. Watch NAMR permitting velocity as the critical inflection signal—accelerated environmental approvals would compress project sanction timelines and revalue development-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Architecture Deployment | Reduces standalone capex for marginal Black Sea discoveries by linking satellite fields to existing Neptune Deep infrastructure. |
| Methane Monitoring Retrofit Program | Secures ANRE tariff eligibility for offshore producers under EU emissions compliance frameworks. |
| Extended-Reach Horizontal Drilling Campaign | Unlocks bypassed pay zones in Carpathian foreland basins without new NAMR concession awards. |
| Cross-Border Interconnector Expansion | Enables Bulgaria-Romania-Hungary corridor arbitrage for Black Sea gas producers. |
| Decommissioning Liability Partnership | Captures growing plug-and-abandonment volumes in Transylvanian Basin as mature fields retire. |
Research Methodology
Direct dialogue with upstream operations managers, drilling contractors, subsea equipment procurement leads, and NAMR regulatory officials grounded qualitative assessment, cross-referenced against NAMR production statistics, ANRE grid access filings, EU ETS emissions disclosures, and offshore rig utilization databases from North Sea and Mediterranean contractors. Bottom-up field-by-field production modeling and top-down macroeconomic scenario analysis triangulated volume and value estimates.
Bottom-up modeling tracked individual concession production profiles, development timelines, and capex schedules across the analysis window, while top-down validation referenced European gas demand forecasts and regional supply competition from Azerbaijan and Eastern Mediterranean fields. Segmentation dimensions spanned hydrocarbon type, operator category, water depth, reservoir pressure regime, and emissions intensity tier. CAGRs derived from weighted average production growth trajectories, incorporating project sanction probability adjustments for pre-FID developments.
Revisions become necessary when NAMR permitting timelines extend materially, EU methane regulations impose unanticipated monitoring cost burdens, or Black Sea reservoir performance diverges from extended well test results. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Drilling Services Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Wellhead System Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
India AI in Oil and Gas Market