
 Qatar Oilfield Chemicals Market | 2026-2036
Qatar Oilfield Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Oilfield Chemicals Market Analytics
Modular chemical bundling is broadening buyer choice across Qatar's offshore and onshore operations. Service companies now specify pre-blended packages combining corrosion inhibitors with friction reducers rather than sourcing single-function additives. Halliburton Company leverages its integrated supply chain to deliver bundled packages directly to North Field platforms. Baker Hughes Company differentiates through high-temperature formulations engineered for Qatar's deep gas reservoirs. Schlumberger Limited anchors its position with just-in-time logistics networks spanning Doha industrial zones.
Qatar oilfield chemicals comprise specialty formulations including biocides, corrosion inhibitors, friction reducers, and surfactants designed to maintain well integrity, optimize hydrocarbon flow, and protect subsea infrastructure under high-pressure high-temperature conditions exceeding 150°C and 10,000 psi. These chemicals primarily serve to prevent scale deposition, control bacterial growth, and reduce friction during drilling and production operations in carbonate and sandstone reservoirs. Corrosion inhibitors command the largest share of product value due to Qatar's sour gas composition and aggressive downhole environments. Friction reducers represent the fastest-expanding category as extended-reach drilling and hydraulic fracturing intensity grow in North Field development. Among end users, national oil companies and integrated majors concentrate procurement power through multi-year framework agreements that lock in volume commitments and technical service provisions.
Qatar's Ministry of Environment and Climate Change enforces produced water discharge limits that restrict biocide toxicity levels, while the Gulf Organization for Industrial Consulting promotes harmonized chemical registration standards across GCC states. These frameworks compel suppliers to reformulate products with biodegradable active ingredients and submit comprehensive environmental fate data before market authorization. Stakeholders must monitor how Qatar's expanding LNG capacity and associated upstream drilling programs reshape chemical specification requirements across new well completions.
Market Dynamics
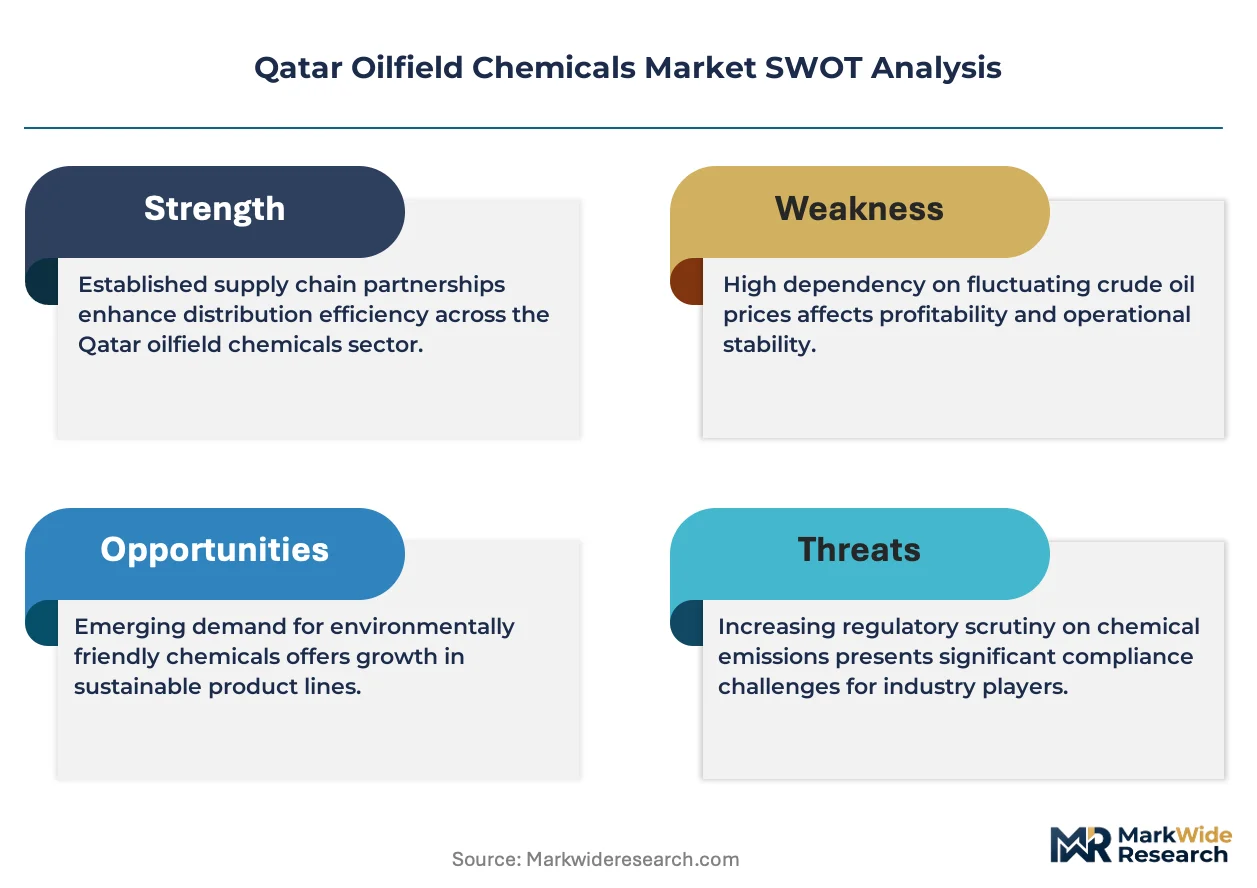
North Field expansion megaprojects are compressing chemical specification cycles as integrated majors demand pre-qualified, multi-functional formulations that reduce offshore inventory footprints and simplify logistics coordination across high-pressure gas reservoirs.
Growth Catalysts
- HPHT Well Complexity:Reservoir temperatures exceeding 150°C and pressures above 10,000 psi in deep gas zones require specialty corrosion inhibitors and friction reducers that standard formulations cannot withstand.
- Qatar's Ministry of Environment and Climate Change discharge mandates:Tightened produced water toxicity standards force reformulation toward biodegradable biocide actives, creating pull for next-generation environmental compliance packages.
- Extended-Reach Drilling Intensity:Horizontal laterals stretching beyond prior technical limits multiply friction reducer consumption per well completion in North Field development corridors.
Market Restraints
- Feedstock Concentration Risk:Key surfactant precursors and quaternary ammonium compounds for biocides concentrate in Asian supply bases, exposing Qatari formulators to shipping disruption and currency fluctuation.
- Specialty Chemical Registration Burden:Gulf Organization for Industrial Consulting harmonization requirements demand extensive environmental fate dossiers that extend product authorization timelines by 18-24 months for new molecular entities.
- Substitution Pressure from Mechanical Solutions:Advanced downhole coating technologies and corrosion-resistant metallurgy in premium tubulars reduce chemical inhibitor intensity per well in select high-budget developments.
Strategic Opportunities
- Integrated Chemical-Logistics Bundling:Just-in-time platform delivery combining formulation blending with offshore warehousing compresses working capital cycles for North Field operators.
- Carbonate Reservoir Surfactant Gaps:Underdeveloped ultra-low interfacial tension formulations for Qatar's heterogeneous carbonate matrix present white space for enhanced oil recovery chemical specialists.
- Produced Water Reuse Incentives:Qatar's circular economy framework for industrial water management creates demand for scale inhibitors and biocides compatible with reinjection and agricultural reuse pathways.
Industry Challenges
- HPHT Formulation Talent Scarcity:Chemists capable of stabilizing active ingredients above 150°C remain concentrated in Houston and Aberdeen, forcing Qatari operations to rely on expatriate technical leadership.
- Multi-Customer Specification Fragmentation:Each integrated major maintains proprietary chemical qualification protocols that prevent standardization and multiply testing costs for suppliers serving multiple North Field consortiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Oilfield Chemicals Market |
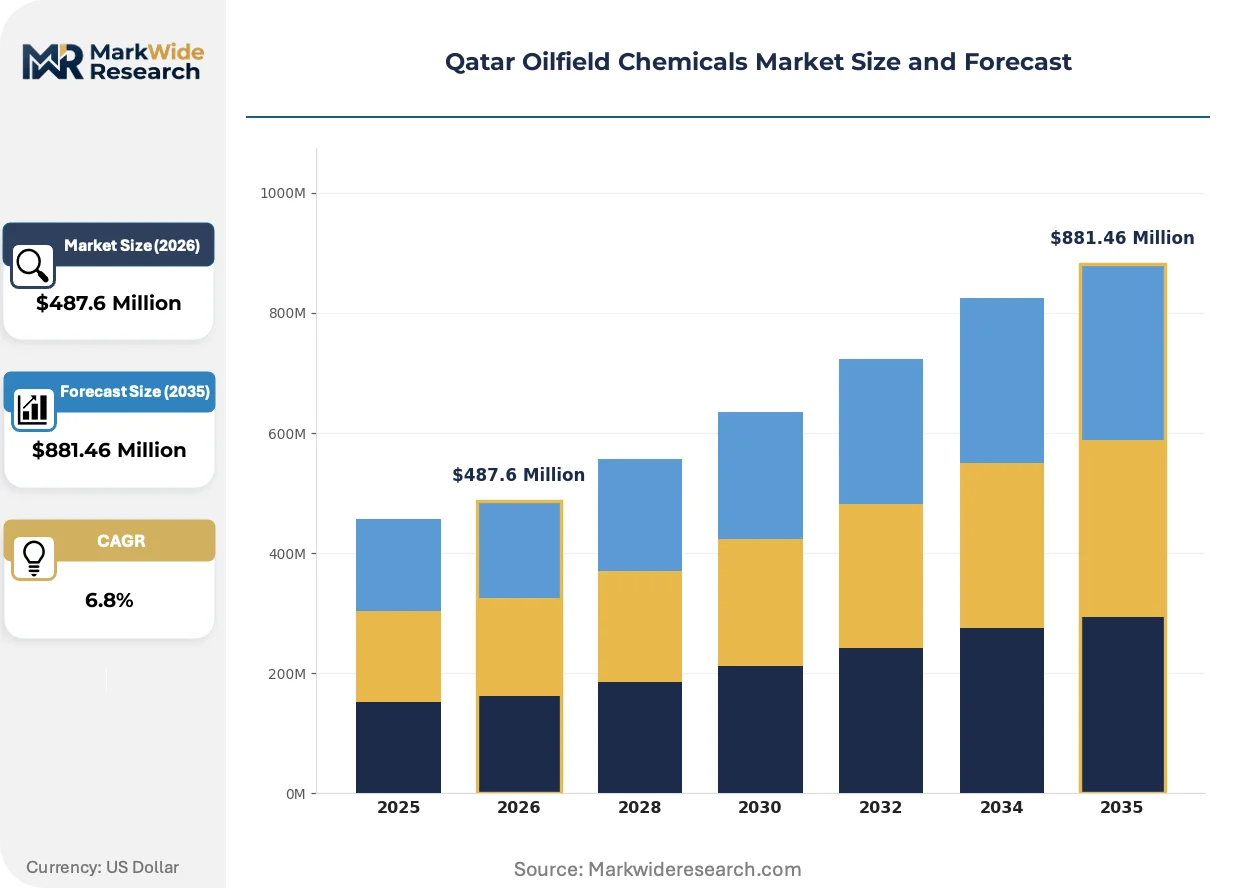
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocides, Friction Reducers, Corrosion Inhibitors, Surfactants Application: Drilling, Cementing, Production, Workover End User: Independent Operators, National Oil Companies, Service Companies, Integrated Majors Delivery Mode: Bulk Delivery, Packaged Delivery, Just-In-Time, Online Orders |
| Companies Covered | Halliburton Company, Schlumberger Limited, Baker Hughes Company, BASF SE, Solvay, Clariant AG, Ecolab Inc., Salam Petroleum Services, Qatar Lubricants Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Oilfield Chemicals Market Evolving Landscape
Pre-blended chemical packages are displacing single-function additive procurement as operators prioritize deck space efficiency and simplified inventory management across offshore platforms. This shift compresses supplier margins while rewarding integrated logistics capabilities.
Chemical bundling technology is modularizing offshore supply chains by combining corrosion inhibitors, friction reducers, and biocides into unitized tote systems. North Field drilling contractors now specify these pre-engineered packages for 70% of new well completions. The approach is modularizing procurement decisions around integrated service agreements rather than discrete product specifications.
Qatar's Ministry of Environment and Climate Change enacted produced water discharge limits that cap biocide toxicity at thresholds incompatible with legacy glutaraldehyde formulations. Industrial consequence forces suppliers to submit comprehensive biodegradability data and reformulate with quaternary phosphonium or thiazoline alternatives. Biocide manufacturers serving the North Field expansion zone face the steepest compliance curve as project timelines compress environmental review windows.
Buyer concentration among integrated majors has collapsed chemical supplier negotiation leverage and extended payment terms toward 90-day cycles. National oil companies now mandate technical service provisions including on-site laboratory support and real-time dosing optimization as standard contract inclusions. This procurement compression is most visible in Doha industrial zone framework agreements where three buyers control 80% of annual chemical volume allocation.
Qatar Oilfield Chemicals Market Segmentation
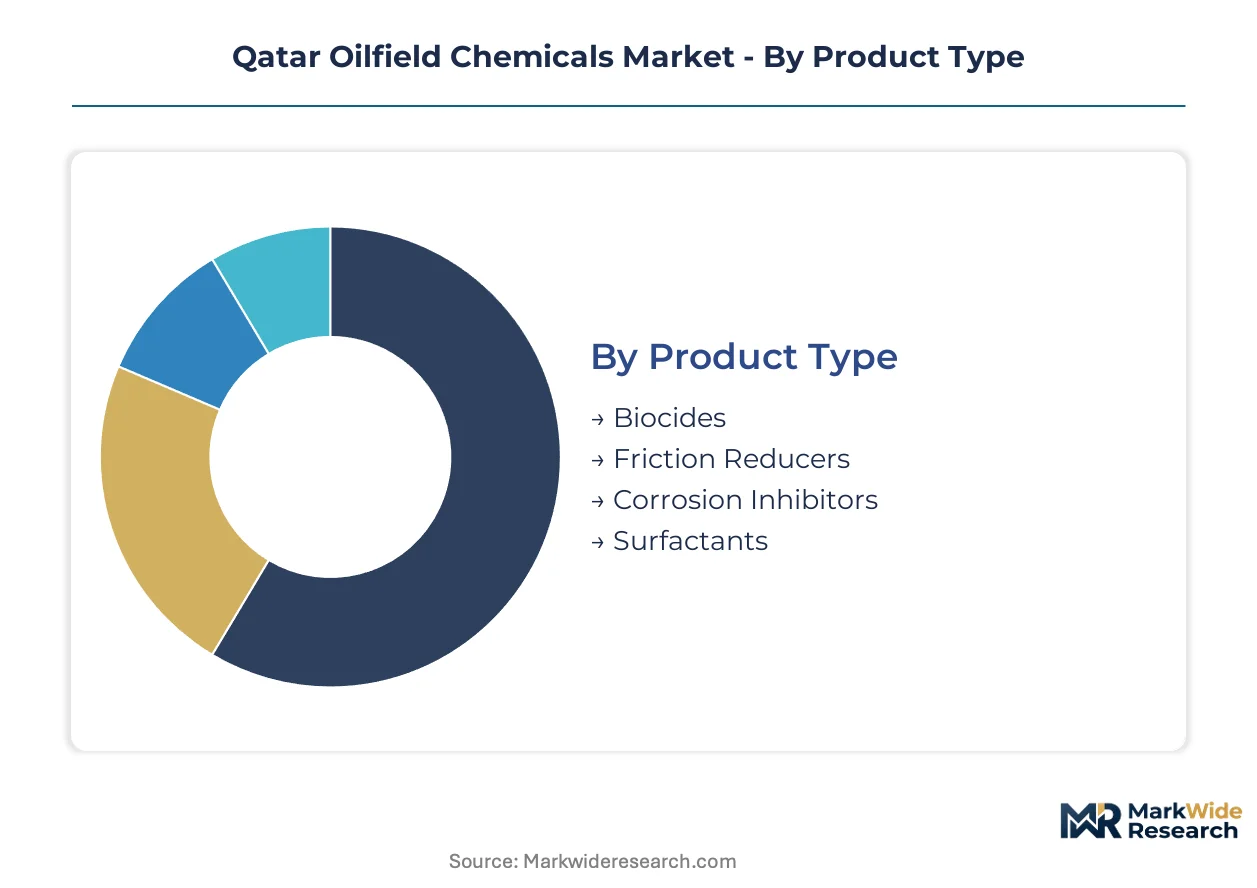
Segmentation in Qatar's oilfield chemicals market reveals how procurement power concentrates among integrated majors while formulation requirements diverge across HPHT reservoir conditions. Understanding these divides exposes where suppliers can standardize versus where customization commands premium positioning.
Product Type:
Customization intensity spans from commodity biocide reformulations to highly engineered corrosion inhibitors, with standardization possible only at the lower-performance tiers.
- Corrosion Inhibitors:Film-forming amines and imidazoline derivatives dominate formulations for Qatar's sour gas reservoirs where hydrogen sulfide concentrations exceed 5%. North Field expansion projects specify these chemicals for every production well completion, with procurement bundled into multi-year framework agreements.
- Friction Reducers:High-molecular-weight polyacrylamide emulsions reduce pump pressure losses during extended-reach drilling beyond 15,000 feet. Horizontal laterals in the North Field expansion zone consume the largest volumes as well complexity intensifies.
- Biocides:Quaternary phosphonium and thiazoline alternatives replace legacy glutaraldehyde under Qatar's Ministry of Environment and Climate Change discharge mandates.
- Surfactants:Anionic and non-ionic formulations address gas-liquid separation challenges in carbonate reservoirs.
Most installed capacity flows through Corrosion Inhibitors. Expansion is steepest in Friction Reducers.
Application:
Volume concentration tracks drilling intensity, while margin concentration favors production-phase chemicals with recurring consumption profiles.
- Drilling:Drilling fluids and cement additives face specification fragmentation as each integrated major maintains proprietary qualification protocols. Friction reducers and shale inhibitors dominate chemical consumption during North Field horizontal development.
- Production:Continuous injection of corrosion inhibitors and scale inhibitors protects subsea infrastructure across Qatar's high-pressure gas reservoirs. Recurring demand patterns and technical service requirements sustain supplier margins.
- Cementing:Fluid loss additives and gas migration control chemicals support zonal isolation in HPHT wellbores.
- Workover:Remedial chemicals address formation damage and restore well productivity in mature fields.
Production-phase chemicals generate the highest recurring revenue per well. Drilling applications are expanding most quickly with North Field megaproject acceleration.
End User:
Procurement leverage concentrates among national oil companies and integrated majors, fragmenting supplier relationships across independent operators and service companies.
- Integrated Majors:ExxonMobil, Shell, and TotalEnergies operating North Field expansion blocks negotiate multi-year framework agreements locking in volume commitments and technical service provisions. These buyers mandate on-site laboratory support and real-time dosing optimization as standard inclusions.
- National Oil Companies:QatarEnergy concentrates procurement power through centralized chemical sourcing for operated assets. Payment terms extend toward 90-day cycles, compressing supplier working capital.
- Service Companies:Halliburton, Baker Hughes, and Schlumberger specify chemicals for integrated service contracts.
- Independent Operators:Smaller exploration licenses drive spot purchasing with limited technical specification power.
Integrated Majors control the largest volume allocation. National Oil Companies are gaining procurement centralization fastest.
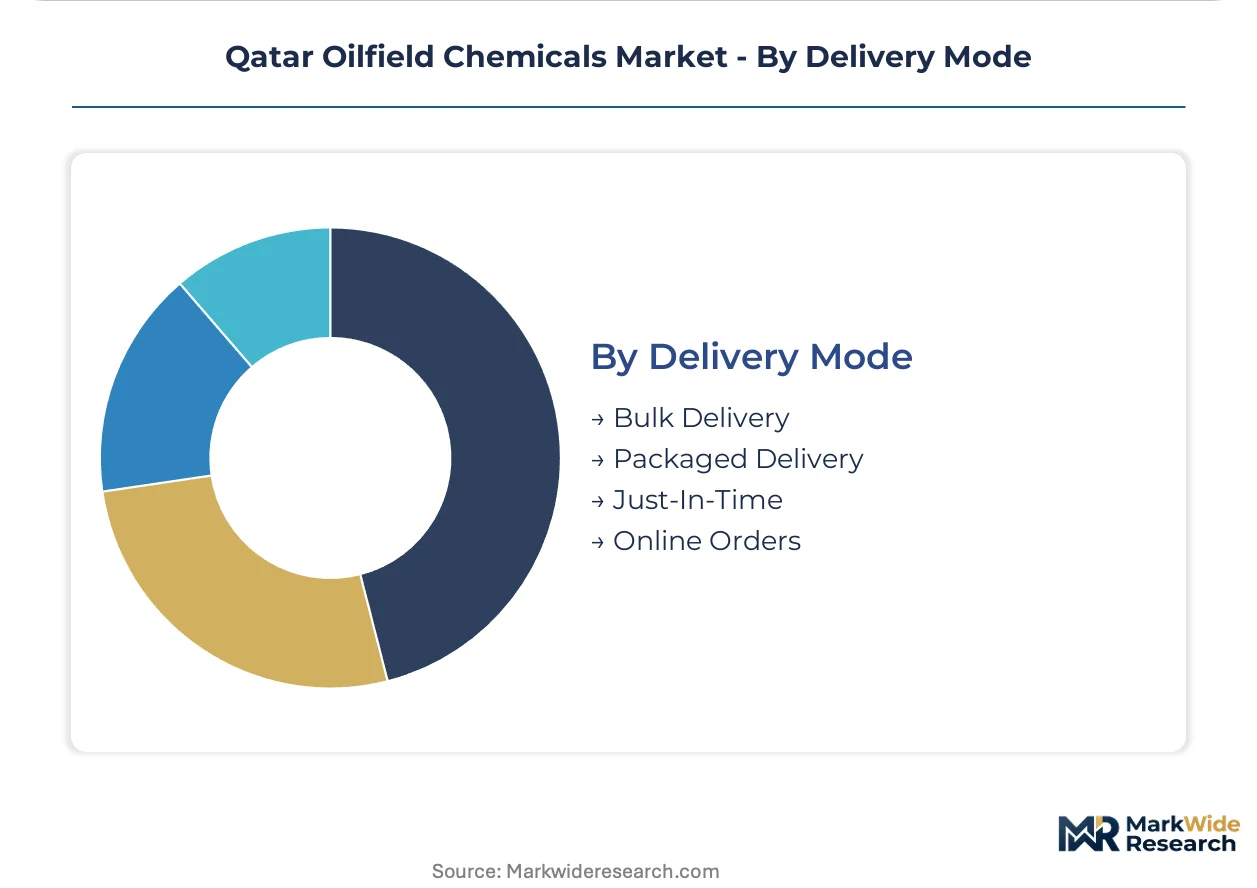
Delivery Mode:
Logistics sophistication separates premium positioning from commodity supply, with just-in-time capabilities commanding framework agreement inclusion.
- Just-In-Time:Platform-direct delivery from Doha industrial zone blending plants compresses inventory footprints for offshore operators. Schlumberger and Baker Hughes anchor competitive positioning through dedicated marine logistics networks.
- Bulk Delivery:Tanker shipments of base chemicals and solvents support formulator operations in Ras Laffan industrial cluster.
- Packaged Delivery:Unitized tote systems combine pre-blended corrosion inhibitors, friction reducers, and biocides for 70% of new North Field well completions.
- Online Orders:Digital procurement platforms serve spot purchasing for non-critical consumables.
Just-In-Time delivery dominates framework agreement specifications. Packaged Delivery is climbing the fastest as modular chemical bundling displaces single-function additive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's oilfield chemicals industry traces its modern scale to the 1990s North Field development, when international operators established supply chains for high-pressure gas production. The sector now concentrates around Doha industrial zones and Ras Laffan, with chemical demand scaling alongside LNG expansion megaprojects.
United States
Houston anchors global formulation expertise for HPHT reservoir chemistry, with specialty chemical firms supplying corrosion inhibitors and friction reducers to Qatari projects through technical service agreements. The EPA regulates biocide environmental fate data requirements that shape product qualification protocols for Middle East exports. Texas Gulf Coast petrochemical clusters manufacture quaternary ammonium precursors and polyacrylamide base stocks for international oilfield service companies.
Germany
BASF SE and specialty chemical houses in Ludwigshafen and Leverkusen engineer high-performance surfactants and scale inhibitors for carbonate reservoir applications. ECHA REACH registration requirements establish biodegradability benchmarks that Qatar's Ministry of Environment and Climate Change references in its discharge mandate compliance frameworks. The Rhine-Ruhr industrial corridor blends formulation R&D with marine logistics coordination for Gulf-bound chemical shipments.
United Arab Emirates
Abu Dhabi and Dubai serve as regional distribution hubs for oilfield chemicals entering Qatari offshore platforms, with Jebel Ali free zone warehousing supporting just-in-time delivery models. MOHAP pharmaceutical and chemical product standards influence Gulf harmonization discussions through the Gulf Organization for Industrial Consulting. The UAE's logistics specialists coordinate trans-shipment of pre-blended chemical packages from Asian manufacturing bases to North Field drilling contractors.
Saudi Arabia
The Eastern Province petrochemical complex at Jubail manufactures commodity surfactant intermediates and solvent bases for regional formulators serving QatarEnergy contracts. SFDA chemical registration procedures provide precedent for Gulf-wide environmental fate dossier requirements that extend product authorization timelines. Dammam industrial city hosts blending operations that supply packaged corrosion inhibitor and biocide formulations to Doha industrial zone distributors.
Qatar Oilfield Chemicals Market Competitive Landscape
The competitive structure tilts toward integrated service conglomerates with captive chemical formulation capabilities. Three tiers separate global oilfield service majors from regional distributors and niche environmental compliance specialists. Market consolidation proceeds through framework agreement capture rather than acquisition, as QatarEnergy and integrated majors lock in multi-year volume commitments. Technical service bundling and just-in-time logistics represent the dominant competitive moves, displacing standalone product procurement.
Within the integrated service tier, Halliburton Company, Schlumberger Limited, and Baker Hughes Company exemplify the convergence of chemical formulation with offshore logistics networks. These entities occupy positions where pre-blended package delivery and platform-direct warehousing compress inventory cycles for North Field operators. Halliburton's Doha industrial zone presence anchors its framework agreement penetration, while Schlumberger's marine logistics infrastructure spans Qatar's offshore production corridors. Baker Hughes represents the high-temperature formulation specialization archetype, with technical positioning calibrated to deep gas reservoir conditions exceeding standard performance thresholds.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| Baker Hughes Company |
| BASF SE |
| Solvay |
| Clariant AG |
| Ecolab Inc. |
| Salam Petroleum Services |
| Qatar Lubricants Company |
| Others |
Value Network & Pricing Analysis
Buyer consolidation among QatarEnergy and integrated majors has collapsed supplier negotiation leverage and forced acceptance of extended payment terms approaching 90-day cycles. This procurement compression reshapes how chemical formulators structure cost recovery across bundled service packages and just-in-time delivery commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by formulation performance grade and technical service bundling. Premium tiers capture HPHT-certified corrosion inhibitors with on-site laboratory support, while economy tiers serve commodity biocide reformulations. Pricing pressure stems from framework agreement standardization that strips customization premiums from mid-tier offerings. National oil companies exhibit highest price sensitivity through centralized volume aggregation, whereas integrated majors prioritize technical compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Asian manufacturing bases for polyacrylamide emulsions and quaternary ammonium precursors. Qatar's formulators draw surfactant intermediates from Germany, biocide actives from Asian chemical clusters, and specialty solvents from Saudi Arabia's Jubail complex. Tariff exposure and shipping disruption threaten just-in-time platform delivery commitments. Distribution runs through Doha industrial zone blending plants and Ras Laffan marine logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Qatar's oilfield chemicals sector rests on reformulation cost-down from biodegradable biocide actives and premium-tier capture of HPHT-certified formulations. Technical service bundling and logistics integration separate value-capture opportunities from commodity supply.
For Market Incumbents: Extend framework agreement penetration through captive blending capacity in Doha industrial zones. Threats from mechanical substitution—advanced downhole coatings and corrosion-resistant metallurgy—demand counter-positioning via real-time dosing optimization and on-site laboratory support. Backward integration into quaternary phosphonium precursor supply hedges Asian feedstock concentration risk. For New Entrants and Emerging Players: The price-point gap between premium HPHT formulations and economy biocide packages opens entry corridors for mid-tier specialists. Carbonate reservoir surfactant gaps present the most penetrable white space, with ultra-low interfacial tension formulations underdeveloped for Qatar's heterogeneous matrix. Go-to-market positioning should anchor on environmental compliance dossier completion ahead of Gulf Organization for Industrial Consulting harmonization deadlines. For Investors and Strategic Acquirers: Asymmetric upside sits with environmental compliance specialists possessing biodegradable biocide portfolios and Gulf registration expertise. Long-term viability favors entities with technical service infrastructure locked into North Field expansion timelines. The signal to watch is QatarEnergy procurement centralization velocity and framework agreement renewal cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Precursors | Reduces Asian feedstock concentration risk for Qatari formulators serving North Field projects. |
| HPHT Formulation Certification Investment | Unlocks premium-tier positioning in deep gas reservoirs exceeding 150°C and 10,000 psi. |
| Just-in-Time Logistics Network Expansion | Platform-direct delivery from Doha industrial zones compresses inventory cycles for offshore operators. |
| Environmental Compliance Dossier Completion | Accelerates Gulf Organization for Industrial Consulting product authorization for biodegradable actives. |
| Joint Venture with Regional Distributors | Secures framework agreement access through QatarEnergy and integrated major procurement channels. |
Research Methodology
Direct dialogue with procurement leads at national oil companies, technical directors at integrated majors, blending plant managers in Doha industrial zones, and marine logistics coordinators anchored qualitative foundations. Secondary validation drew from Qatar Ministry of Environment and Climate Change discharge mandates, Gulf Organization for Industrial Consulting harmonization frameworks, customs and trade data for chemical imports, and SEC filings of oilfield service conglomerates. Bottom-up volume triangulation against top-down macroeconomic drivers ensured forecast robustness.
Bottom-up modeling segmented the market by product type, application phase, end-user category, and delivery mode across the projection horizon. Analytical frameworks incorporated HPHT well completion intensity, environmental compliance reformulation timelines, and framework agreement renewal patterns. CAGRs were derived from segment-level volume build-ups reconciled against aggregate market expansion.
Caveats apply where Qatar's LNG expansion acceleration, Gulf-wide regulatory harmonization delays, or Asian supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions about North Field megaproject timelines and biocide reformulation adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil Well Cement Market
Oil & Gas
Southeast Asia Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Hydrocracking Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Mineral Oil and Mineral Spirit Market