
 Frac Tree Market | 2026-2036
Frac Tree Market Size, Share, and Industry Trends Forecast 2026-2036
Frac Tree Market Analysis
North American pressure pumping equipment fabrication is shifting toward higher-specification alloy construction to withstand 15,000 psi wellhead environments. Schlumberger Ltd. leverages integrated well construction portfolios to bundle frac tree offerings with completion services. Halliburton Company anchors its position through captive manufacturing of flow-control iron for its pressure pumping fleet. Baker Hughes Company competes via specialized metallurgy programs targeting corrosive, high-temperature shale formations.
A frac tree is an assembled wellhead manifold system comprising master valves, wing valves, goat heads, and choke assemblies, typically rated for 10,000–20,000 psi working pressure, that directs pressurized fracturing fluid from surface pumps into the wellbore during hydraulic stimulation operations. Steel material grades dominate installed base volumes due to established ASME boiler code compliance and repair infrastructure, though alloy and composite configurations capture attention in weight-sensitive offshore applications. Digital frac tree variants incorporating real-time pressure telemetry represent the fastest-expanding type segment as operators pursue remote monitoring capabilities for simultaneous multi-well operations. Onshore operations absorb the majority of application-specific demand, driven by Permian and Appalachian basin development intensity.
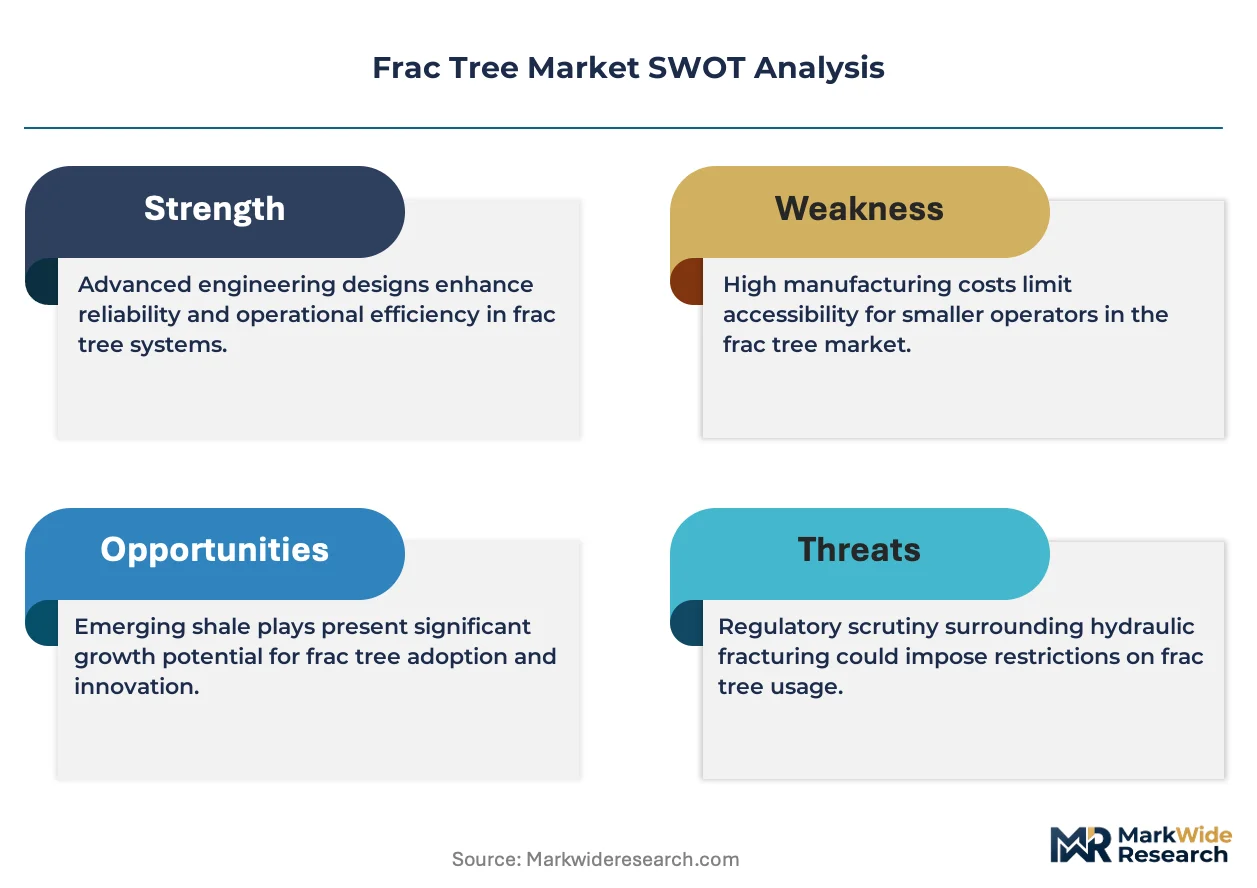
API 6A wellhead equipment standards, ASME BPVC Section VIII pressure vessel codes, and EPA methane emissions regulations collectively shape product design, material traceability, and leak-detection integration requirements for frac tree manufacturers. OSHA Process Safety Management standards enforce rigorous pressure testing protocols that extend qualification timelines for new assembly designs. Stakeholders must monitor evolving state-level methane rules and operator ESG commitments to anticipate demand shifts toward instrumented, low-emission frac tree configurations.
Market Dynamics
Multi-well pad development in unconventional shale basins is compressing cycle times and forcing frac tree manufacturers toward standardized, rapid-deployment manifold configurations that integrate digital pressure monitoring from the factory floor.
Growth Catalysts
- API 6A Certification Mandates:Tightening wellhead equipment standards across Texas and North Dakota are disqualifying legacy suppliers and consolidating procurement toward certified fabricators with full material traceability systems.
- 15,000 psi Wellhead Environments:Permian Basin operators are pushing stimulation pressures higher, driving replacement demand for alloy-construction frac trees that withstand extended-duty hydraulic fracturing campaigns.
- Simultaneous Multi-Well Operations:Digital frac tree variants with real-time telemetry are capturing preference among pressure pumping fleets pursuing remote monitoring capabilities for multi-well pad efficiency.
Market Restraints
- High-Grade Alloy Input Volatility:Chromium-molybdenum steel pricing fluctuations compress fabrication margins and complicate long-term contract bidding for wellhead equipment suppliers.
- Gulf Coast Manufacturing Concentration:Heavy reliance on Houston-area machining and forging capacity creates geographic vulnerability to hurricane disruptions and logistics bottlenecks.
- EPA Methane Emissions Rules:Leak-detection integration requirements extend engineering qualification timelines and raise non-recurring development costs for new frac tree assemblies.
Strategic Opportunities
- Appalachian Basin Underpenetration:Marcellus and Utica shale operators lag Permian adoption rates for instrumented frac trees, presenting volume expansion potential for suppliers with regional service infrastructure.
- Offshore Weight-Sensitive Applications:Composite-material frac tree configurations are gaining evaluation for platform-mounted hydraulic stimulation where deck load limits constrain conventional steel assemblies.
- OSHA Process Safety Management Alignment:Rigorous pressure testing protocols create competitive differentiation for manufacturers with automated validation workflows that accelerate customer qualification.
Industry Challenges
- ASME BPVC Section VIII Certification Timelines:Pressure vessel code compliance documentation extends product development cycles and delays revenue recognition for new frac tree designs.
- Legacy Wellhead Integration Complexity:Retrofitting digital telemetry into installed base equipment requires custom engineering that strains technical service bandwidth and fragments product standardization efforts.
- Specialized Welding Skill Scarcity:Qualified sour-service alloy welders command premium labor rates and constrain fabrication throughput for high-specification frac tree orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frac Tree Market |
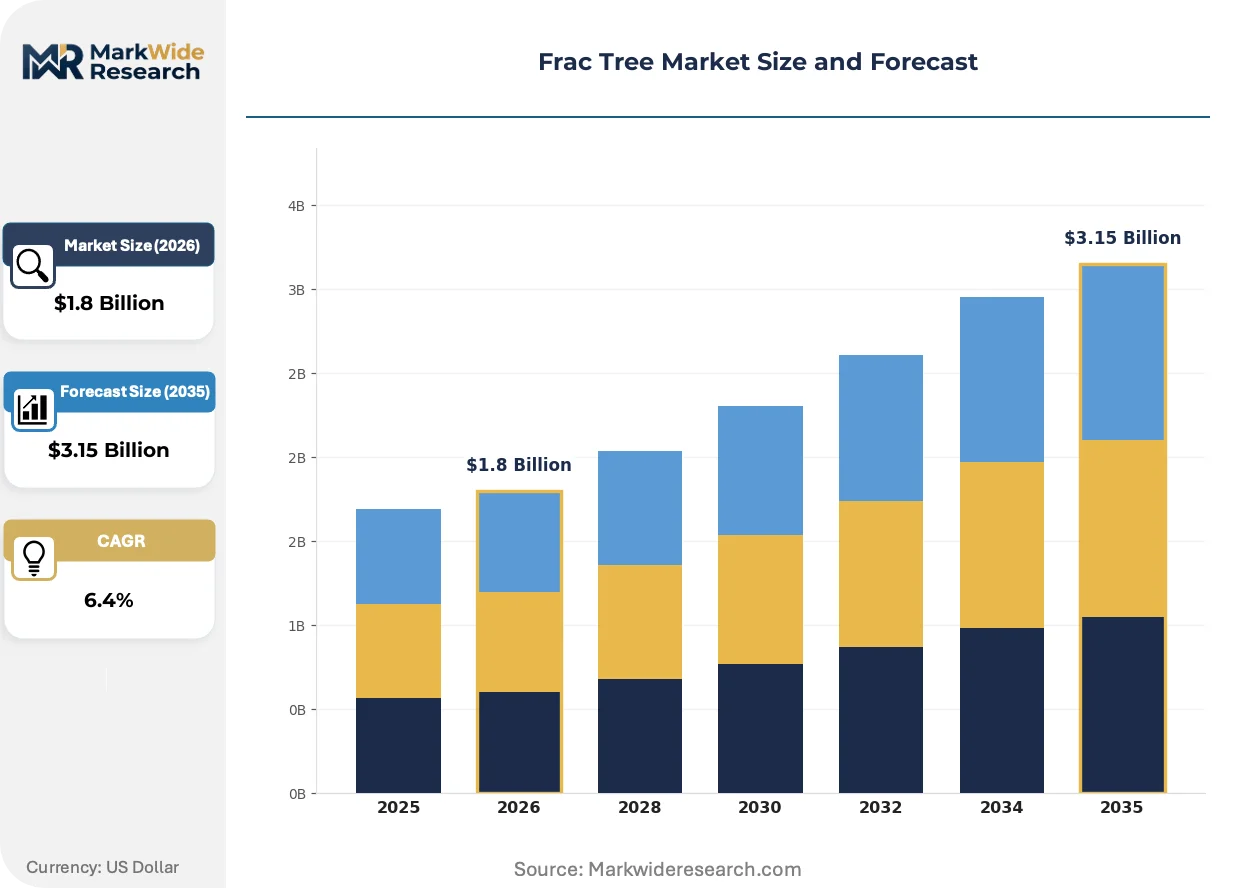
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Digital, Hydraulic, Adjustable Material: Steel, Aluminum, Composite, Alloy Application: Onshore Operations, Offshore Operations, Test Sites, Maintenance Activities End User: Oil & Gas Producers, Service Companies, Contractors, Equipment Suppliers |
| Companies Covered | Weatherford International plc, Liberty Energy Inc., Schlumberger Ltd., Calfrac Well Services Ltd., ProFrac, Baker Hughes Company, Patterson-UTI Energy, Inc., Nine Energy Service, Inc., Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frac Tree Market Emerging Trajectories
Digital instrumentation is penetrating wellhead equipment at the component level, creating new competitive dimensions around data integration rather than standalone mechanical performance. Fabricators are repositioning around software-enabled service models.
Integrated pressure-telemetry frac trees are unifying mechanical flow control with real-time data acquisition in a single manifold assembly. Permian Basin pressure pumping operators are specifying these configurations for multi-well pad deployments where simultaneous monitoring of six to twelve wells compresses surface equipment footprint. This convergence is unifying procurement decisions around vendors with both metallurgical and embedded systems capabilities, marginalizing pure-play mechanical suppliers.
EPA methane emissions regulations are mandating leak-detection integration in surface wellhead equipment. Fabricators must now engineer instrumented valve position indicators and automated shutoff triggers into standard frac tree configurations. Sour-service applications in West Texas and southeastern New Mexico face the steepest compliance engineering burdens, driving preference toward suppliers with pre-certified low-emission product families.
Operator procurement patterns are consolidating around bundled well construction packages rather than discrete equipment purchases. Exploration and production companies in the Delaware Basin are negotiating integrated contracts covering frac trees, completion services, and digital monitoring subscriptions. This bundling compresses standalone equipment margins and rewards fabricators with captive pressure pumping affiliations or partnership structures with major service companies.
Frac Tree Market Segmentation
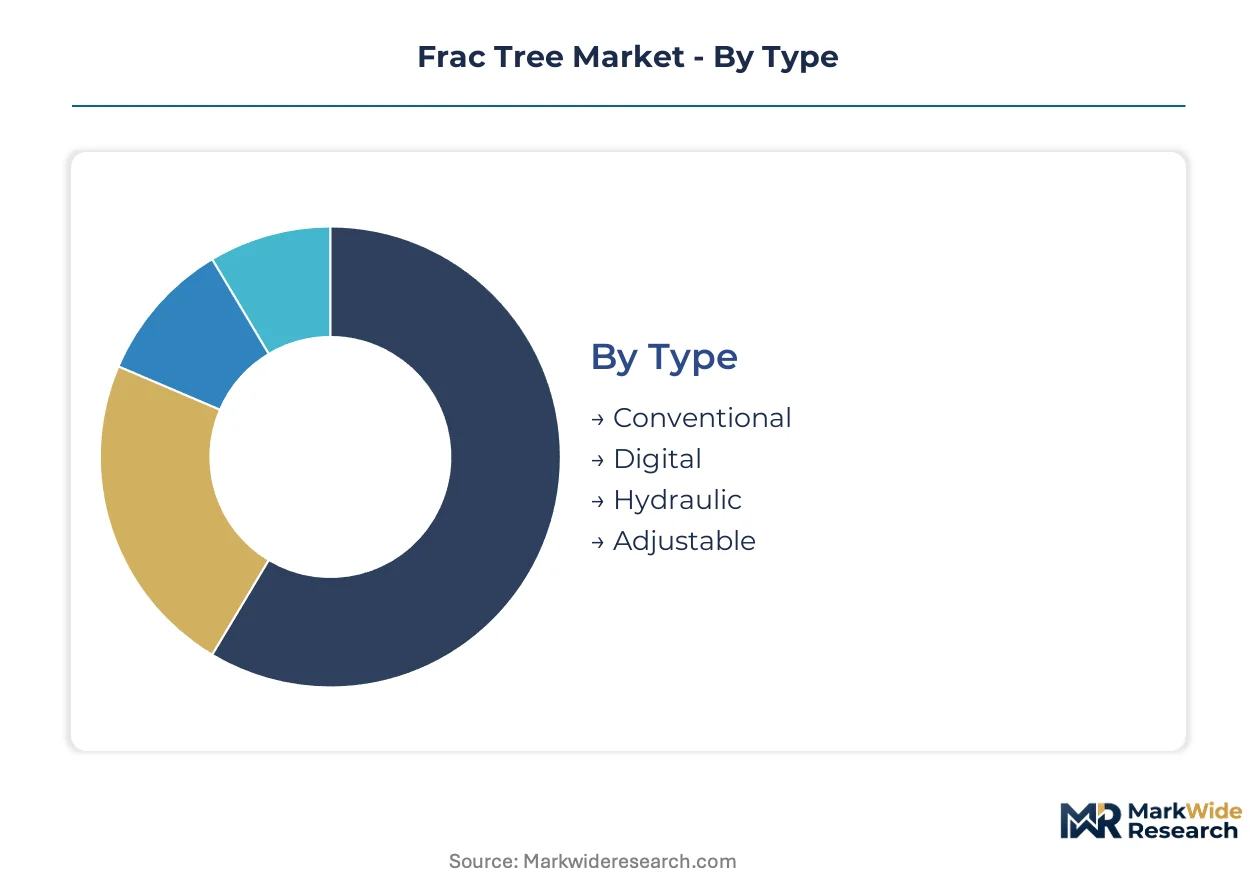
Frac tree procurement decisions split across technical specifications, material durability requirements, and operational deployment contexts. Buyers evaluate pressure ratings, telemetry integration, and sour-service compatibility against pad development economics and regulatory compliance burdens.
Type:
Pressure pumping fleets prioritize pressure containment reliability and remote monitoring integration when selecting manifold configurations.
- Conventional:Mechanical-only frac trees with manual valve operation and static pressure gauges dominate installed base volumes. Demand concentrates among smaller Permian Basin operators running standardized 10,000 psi campaigns where digital retrofit costs outweigh operational benefits.
- Digital:Integrated telemetry systems capture real-time pressure, temperature, and flow data for centralized pad monitoring. West Texas pressure pumping fleets specify these configurations for simultaneous multi-well operations where remote diagnostics compress surface crew requirements and accelerate troubleshooting response.
- Hydraulic:Actuated valve control enables remote choke adjustment during high-rate stimulation. Service companies deploy these for extended-reach laterals requiring dynamic pressure management without manual intervention at the wellhead.
- Adjustable:Modular bore configurations accommodate varying casing programs across multi-well pads. Operators in the Delaware Basin favor these for pad uniformity where standardized completion designs reduce spare parts inventory.
Conventional configurations lead on scale; Digital variants lead on momentum.
Material:
Fabrication economics and corrosion resistance requirements determine alloy selection for sour-service and high-pressure applications.
- Steel:Established ASME BPVC compliance and extensive repair infrastructure sustain dominance in conventional onshore deployments. Permian operators specify standard carbon steel for dry-gas applications where H2S exposure remains minimal.
- Alloy:Chromium-molybdenum grades withstand 15,000 psi wellhead pressures and corrosive West Texas sour gas. Delaware Basin operators mandate these for extended-duty frac campaigns where material fatigue risks dominate lifecycle economics.
- Aluminum:Weight reduction benefits offshore platform applications where deck load constraints limit conventional steel assemblies. Gulf of Mexico operators evaluate these for subsea tieback stimulation.
- Composite:Fiber-reinforced polymer configurations eliminate corrosion risks in high-CO2 environments. Deepwater pre-salt operators in Brazil pilot these for weight-sensitive subsea installations.
Steel dominates current procurement volumes; Alloy grades are expanding most quickly.
Application:
Surface equipment footprint constraints and environmental exposure severity shape specification intensity across deployment contexts.
- Onshore Operations:Multi-well pad development in Texas and North Dakota drives standardized manifold configurations with rapid-deployment skidding. Digital telemetry integration accelerates as fleet operators pursue remote monitoring for twelve-well simultaneous operations.
- Offshore Operations:Platform-mounted stimulation requires compact, weight-optimized assemblies with marine-grade corrosion protection. Gulf of Mexico developments specify these for tieback completions where deck space commands premium logistics costs.
- Test Sites:Prototype validation environments demand flexible reconfigurability for pressure cycling research. Oklahoma-based equipment qualification facilities utilize these for API 6A certification testing.
- Maintenance Activities:Workover and recompletion operations require portable frac trees compatible with legacy wellhead geometries. Appalachian Basin operators deploy these for refracturing campaigns on decade-old Marcellus wells.
Onshore deployments absorb the majority of unit demand; Offshore configurations command premium pricing tiers.
End User:
Procurement authority and technical specification control vary dramatically across the value chain.
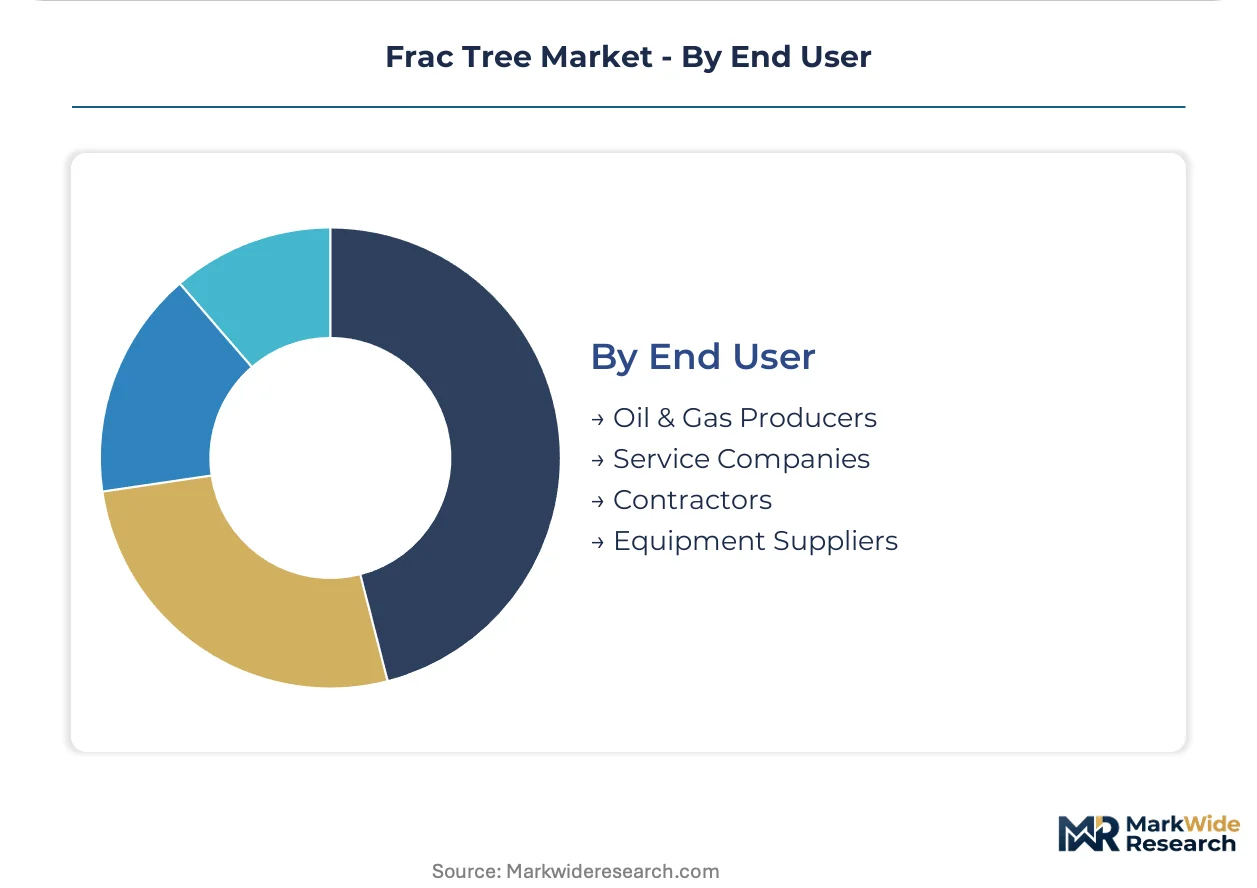
- Oil & Gas Producers:Exploration and production companies with captive pressure pumping capabilities specify integrated well construction packages bundling frac trees with completion services. Delaware Basin independents negotiate these arrangements to compress supplier management overhead.
- Service Companies:Pressure pumping fleets with equipment ownership models drive standardization across multi-basin operations. Halliburton and Schlumberger procurement teams mandate interoperable manifold specifications to maximize iron utilization rates.
- Contractors:Third-party stimulation providers with rental-focused business models prioritize rapid-deployment configurations minimizing rig-up time. Permian Basin contract fleets favor lightweight skidded assemblies for pad-hopping efficiency.
- Equipment Suppliers:Pure-play fabricators without service affiliations compete on material traceability and API 6A certification documentation. Houston-area machine shops target these customers with sour-service alloy specialization.
Service Companies control the largest procurement volumes; Oil & Gas Producers are gaining specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping frac tree manufacturing geography as fabricators migrate toward jurisdictions with streamlined API 6A certification pathways and lower alloy input tariffs. Cost-of-compliance gaps between North American and Middle Eastern production bases now exceed fifteen percentage points on equivalent pressure-rated assemblies.
United States
Permian Basin operators in West Texas and southeastern New Mexico are mandating 15,000 psi alloy-construction frac trees for extended-duty campaigns. EPA methane emissions rules require instrumented valve position indicators and automated shutoff triggers on all new surface wellhead equipment. Houston-area machining and forging clusters concentrate domestic fabrication capacity, though hurricane exposure creates recurring logistics vulnerability.
Canada
Montney and Duvernay shale development in Alberta and British Columbia is driving demand for sour-service frac trees rated for H2S exposure. Health Canada and provincial regulators enforce ASME BPVC Section VIII pressure vessel codes that extend qualification timelines for new assembly designs. Calgary-based equipment qualification facilities serve as North American hubs for prototype validation and API 6A certification testing.
Saudi Arabia
Unconventional gas development in the Jafurah Basin is accelerating procurement of high-pressure frac tree systems for tight sandstone stimulation. The country's national oil company mandates full material traceability systems and sour-service metallurgy programs aligned with domestic content requirements. Eastern Province industrial cities host emerging fabrication partnerships between international service companies and local manufacturing ventures.
China
Domestic shale gas development in Sichuan and Chongqing is expanding demand for cost-optimized frac tree configurations in 10,000–12,000 psi ranges. GB standards and MIIT industrial policy prioritize local fabrication capacity for pressure pumping equipment serving state-owned exploration companies. Yangtze River Delta manufacturing clusters are developing alloy-forging capabilities to reduce import dependence for high-specification wellhead components.
Brazil
Pre-salt deepwater stimulation programs are evaluating composite-material frac trees for weight-sensitive subsea installations. ANVISA and national petroleum regulator requirements govern subsea equipment certification, though surface wellhead standards remain less prescriptive than North American equivalents. Rio de Janeiro and São Paulo engineering centers pilot fiber-reinforced polymer configurations for platform-mounted hydraulic stimulation.
Frac Tree Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital telemetry integration and composite-material specialization. The vendor base stratifies across three maturity tiers: integrated oilfield service conglomerates with captive manufacturing, independent wellhead equipment fabricators with API 6A certification depth, and regional machine shops serving maintenance and workover markets. Dominant competitive moves include backward integration into alloy forging capacity and strategic partnerships with pressure pumping fleets for bundled procurement contracts.
Among Houston-based service conglomerates, Halliburton Company and Schlumberger Ltd. exemplify the integrated-tier archetype through captive flow-control iron manufacturing and completion service bundling. Baker Hughes Company anchors the specialized-metallurgy vector with programs targeting corrosive, high-temperature shale formations. These three entities collectively represent the competitive standard against which independent fabricators and regional specialists benchmark qualification timelines and material traceability systems.
| Leading Market Players |
|---|
| Weatherford International plc |
| Liberty Energy Inc. |
| Schlumberger Ltd. |
| Calfrac Well Services Ltd. |
| ProFrac |
| Baker Hughes Company |
| Patterson-UTI Energy, Inc. |
| Nine Energy Service, Inc. |
| Halliburton Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up pressure pumping specialists have consolidated regional service fleets across Texas and North Dakota, compressing procurement timelines and hardening price discipline for API 6A-certified frac tree assemblies. This ownership concentration amplifies volume bargaining leverage while funneling specification authority toward bundled well construction packages.
Pricing Analysis
Direct-to-OEM discounts dominate high-volume procurement between integrated service companies and captive fabrication affiliates. Three-tier pricing structure across premium alloy, standard carbon steel, and economy refurbished tiers separates sour-service certified assemblies from conventional onshore configurations. Cost compression in standard steel grades intensifies because of chromium-molybdenum input volatility. Independent Permian Basin operators exhibit highest price sensitivity; national oil companies with captive engineering teams show lowest.
Supply Chain Analysis
API 6A certification documentation requirements gate entry for new forging suppliers and extend qualification cycles for alloy material traceability systems. Manufacturing concentrates in the United States, China, and Saudi Arabia. Supply chains draw from chromium-molybdenum steel mills, precision machining centers, and embedded sensor component suppliers. Single-source vulnerability around Houston-area forging capacity creates hurricane exposure. Distribution runs through pressure pumping fleet procurement teams and regional equipment rental depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA methane emissions rules mandate instrumented valve integration and automated shutoff triggers, permanently elevating engineering specifications for surface wellhead equipment.
For Market Incumbents: Deploy captive alloy forging capacity to insulate margin structures from chromium-molybdenum price volatility. Consolidate regional service infrastructure in the Appalachian Basin to preempt emerging entrant expansion. Certification depth in sour-service metallurgy programs anchors defensive positioning against pure-play digital telemetry specialists. For New Entrants and Emerging Players: EPA methane regulations in the United States open a window for instrumented frac tree configurations with pre-integrated leak detection. White-space concentration lies in Appalachian Basin Marcellus operations lagging Permian digital adoption rates. Composite-material offshore configurations for Gulf of Mexico platform constraints offer secondary penetration vector. Go-to-market execution should target contract pressure pumping fleets with rental-focused procurement models. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, seeking API 6A-certified fabrication assets to complete bundled well construction offerings. Five-to-ten year viability hinges on digital telemetry integration capabilities and sour-service alloy specialization. Acquisition target archetype: independent wellhead fabricators with full material traceability systems and regional service infrastructure. Signal to watch: state-level methane rule adoption beyond federal EPA baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Halliburton and Schlumberger captive supply chains neutralize chromium-molybdenum price volatility. |
| Digital Telemetry Platform Integration | Real-time pressure monitoring unifies mechanical flow control with data acquisition for multi-well pads. |
| Sour-Service Metallurgy Certification | API 6A compliance in corrosive West Texas formations creates procurement preference for certified fabricators. |
| Regional Service Infrastructure Expansion | Appalachian Basin penetration lags Permian adoption, presenting volume expansion for equipped suppliers. |
| Composite-Material Product Development | Fiber-reinforced polymer configurations address weight constraints in Gulf of Mexico offshore installations. |
Methodological Framework
Multiple input streams — primary interviews with pressure pumping fleet managers, wellhead procurement officers, and API certification engineers; secondary validation through EPA regulatory filings, ASME BPVC documentation, and pressure pumping equipment trade data; plus customs records for alloy steel imports — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned service company engineering directors, independent fabricator operations heads, and EHS compliance officers at Delaware Basin operators.
Historical deployment patterns were cross-referenced against panel input from equipment procurement teams to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include frac tree type, material grade, application context, and end-user procurement authority. CAGRs were derived from unit deployment trajectories in high-pressure shale basins and alloy substitution rates in sour-service environments.
Revisions become necessary when EPA methane enforcement intensity shifts, API 6A certification standards update, or hurricane disruptions alter Houston-area manufacturing capacity. Forecasts reflect assumptions about regulatory stability and alloy input pricing continuity. A model refresh is warranted upon material change in state-level methane rule adoption or unconventional shale development pace in the Permian Basin.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Downhole Tractor Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market