
 Single Point Anchor Reservoir (SPAR) Market | 2026-2036
Single Point Anchor Reservoir (SPAR) Market Size, Share, and Industry Trends Forecast 2026-2036
Single Point Anchor Reservoir (SPAR) Market Analytics
Specification upgrades toward high-fatigue mooring chains and dynamic positioning redundancy is unwinding legacy cost structures across the SPAR supply base. TechnipFMC leverages integrated engineering-to-installation capabilities across deepwater projects. Samsung Heavy Industries anchors its position through dedicated offshore yard capacity in South Korea. SBM Offshore differentiates via proprietary hull designs and long-term lease-operate contracts.
A Single Point Anchor Reservoir is a floating offshore platform consisting of a large-diameter vertical cylindrical hull moored to the seabed by a spread mooring system, typically operating in water depths exceeding 1,000 meters to support drilling, production, and storage of hydrocarbons. The structure relies on ballasting systems to maintain stability and dynamic positioning technology for station-keeping during offloading operations. Floating-type SPAR configurations dominate current order books due to their proven track record in harsh environments, while mooring systems technology commands concentrated R&D investment as operators push into ultra-deepwater frontiers. Offshore wind as an end user represents an emerging demand vector, though oil and gas applications still absorb the majority of fabrication capacity.
The US Bureau of Safety and Environmental Enforcement and Brazil's national petroleum regulator enforce stringent well containment and station-keeping standards that elevate technical barriers for new platform entrants. ISO 19901-7 mooring design standards and API RP 2SK guidelines shape global product specifications and certification requirements. Stakeholders must weigh exposure to deepwater exploration cycles against the capital intensity of hull fabrication and mooring system qualification programs.
Market Dynamics
Ultra-deepwater frontier expansion is compressing mooring system qualification timelines while elevating technical barriers for platform fabricators. The US Bureau of Safety and Environmental Enforcement mandates real-time structural monitoring, forcing simultaneous investment in sensor integration and hull design standardization.
Growth Catalysts
- API RP 2SK mooring guidelines:Revised station-keeping standards in US federal waters are accelerating replacement cycles for legacy chain systems. Operators must upgrade spread mooring configurations to maintain drilling permits.
- Brazilian pre-salt development:Petrobras-led production targets in the Santos Basin are sustaining fabrication demand at Southeast Asian and Gulf Coast yards. Floating SPAR configurations dominate tender specifications.
- Dynamic positioning redundancy:Dual-thruster architectures are becoming baseline for offloading operations, driving ballast control system procurement. This specification shift favors integrated engineering contractors.
Market Restraints
- High-grade steel alloy volatility:R4 and R5 mooring chain grades face concentrated supply from European and Japanese specialty mills. Input cost swings compress fabrication margins during contract bidding.
- ISO 19901-7 certification bottlenecks:Third-party verification capacity for deepwater mooring designs concentrates among four global classification societies. Qualification queues extend project timelines.
- Fixed platform substitution:Shallow-water tieback economics occasionally favor compliant tower structures over SPAR hulls. This technology competition constrains addressable market expansion.
Strategic Opportunities
- West African frontier basins:Mauritania-Senegal and Namibian ultra-deepwater blocks lack established platform supply chains. First-mover fabricators can anchor regional service infrastructure.
- Offshore wind floating foundations:SPAR-derived hull geometries are migrating into turbine support applications. Shared fabrication capacity creates demand smoothing across energy cycles.
- US Inflation Reduction Act lease provisions:Enhanced depreciation schedules for offshore infrastructure are improving project economics. Gulf of Mexico brownfield redevelopment qualifies for modified terms.
Industry Challenges
- Weld inspection technician scarcity:Automated ultrasonic testing certification for thick-section cylindrical hulls concentrates among aging specialist workforces. Training pipeline gaps threaten yard throughput.
- Legacy platform integration:Brownfield SPAR installations must interface with existing subsea architecture. Tieback engineering complexity elevates commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Point Anchor Reservoir (SPAR) Market |
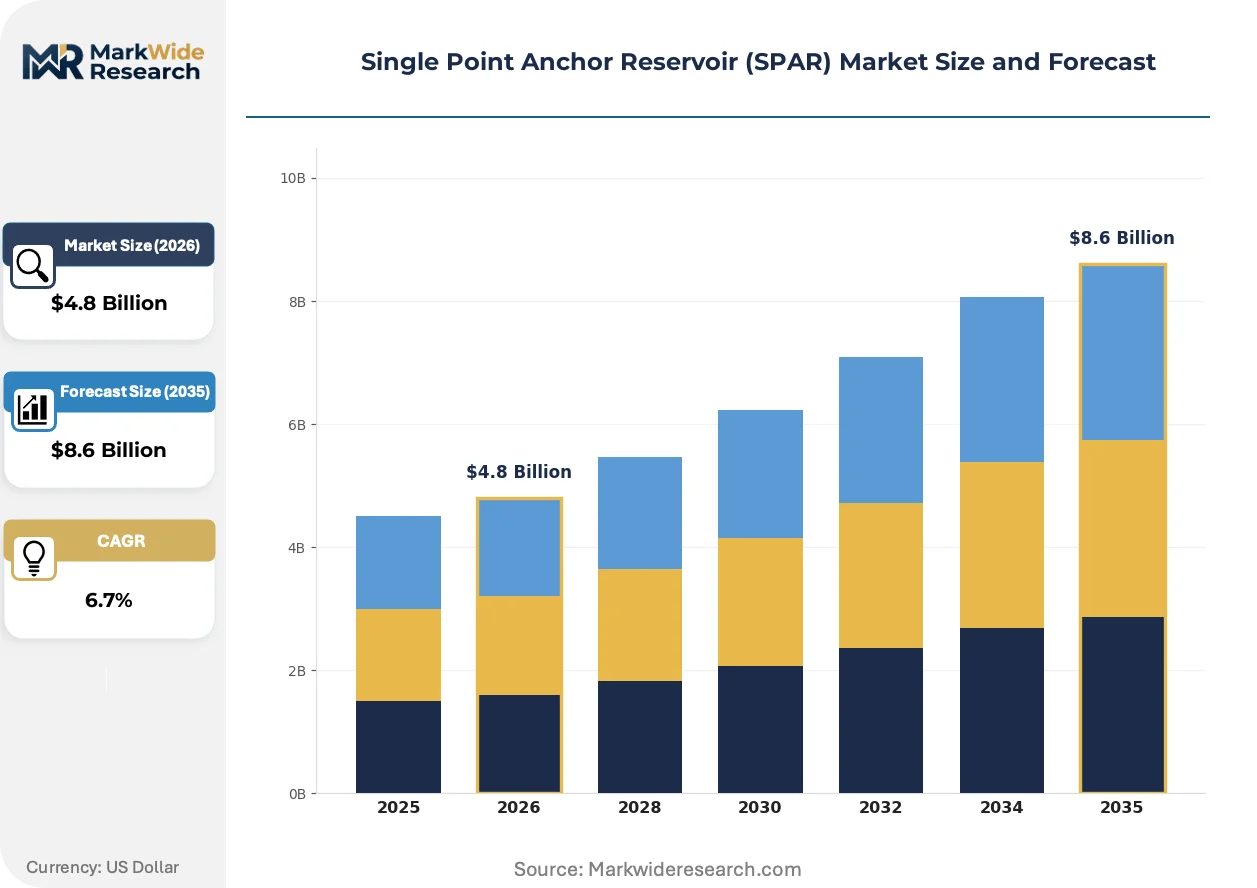
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floating, Fixed, Tension Leg, Submersible Technology: Dynamic Positioning, Ballasting, Mooring Systems, Backup Systems End User: Oil & Gas, Marine Engineering, Research Institutions, Offshore Wind Application: Exploration, Production, Storage, Transportation |
| Companies Covered | Bumi Armada Berhad, TechnipFMC, Samsung Heavy Industries, MODEC, Mitsubishi Heavy Industries, Hyundai Heavy Industries, Teekay Corporation, Aker Solutions, SBM Offshore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Point Anchor Reservoir (SPAR) Market Evolving Landscape
Digital twin deployment is compressing structural integrity verification timelines while enabling predictive maintenance models for mooring fatigue. These capabilities are reshaping competitive differentiation among platform integrators.
Fiber-optic strain sensing arrays embedded within mooring chains are miniaturizing. Deepwater operators in the Gulf of Mexico are retrofitting legacy SPAR installations with real-time tension monitoring. This sensor integration is miniaturizing inspection intervals and enabling condition-based replacement rather than calendar-driven chain swaps.
The EU Green Deal methane emission monitoring framework is extending to offshore production infrastructure. Floating platform operators must install continuous venting detection systems to maintain chartering eligibility. North Sea assets face the most compressed compliance timelines, with Norwegian regulators mandating full-facility coverage by 2027.
Integrated lease-operate contracting is displacing traditional engineering-procurement-construction arrangements. National oil companies in Brazil and West Africa now prefer long-term availability-based payments over capital-heavy platform purchases. This preference shift concentrates risk with contractors possessing balance sheet capacity for hull ownership.
Single Point Anchor Reservoir (SPAR) Market Segmentation
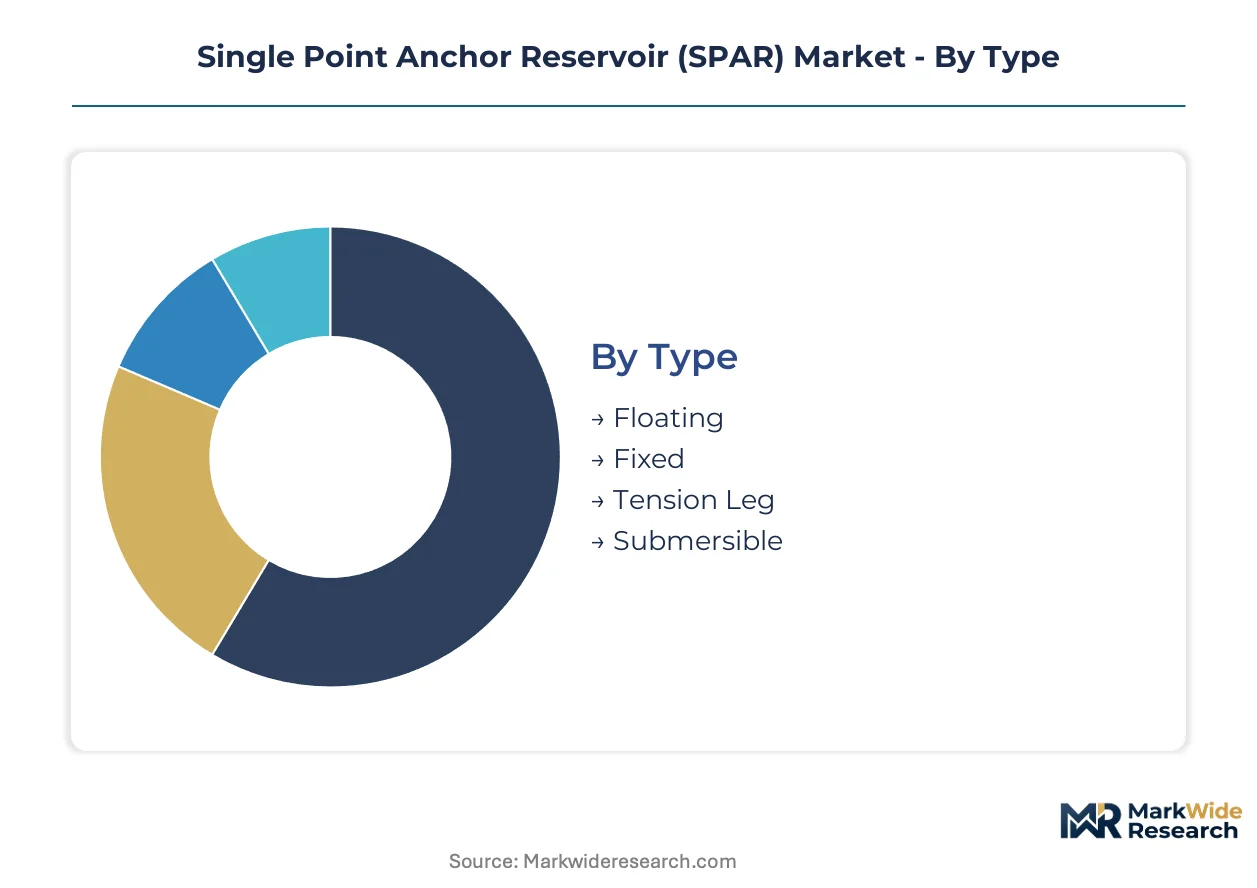
SPAR platform procurement splits across hull configuration, station-keeping technology, and end-use application. Each dimension carries distinct qualification requirements and regional deployment patterns that shape vendor selection criteria.
Type:
Floating configurations dominate export-led fabrication from South Korean and Singaporean yards, while fixed and submersible variants serve domestic Gulf of Mexico brownfield tiebacks.
- Floating:Cylindrical hull designs with catenary or taut-leg mooring dominate ultra-deepwater deployments. Operators in Brazil's Santos Basin specify these for pre-salt production, where water depths exceed 2,000 meters and dynamic response characteristics prove critical.
- Fixed:Compliant tower derivatives anchor to seabed through rigid structural elements. US Gulf operators favor these for hub platform applications in 300-800 meter depths where drilling rig integration demands minimal vessel motion.
- Tension Leg:Vertical tendon mooring eliminates heave response for dry-tree production. Demand concentrates in West African frontier blocks where harsh environment survival requirements intersect with steel tendon supply chain availability.
- Submersible:Buoyancy-controlled hull sections operate below wave action. Norwegian North Sea developments specify these for marginal field economics where topside weight minimization drives facility design.
Floating holds the largest share; momentum sits with tension leg configurations as operators push into West African ultra-deepwater frontiers.
Technology:
Cost tier separation is pronounced: dynamic positioning and integrated mooring systems command premium engineering margins, while ballasting and backup systems compete on standardization.
- Dynamic Positioning:Dual-redundant thruster arrays with DPS-3 classification enable disconnectable offloading operations. Norwegian regulators mandate this specification for tanker loading in harsh weather zones, compressing qualification timelines for system integrators.
- Mooring Systems:R5-grade studless chain and polyester rope configurations anchor hulls in 3,000-meter water depths. Japanese and European specialty mills control high-fatigue alloy supply, creating procurement bottlenecks during project sanctioning waves.
- Ballasting:Seawater and fixed ballast systems adjust hull draft for transportation and installation. Southeast Asian fabrication yards standardize these packages to accelerate hull delivery schedules.
- Backup Systems:Emergency disconnect and storm survival modes protect against mooring failure. API RP 2SK compliance drives specification convergence across Gulf of Mexico and Brazilian installations.
Mooring systems capture the highest engineering margins; backup systems are expanding most quickly as BSEE mandates real-time structural monitoring.
End User:
Application maturity varies sharply: oil and gas absorbs qualified fabrication capacity while offshore wind represents nascent demand with divergent certification pathways.
- Oil & Gas:Integrated production, drilling, and storage requirements drive hull scale and complexity. Petrobras and ExxonMobil anchor demand through long-term platform lease contracts with availability-based payment structures.
- Offshore Wind:SPAR-derived floating turbine foundations migrate oilfield hull geometries into renewable applications. Scottish and Portuguese demonstration projects test shared fabrication capacity across energy cycles.
- Marine Engineering:Installation contractors and heavy-lift vessel operators specify temporary mooring SPARs for pipeline laydown operations. North Sea decommissioning campaigns sustain episodic demand.
- Research Institutions:Oceanographic monitoring platforms utilize miniaturized SPAR hulls for deep-sea sensor deployment. Scripps Institution and IFREMER operate dedicated vessels with modified ballast systems.
Oil and gas dominates fabrication throughput; offshore wind shows the steepest expansion trajectory as floating turbine foundations scale toward commercial arrays.
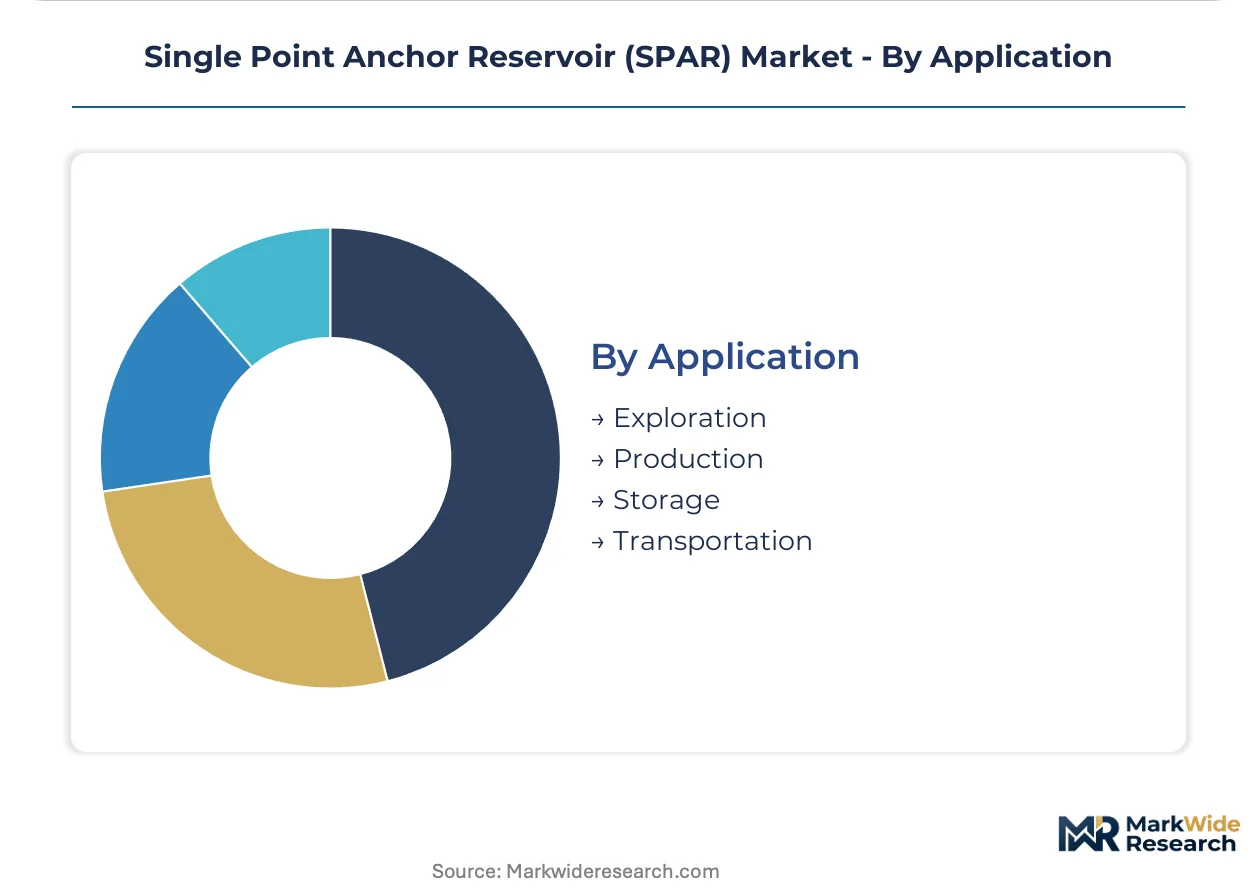
Application:
Volume concentration sits with production installations, while exploration and storage applications carry distinct technical risk profiles that shape contracting structures.
- Production:Dry-tree and subsea tieback configurations process hydrocarbons through integrated topside facilities. Gulf of Mexico brownfield redevelopment sustains demand for hull life extension and module upgrades.
- Exploration:Mobile offshore drilling unit support requires rapid disconnect capability and minimal station-keeping footprint. West African wildcat drilling programs favor leased floating SPARs over owned infrastructure.
- Storage:Crude oil buffering capacity integrates with offloading systems for shuttle tanker scheduling. Brazilian pre-salt fields specify these to manage production variability and export logistics.
- Transportation:Pipeline initiation points and subsea tieback hubs aggregate production from satellite wells. Mauritania-Senegal basin developments utilize SPAR-based export systems for first-phase production.
Production commands the largest installed base; exploration is gaining share fastest as frontier basin drilling intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and the US Gulf Coast demonstrate the lowest price elasticity, absorbing premium engineering costs for ultra-deepwater specifications, while Southeast Asian fabrication markets compete aggressively on hull delivery schedules. European North Sea operators occupy the middle tier, balancing compliance premiums against decommissioning liabilities. West African frontier markets exhibit the highest sensitivity, with first-phase developments driving intense competition among integrated contractors.
United States
The US Bureau of Safety and Environmental Enforcement mandates real-time structural monitoring and API RP 2SK mooring compliance for all new floating platform permits. Brownfield redevelopment in the Gulf of Mexico absorbs the majority of domestic fabrication capacity, with operators qualifying modified depreciation schedules under Inflation Reduction Act lease provisions. Houston anchors engineering headquarters activity, while Gulf Coast fabrication yards specialize in hull life extension and topside integration modules.
Brazil
Petrobras-led pre-salt production targets in the Santos Basin sustain the world's most concentrated SPAR procurement pipeline, with water depths exceeding 2,000 meters demanding floating configurations exclusively. The national petroleum regulator enforces station-keeping standards that exceed ISO 19901-7 baselines, compressing qualification timelines for foreign fabricators. Southeast Asian yards capture the majority of hull construction contracts, though Brazilian content requirements mandate increasing local module fabrication at Rio de Janeiro industrial clusters.
Norway
North Sea operators face the EU Green Deal's most compressed methane emission compliance timeline, with Norwegian regulators mandating full-facility venting detection coverage by 2027. Submersible SPAR variants dominate marginal field economics where topside weight minimization drives facility design. Stavanger and Bergen anchor subsea engineering clusters, with specialized yards focusing on tension leg mooring integration for harsh environment survival specifications.
South Korea
Samsung Heavy Industries and Hyundai Heavy Industries anchor dedicated offshore fabrication capacity, with government-backed shipyard restructuring programs preserving deepwater construction expertise. The Ministry of Trade, Industry and Energy classifies offshore platform hulls as strategic export products eligible for preferential financing. Geoje and Ulsan industrial complexes concentrate cylindrical hull construction, with standardized ballast system packages accelerating delivery schedules for Brazilian and West African export markets.
Mauritania
Ultra-deepwater frontier blocks in the Mauritania-Senegal basin lack established platform supply chains, creating first-mover opportunities for integrated engineering contractors willing to anchor regional service infrastructure. The national petroleum regulator adopts API standards by reference, reducing technical barriers for US Gulf Coast experienced operators. Nouakchott serves as logistics coordination hub, though major hull fabrication imports from South Korean yards dominate capital deployment patterns.
Single Point Anchor Reservoir (SPAR) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated engineering-to-installation contractors commanding premium margins on complex ultra-deepwater projects while Asian fabrication specialists compete on hull delivery velocity and standardized ballast packages. The market structure concentrates around three tiers: full-service lease-operate contractors with balance sheet capacity for hull ownership; integrated engineering houses with proprietary mooring system capabilities; and pure-play fabrication yards competing on capacity utilization. Dominant competitive moves include integrated lease-operate contracting displacing traditional engineering-procurement-construction arrangements, and strategic partnerships between hull fabricators and subsea system integrators to compress commissioning timelines.
Among Asian fabrication specialists, Samsung Heavy Industries and Hyundai Heavy Industries occupy positions exemplifying scale-driven cost leadership, with dedicated offshore yard capacity supporting standardized hull delivery schedules. European engineering integrators anchor the premium tier, with TechnipFMC representing the integrated engineering-to-installation archetype across deepwater project portfolios. SBM Offshore sits within the lease-operate contractor category, differentiating through proprietary hull design ownership and long-term availability-based payment structures with national oil companies.
| Leading Market Players |
|---|
| Bumi Armada Berhad |
| TechnipFMC |
| Samsung Heavy Industries |
| MODEC |
| Mitsubishi Heavy Industries |
| Hyundai Heavy Industries |
| Teekay Corporation |
| Aker Solutions |
| SBM Offshore |
| Others |
Value Network & Pricing Analysis
Long-term lease-operate contracts with availability-based payment structures lock in fabrication yard capacity and mooring system supply access years ahead of hull delivery, compressing price volatility for operators while elevating upfront capital commitments for contractors. This contracting pattern concentrates pricing power with integrated engineering houses possessing balance sheet capacity for hull ownership, particularly in Brazilian and West African markets where national oil companies favor operational expenditure models over capital-heavy platform purchases.
Pricing Analysis
API RP 2SK mooring guidelines dictate the pricing tier structure across Gulf of Mexico and Brazilian installations, with R5-grade studless chain configurations commanding premium engineering margins over standard R4 grades due to Japanese and European specialty mill supply concentration. Price differentiation hinges on certification grade and geographic delivery cost, with Southeast Asian yards competing aggressively on standardized ballast packages while Norwegian integrators extract premiums for DPS-3 dynamic positioning redundancy. Cost compression in mid-tier hull fabrication is intensifying because Brazilian content requirements mandate increasing local module work at Rio de Janeiro industrial clusters. National oil companies in Brazil demonstrate the lowest price elasticity, absorbing premium specifications for ultra-deepwater pre-salt development, while West African frontier operators exhibit highest sensitivity during first-phase project sanctioning.
Supply Chain Analysis
Strategic stockpiling of R4 and R5 mooring chain grades prevails among integrated contractors facing extended qualification timelines at third-party classification societies, while just-in-time hull section delivery dominates Southeast Asian yard operations serving Brazilian export markets. Supply concentration rests on South Korea, Japan, and Singapore for cylindrical hull construction, with Geoje and Ulsan industrial complexes anchoring standardized fabrication output. Raw material dependencies draw from high-grade steel alloys, polyester rope configurations, and fiber-optic strain sensing arrays for real-time mooring monitoring. Single-source vulnerability concentrates in European and Japanese specialty mills controlling fatigue-resistant alloy supply. Distribution runs through integrated engineering-to-installation contractors compressing commissioning timelines via direct hull-subsea system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
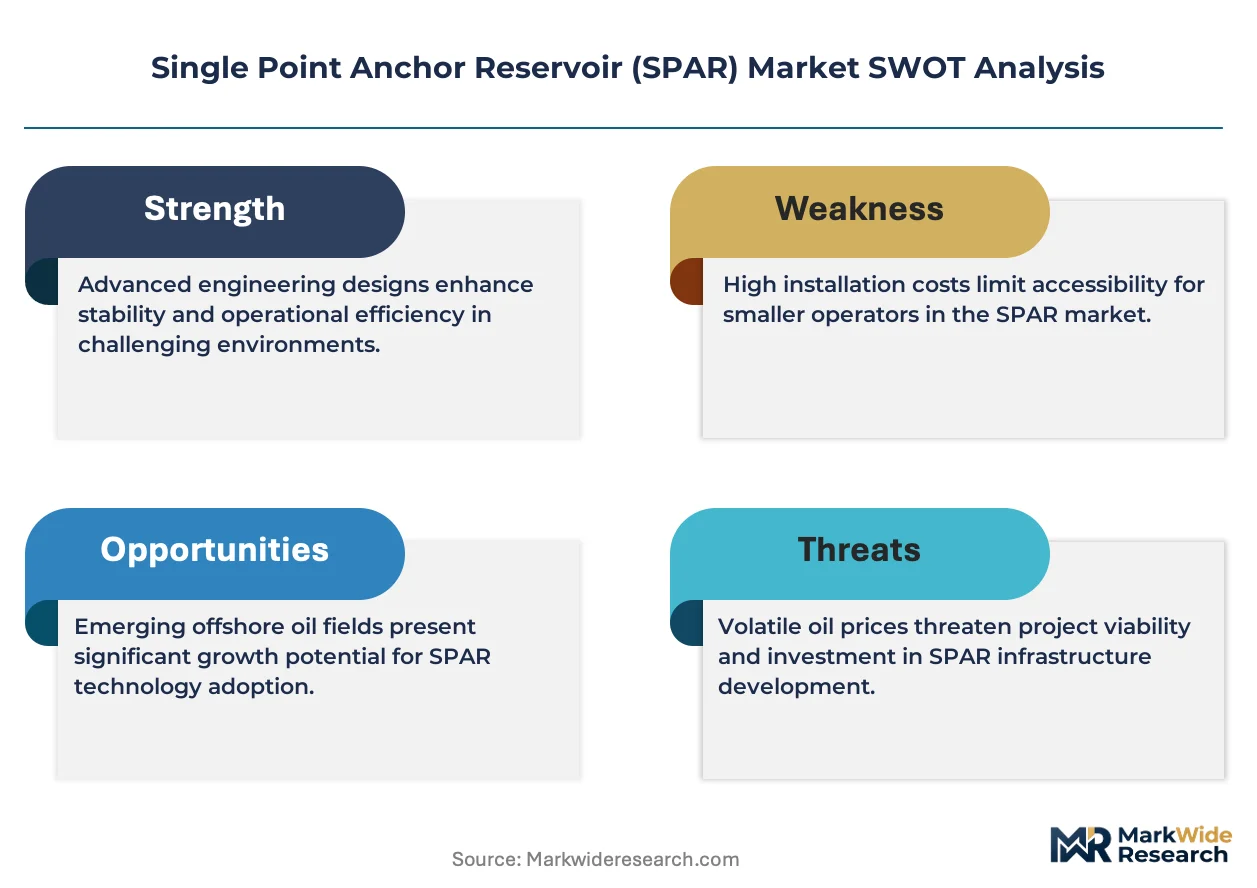
This market functions as a defensive-moat arena where regulatory entrenchment creates formidable barriers: ISO 19901-7 certification bottlenecks and BSEE real-time monitoring mandates concentrate qualification capacity among incumbent engineering houses with established classification society relationships.
For Market Incumbents: Fortify proprietary mooring system capabilities through captive R5-grade alloy supply arrangements with Japanese specialty mills, insulating fabrication margins from input cost volatility. Expand certified weld inspection technician training pipelines at dedicated offshore yards to preempt throughput constraints from aging specialist workforces. Defend against fixed platform substitution in shallow-water tieback economics by emphasizing SPAR hull motion characteristics for dry-tree drilling integration.
For New Entrants and Emerging Players: Lead with tension leg configuration specialization targeting West African frontier basins where harsh environment survival requirements intersect with limited established platform supply chains. Mauritania-Senegal ultra-deepwater blocks offer the most penetrable geography for first-mover regional service infrastructure. Anchor go-to-market positioning through API standards adoption by reference, reducing technical barriers for US Gulf Coast experienced operators entering nascent markets.
For Investors and Strategic Acquirers: Lease-operate contractors with proprietary hull design ownership and long-term national oil company relationships represent the most attractive acquisition archetype for portfolio exposure to deepwater production cycles. Monitor offshore wind floating foundation demonstration projects in Scottish and Portuguese waters as the critical signal for demand smoothing potential across energy cycles. Long-term viability hinges on balance sheet capacity to absorb hull ownership risk through multi-decade availability-based payment structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Mooring System Qualification | Compresses project timelines by securing R5-grade chain supply from Japanese specialty mills ahead of sanctioning waves. |
| Digital Twin Deployment | Enables predictive maintenance models for mooring fatigue at Gulf of Mexico installations under BSEE real-time monitoring mandates. |
| Offshore Wind Foundation Adaptation | Migrates SPAR-derived hull geometries into floating turbine applications at Scottish demonstration projects. |
| Regional Service Infrastructure Buildout | Anchors first-mover position in Mauritania-Senegal basin logistics coordination through Nouakchott hub establishment. |
| Automated Weld Inspection Certification | Addresses technician scarcity for thick-section cylindrical hulls at South Korean fabrication yards. |
Research Methodology
Initial hypotheses were tested against primary input from offshore project developers, platform integration engineers, classification society surveyors, and national oil company procurement directors, and refined through secondary validation against regulatory filings with the US Bureau of Safety and Environmental Enforcement, Brazilian national petroleum regulator submissions, ISO 19901-7 certification records, API RP 2SK compliance documentation, and Southeast Asian yard delivery schedules. Bottom-up hull fabrication capacity assessments triangulated with top-down deepwater expenditure forecasts across the analysis window.
Variance decomposition across type, technology, end user, and application segments shaped the analytical framework, with CAGRs derived from installation volume trajectories weighted by water depth specifications and mooring system complexity tiers. Modeled dimensions included hull configuration, station-keeping technology classification, and regional regulatory cluster alignment. Forecast inputs incorporated Petrobras pre-salt production targets, Gulf of Mexico brownfield redevelopment pipelines, and West African frontier block licensing rounds.
Underlying assumptions cover sustained ultra-deepwater frontier expansion, stable high-grade steel alloy supply from Japanese and European mills, and classification society capacity absorption rates, with deviation risk concentrated in weld inspection technician availability and offshore wind floating foundation demand migration. Revision becomes warranted when Brazilian local content requirements cross thresholds that fundamentally alter Southeast Asian yard competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market