
 Geotextiles and Geogrids Market | 2026-2036
Geotextiles and Geogrids Market Size, Share, and Industry Trends Forecast 2026-2036
Geotextiles and Geogrids Market Intelligence
Expanding manufacturing capacity in China for polypropylene and polyester raw materials is realigning the cost structure for geotextile producers. Koninklijke Ten Cate B.V. leverages its broad portfolio of woven and nonwoven products for global projects. HUESKER Synthetic GmbH specializes in high-performance geosynthetics for complex engineering challenges. Meanwhile, Officine Maccaferri S.p.A. competes through its integrated system solutions for civil and environmental engineering.
Geotextiles are permeable fabrics, typically produced from polymers like polypropylene or polyester, used for soil separation, filtration, and drainage. Geogrids are integrally formed polymer grid structures designed with high tensile strength at low elongation for soil reinforcement and stabilization. Nonwoven geotextiles command a significant share due to their utility in separation and filtration. Road reinforcement applications are expanding rapidly, driven by infrastructure development and the need for durable pavement systems.
Product quality and market access are governed by a matrix of international and national standards. These include ISO 10319 for tensile strength testing, CE marking requirements in Europe for construction products, and EPA guidelines in the United States for landfill liner systems. Such regulations mandate specific performance criteria for materials used in critical infrastructure. Stakeholders must navigate the trade-off between adopting lower-cost conventional materials and investing in higher-performance, recycled-content geosynthetics to meet sustainability goals.
Market Dynamics
The central dynamic shaping the market is the expansion of public infrastructure investment, particularly through initiatives like the US Inflation Reduction Act and India's National Infrastructure Pipeline, which directly stimulates demand for soil reinforcement and stabilization solutions.
Growth Catalysts
- Infrastructure Investment:Government-led spending on transportation projects, including new highways, rail lines, and airport runways in countries like India and the United States, provides a foundational demand driver for both geotextiles and geogrids.
- Regulatory Mandates:Environmental regulations, such as those from the EPA in the US for landfill liner and capping systems, mandate the use of geosynthetics to ensure containment and prevent soil contamination, creating a non-discretionary market segment.
- Sustainability Goals:The push for circular economy principles encourages the use of geosynthetics made from recycled polymers, such as rPET, as specifiers and contractors seek to meet corporate sustainability targets and green building certifications.
Market Restraints
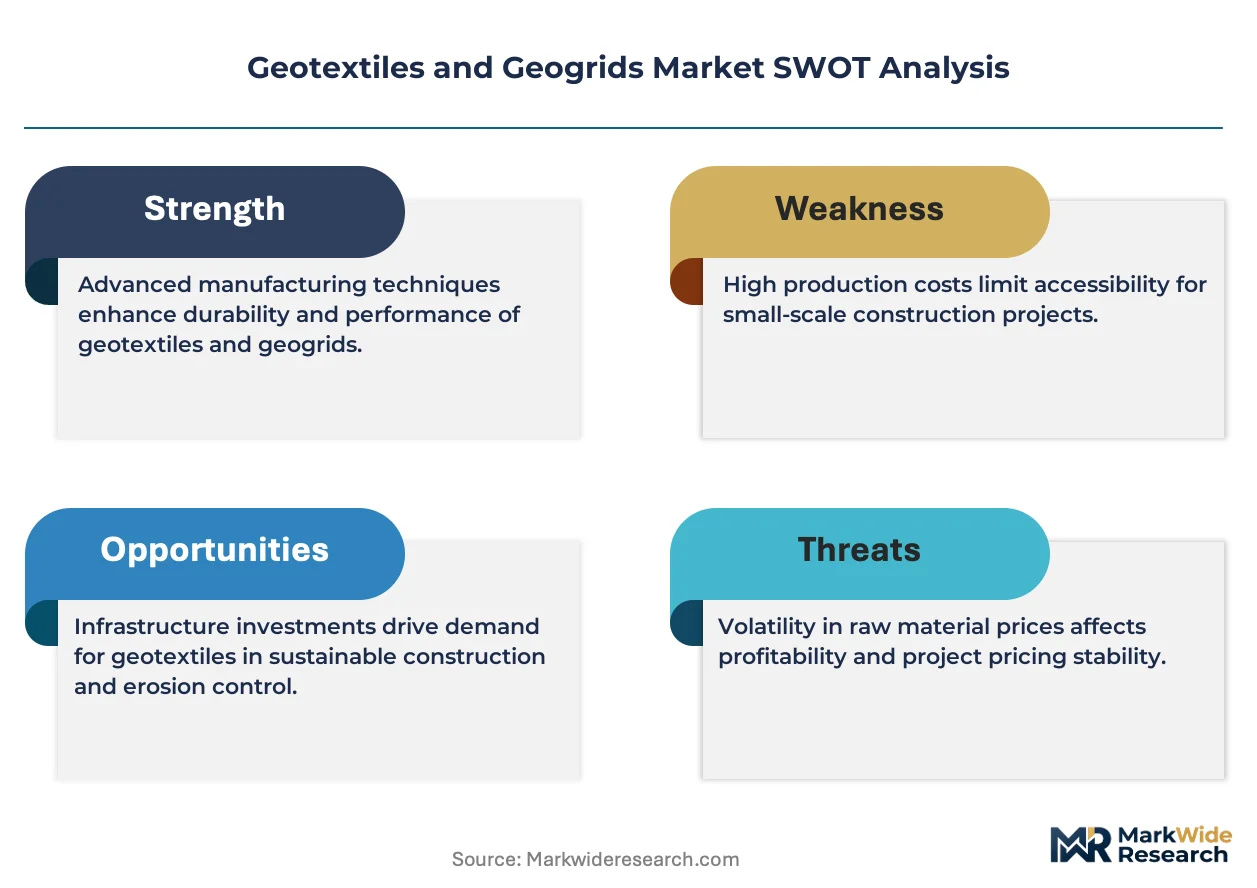
- Raw Material Volatility:Prices for key raw materials like polypropylene and polyester are linked to volatile crude oil markets, creating unpredictable cost structures and margin pressure for manufacturers, which can be difficult to pass on to customers.
- Substitution by Conventional Materials:In cost-sensitive projects, traditional materials like aggregate, sand, and concrete remain a significant substitution threat, particularly where decision-makers are not fully educated on the lifecycle cost benefits of geosynthetics.
- Technical Knowledge Gaps:A persistent lack of awareness and technical expertise among some civil engineering consultants and local contractors regarding proper design and installation can lead to misapplication or a reluctance to specify geosynthetic solutions over familiar methods.
Strategic Opportunities
- Smart Geosynthetics:Integrating fiber optic sensors or other monitoring technologies into geotextiles and geogrids creates an opportunity to offer real-time structural health monitoring for critical infrastructure like dams, levees, and railway beds.
- Coastal Protection Systems:Growing concerns over climate change and sea-level rise open a significant market for geosynthetic-based solutions in coastal and riverbank erosion control, shoreline stabilization, and breakwater construction.
- Geographic Expansion:Significant untapped demand exists in developing regions across Sub-Saharan Africa and parts of Latin America, where major infrastructure upgrades are planned but geosynthetic penetration remains low compared to developed economies.
Industry Challenges
- Certification Complexity:Navigating the matrix of different national and regional standards, such as CE marking in Europe and individual Department of Transportation (DOT) approvals in the US, creates lengthy and costly qualification processes for new products.
- Installation Skill Scarcity:The performance of a geosynthetic system is highly dependent on correct installation. A shortage of trained and experienced installation crews can lead to project delays and performance failures, damaging market confidence.
- Standardization of Recycled Content:The absence of universally accepted standards for testing and certifying the long-term performance and durability of geosynthetics produced with high percentages of recycled content creates uncertainty for specifiers and asset owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geotextiles and Geogrids Market |
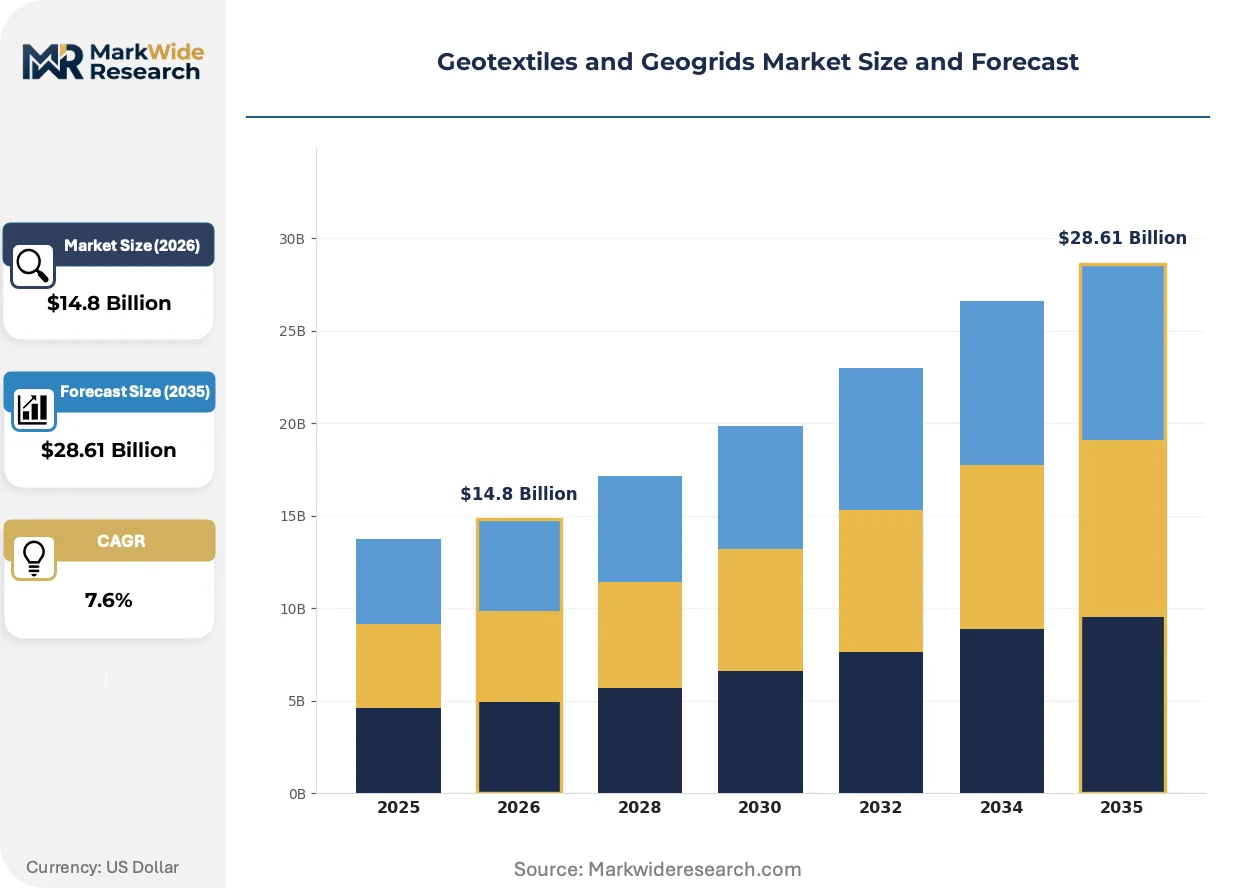
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Geotextiles, Nonwoven Geotextiles, Knitted Geogrids, Extruded Geogrids, Composite Geomaterials Application: Soil Stabilization, Erosion Control, Road Reinforcement, Retaining Walls, Landfill Liners, Drainage Systems End User Industry: Civil Engineering, Transportation Infrastructure, Mining Operations, Coastal Protection, Agricultural Projects Installation Method: Surface Installation, Trench Installation, Rolling Placement, Anchoring Systems |
| Companies Covered | Officine Maccaferri S.p.A., HUESKER Synthetic GmbH, Koninklijke Ten Cate B.V., Thrace Group, Propex Operating Company, LLC, GSE Environmental, Low & Bonar, SKAPS Industries, NAUE GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geotextiles and Geogrids Market Strategic Shifts & Innovations
Performance and sustainability are becoming the primary axes of innovation. The market is evolving from supplying basic commodity materials to providing advanced, engineered solutions that incorporate recycled content, offer verifiable lifecycle benefits, and integrate digital monitoring capabilities.
Bio-based and biodegradable polymers are emerging as a niche material for temporary geosynthetic applications like short-term erosion control and vegetation establishment. Environmental engineering firms and agricultural projects are the primary adopters, driven by a need to minimize plastic residue in sensitive ecosystems. This development is absorbing a portion of the demand for conventional polypropylene nonwovens in applications where long-term durability is not required.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling large construction and engineering firms to meticulously track and report on their supply chain's environmental impact. This regulation directly increases the value of geosynthetics with documented recycled content and transparent lifecycle assessments. Producers in Europe are responding by investing in certification and traceability to provide clients with the data needed to comply with CSRD mandates.
A shift from transactional product sales to the procurement of integrated, engineered systems is altering buyer behavior. This model disrupts traditional distributors by bundling design assistance, material supply, and installation quality control into a single performance-based package. This trend is most visible in complex infrastructure projects in North America and Western Europe, especially for critical applications like high-performance pavements and mechanically stabilized earth walls.
Geotextiles and Geogrids Market Segmentation
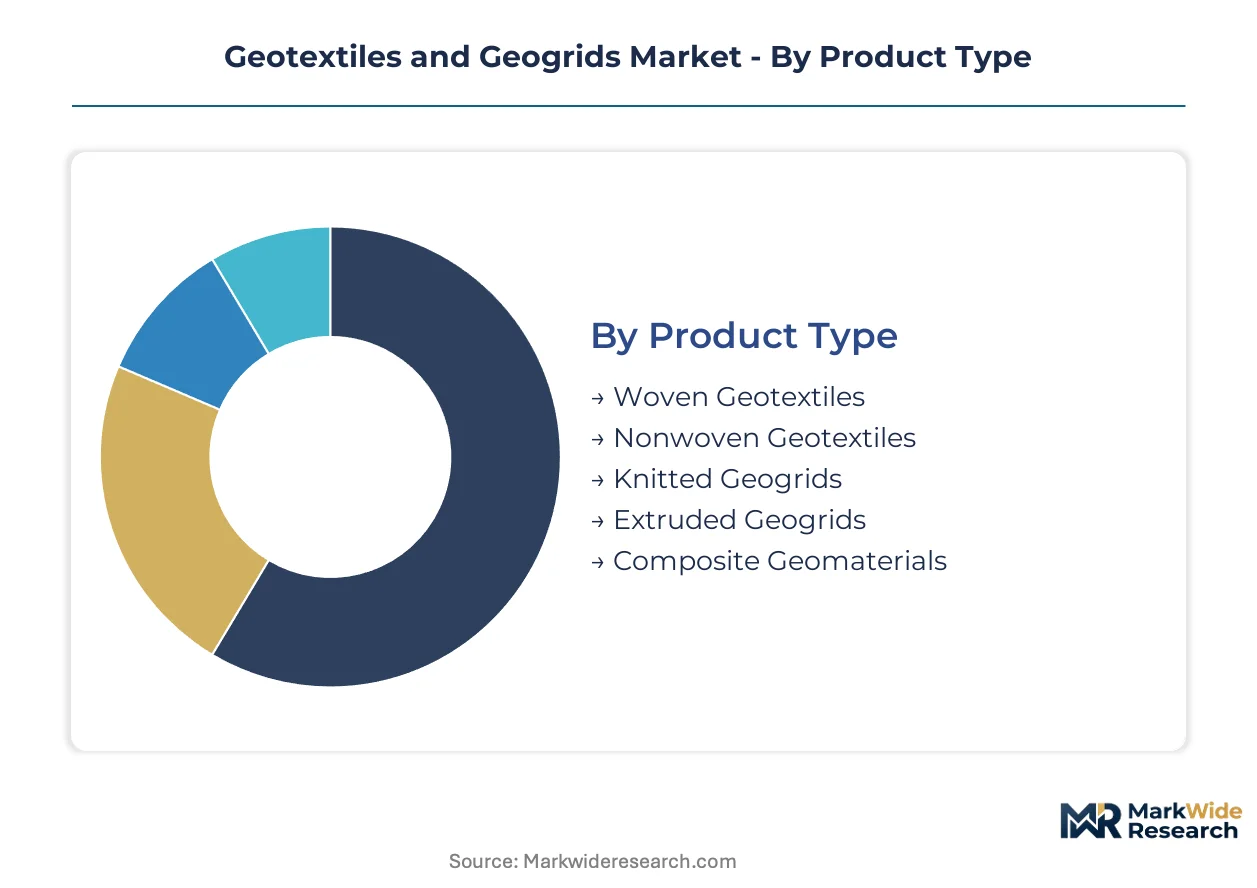
The segmentation analysis for the Geotextiles and Geogrids Market provides a structured view of how different product characteristics, applications, and end-user demands shape market dynamics. Understanding these distinct segments helps stakeholders identify specific growth vectors and strategic entry points.
Product Type:
Product types differentiate based on their manufacturing process and structural integrity, from standalone barriers to integrated reinforcement systems.
- Nonwoven Geotextiles:Permeable fabrics, made from polypropylene or polyester, form a random fiber network. Demand concentrates in separation and filtration for drainage and road construction.
- Extruded Geogrids:High-density polyethylene grid structures offer high tensile strength. Primary demand comes from road reinforcement and mechanically stabilized earth walls, where long-term stability is critical.
- Woven Geotextiles:Interlaced synthetic fibers provide high tensile strength for separation and reinforcement in civil engineering.
- Knitted Geogrids:Knitted yarns form these geogrids, used for soil reinforcement in challenging ground conditions.
- Composite Geomaterials:These combine two or more geosynthetic functions, addressing complex engineering challenges like drainage and reinforcement.
Volume placements concentrate in Nonwoven Geotextiles; the faster expansion belongs to Extruded Geogrids.
Application:
Applications address diverse engineering challenges from soil management to structural support, each with distinct performance requirements.
- Road Reinforcement:Geogrids and geotextiles integrate into pavement layers to enhance load distribution and extend road lifespan. Infrastructure investment in India and the United States drives demand.
- Landfill Liners:Geosynthetics form critical components in landfill containment systems, ensuring impermeability and protection against leachate leakage. EPA guidelines mandate their use.
- Soil Stabilization:Geotextiles and geogrids enhance bearing capacity of weak soils, preventing subsidence.
- Erosion Control:Materials protect soil surfaces from wind and water erosion, promoting vegetation growth.
- Retaining Walls:Geogrids are crucial for mechanically stabilized earth (MSE) walls, reinforcing soil structures for highway approaches.
- Drainage Systems:Geotextiles filter fine soil particles in drainage, preventing clogging in subsurface drains.
Demand for Landfill Liners is driven by regulatory compliance, while Road Reinforcement represents a significant growth area.
End User Industry:
End-user industries dictate scale and performance criteria for geosynthetic solutions, reflecting varying project complexities.
- Transportation Infrastructure:This segment includes highways, railways, and airport runways, where geosynthetics are essential for soil stabilization and road reinforcement. Government initiatives boost demand.
- Coastal Protection:Climate change concerns drive geosynthetic solutions for erosion control and shoreline stabilization. This sector requires durable materials for marine environments.
- Civil Engineering:This sector utilizes geotextiles and geogrids for foundations, embankments, and ground improvement.
- Mining Operations:Geosynthetics serve in heap leach pads and tailings dams, providing containment and reinforcement.
- Agricultural Projects:Applications include erosion control, drainage for irrigation, and soil reinforcement for access roads.
Government initiatives heavily influence demand from Transportation Infrastructure, whereas Coastal Protection is gaining traction due to environmental concerns.
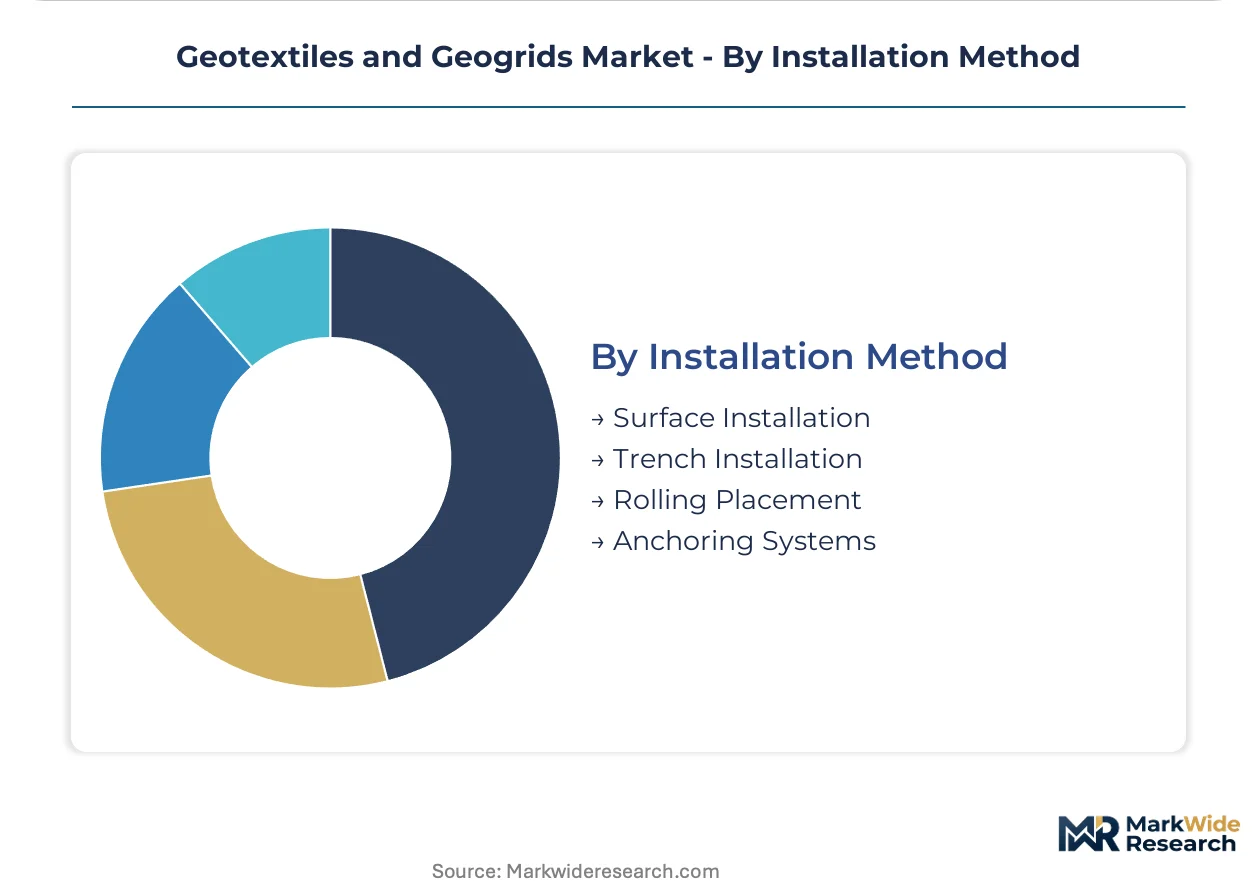
Installation Method:
Installation methods vary based on project requirements and site conditions, influencing efficiency and overall costs.
- Rolling Placement:This method unrolls geosynthetic materials onto prepared surfaces, common for large-area applications like roadbeds or landfill caps. It prioritizes speed.
- Anchoring Systems:These methods secure geosynthetics to the ground using pins or anchors, critical for steep slopes and retaining walls. Anchoring ensures stability.
- Surface Installation:Geotextiles are laid directly on the ground for temporary erosion control or separation layers.
- Trench Installation:This technique places geosynthetics within excavated trenches for drainage systems or filtration barriers.
Simpler methods like Surface Installation are widespread, but Anchoring Systems offer enhanced stability for critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene and polyester raw material production in Asia anchors global geotextiles and geogrids supply. This concentration influences cost structures for producers worldwide. Major infrastructure projects across diverse regions drive significant demand.
China
Extensive transportation infrastructure development and environmental protection projects drive demand for geosynthetics. China's dual carbon goals promote sustainable construction practices in major projects. The Yangtze River Delta region sees significant investment in high-speed rail and coastal protection initiatives.
United States
Large-scale public infrastructure investment, particularly road reinforcement and civil engineering, sustains market expansion. The US Inflation Reduction Act provides funding for civil engineering; EPA guidelines mandate geosynthetics for landfill liner systems. Major metropolitan areas like New York and Los Angeles drive demand for advanced ground improvement solutions.
India
The National Infrastructure Pipeline and government-led construction initiatives provide foundational demand for geotextiles and geogrids. India's infrastructure development plans prioritize durable pavement systems for its expanding road networks. Urban centers such as Delhi-NCR and Mumbai experience substantial demand for soil stabilization in new developments.
Germany
Advanced civil engineering projects and stringent environmental standards for construction create consistent demand. CE marking requirements in Europe mandate specific performance criteria for construction products. The Rhine-Ruhr metropolitan region utilizes high-performance geosynthetics for complex ground engineering and railway infrastructure.
Brazil
Significant infrastructure upgrades, including road networks and mining operations, fuel geosynthetic demand. National development programs aim to modernize transportation links across the country. The state of São Paulo drives demand for geosynthetic solutions in large-scale urban and industrial projects.
Geotextiles and Geogrids Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced engineered systems and sustainable product lines. The market exhibits tiered competition, with large manufacturers focusing on scale and smaller players targeting niche solutions. Strategic archetypes include integrated system providers, raw material specialists, and regional solution providers. Geographic expansion into developing regions and technology licensing are also common competitive moves.
On the premium-tier vector, Koninklijke Ten Cate B.V. exemplifies broad portfolio strength across woven and nonwoven products, serving diverse global projects. HUESKER Synthetic GmbH, a German-based GmbH, represents specialization in high-performance geosynthetics, addressing complex engineering challenges with precision. Officine Maccaferri S.p.A., an Italian S.p.A., sits within the integrated system solutions archetype, providing comprehensive offerings for civil and environmental engineering. These companies anchor distinct segments of the market by leveraging their operational models and product focuses. Their presence collectively underscores the importance of both material versatility and specialized application expertise in the industry.
| Leading Market Players |
|---|
| Officine Maccaferri S.p.A. |
| HUESKER Synthetic GmbH |
| Koninklijke Ten Cate B.V. |
| Thrace Group |
| Propex Operating Company, LLC |
| GSE Environmental |
| Low & Bonar |
| SKAPS Industries |
| NAUE GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
European Union's Corporate Sustainability Reporting Directive (CSRD) gates qualified supply and premium-tier pricing access for geosynthetics. This mandate compels large construction firms to report supply chain environmental impact, increasing demand for certified recycled-content materials.
Pricing Analysis
Integrated, engineered systems bundle design and installation quality, moving pricing towards value-based models for complex projects. Price differentiation stems from product quality, specific certifications like CE marking, and the level of customization offered. Pricing pressure affects commodity nonwoven geotextiles due to expanded manufacturing capacity in China. Cost-sensitive projects remain highly price-sensitive, often opting for conventional materials over geosynthetics.
Supply Chain Analysis
Single-source vulnerability sits with the global crude oil markets, directly impacting prices for polypropylene and polyester raw materials. Geographic supply concentration for these polymers anchors in China and other Asian manufacturing hubs. The supply chain relies on consistent availability of virgin and recycled polymers like rPET. Commodity price volatility represents a significant structural risk for manufacturers. Distribution runs through both traditional product sales and integrated system solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Geotextiles and Geogrids market operates as a cost-of-compliance story, particularly due to EPA guidelines for landfill liner systems. These regulations create a significant barrier-to-entry moat for manufacturers able to meet stringent performance and certification criteria.
For Market Incumbents:Anchor existing market share by investing in advanced material R&D, particularly for high-performance sustainable geosynthetics. Secure long-term supply contracts for recycled polymers like rPET to mitigate raw material volatility. Pursue strategic acquisitions of niche technology providers specializing in smart geosynthetics to counter the threat of conventional material substitution. Invest heavily in certifications like CE marking to reinforce market access.
For New Entrants and Emerging Players:Launch via direct sales teams targeting civil engineering consultants and environmental firms to educate on geosynthetic benefits. Focus on white-space opportunities like smart geosynthetics for real-time infrastructure monitoring. Target developing regions in Sub-Saharan Africa and Latin America, where geosynthetic penetration remains low despite planned infrastructure upgrades. Emphasize lifecycle cost benefits and sustainability credentials as a key go-to-market angle.
For Investors and Strategic Acquirers:Increased government spending on climate resilience projects is the leading indicator that validates long-term market growth. The Geotextiles and Geogrids market demonstrates strong viability over the next 5-10 years, driven by persistent infrastructure needs and environmental regulations. Target acquisition profiles include vertically integrated mid-cap specialists with robust R&D in smart or sustainable geosynthetics. Watch for accelerated adoption rates of bio-based or recycled-content geosynthetics in major public infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Reduces raw material cost volatility for geotextile producers. |
| Green Manufacturing Transition | Meets corporate sustainability targets and CSRD compliance for European clients. |
| Long-term Supply Agreement | Stabilizes cost structures and ensures consistent production for geotextile manufacturers. |
| Joint Venture | Integrates real-time monitoring capabilities into infrastructure projects like dams. |
| Geographic Expansion | Taps into underpenetrated markets with significant planned infrastructure upgrades. |
Research Approach
Independent corroboration across industry association reports, government infrastructure spending plans, and corporate financial disclosures underwrites the qualitative findings. Primary interviews with civil engineering consultants, material scientists, procurement officers, and project managers provided critical insights. Secondary data validation utilized ISO standards documents, EPA guidelines, and CE marking specifications. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Rate-of-change decomposition formed the core analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and material composition. Compound annual growth rates were derived from historical trends, projected infrastructure spending, and technology adoption curves. Public infrastructure project volumes and regulatory changes served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for smart geosynthetics would alter the outlook. Forecasts reflect assumptions concerning raw material price stability and consistent infrastructure investment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Construction Textile Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Webbing Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market