
 Global Conductive Textiles Market | 2026-2036
Global Conductive Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conductive Textiles Market Foresight
Integration of microelectromechanical systems into woven substrates is fragmenting the traditional textile-electronics supply chain. Toray Industries leverages its polymer science heritage to anchor high-performance carbon-based yarn production in Japanese manufacturing corridors. Bekaert sustains metallization expertise that dominates copper-wire textile architectures for industrial automation harnesses. Seiren Co., Ltd. specializes in precision coating technologies that extend conductive polymer durability for wearable electronics brands.
Conductive textiles are engineered fabrics incorporating electrically functional elements such as silver-coated fibers, carbon nanotube yarns, or metal-plated filaments to enable signal transmission, thermal regulation, or electromagnetic interference shielding across flexible substrates. Silver-coated fibers command premium positioning in medical and defense applications where antimicrobial properties and signal fidelity justify material costs. Carbon-based yarns occupy the fastest-expanding tier as sports equipment manufacturers and automotive seating suppliers adopt stretchable sensing architectures. Coating technology leads fabrication methods for achieving uniform conductivity without compromising textile hand-feel or wash durability.
The U.S. Department of Defense's MIL-STD-285 shielding effectiveness requirements and the EU's REACH restrictions on nickel migration constrain material choices and certification pathways for suppliers seeking transatlantic market access. Japan's METI promotes conductive textile R&D through national technology roadmaps targeting healthcare monitoring applications. Stakeholders must monitor evolving electromagnetic compatibility standards from the IEC and regional biodegradability mandates that will determine which conductive polymer chemistries retain commercial viability.
Market Dynamics
Integration of microelectromechanical systems into woven substrates is fragmenting the traditional textile-electronics supply chain and forcing material suppliers to develop polymer formulations that satisfy both IEC electromagnetic compatibility standards and EU biodegradability mandates.
Growth Catalysts
- Military Procurement Expansion:The U.S. Department of Defense's sensor-integrated uniform programs and allied nations' electromagnetic shielding garment orders are pulling advanced conductive yarn volumes through defense contractors.
- REACH-Driven Material Substitution:Nickel migration restrictions under EU REACH are accelerating silver-coated fiber and carbon nanotube yarn adoption in medical wearable applications where antimicrobial performance is mandatory.
- East Asian Manufacturing Clustering:South Korean and Japanese textile-electronics hybrid production lines are scaling precision coating capacities that reduce unit costs for stretchable sensing architectures.
Market Restraints
- Silver Price Volatility:Silver-coated fiber input costs fluctuate with precious metal markets, compressing margins for medical and defense suppliers locked into fixed-price contracts.
- Japanese Polymer Concentration:High-performance carbon-based yarn production clusters heavily in Japanese manufacturing corridors, creating geographic supply risk for automotive seating and sports equipment brands.
- MIL-STD-285 Certification Barriers:Shielding effectiveness testing requirements constrain small-batch producers from accessing transatlantic defense procurement channels.
Strategic Opportunities
- Indian Domestic Production:BIS standards adoption and PLI scheme incentives for advanced textiles are opening fabrication opportunities for copper-wire textile architectures in industrial automation harnesses.
- Healthcare Monitoring Convergence:Japan's METI technology roadmaps are aligning conductive polymer R&D with PMDA regulatory pathways for continuous physiological monitoring garments.
- Recyclable Polymer Formulations:The EU Ecodesign for Sustainable Products Regulation is creating first-mover advantage for suppliers mastering closed-loop conductive coating chemistries.
Industry Challenges
- Electromagnetic Compatibility Talent Scarcity:Textile engineers with IEC 61000-series testing expertise remain concentrated in Japanese and German certification labs, slowing product validation cycles.
- Wash Durability Certification Timelines:AATCC and ISO wash-fastness protocols for conductive coatings require extended aging studies that delay wearable electronics launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conductive Textiles Market |
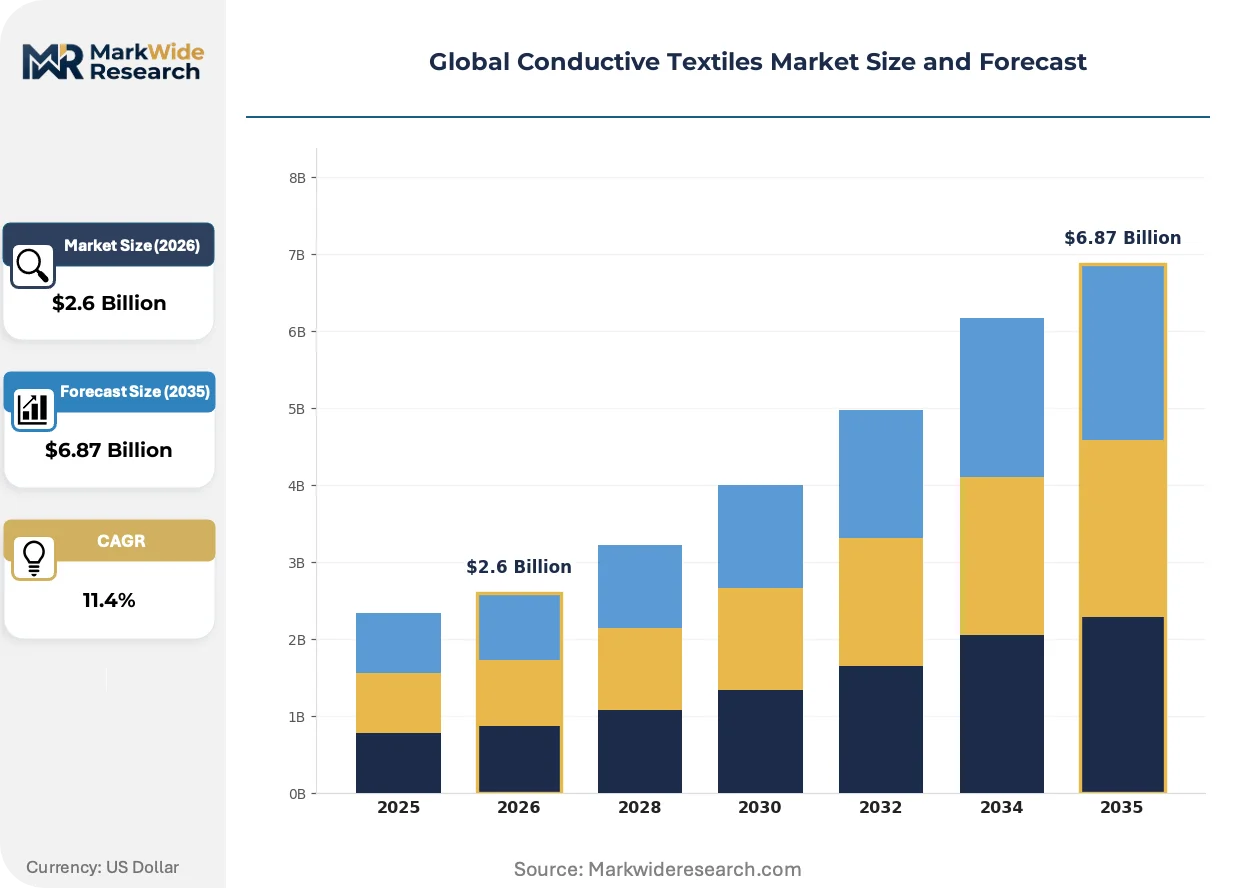
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-Coated Fibers, Carbon-Based Yarns, Metal-Plated Fabrics, Conductive Polymers, Copper-Wire Textiles Application: Smart Clothing, Wearable Electronics, Electromagnetic Shielding, Sensor Fabrics, Flexible Circuits End User Industry: Consumer Electronics, Defense & Aerospace, Industrial Automation, Sports Equipment, Personal Protective Equipment Technology: Knitting, Weaving, Coating, Embroidery, Printing |
| Companies Covered | Toray Industries, Bekaert, Seiren Co., Ltd., Laird Performance Materials, AiQ Smart Clothing, Holland Shielding Systems BV, Shieldex, HeiQ Materials AG, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conductive Textiles Market Shifts & Advancements
Material science advances are compressing the performance gap between metallic and polymer-based conductive elements while regulatory pressure on chemical inputs is redirecting R&D investment toward bio-derived formulations.
Silver nanowire coating technology is migrating from medical electrode applications into consumer fitness apparel where signal fidelity requirements are less stringent. Athletic wear brands in South Korea are adopting these formulations for heart-rate monitoring sports bras and compression garments. The shift is compressing pricing premiums for antimicrobial conductive textiles and forcing traditional silver-coated fiber suppliers to defend position through MIL-STD-285 certification exclusivity.
The EU Ecodesign for Sustainable Products Regulation is mandating recyclable content thresholds for textiles sold in member states, compelling conductive polymer suppliers to reformulate petroleum-based coatings. Manufacturers are responding by accelerating bio-polymer substrate development and establishing take-back partnerships with European end-of-life textile processors. Medical wearable suppliers face the steepest compliance curve given sterilization requirements that conflict with biodegradable material stability.
Defense and healthcare buyers are consolidating supplier relationships around vertically integrated producers capable of delivering certified conductive fabrics without subcontracted coating steps. This concentration is displacing merchant market distributors in Germany and the United States who previously aggregated small-batch orders from Asian coating houses. The pattern is most visible in U.S. Department of Defense procurement, where prime contractors now require in-house polymer compounding and metallization capabilities for electromagnetic shielding garment awards.
Global Conductive Textiles Market Segmentation
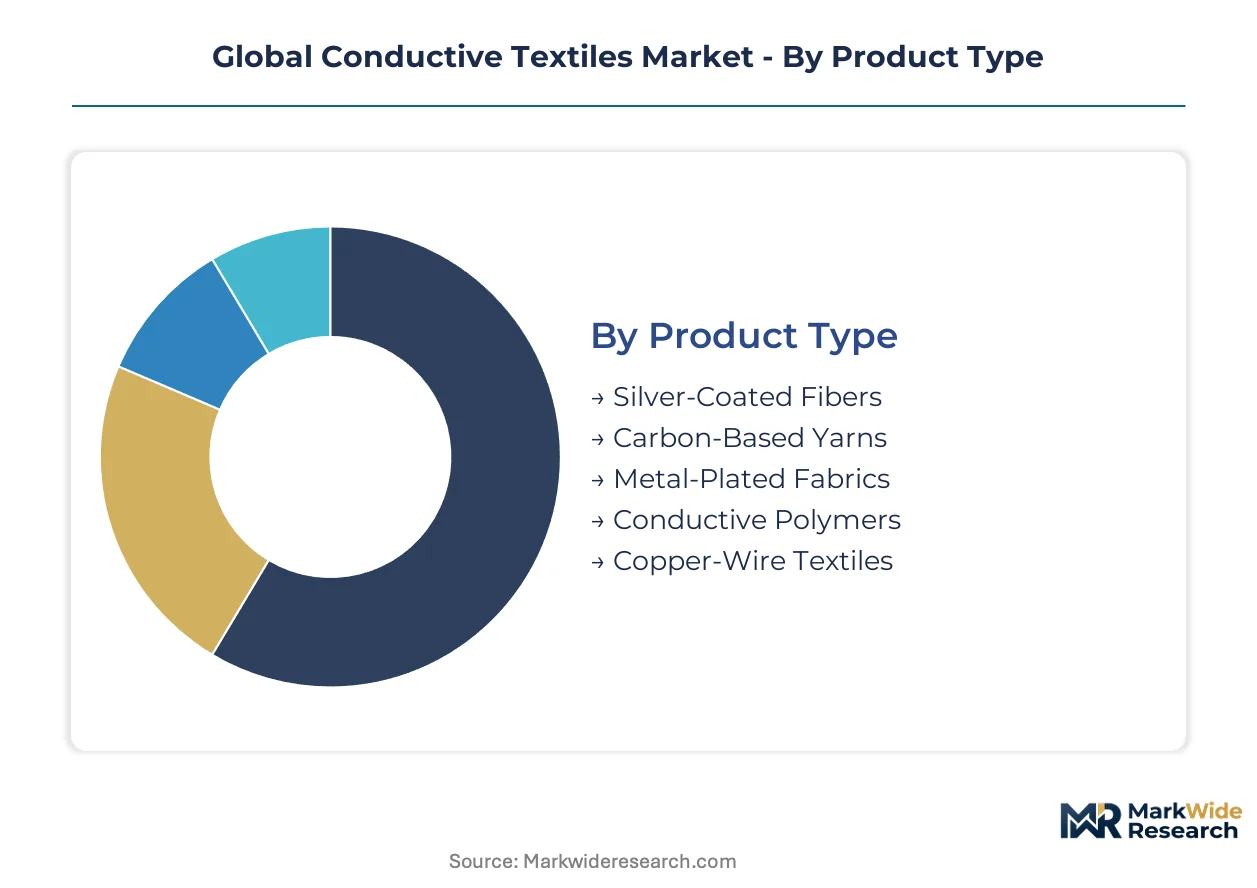
Conductive textiles fragment across four intersecting dimensions that determine pricing power, certification requirements, and supply chain configuration. Product chemistry dictates raw material exposure to precious metal volatility. Application specificity governs electromagnetic compatibility testing intensity. End-user industry concentration shapes procurement consolidation patterns. Fabrication technology controls margin structure through capital intensity differentiation.
Product Type:
Mature metallized fibers coexist with emerging polymer formulations as regulatory pressure reshapes material hierarchies.
- Silver-Coated Fibers:Continuous filament substrates plated with elemental silver achieve surface resistivity below 0.1 ohm/sq for signal transmission applications. Defense contractors in the United States and medical device manufacturers in Germany concentrate procurement around antimicrobial performance specifications that justify premium positioning against nickel migration restrictions under EU REACH.
- Carbon-Based Yarns:Polyacrylonitrile-derived carbon fiber tows and carbon nanotube dispersions enable stretchable sensing architectures with mechanical compliance exceeding 30% elongation. South Korean sports equipment manufacturers and Japanese automotive seating suppliers are scaling orders fastest as Toray Industries expands precursor production capacity in Mishima.
- Metal-Plated Fabrics:Electroless nickel-copper deposition onto woven substrates delivers electromagnetic interference shielding effectiveness exceeding 60 dB across military frequency bands.
- Conductive Polymers:Intrinsically conductive polyaniline and PEDOT:PSS formulations eliminate metallization steps but face wash durability limitations in garment applications.
- Copper-Wire Textiles:Fine-gauge copper filaments woven into industrial harness architectures dominate factory automation ground plane applications where flex cycle requirements exceed 100,000 repetitions.
Silver-Coated Fibers retain volume leadership; Carbon-Based Yarns hold the steepest expansion curve.
Application:
Application segmentation tracks the migration from discrete electronic components toward fully integrated textile systems.
- Smart Clothing:Fully integrated garments with embedded microcontrollers, power distribution networks, and biometric sensors require conductive pathways that survive domestic laundering cycles. European athletic wear brands and Japanese healthcare monitoring developers are driving specification convergence around IEC 60601-1 electromagnetic compatibility for wearable medical devices.
- Wearable Electronics:Wrist-worn and head-mounted devices utilize conductive textile straps and headbands for electrical grounding and antenna functionality. Consumer electronics manufacturers in South Korea and the United States are consolidating supplier relationships around vertically integrated producers capable of delivering certified conductive fabrics without subcontracted coating steps.
- Electromagnetic Shielding:Faraday cage enclosures for sensitive electronics and personnel protection rely on conductive textile architectures meeting MIL-STD-285 shielding effectiveness requirements.
- Sensor Fabrics:Piezoresistive and capacitive sensing matrices enable pressure mapping and gesture recognition in automotive seating and industrial safety equipment.
- Flexible Circuits:Textile-based printed circuit board replacements accommodate three-dimensional product geometries impossible with rigid substrates.
Wearable Electronics commands the largest installed base; Smart Clothing is climbing the fastest toward mass-market penetration.
End User Industry:
End-user segmentation reveals divergent procurement patterns between specification-driven institutional buyers and cost-sensitive consumer markets.
- Defense & Aerospace:Electromagnetic shielding garments and sensor-integrated uniforms require traceable supply chains certified to MIL-STD-285 shielding effectiveness and AATCC wash-fastness protocols. The U.S. Department of Defense's expanding procurement programs are pulling advanced conductive yarn volumes through prime contractors who now mandate in-house polymer compounding capabilities.
- Consumer Electronics:High-volume wearable device straps and charging pads prioritize unit cost reduction over extended durability. East Asian manufacturing clusters in South Korea and Japan are scaling precision coating capacities that reduce unit costs for stretchable sensing architectures.
- Industrial Automation:Robotic cable harnesses and static-dissipative workwear demand conductive textile architectures with verified flex cycle performance.
- Sports Equipment:Heart-rate monitoring compression garments and heated ski apparel integrate conductive elements for physiological monitoring and thermal regulation.
- Personal Protective Equipment:Arc-flash rated garments and cleanroom apparel incorporate conductive fibers for static dissipation and thermal protection.
Defense & Aerospace retains specification leadership; Consumer Electronics is gaining share fastest through volume scaling.
Technology:
Technology segmentation distinguishes capital-intensive continuous processes from flexible batch fabrication methods.
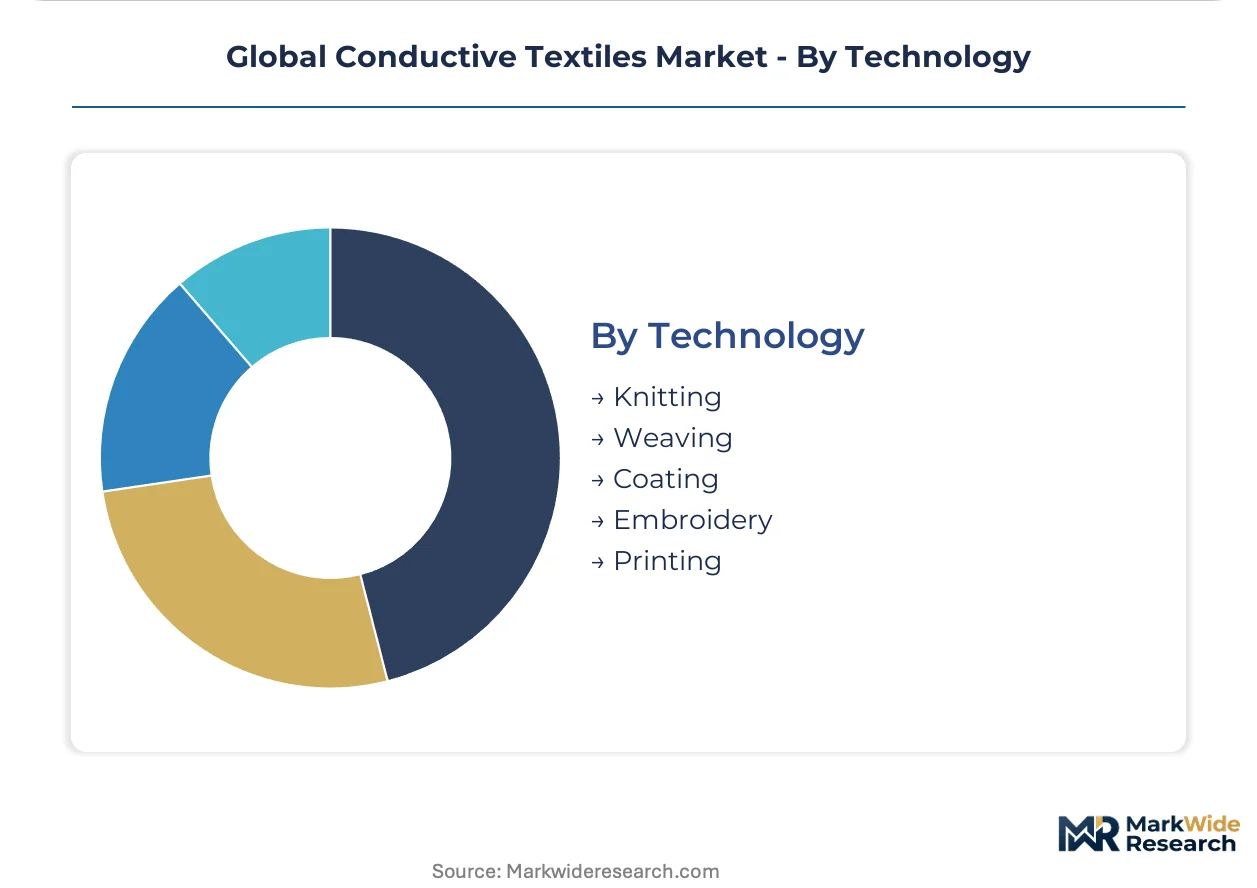
- Coating:Roll-to-roll sputtering, chemical vapor deposition, and dip-coating processes apply conductive layers onto textile substrates with thickness control below 100 nanometers. Japanese precision coating specialists and South Korean textile-electronics hybrid producers are scaling capacity fastest as the EU Ecodesign for Sustainable Products Regulation drives reformulation toward recyclable conductive polymer chemistries.
- Weaving:Loom-based integration of conductive warp and weft yarns creates durable conductive pathways with mechanical properties matching base textile substrates. German industrial textile manufacturers and Japanese carbon fiber weavers dominate high-performance applications where structural integrity coexists with electrical functionality.
- Knitting:Circular and flat-bed knitting machines accommodate conductive yarn integration into stretchable garment architectures with variable density patterning.
- Embroidery:Computer-controlled stitching applies conductive thread patterns onto existing substrates for antenna and interconnect applications.
- Printing:Screen and inkjet deposition of conductive pastes enables rapid prototyping and low-volume customization with minimal capital investment.
Coating retains process leadership for high-volume production; Weaving is climbing the fastest through structural integration advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision coating specialists export conductive yarn architectures to South Korean wearable electronics manufacturers, establishing the primary trade-flow corridor for textile-electronics hybrid components.
United States
The U.S. Department of Defense's sensor-integrated uniform programs and electromagnetic shielding garment procurement are pulling advanced conductive volumes through prime contractors. MIL-STD-285 certification requirements constrain material choices for transatlantic market access. Defense manufacturing corridors in Massachusetts and Virginia concentrate prime contractor facilities with in-house polymer compounding capabilities.
Germany
Medical device manufacturers concentrate procurement around antimicrobial performance specifications that justify premium silver-coated fiber positioning. EU REACH restrictions on nickel migration accelerate material substitution toward compliant conductive formulations. Industrial textile manufacturers in the Baden-Württemberg region dominate high-performance weaving applications where structural integrity coexists with electrical functionality.
Japan
METI technology roadmaps align conductive polymer R&D with PMDA regulatory pathways for continuous physiological monitoring garments. JIS standards and national technology roadmaps target healthcare monitoring applications. Toray Industries anchors high-performance carbon-based yarn production in the Mishima manufacturing corridor, expanding precursor production capacity for automotive seating suppliers.
South Korea
Consumer electronics manufacturers consolidate supplier relationships around vertically integrated producers capable of delivering certified conductive fabrics without subcontracted coating steps. MFDS regulatory alignment supports wearable medical device development. Textile-electronics hybrid production lines in the Seoul Capital Area are scaling precision coating capacities that reduce unit costs for stretchable sensing architectures.
India
BIS standards adoption and PLI scheme incentives for advanced textiles are opening fabrication opportunities for copper-wire textile architectures in industrial automation harnesses. CDSCO regulatory pathways support medical wearable development. Manufacturing clusters in Gujarat and Tamil Nadu are attracting investment for precision coating and metallization capabilities serving domestic and export markets.
Global Conductive Textiles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into defense-certified prime contractors, precision coating specialists, and carbon fiber heritage manufacturers. Three archetypes dominate: vertically integrated polymer compounders, Japanese precision coating houses, and European electromagnetic shielding fabricators. Competitive moves concentrate on backward integration into precursor production and geographic expansion into Indian manufacturing corridors.
Among Japanese heritage manufacturers, Toray Industries exemplifies the carbon fiber precursor archetype with polymer science capabilities spanning precursor through finished yarn. Bekaert represents the metallization expertise cluster dominating copper-wire textile architectures. Seiren Co., Ltd. occupies a position within the precision coating specialist tier, extending conductive polymer durability for wearable electronics applications. These three anchors illustrate how geographic concentration in East Asian manufacturing corridors shapes competitive positioning.
| Leading Market Players |
|---|
| Toray Industries |
| Bekaert |
| Seiren Co., Ltd. |
| Laird Performance Materials |
| AiQ Smart Clothing |
| Holland Shielding Systems BV |
| Shieldex |
| HeiQ Materials AG |
| 3M |
| Others |
Supply & Pricing Matrix
The Mishima manufacturing corridor in Shizuoka Prefecture anchors global carbon-based yarn capacity, and Toray Industries' precursor expansion decisions directly shape pricing power for automotive seating suppliers negotiating stretchable sensing architectures.
Pricing Analysis
Current-generation silver-coated fibers command substantial premiums over prior-generation nickel-copper plated alternatives, while next-generation bio-derived conductive polymers remain pre-commercial with undefined pricing benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-285 certified defense grades from industrial automation harnesses and consumer fitness apparel. Pricing pressure stems from silver price volatility compressing margins for medical suppliers locked into fixed-price contracts. Consumer electronics manufacturers exhibit highest price sensitivity, while defense contractors accept premium positioning for traceable supply chains.
Supply Chain Analysis
Upstream feedstock dynamics center on polyacrylonitrile precursor supply from Japanese petrochemical complexes, silver bullion from London and COMEX exchanges, and copper cathode from Chilean and Indonesian smelters. Manufacturing concentration in Japan, South Korea, and Germany creates geographic supply risk for automotive and sports equipment brands. Single-source vulnerability runs through Toray Industries' carbon fiber precursor monopoly in Mishima. Distribution runs through vertically integrated prime contractors displacing merchant distributors in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from printed electronics and flexible hybrid electronics that bypass woven substrates entirely, requiring defensive positioning around certification moats and manufacturing scale.
For Market Incumbents: Build certification moats around MIL-STD-285 and IEC 60601-1 electromagnetic compatibility exclusivity. Invest in backward integration into silver recovery and carbon precursor production to offset precious metal volatility. Consolidate coating capacity in South Korean textile-electronics hybrid corridors to capture consumer electronics volume scaling before printed electronics mature.
For New Entrants and Emerging Players: Build out copper-wire textile architectures for Indian industrial automation harnesses under BIS standards and PLI scheme incentives. Target healthcare monitoring convergence in Japan where METI roadmaps align with PMDA regulatory pathways. Pursue recyclable polymer formulation partnerships with European end-of-life textile processors to capture EU Ecodesign compliance premiums.
For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because defense procurement consolidation and healthcare monitoring convergence favor vertically integrated compounders with captive precursor supply. Acquisition targets should display in-house polymer compounding plus metallization capabilities without subcontracted coating steps. Watch IEC 61000-series electromagnetic compatibility talent scarcity as the inflection signal—when certification lab capacity constraints ease, merchant market distributors face accelerated displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Toray Industries' polyacrylonitrile expansion in Mishima secures carbon fiber supply for automotive seating tiers. |
| MIL-STD-285 Certification Investment | Prime contractors in Massachusetts and Virginia demand in-house shielding effectiveness testing for defense awards. |
| Recyclable Polymer Formulation Partnerships | EU Ecodesign compliance creates first-mover advantage with European end-of-life textile processors. |
| Precision Coating Capacity Expansion | Seoul Capital Area facilities reduce unit costs for stretchable sensing architectures in South Korean consumer electronics. |
| Healthcare Monitoring Regulatory Alignment | METI roadmaps and PMDA pathways converge for continuous physiological monitoring garments in Japanese healthcare. |
Research Methodology
Cross-validation between primary interviews with textile-electronics hybrid production managers, defense procurement officers, and medical device regulatory affairs leads anchors the qualitative findings against secondary validation from SEC filings of listed materials companies, IEC electromagnetic compatibility standard drafts, and EU Ecodesign regulatory impact assessments. Bottom-up demand modeling from individual application segments triangulates against top-down market sizing from trade flow analysis of conductive yarn exports.
Calibration against historical CAGRs from comparable functional material markets informs the projection framework across the analysis window. Segmentation dimensions include product chemistry, fabrication technology, end-use industry concentration, and application specificity. Modeled inputs incorporate military procurement program announcements, REACH restriction timelines, and METI technology roadmap commitments. CAGRs derive from elasticity-adjusted demand curves rather than linear extrapolation.
Stress conditions across silver price volatility bands, Japanese precursor supply disruption scenarios, and EU biodegradability mandate acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against customs trade data for conductive textile exports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Absorbent Cover Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Webbing Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Geotextiles and Geogrids Market