
 Nonwoven Weed Control Fabric Market | 2026-2036
Nonwoven Weed Control Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Weed Control Fabric Market Intelligence
Expanded production capacity in China is narrowing the technology gap with established European producers. Berry Global Group leverages its manufacturing scale to serve high-volume agricultural accounts across North America and Europe. Meanwhile, Freudenberg Group specializes in high-performance, durable materials for demanding construction and landscaping applications. Tencate Geosynthetics differentiates through its focus on engineered geotextile solutions that offer superior longevity and strength.
Nonwoven weed control fabric is a textile-like material produced by bonding or interlocking fibers, commonly polypropylene, through thermal or mechanical means like spunbonding. These fabrics are engineered to block sunlight, inhibiting weed growth, while remaining permeable to water and air to maintain soil health. Spunbond polypropylene products dominate the market due to their balance of cost-effectiveness and durability. However, materials based on biodegradable fibers represent the fastest-growing segment, driven by sustainability mandates in landscaping and agriculture.
Regulations such as the European Union's REACH framework and the US EPA's guidelines on agricultural plastics influence material composition and disposal. In parallel, standards from bodies like China's MEE concerning soil and water conservation encourage the use of geotextiles in infrastructure projects. Material suppliers must decide whether to invest in biodegradable fiber production capacity or focus on optimizing the performance of conventional polymer-based fabrics.
Market Dynamics
The market's structure is defined by a central tension between cost-effective polypropylene fabrics and the rising adoption of biodegradable materials. This shift is driven by agricultural sustainability mandates and evolving consumer preferences for eco-friendly landscaping solutions, forcing a re-evaluation of material science and production investment across the supply chain.
Growth Catalysts
- Government Support:China's MEE standards on soil and water conservation promote the use of geotextiles in infrastructure and modern farming, creating consistent demand for nonwoven fabrics to prevent erosion and manage vegetation.
- Agricultural Modernization:The expansion of large-scale commercial agriculture, particularly in North America, requires efficient, low-labor weed suppression solutions to maximize crop yields and operational efficiency, directly fueling fabric consumption.
- Material Cost-Effectiveness:Spunbond polypropylene technology offers a compelling balance of durability, UV resistance, and low production cost, making it the dominant material choice for high-volume agricultural and landscaping projects.
Market Restraints
- Raw Material Volatility:The market's heavy reliance on polypropylene, a petrochemical derivative, exposes manufacturers to price fluctuations in global oil and gas markets, impacting production costs and margin stability.
- Competition from Alternatives:Traditional weed control methods, including chemical herbicides and organic mulching, remain entrenched in certain agricultural and residential segments due to familiarity and lower initial costs.
- Performance Trade-offs:A fundamental trade-off exists between water permeability and fabric durability; higher-permeability fabrics can be less robust, while thicker materials may impede optimal air and water exchange in soil.
Strategic Opportunities
- Biodegradable Product Lines:Developing and scaling production of fabrics from polylactic acid (PLA) or other biodegradable fibers meets sustainability mandates from regulators like the European Union under its Green Deal framework.
- Urban Green Infrastructure:Targeting applications in green roofs, vertical gardens, and urban landscaping projects provides a new growth vector beyond traditional agriculture, especially in densely populated European cities.
- Specialized Geotextiles:Engineering fabrics with enhanced properties like superior UV resistance or specific filtration characteristics for demanding civil engineering and construction applications opens high-margin niche markets.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers face challenges navigating disparate international standards, such as the EU's REACH framework for chemical safety and US EPA guidelines on agricultural plastics, increasing testing and certification costs.
- Capital Investment for Biodegradables:Shifting production towards biodegradable fibers requires significant capital expenditure in new extrusion and bonding equipment, creating a barrier for smaller producers and delaying market-wide transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Weed Control Fabric Market |
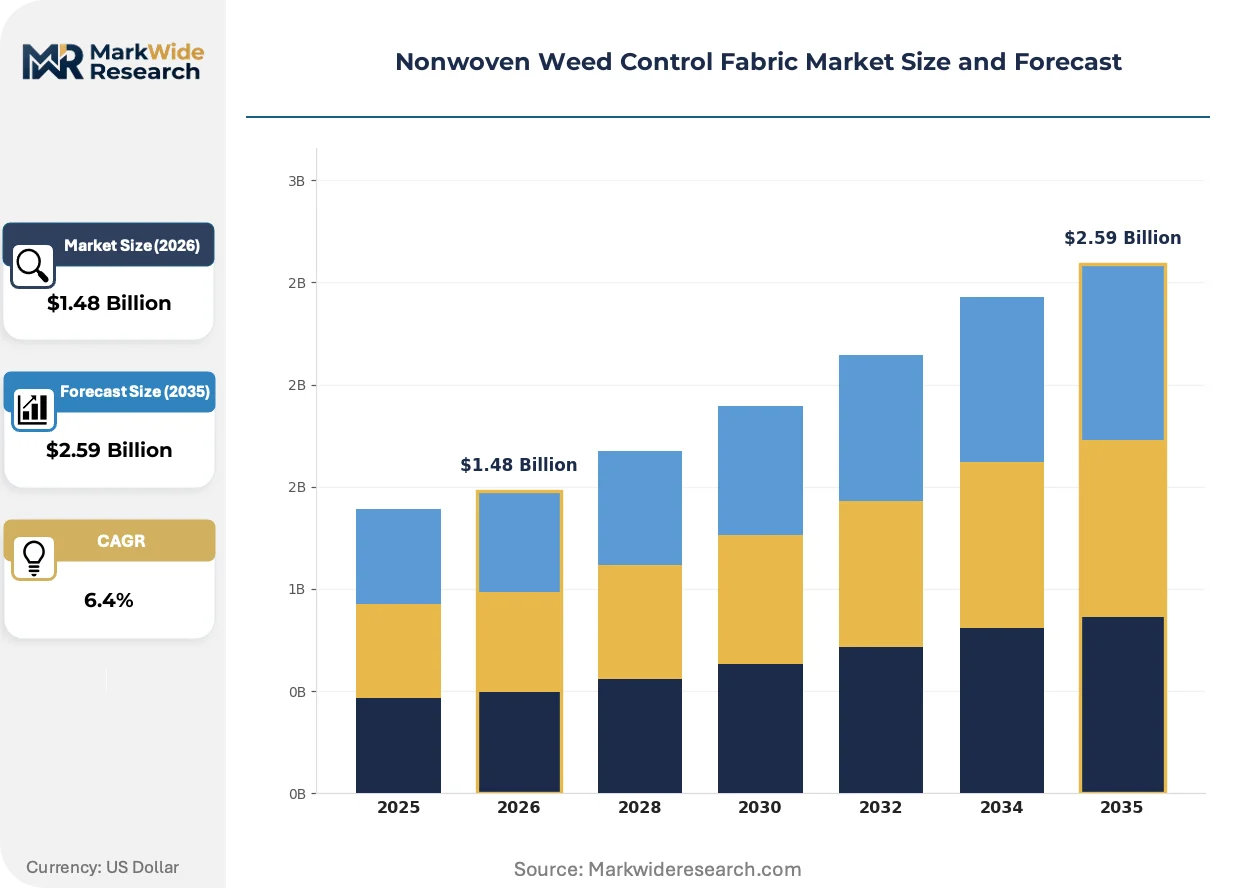
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Needlepunch, Composite Material: Polypropylene, Polyester, Biodegradable Fibers, Polyethylene End User: Agriculture, Landscaping, Gardening, Construction Feature: UV Resistant, Water Permeable, Durable, Lightweight |
| Companies Covered | Ahlstrom-Munksjö, BASF, Berry Global Group, Tencate Geosynthetics, Mondi Group, DuPont, Kimberly-Clark, Glatfelter, Freudenberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Weed Control Fabric Market Strategic Shifts & Innovations
Product development is increasingly focused on enhancing ecological compatibility and integrating new functionalities beyond simple weed suppression. This fundamental transition from passive barrier materials toward intelligent and sustainable systems is reshaping the market's value proposition for agricultural and landscaping end-users.
Smart fabrics embedded with micro-sensors represent a key innovation. These materials can monitor soil moisture, temperature, and nutrient levels in real-time. High-value horticulture and precision agriculture are the primary adopters, seeking data-driven insights. This development is digitizing soil health management, transforming the fabric from a passive barrier into an active data collection tool.
The European Union's push to reduce single-use plastics under its Green Deal framework directly impacts material selection. This regulatory pressure accelerates the shift away from disposable polypropylene fabrics in landscaping and agriculture. As a result, demand is polarizing towards either highly durable, multi-season fabrics or certified biodegradable options that align with circular economy principles.
A shift in buying behavior is evident as large agricultural operators now specify fabrics as part of an integrated system. Procurement criteria increasingly include compatibility with specific drip irrigation technologies and compliance with organic farming certifications like the USDA's National Organic Program. This systems-based approach is most visible in North American horticulture, prioritizing water efficiency and certifiable production methods.
Nonwoven Weed Control Fabric Market Segmentation
The nonwoven weed control fabric market is categorized by distinct product attributes and end-user requirements. Understanding these segments helps manufacturers tailor offerings and optimize material science investments. Each segment reflects specific performance needs and economic considerations across diverse applications.
Product Type:
Product type segmentation highlights the varying lifecycles and replacement frequencies inherent in nonwoven weed control fabrics.
- Spunbond:This fabric is produced by extruding polymer filaments and bonding them with heat, creating a strong, uniform material. Demand concentrates in large-scale agriculture across North America due to its balance of cost-effectiveness and durability for seasonal use.
- Needlepunch:Mechanical interlocking of fibers through barbed needles forms a dense, robust fabric, often thicker and more permeable than spunbond. Applications in civil engineering projects, particularly in China's infrastructure development, value its strength and filtration capabilities.
- Meltblown:Characterized by fine fibers and high surface area, this type offers excellent filtration and barrier properties.
- Composite:These fabrics combine multiple nonwoven technologies or materials to achieve synergistic properties for specialized functions.
Spunbond dominates the installed base for general weed control. Needlepunch is where expansion concentrates for heavy-duty infrastructure applications.
Material:
Material choices significantly influence the cost structure and environmental footprint of nonwoven weed control fabrics.
- Polypropylene:A thermoplastic polymer, polypropylene offers excellent tensile strength, UV resistance, and chemical inertness, making it highly durable. Large-scale agricultural operations in the US prefer polypropylene for its economic efficiency and proven performance.
- Biodegradable Fibers:Materials like polylactic acid (PLA) or bio-based polymers naturally decompose, reducing environmental impact. European landscaping projects and organic farms increasingly adopt these fibers to comply with sustainability mandates and circular economy principles.
- Polyester:Known for its high strength and dimensional stability, polyester fabrics offer enhanced durability in demanding conditions.
- Polyethylene:These fabrics provide good chemical resistance and flexibility, often used in specific agricultural film applications.
Polypropylene remains the market's volume leader. Biodegradable fibers represent the fastest-growing segment, driven by new regulatory frameworks.
End User:
End-user segmentation reveals the diverse functional requirements and scale of deployment for nonwoven weed control solutions.
- Agriculture:This segment encompasses large-scale farming operations that utilize fabrics for crop protection, soil moisture retention, and efficient weed management. Modern farming techniques in China and North America drive substantial demand for durable, permeable fabrics.
- Landscaping:Professional and residential landscaping projects employ these fabrics for aesthetic weed suppression, erosion control, and pathway stabilization. European urban green infrastructure initiatives increasingly specify biodegradable options for public spaces.
- Gardening:Smaller-scale residential and community garden applications prioritize ease of installation and environmental compatibility.
- Construction:Civil engineering projects use geotextiles for ground stabilization, drainage, and erosion control around new structures.
Agricultural end-users consume the largest volume of nonwoven fabrics. The landscaping segment exhibits strong growth, particularly for eco-friendly solutions.
Feature:
Feature-based segmentation highlights the performance characteristics critical for specific environmental conditions and application longevity.
- Durable:Fabrics engineered for extended lifespan withstand repeated use, mechanical stress, and harsh environmental conditions. Civil engineering projects and permanent landscaping installations require high durability to minimize replacement frequency and maintenance costs.
- UV Resistant:These fabrics incorporate stabilizers or coatings to prevent degradation from prolonged sunlight exposure, maintaining structural integrity over time. Agricultural applications in sun-intensive regions, such as parts of the US, rely on UV-resistant materials for multi-season use.
- Water Permeable:Fabrics designed to allow water and nutrients to pass through efficiently, supporting soil health beneath the barrier.
- Lightweight:These fabrics prioritize ease of handling and installation, reducing labor costs for large-area coverage in agricultural settings.
Durable and UV-resistant fabrics are fundamental for outdoor, long-term applications. Water-permeable options are gaining traction for their soil health benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for nonwoven weed control fabrics varies significantly across regions. China prioritizes large-scale agricultural and infrastructure applications, driven by government initiatives. European markets emphasize biodegradable solutions for landscaping, influenced by sustainability mandates, while North America focuses on cost-effective, durable fabrics for commercial agriculture.
China
China's agricultural modernization initiatives fuel substantial demand for nonwoven weed control fabrics, particularly in large-scale farming. The MEE standards on soil and water conservation actively promote geotextile use in infrastructure development. Production capacity is expanding rapidly across the Yangtze River Delta, narrowing the technology gap with established European producers.
United States
Large-scale commercial agriculture in the United States requires efficient, low-labor weed suppression solutions to maximize crop yields. The USDA's National Organic Program influences material selection for certified organic farms. Horticulture operations across California and the Midwest increasingly specify fabrics compatible with advanced drip irrigation technologies.
Germany
Urban green infrastructure projects in Germany drive demand for sustainable nonwoven fabrics, especially in densely populated areas. The EU Green Deal framework strongly encourages the shift towards biodegradable options for public landscaping and private gardens. Berlin's municipal projects frequently utilize eco-friendly geotextiles for public parks, green roofs, and vertical gardens.
India
Agricultural modernization across India creates a consistent need for effective weed management and soil preservation. Government policies supporting agricultural efficiency and infrastructure development indirectly boost demand for these specialized fabrics. Farming regions in Maharashtra and Punjab are increasingly adopting nonwoven solutions to enhance crop yields and reduce labor costs.
Nonwoven Weed Control Fabric Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the nonwoven weed control fabric market. The market structure is tiered, featuring specialized players focused on high-performance materials alongside volume-driven manufacturers. Key archetypes include innovative material developers, cost-effective commodity producers, and sustainable solution providers for eco-conscious segments. Dominant competitive moves involve significant capacity expansion to meet agricultural demand and strategic partnerships for new biodegradable fiber development.
Specialists in high-performance and sustainable materials include Freudenberg Group, which exemplifies a focus on durable solutions for demanding construction and landscaping applications. Tencate Geosynthetics represents providers of engineered geotextile solutions, emphasizing superior longevity and strength for civil engineering projects. Berry Global Group occupies a position leveraging manufacturing scale to serve high-volume agricultural accounts across North America and Europe. These companies collectively illustrate the market's differentiation across performance and volume segments.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| BASF |
| Berry Global Group |
| Tencate Geosynthetics |
| Mondi Group |
| DuPont |
| Kimberly-Clark |
| Glatfelter |
| Freudenberg Group |
| Others |
Cost & Logistics Intelligence
China's expanding production capacity in the Yangtze River Delta shifts global supply dynamics, influencing downstream pricing power for conventional nonwoven fabrics. This concentration of manufacturing capability creates competitive pricing for high-volume agricultural buyers.
Pricing Analysis
Geographic price-spread observations reveal regional disparities driven by logistics and regulatory compliance costs. The dominant pricing structure for high-volume polypropylene fabrics is contract-based long-term offtake, ensuring supply stability for large agricultural operators. Price differentiation stems from quality grade, particularly UV resistance and tensile strength, and certification level for biodegradable options under frameworks like the EU Green Deal. Pricing softness reflects raw material volatility for petrochemical-derived polypropylene, impacting manufacturer margins. Large-scale agricultural buyers in North America exhibit high price sensitivity for commodity-grade fabrics, while specialized urban landscaping projects in Europe show lower sensitivity for certified biodegradable products.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital for manufacturers and distributors. Geographic supply concentration centers on China, Europe, and the United States, reflecting both production hubs and major consumption markets. The industry's manufacturing process heavily draws from polypropylene granules and polylactic acid (PLA) or other bio-based polymers as primary inputs. Commodity price volatility for petrochemicals represents a significant structural risk, directly impacting production costs. Distribution runs through direct sales channels to large agricultural enterprises and a network of specialized distributors serving landscaping and construction sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a buyer-power-shift story, driven by large agricultural operators increasingly specifying fabrics as integral components of advanced farming systems.
For Market Incumbents: Entrench market position by strategically investing in both biodegradable fiber production capacity and optimizing existing conventional polymer-based fabric performance. This dual approach mitigates regulatory threats, such as the EU Green Deal's push for sustainable materials, while addressing cost-efficiency demands. Focus R&D on smart fabric integration for precision agriculture and expand manufacturing scale in key geographies like China to maintain cost leadership.
For New Entrants and Emerging Players: Establish a beachhead in specialized, high-value segments less dominated by scale players. Target urban green infrastructure applications in European cities and specialized geotextiles for demanding civil engineering projects. A go-to-market angle focused on certified biodegradable solutions, aligning with evolving sustainability mandates, offers a compelling differentiation strategy. European urban landscaping presents a highly penetrable segment for innovative, eco-friendly offerings.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical and textile conglomerates seeking to divest non-core nonwoven assets. The long-term viability of this market is anchored in consistent demand from agricultural modernization and infrastructure development, particularly for sustainable solutions. Acquisition targets should be niche specialists in biodegradable materials, advanced geotextiles, or smart fabric technology providers. Accelerated regulatory mandates for bio-based plastics and geotextiles serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Biodegradable Fiber Production | Meets sustainability mandates from the EU Green Deal and evolving consumer preferences in landscaping. |
| Invest in Smart Fabric R&D | Digitizes soil health management for precision agriculture, transforming fabrics into active data tools. |
| Optimize Conventional Polypropylene Formulations | Enhances cost-effectiveness and durability for large-scale agriculture, maintaining market share against alternatives. |
| Target Urban Green Infrastructure Projects | Opens new growth vectors beyond traditional agriculture in densely populated European cities. |
| Develop Specialized Geotextile Solutions | Captures high-margin niche markets in civil engineering and construction applications requiring superior longevity. |
Research Approach
The analysis maps nonwoven weed control fabric sub-sectors, each validated through extensive primary interviews with industry stakeholders. We engaged agricultural managers, landscaping contractors, civil engineers, and material scientists to gather first-hand insights. Secondary research involved government agricultural reports, environmental agency guidelines from the EPA and REACH, industry association publications, and company financial filings, triangulated with bottom-up and top-down data approaches.
Assumptions regarding regulatory stability and sustained investment in agricultural modernization were held fixed across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, end-user, feature, and regional regulatory frameworks. Compound annual growth rates were derived from historical market performance and projected growth drivers, accounting for technological advancements. Key forecast inputs included raw material price trends and government agricultural subsidies.
Sensitivities concentrate around geopolitical shifts affecting global trade and unforeseen technological breakthroughs in alternative weed control methods. Forecasts reflect these documented assumptions, but significant shifts in raw material availability or changes in global environmental policies could revise projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Polyester Fabric Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market