
 Military Textile Materials Testing Market | 2026-2036
Military Textile Materials Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Military Textile Materials Testing Market Foresight
Market Context
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of flame-resistant fabrics. SGS SA leverages its multi-accreditation footprint across NATO testing protocols to sustain contract flows from defense ministries. Bureau Veritas anchors its position through specialized ballistic certification labs in France and Belgium. Intertek Group plc competes on turnaround speed for urgent military procurement cycles.
Technical Definition and Segments
Military textile materials testing encompasses mechanical, chemical, and ballistic evaluation of woven and non-woven fabrics designed to withstand extreme operational stress, including tensile loads exceeding 500 MPa for aramid composites and flame exposure durations per ASTM D6413 protocols. The testing method dimension shows flame resistance and tensile strength commanding premium pricing due to stringent NATO STANAG requirements, while water repellency testing matures into a commoditized service tier. Kevlar and nylon within material type concentrate margin pools where ballistic certification adds substantial value above standard polymer testing.
Regulatory Frame
The U.S. Department of Defense enforces MIL-STD-810 for environmental durability and MIL-STD-662F for ballistic performance, while the EU Green Deal's PFAS restrictions are forcing reformulation of legacy water-repellent treatments used in uniform fabrics. Stakeholders must monitor how emerging per- and polyfluoroalkyl substance bans interact with existing durability specifications before committing capital to new coating lines.
Market Dynamics
Ballistic protection procurement by NATO-aligned defense ministries is tightening certification requirements faster than testing capacity can expand, creating bottlenecks at accredited laboratories.
Growth Catalysts
- MIL-STD-662F Revision:The U.S. Department of Defense's updated fragment-resistant materials standard is mandating retesting of legacy inventories, generating substantial contract volumes for certified facilities.
- Nearshoring Mandates:Domestic sourcing requirements in the United States are pulling test demand away from offshore laboratories toward accredited domestic providers.
- Aramid Composite Adoption:Tensile loads exceeding 500 MPa in next-generation body armor are requiring specialized mechanical testing protocols that command premium pricing tiers.
Market Restraints
- PFAS Input Volatility:The EU Green Deal's per- and polyfluoroalkyl substance restrictions are forcing reformulation of water-repellent treatments, disrupting established coating validation workflows.
- Accreditation Concentration:Multi-protocol NATO STANAG certification remains concentrated among a limited pool of European and North American laboratories, constraining supplier choice.
- Technical Ceiling:Flame exposure duration testing per ASTM D6413 protocols has approached methodological limits, compressing differentiation opportunities in commoditized service tiers.
Strategic Opportunities
- Eastern European Expansion:NATO's eastern flank members are building domestic textile testing capabilities, creating first-mover advantages for accredited entrants.
- Multi-Threat Integration:Convergence of ballistic, flame-resistant, and chemical protection requirements is opening unified testing service contracts that replace fragmented single-protocol engagements.
- Digital Certification Platforms:Blockchain-anchored test result verification is emerging as a channel innovation for urgent procurement cycles requiring immutable chain-of-custody documentation.
Industry Challenges
- Specialized Technician Scarcity:Ballistic certification requires expertise in fragment simulating projectile analysis that outpaces vocational training program output.
- Capex Intensity:High-velocity test ranges and environmental simulation chambers demand capital commitments that strain mid-tier laboratory balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Textile Materials Testing Market |
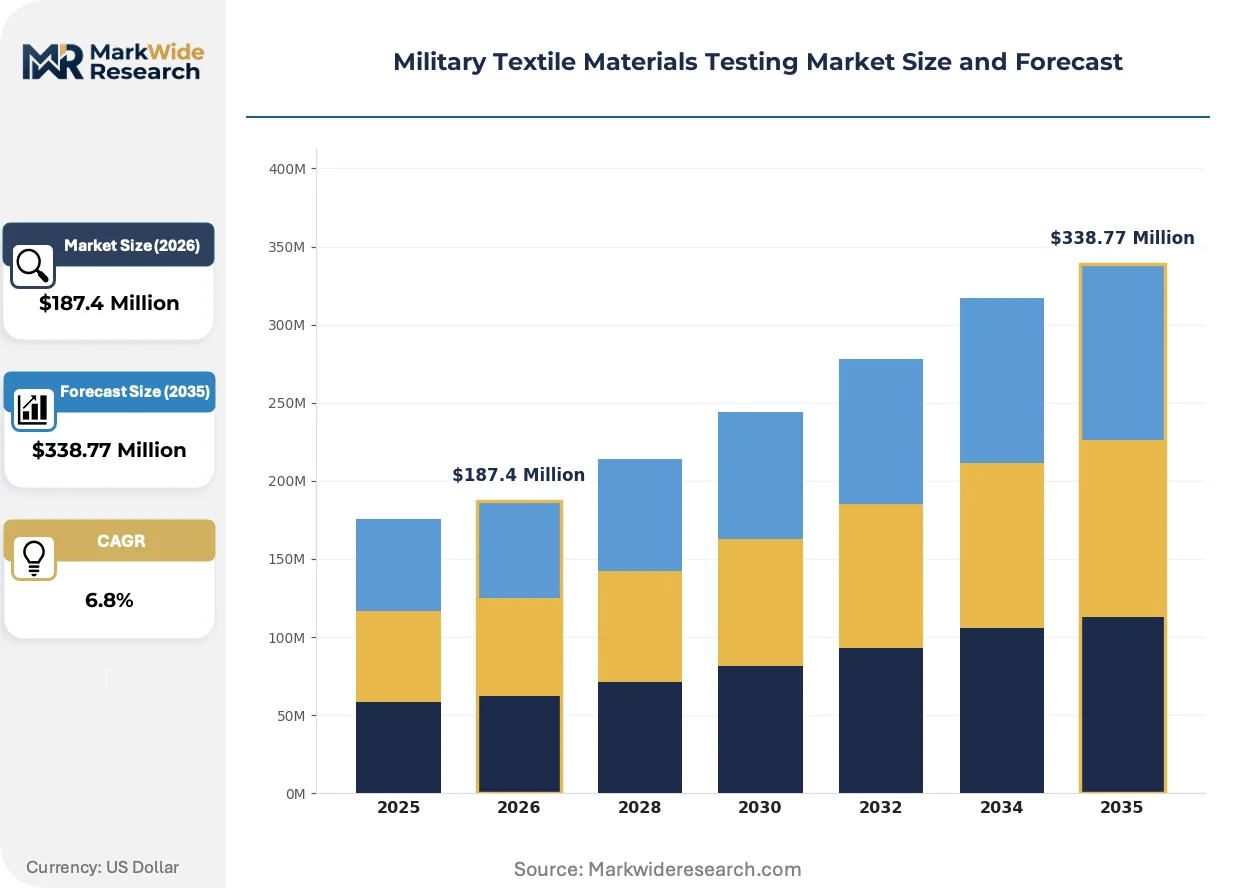
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Tensile Strength, Abrasion Resistance, Water Repellency, Flame Resistance Material Type: Nylon, Polyester, Kevlar, Cotton Application: Bodies Armor, Uniforms, Gear, Parachutes End User: Military, Defense Contractors, Research Institutions, Government Agencies |
| Companies Covered | SGS SA, UL LLC, Hohenstein Institute, VARTEST Laboratories Inc., Element Materials Technology, Precision Testing Laboratories, Inc., Bureau Veritas, Intertek Group plc, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Textile Materials Testing Market Shifts & Advancements
Advanced materials characterization is compressing development cycles for next-generation protective textiles while regulatory fragmentation across defense procurement blocs is multiplying compliance pathways.
Non-destructive evaluation using terahertz imaging is expanding into quality assurance workflows for woven aramid composites. Defense contractors in the United States are adopting these systems at pilot scale to reduce sample destruction rates during lot acceptance testing. This technology is expanding into contract structures that tie payment milestones to real-time defect detection rather than post-hoc batch certification.
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of flame-resistant fabrics. The European Chemicals Agency's substance restriction timelines are forcing reformulation of legacy water-repellent chemistries ahead of full prohibition dates. Testing laboratories in France and Belgium are responding by building accelerated aging capabilities to validate replacement coating durability against compressed certification deadlines.
Defense ministries are consolidating vendor panels around laboratories offering multi-protocol accreditation under single contracts. This pattern is displacing fragmented sourcing across specialized mechanical, chemical, and ballistic testing providers. The United Kingdom and Germany show the most visible consolidation, with procurement officers prioritizing turnaround speed for urgent military procurement cycles over narrow technical specialization.
Military Textile Materials Testing Market Segmentation
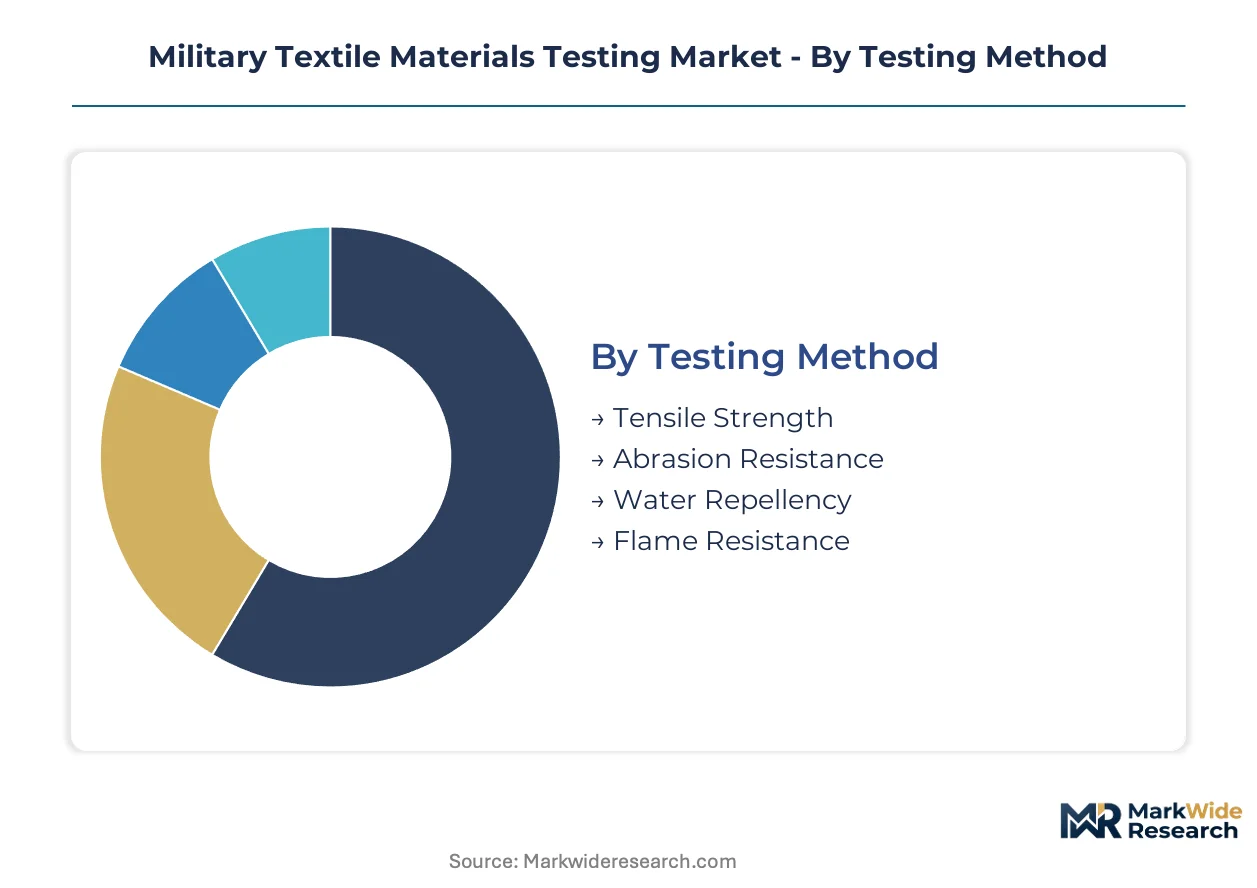
Testing protocols diverge sharply across material grades and threat specifications, fragmenting procurement into specialized accreditation tiers. Laboratories capture margin through protocol bundling rather than volume scale.
Testing Method:
Supply concentration clusters around laboratories maintaining NATO STANAG multi-protocol accreditation, with single-protocol providers relegated to commoditized tiers.
- Flame Resistance:Evaluation per ASTM D6413 protocols measures after-flame time and char length for aramid and treated cotton blends. U.S. Army Natick Soldier Systems Center drives specification tightening for next-generation combat uniforms, compressing turnaround requirements for certified facilities.
- Tensile Strength:Mechanical loading tests exceeding 500 MPa for aramid composites require specialized grips and environmental chambers. Defense contractors in the United States prioritize domestic sourcing mandates, pulling contract volume toward accredited domestic laboratories.
- Abrasion Resistance:Martindale and Wyzenbeek methods evaluate fabric durability under cyclic loading for tactical gear applications.
- Water Repellency:Spray rating and hydrostatic head tests for treated fabrics face reformulation pressure from EU Green Deal PFAS restrictions.
Flame resistance absorbs the bulk of installed capacity; tensile strength is expanding most quickly.
Material Type:
Margin pools concentrate where ballistic certification adds substantial value above standard polymer characterization.
- Kevlar:Para-aramid fiber testing demands fragment-simulating projectile analysis and backface deformation measurement per MIL-STD-662F. The U.S. Department of Defense's revision mandates retesting of legacy inventories, generating substantial contract volumes for certified high-velocity ranges.
- Nylon:Polyamide 6,6 and 6 variants require tensile, abrasion, and accelerated aging protocols for parachute canopy and suspension line applications. Domestic sourcing requirements in the United States favor accredited laboratories with captive environmental simulation capacity.
- Polyester:PET fiber evaluation for uniform fabrics emphasizes colorfastness and dimensional stability under tropical storage conditions.
- Cotton:Natural fiber testing focuses on flame-retardant treatment durability and moisture management for base layer applications.
Kevlar dominates revenue concentration; nylon is climbing the fastest on parachute procurement cycles.
Application:
Threat convergence is compressing fragmented single-protocol engagements into unified multi-threat testing contracts.
- Body Armor:Integrated ballistic, blunt trauma, and environmental durability evaluation for soft and hard armor systems. The United Kingdom and Germany consolidate vendor panels around laboratories offering multi-protocol accreditation under single contracts.
- Uniforms:Flame resistance, insect repellency, and infrared signature management testing for combat and garrison dress. REACH compliance recalibrates cost-of-entry for European suppliers of flame-resistant fabrics.
- Gear:Load carriage equipment testing emphasizes abrasion resistance and hydrolytic stability for tropical deployment.
- Parachutes:Canopy permeability and suspension line tensile evaluation for personnel and cargo delivery systems.
Body armor commands the steepest expansion trajectory; uniforms retain the largest addressable base.
End User:
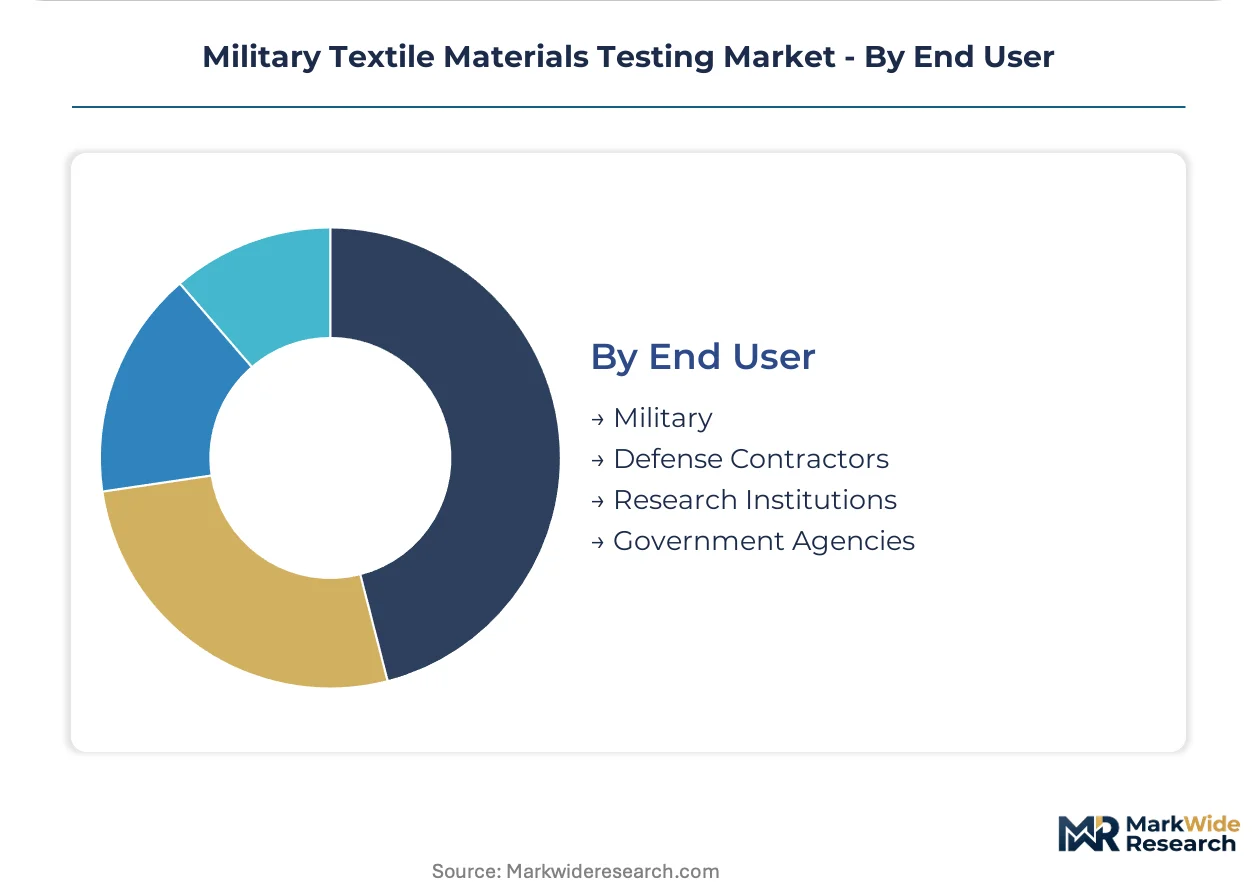
Procurement authority fragmentation across defense ministries and prime contractors multiplies compliance pathways.
- Military:Direct defense ministry contracts specify NATO STANAG, MIL-STD-810, and MIL-STD-662F protocols with immutable chain-of-custody documentation requirements. Bureau Veritas anchors position through specialized ballistic certification labs in France and Belgium.
- Defense Contractors:Prime contractor lot acceptance testing demands turnaround speed for urgent procurement cycles, favoring laboratories with digital certification platforms.
- Research Institutions:Developmental material characterization for next-generation protective textiles requires non-standard protocol flexibility.
- Government Agencies:Federal emergency response and law enforcement procurement follows adapted military specifications with reduced ballistic threat levels.
Military end users absorb the bulk of accredited capacity; defense contractors are gaining share fastest on nearshoring mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in NATO-aligned economies where domestic sourcing mandates and multi-protocol accreditation requirements concentrate testing demand among specialized laboratories.
United States
The U.S. Department of Defense drives retesting volumes through MIL-STD-662F revisions for fragment-resistant materials. Domestic sourcing requirements under the Berry Amendment pull contract flow toward accredited domestic providers. Natick Soldier Systems Center in Massachusetts tightens specifications for next-generation combat uniforms, compressing turnaround requirements for certified facilities.
Germany
Defense ministry procurement officers prioritize laboratories offering NATO STANAG multi-protocol accreditation under single contracts. The EU Green Deal's PFAS restrictions force reformulation of legacy water-repellent treatments ahead of full prohibition dates. Testing clusters in Bavaria and North Rhine-Westphalia build accelerated aging capabilities to validate replacement coating durability.
United Kingdom
Consolidation of vendor panels around unified testing service contracts displaces fragmented single-protocol engagements. Ministry of Defence procurement emphasizes turnaround speed for urgent military cycles over narrow technical specialization. Laboratories in the Midlands and Southeast England capture contract flow through digital certification platforms.
France
REACH compliance recalibrates cost-of-entry for European suppliers of flame-resistant fabrics. The European Chemicals Agency's substance restriction timelines compress certification deadlines for reformulated water-repellent chemistries. Specialized ballistic certification laboratories in the Île-de-France and Provence-Alpes-Côte d'Azur regions anchor contract flows from defense ministries.
Belgium
NATO headquarters proximity sustains demand for multi-protocol accreditation across mechanical, chemical, and ballistic evaluation. EU Green Deal regulations interact with existing durability specifications for uniform fabrics. Testing facilities in Brussels and Flanders build capacity for unified multi-threat testing contracts.
Military Textile Materials Testing Market Competitive Landscape
North American producers anchor one tier; European specialists hold accreditation density around NATO STANAG protocols. The vendor base splits between consolidated multi-national testing groups and mid-tier laboratories with captive ballistic ranges. Three archetypes dominate: full-service accreditation holders, ballistic certification specialists, and turnaround-focused urgent procurement providers. Capacity expansion and multi-protocol bundling represent the dominant competitive moves as defense ministries consolidate vendor panels.
Among Switzerland-based testing groups, SGS SA occupies a position exemplifying the full-service accreditation archetype through multi-protocol NATO coverage. Bureau Veritas and Intertek Group plc represent European-anchored competitors building specialized ballistic certification density. These three entities sit within the tier capturing premium contract flow from defense ministry consolidation patterns.
| Leading Market Players |
|---|
| SGS SA |
| UL LLC |
| Hohenstein Institute |
| VARTEST Laboratories Inc. |
| Element Materials Technology |
| Precision Testing Laboratories, Inc. |
| Bureau Veritas |
| Intertek Group plc |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Ballistic certification technicians concentrated in Massachusetts and Bavaria create labor-cost differentials that widen spreads between premium multi-protocol testing and commoditized single-service tiers. European REACH compliance deadlines and U.S. Berry Amendment sourcing mandates reshape cost structures for laboratories competing on turnaround speed versus accreditation breadth.
Pricing Analysis
High-volume flame-resistance and water-repellency testing compresses margins while low-volume ballistic certification captures premium returns. Pricing stratifies across NATO STANAG multi-protocol, MIL-STD single-protocol, and non-accredited economy tiers, with certification grade and domestic sourcing compliance as primary differentiation drivers. Cost compression in standard mechanical testing intensifies as environmental simulation capacity expands. Defense contractors show highest price sensitivity for urgent procurement cycles; defense ministries prioritize accreditation density over unit cost.
Supply Chain Analysis
Domestic sourcing requirements under the U.S. Berry Amendment and EU defense procurement directives reshape laboratory location decisions, pulling capacity toward accredited facilities in the United States, Germany, and the United Kingdom. Testing protocols draw from aramid fiber supply chains anchored in the United States, para-aramid imports from European producers, and specialized ballistic gelatin production. Single-source vulnerability concentrates in fragment-simulating projectile supply. Distribution runs through defense ministry vendor panels and prime contractor lot acceptance workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races into captive high-velocity test ranges and in-house environmental simulation chambers that lock in accreditation moats.
For Market Incumbents: Deploy multi-protocol bundling under single contracts to displace fragmented competitors as NATO ministries consolidate vendor panels. Add accelerated aging capacity in France and Belgium ahead of EU Green Deal PFAS prohibition dates. Certification scarcity at accredited ballistic ranges insulates pricing power from mid-tier entrants with standard mechanical testing only. For New Entrants and Emerging Players: Capture first-mover positions in NATO's eastern flank domestic testing buildouts in Poland and Romania where accreditation density remains thin. Target urgent procurement turnaround contracts where digital certification platforms displace incumbent relationships. Lead with blockchain-anchored chain-of-custody documentation as a channel wedge against established laboratories. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier laboratories holding captive ballistic ranges given MIL-STD-662F revision retesting volumes. Long-term viability favors assets with NATO STANAG multi-protocol density rather than single-service commoditized tiers. Watch PFAS substitution timelines as inflection indicators for coating validation workflow disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Accreditation Expansion | Captures defense ministry vendor panel consolidation in the United Kingdom and Germany. |
| Accelerated Aging Capacity Buildout | Validates replacement water-repellent chemistries ahead of ECHA restriction deadlines. |
| Digital Certification Platform Launch | Reduces turnaround times for urgent U.S. Department of Defense procurement cycles. |
| Eastern European Laboratory Establishment | Secures first-mover advantage in NATO eastern flank domestic capability buildouts. |
| Terahertz Imaging Integration | Reduces sample destruction rates for aramid composite lot acceptance testing. |
Research Methodology
Document review covered defense procurement databases, NATO STANAG protocol specifications, and regulatory filings from ECHA and the U.S. Department of Defense, complemented by interviews with laboratory accreditation managers, defense contractor procurement leads, and testing protocol engineers. Secondary sources included customs trade data for aramid fiber flows, SEC filings from listed testing groups, and environmental simulation equipment manufacturer disclosures. Bottom-up capacity modeling and top-down defense budget allocation triangulation validated segment-level outputs.
Segmentation outputs reflect testing method, material type, application, and end-user dimensions modeled across the projection horizon. CAGRs derive from accredited laboratory capacity expansion schedules, retesting volumes tied to MIL-STD-662F revision implementation, and PFAS substitution timelines affecting coating validation demand. Forecast inputs incorporate Natick Soldier Systems Center specification tightening patterns and Berry Amendment domestic sourcing compliance rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal PFAS prohibition enforcement, NATO eastern flank procurement localization speed, and fragment-simulating projectile supply chain disruptions. Forecasts reflect documented assumptions about defense budget trajectories and accreditation body capacity expansion plans. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Webbing Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Construction Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Smart Sports Textile Market