
 Buildtech Textiles Market | 2026-2036
Buildtech Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Buildtech Textiles Market Analysis
The EU Green Deal is pivoting Buildtech Textiles procurement toward lower-carbon fiber systems and recycled-content thresholds. DuPont leverages its fluoropolymer expertise to dominate high-performance roofing membrane segments. Ahlstrom-Munksjö anchors European supply of sustainable nonwoven geotextiles through integrated pulp-to-fiber operations. SRF Limited competes on polyester industrial yarn scale, serving Indian infrastructure and export markets.
Buildtech Textiles are engineered fiber-based materials designed for load distribution, thermal insulation, weatherproofing, and structural reinforcement in built environments, typically manufactured through woven, nonwoven, or coated processes with basis weights ranging from 100 to 1500 gsm. Geotextiles lead product-type revenue due to decades of civil engineering standardization, while structural fabrics represent the fastest-expanding margin pool as tensile architecture gains commercial traction. Polyester commands material share through cost-performance balance, though fiber glass displaces conventional options in fire-rated building envelopes where ASTM E84 and EN 13501-1 compliance is mandatory.
REACH regulates chemical content in coated textiles across Europe, while the EPA oversees volatile organic compound emissions from U.S. manufacturing facilities, and BIS certifies Indian geotextile products for national highway projects. These frameworks collectively elevate testing costs but lock out uncertified suppliers, tightening qualified vendor pools. Stakeholders must monitor evolving extended-producer-responsibility rules in the EU and pending state-level green building codes in California and New York.
Market Dynamics
The EU Green Deal's material circularity mandates are restructuring Buildtech Textiles procurement, forcing fiber producers to retool recycling infrastructure and coating chemistries while civil engineering contractors consolidate qualified supplier lists.
Growth Catalysts
- REACH chemical compliance:European coating manufacturers are reformulating solvent systems to meet ECHA substance restrictions, creating first-mover advantage for certified textile finishers.
- Geotextile reinforcement demand:German infrastructure renewal corridors are specifying high-tenacity polyester woven fabrics for soil stabilization in highway expansion projects.
- Fluoropolymer membrane performance:Roofing contractors are specifying PTFE-coated glass fiber for tensile structures requiring 25-year weathering warranties.
Market Restraints
- Petrochemical feedstock volatility:PTA and MEG price swings compress polyester yarn margins for non-integrated spinners.
- China glass fiber supply concentration:E-glass roving for fire-rated building envelopes routes through a handful of state-controlled fiber producers.
- Mechanical recycling degradation:PET geotextile reprocessing limits fiber length retention, constraining closed-loop circularity claims.
Strategic Opportunities
- India national highway buildout:BIS-certified geotextile suppliers are capturing NHAI tenders for slope protection and subgrade separation.
- Bio-based polyamide development:Castor oil-derived PA11 yarns are penetrating European architectural membrane specifications seeking reduced carbon intensity.
- Digital textile printing integration:Coated fabric converters are adding inkjet patterning for custom tensile architecture visual branding.
Industry Challenges
- Multiaxial weaving technician scarcity:European loom operators with carbon fiber handling expertise command premium wages.
- ISO 9001 plus EN 13249 certification timelines:Geotextile qualification for rail embankment projects requires 18-month testing protocols.
- Legacy ERP-to-MES integration:Coating lines with 1990s control systems resist real-time quality data capture for customer traceability portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buildtech Textiles Market |
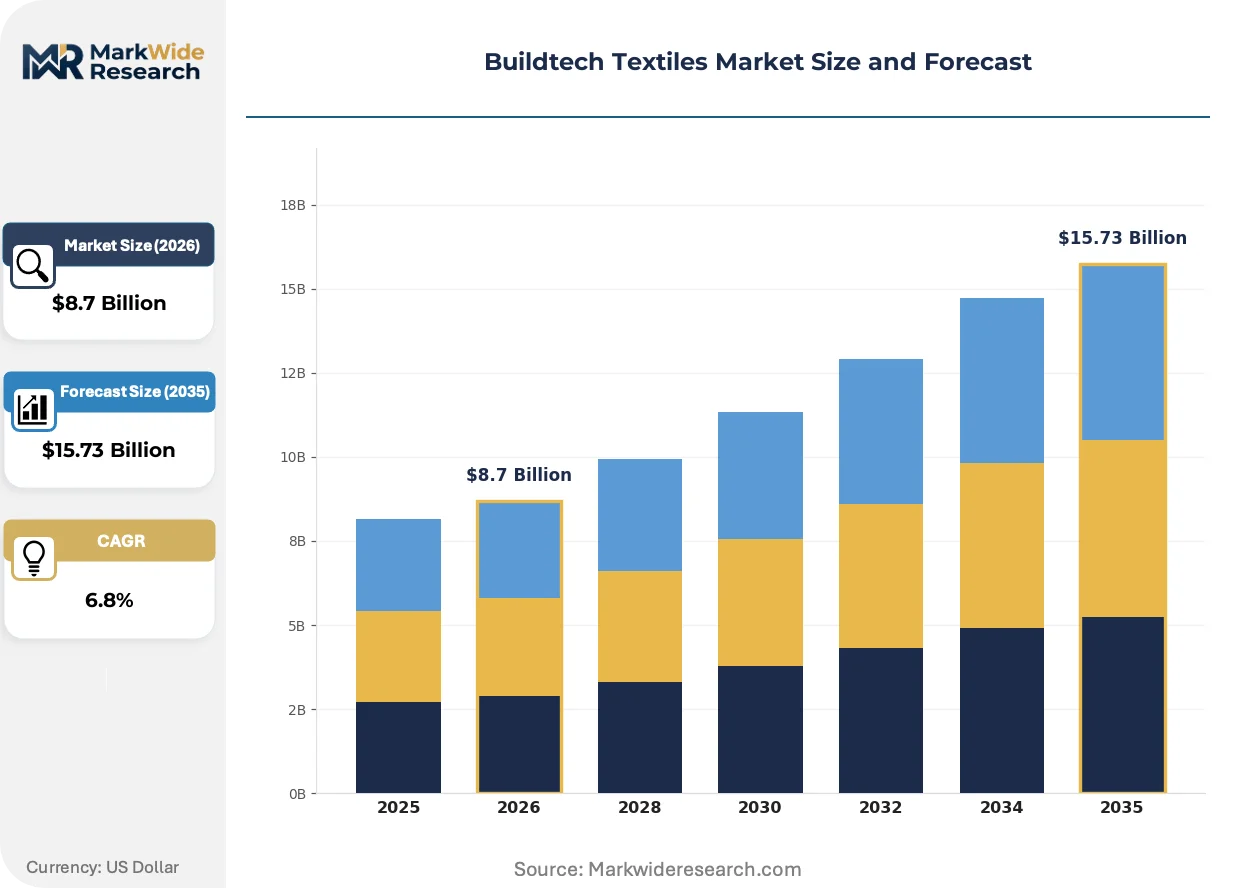
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Insulation Materials, Roofing Fabrics, Structural Fabrics Application: Construction, Civil Engineering, Environmental Protection, Fire Safety Material: Polyester, Polypropylene, Nylon, Fiber Glass End User: Contractors, Architects, Building Owners, Developers |
| Companies Covered | DuPont, Ahlstrom-Munksjö, SKAPS Industries, Toray Industries, SRF Limited, 3M, Low & Bonar, Officine Maccaferri SpA, Delcotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buildtech Textiles Market Emerging Trajectories
Digital manufacturing and regulatory chemistry shifts are reconfiguring how Buildtech Textiles are specified, produced, and validated across construction value chains.
Recycled-content rPET yarn production is decentralizing geotextile supply chains by locating fiber spinning near post-consumer bottle collection hubs. Municipal waste processors in the Netherlands and Belgium are partnering with nonwoven manufacturers to shorten logistics loops. This distributed model is compressing virgin polyester price premiums in Western European civil engineering tenders.
EPA volatile organic compound emission limits are forcing U.S. coating facilities to install thermal oxidizers or switch to water-based acrylic systems. Fabric finishers in Georgia and South Carolina are consolidating solvent-based capacity into fewer EPA-permitted sites. Roofing membrane producers serving the Southeast are reformulating at accelerated pace to maintain architectural specification eligibility.
Building information modeling integration is altering how structural engineers specify tensile fabrics, with geometry-to-fabrication data flows replacing manual patterning workflows. Specialist membrane contractors in Germany and Switzerland are requiring BIM-compatible material libraries from textile suppliers. This digitization is most advanced in sports stadium and airport terminal projects where cladding geometry complexity exceeds traditional patterning tolerance.
Buildtech Textiles Market Segmentation
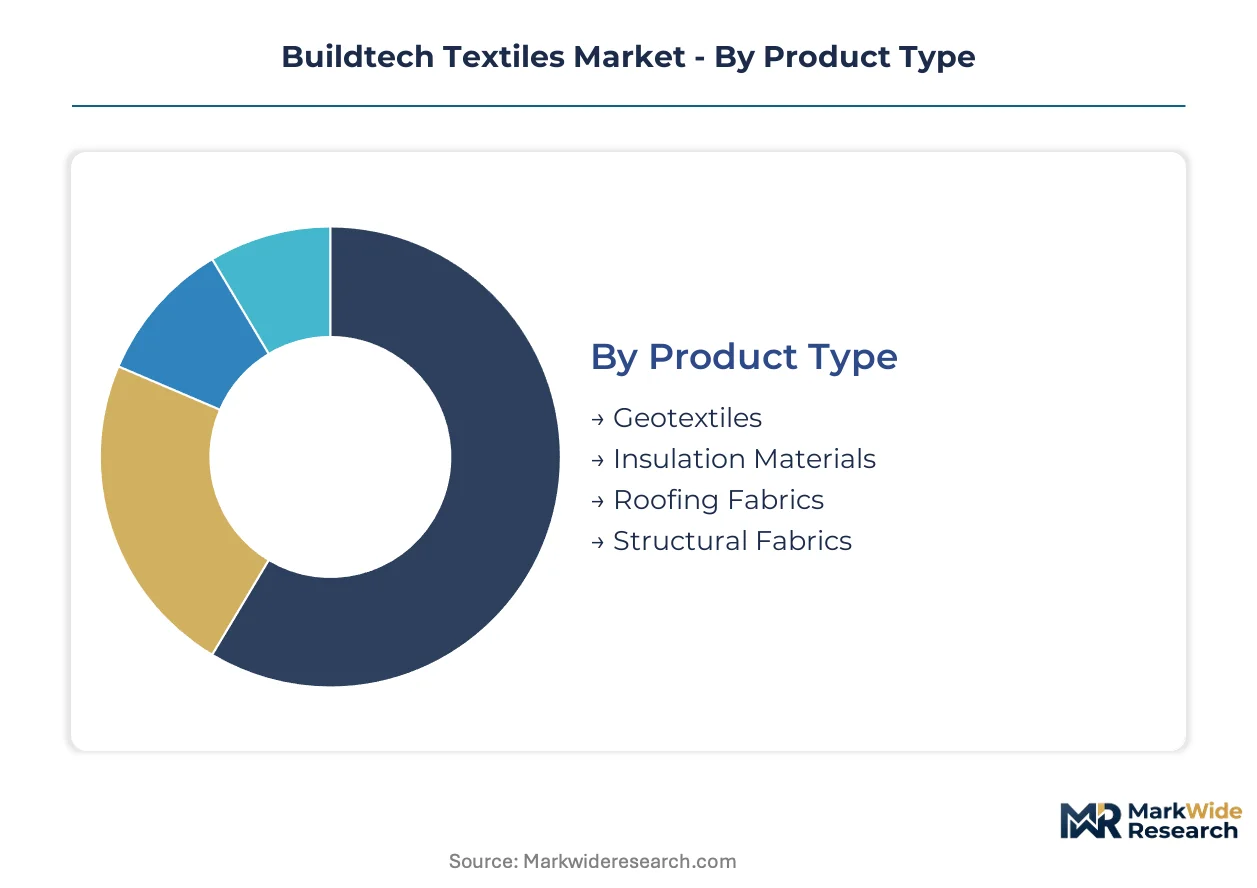
Segmentation in Buildtech Textiles reveals divergent capital requirements and margin profiles across product architectures. Specification patterns vary sharply by end-use, with civil engineering contractors prioritizing standardized geotextiles while architects commission custom structural membranes.
Product Type:
Capital intensity peaks in structural fabric production, where multiaxial weaving and precision coating demand specialized loom investments exceeding standard nonwoven lines.
- Geotextiles:Woven and nonwoven polymer sheets engineered for soil stabilization, drainage, and erosion control, typically specified in 100-1500 gsm basis weights. German infrastructure renewal corridors are driving procurement of high-tenacity polyester woven variants for highway subgrade separation, with BIS certification requirements tightening qualified supplier pools in India.
- Structural Fabrics:High-performance tensile membranes manufactured from PTFE-coated glass fiber or silicone-coated aramid, designed for long-span architectural applications. Demand concentrates in sports stadium and airport terminal projects across Germany and Switzerland, where BIM-integrated specification workflows favor suppliers with parametric material libraries.
- Insulation Materials:Nonwoven batts and reflective barriers providing thermal resistance in building envelopes.
- Roofing Fabrics:Bituminous and synthetic membranes for waterproofing and weatherproofing applications.
Geotextiles absorb the bulk of installed capacity; structural fabrics are expanding most quickly.
Application:
Volume distribution skews toward heavy civil works, though margin concentration follows specification complexity and regulatory testing burdens.
- Civil Engineering:Geotextile deployment for roadways, railways, embankments, and landfills requiring soil reinforcement and filtration. NHAI tenders in India specify BIS-certified products for slope protection, while German contractors consolidate qualified supplier lists around EN 13249 compliance for rail projects.
- Construction:Building envelope applications including roofing, waterproofing, and interior finishes. EPA volatile organic compound limits are forcing U.S. coating facilities toward water-based acrylic reformulations or thermal oxidizer investments.
- Environmental Protection:Containment and remediation textiles for landfill liners and erosion control.
- Fire Safety:E-glass and ceramic fiber fabrics meeting ASTM E84 and EN 13501-1 ratings for fire-rated building envelopes.
Civil engineering commands the greatest tonnage; construction applications yield the highest value per square meter.
Material:
Feedstock selection determines recycling pathway viability and regulatory compliance trajectory under EU circularity mandates.
- Polyester:PET and rPET yarns dominating geotextile production through cost-performance balance. Municipal waste processors in the Netherlands and Belgium are partnering with nonwoven manufacturers to decentralize rPET supply chains near post-consumer bottle collection hubs.
- Fiber Glass:E-glass roving for fire-rated membranes and tensile structures, with supply routing through concentrated state-controlled Chinese producers. PTFE-coated variants command 25-year weathering warranties in European tensile architecture specifications.
- Polypropylene:Staple fiber for chemical-resistant geotextiles and erosion control applications.
- Nylon:PA6 and bio-based PA11 yarns penetrating architectural membrane markets seeking reduced carbon intensity.
Polyester accounts for the largest production footprint; fiber glass is gaining share fastest in premium specification tiers.
End User:
Procurement authority and technical specification depth vary dramatically across the value chain, shaping supplier engagement models.
- Contractors:Civil engineering and construction firms executing infrastructure and building projects, prioritizing certified product availability and logistics reliability. German highway expansion projects specify pre-qualified geotextile suppliers with integrated quality documentation systems.
- Architects:Design professionals specifying structural membranes and aesthetic building textiles, increasingly requiring BIM-compatible material libraries and digital patterning capabilities for complex geometry projects.
- Building Owners:Asset holders influencing long-durability roofing and facade material selections.
- Developers:Project sponsors balancing first-cost and lifecycle performance in procurement decisions.
Contractors drive the greatest procurement volume; architects control specification for the highest-margin structural fabric applications.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European Buildtech Textiles demand, with German infrastructure renewal driving geotextile procurement across highway and rail embankment projects.
Germany
Bavaria and North Rhine-Westphalia concentrate PTFE-coated glass fiber production for tensile architecture applications. EN 13249 certification requirements for rail projects extend supplier qualification timelines to 18 months. Stuttgart and Munich engineering clusters specify BIM-integrated membrane libraries for stadium and airport terminal developments.
United States
Georgia and South Carolina coating facilities face EPA volatile organic compound emission limits requiring thermal oxidizer investments or water-based acrylic reformulations. Southeast roofing membrane producers accelerate reformulation to maintain architectural specification eligibility. Texas and Florida civil contractors drive geotextile volume for highway expansion and coastal erosion control.
India
Maharashtra and Gujarat textile belts supply BIS-certified polyester geotextiles for National Highway Authority of India tenders. NHAI slope protection specifications tighten qualified vendor pools around integrated quality documentation systems. Delhi-Mumbai Industrial Corridor infrastructure buildout concentrates demand in western and northern states.
China
Shandong and Zhejiang provinces dominate E-glass roving output for fire-rated building envelope applications. State-controlled fiber producers control export routing for ASTM E84 and EN 13501-1 compliant materials. Yangtze River Delta coating converters serve domestic tensile architecture and export membrane markets.
Netherlands
Rotterdam municipal waste processors partner with nonwoven manufacturers to decentralize rPET yarn production near post-consumer bottle collection hubs. REACH chemical compliance drives coating reformulation among Antwerp-Rotterdam port cluster finishers. Distributed fiber spinning compresses virgin polyester price premiums in Benelux civil engineering tenders.
Buildtech Textiles Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and specification complexity. The vendor base stratifies into three tiers: integrated fiber-to-fabric producers with captive polymer supply, specialized coating finishers with regulatory compliance depth, and regional converters serving price-sensitive civil engineering tenders. Consolidation pressures concentrate among mid-scale European weavers facing REACH reformulation costs. Dominant competitive moves include backward integration into rPET collection networks and strategic partnerships with municipal waste processors for fiber feedstock security.
Within the integrated fiber-to-fabric tier, DuPont and Ahlstrom-Munksjö occupy positions reflecting fluoropolymer expertise and pulp-to-fiber operational integration respectively. SRF Limited represents the scale-driven polyester yarn archetype serving infrastructure export markets. These three entities exemplify divergent strategic postures: specialty chemistry depth, sustainable nonwoven supply chain control, and industrial yarn manufacturing scale.
| Leading Market Players |
|---|
| DuPont |
| Ahlstrom-Munksjö |
| SKAPS Industries |
| Toray Industries |
| SRF Limited |
| 3M |
| Low & Bonar |
| Officine Maccaferri SpA |
| Delcotex |
| Others |
Supply Flow & Price Mechanics
German civil engineering contractors concentrate procurement authority for geotextile reinforcement, locking contract structures around 18-month EN 13249 certification timelines and compressing margin flexibility for non-integrated spinners.
Pricing Analysis
Value-based pricing anchors on 25-year weathering warranties for PTFE-coated glass fiber tensile membranes specified in Stuttgart and Munich stadium projects. Price differentiation separates EN 13501-1 fire-rated structural fabrics from commodity polyester geotextiles serving NHAI tenders. Pricing pressure stems from PTA and MEG feedstock volatility squeezing non-integrated polyester yarn producers. Civil engineering contractors exhibit highest price sensitivity; architects specifying BIM-integrated membrane libraries show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and Rotterdam-Antwerp port cluster manage just-in-time geotextile logistics for German infrastructure renewal. Raw material supply draws from Shandong and Zhejiang E-glass roving producers, Rotterdam municipal rPET collection hubs, and integrated pulp-to-fiber operations in Finland. Single-source vulnerability concentrates in Chinese state-controlled fiber glass exports. Distribution runs through qualified vendor pools with integrated quality documentation systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical compliance operates as a cost-of-compliance moat, forcing coating reformulation investments that lock out uncertified competitors from European architectural membrane tenders.
For Market Incumbents: To counter rPET supply chain decentralization by municipal waste processors, secure backward integration into post-consumer bottle collection networks and deepen captive fiber spinning capacity near Rotterdam and Antwerp hubs. For New Entrants and Emerging Players: Enter via BIS-certified geotextile supply for NHAI slope protection tenders in Maharashtra and Gujarat, where integrated quality documentation systems remain underdeveloped among regional converters. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European weavers facing REACH reformulation cost burdens in the Benelux corridor, with long-term viability hinging on circularity infrastructure ownership; watch for EU extended-producer-responsibility rule acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Collection | Rotterdam municipal partnerships secure fiber feedstock against virgin polyester price volatility. |
| REACH-Compliant Coating Reformulation | Antwerp-Rotterdam port cluster finishers capture first-mover advantage in ECHA substance restrictions. |
| BIM-Compatible Material Library Development | Stuttgart engineering clusters specify parametric data flows for complex tensile architecture geometry. |
| EN 13249 Certification Investment | German rail embankment projects consolidate procurement around 18-month qualified supplier timelines. |
| Bio-Based PA11 Yarn Scale-Up | Castor oil-derived polyamide penetrates European architectural membrane specifications seeking carbon intensity reduction. |
Methodological Framework
Independent corroboration across civil engineering procurement directors, coating facility technical managers, and municipal waste processor operations heads underwrites the qualitative findings. Primary fieldwork engaged plant managers at Rhine-Ruhr multiaxial weaving operations, NHAI project engineers, and Antwerp-Rotterdam port cluster finishers. Secondary validation drew from REACH substance restriction databases, BIS certification registries, and EN 13249 testing protocol documentation. Bottom-up segment sizing triangulated against top-down construction spend allocation models.
Rate-of-change decomposition separated volume drivers from value mix shifts across the projection horizon. The analytical framework modeled product type, material feedstock, application end-use, and regional regulatory cluster dimensions. CAGRs derived from iterative convergence between historical trajectory analysis and forward scenario weighting. Industry-specific forecast inputs included German infrastructure renewal corridor spend patterns and EPA VOC emission limit compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU circularity mandate acceleration or China E-glass export restriction scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
US Geotextile Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
E-Textile Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Active Smart Textiles Market