
 Smart Fabrics for Transportation Market | 2026-2036
Smart Fabrics for Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fabrics for Transportation Market Analytics
Software-defined thermal management is expanding the addressable value per vehicle seat, converting one-time fabric sales into recurring feature licenses. Schoeller Textil AG leverages its Swiss manufacturing base to sustain premium positioning in conductive textile laminates for aerospace cabins. Teijin Limited anchors Asian supply security through captive aramid fiber production, while DuPont de Nemours competes on fluoropolymer coating chemistry for durable sensor integration.
Smart fabrics for transportation integrate electrically active yarns, conductive polymers, or microelectronic components into woven, knitted, or nonwoven substrates to enable real-time physiological monitoring, adaptive heating, or occupant detection in mobile environments. These textiles typically incorporate silver-coated nylon threads with surface resistivity below 10 ohms per square, manufactured through warp knitting with embedded copper bus bars for signal routing. Sensor-embedded fabrics now capture the deepest margin pools as automotive OEMs spec capacitive pressure matrices for occupancy classification, while heating fabrics dominate current shipment volumes across cold-climate vehicle configurations. Nanotechnology applications in conductive coatings represent the fastest-growing technology segment, though integrated systems command premium pricing due to firmware and calibration complexity.
FAA airworthiness directives and ECE R14 safety standards shape crash-testable textile performance requirements, compelling suppliers to maintain dual certification pipelines. NHTSA FMVSS 302 flammability testing and REACH SVHC substance restrictions further constrain material selection, favoring halogen-free conductive polymers. Stakeholders must monitor evolving type-approval timelines as regulatory bodies develop specific test protocols for textile-integrated electronics rather than applying legacy component standards.
Market Dynamics
Automotive electrification is compressing thermal management cycles and forcing textile suppliers to embed sensor-integrated heating layers directly into seat architectures rather than treating them as aftermarket accessories.
Growth Catalysts
- EU Green Deal chemical compliance:REACH SVHC substance restrictions are compelling European automotive suppliers to accelerate adoption of halogen-free conductive polymers in seat heating systems.
- Sensor-embedded fabrics:Capacitive pressure matrices for occupant classification are capturing premium specification slots as NHTSA FMVSS 302 flammability testing validates crash-testable textile performance.
- German R&D concentration:BMW and Volkswagen supplier networks have integrated smart textile prototyping pipelines that pull adjacent European component makers into conductive yarn development.
Market Restraints
- Silver-coated nylon input volatility:Surface resistivity specifications below 10 ohms per square require precious metal feedstocks exposed to commodity price swings.
- Dual certification pipeline costs:FAA airworthiness directives and ECE R14 safety standards force suppliers to maintain parallel testing regimes for aerospace and automotive verticals.
- Legacy component standard misapplication:Regulatory bodies currently apply textile-integrated electronics to legacy hardware test protocols, creating approval timeline uncertainty.
Strategic Opportunities
- Software-defined thermal licensing:Feature-based monetization models convert one-time fabric sales into recurring revenue streams through firmware-enabled heating calibration.
- Indian electric vehicle assembly:PLI scheme incentives for domestic manufacturing are creating first-mover openings for conductive textile laminates in emerging OEM supply chains.
- Aramid fiber captive supply:In-house production of high-performance substrates enables Asian suppliers to bypass Western coating chemistry dependencies.
Industry Challenges
- Embedded systems firmware calibration:Capacitive pressure matrix integration requires specialized signal processing expertise scarce among traditional textile engineers.
- Copper bus bar warp knitting retrofit:Legacy knitting equipment cannot accommodate conductive thread routing without substantial capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fabrics for Transportation Market |
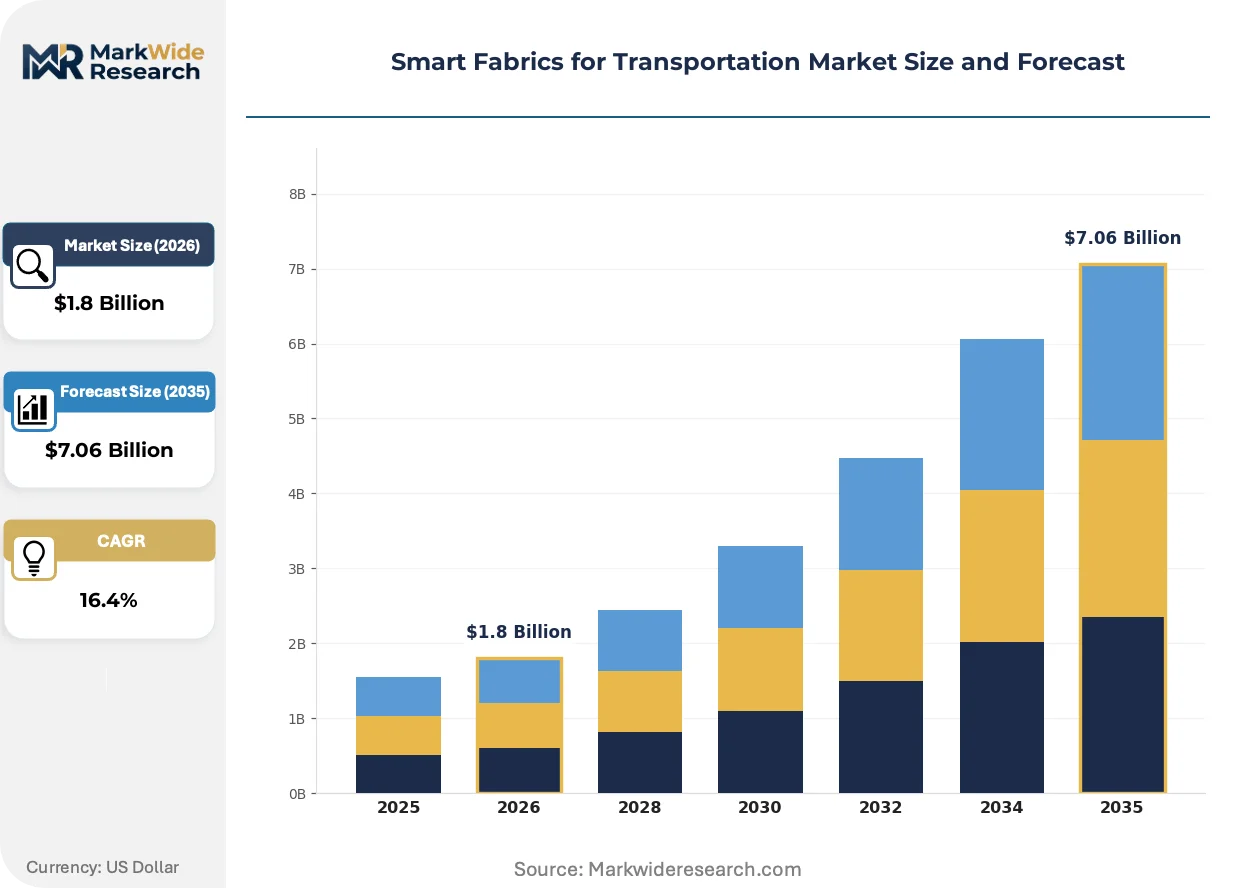
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Fabrics, Heating Fabrics, Sensor-Embedded Fabrics, Wearable Technology Fabrics Application: Vehicle Interiors, Safety Equipment, Wearable Devices, Telematics Systems End User: Automotive Manufacturers, Aerospace Companies, Public Transportation, Fleet Operators Technology: Textile Electronics, Nanotechnology, Smart Sensors, Integrated Systems |
| Companies Covered | Schoeller Textil AG, Teijin Limited, AIQ Smart Clothing Inc., DuPont de Nemours, Toray Industries, Kolon Glotech Inc., Ohmatex, Koninklijke Ten Cate B.V., Interactive Wear AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fabrics for Transportation Market Evolving Landscape
Nanotechnology applications in conductive coatings are compressing manufacturing steps while regulatory bodies scramble to develop textile-specific electronics protocols rather than adapting legacy hardware standards.
Silver nanowire dispersions are replacing continuous metal threads in heating fabric applications. Tier 1 automotive seating suppliers are specifying these materials for 2027 electric vehicle platforms. This substitution is integrating microelectronic functionality directly into warp-knitted substrates without separate wiring harness attachment.
ECHA REACH authorization requirements for persistent organic pollutants are forcing reformulation of fluoropolymer coating chemistries. DuPont de Nemours and European competitors are accelerating halogen-free alternatives through pre-registration data sharing. Aerospace cabin textile specifications in Switzerland and Germany are most affected, with Swissmedic-equivalent material safety protocols now requiring substance-level traceability.
Fleet procurement departments are unbundling after-sales sensor calibration from initial fabric supply contracts. Rental vehicle operators and shared mobility platforms now demand firmware update subscriptions separate from hardware purchase. This disintermediation is most visible in German corporate fleet channels, where BMW and Volkswagen leasing subsidiaries are piloting usage-based heating feature activation.
Smart Fabrics for Transportation Market Segmentation
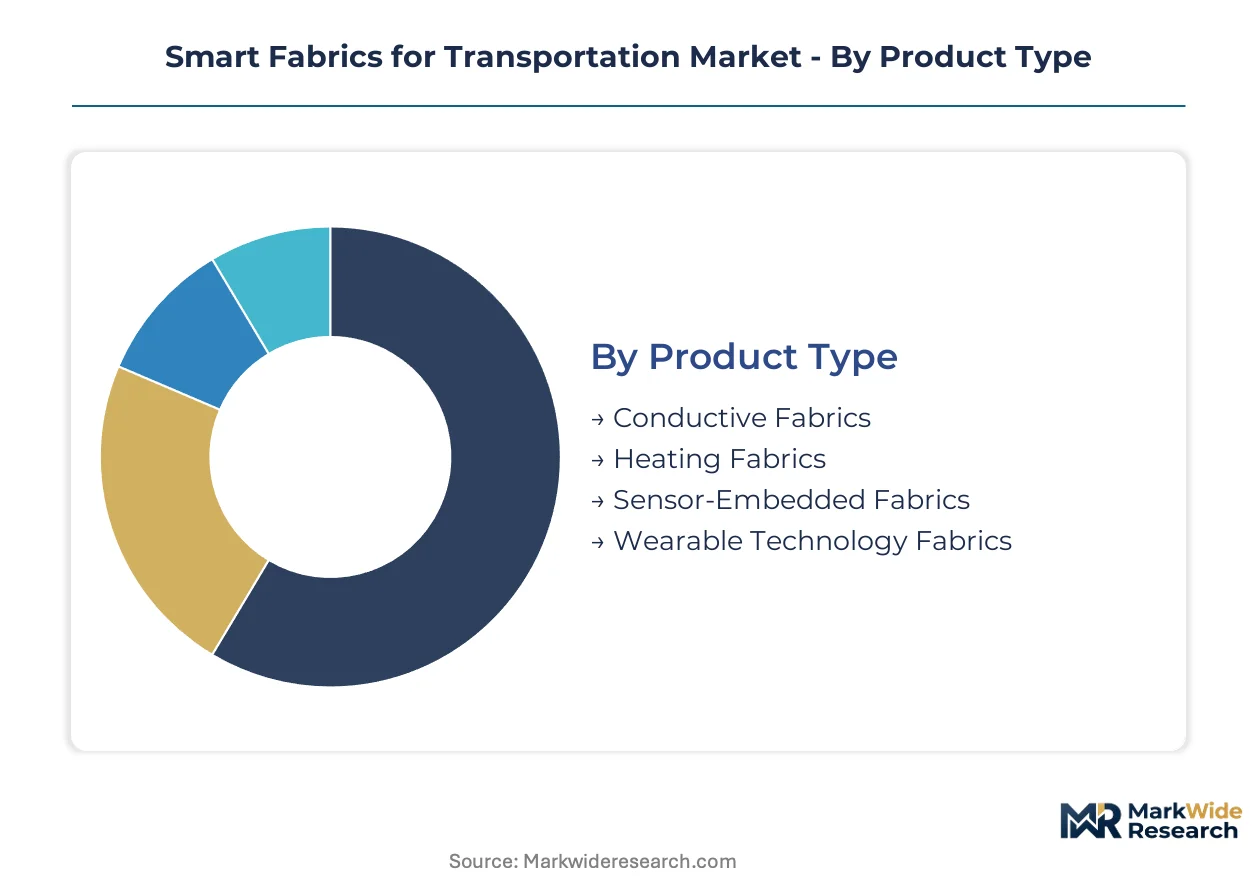
Smart fabric architectures in transportation demand precise segmentation because vehicle electrification and regulatory compliance create divergent technical requirements across seating, safety, and connectivity applications. Upgrade cycles now separate hardware substrate sales from firmware-enabled feature licensing, reshaping how suppliers position across product tiers.
Product Type:
Replacement cycles for conductive textile systems accelerate as automotive OEMs redesign seat architectures around electric vehicle thermal management requirements.
- Sensor-Embedded Fabrics:Capacitive pressure matrices integrate silver-coated nylon threads with copper bus bar routing for real-time occupant classification. BMW and Volkswagen supplier networks in Germany specify these for crash-testable seat systems under ECE R14 safety standards.
- Heating Fabrics:Warp-knitted substrates with embedded conductive yarns deliver adaptive thermal management through resistive heating layers. Cold-climate vehicle configurations across Nordic automotive markets drive current shipment volumes, with REACH SVHC compliance forcing halogen-free polymer reformulation.
- Conductive Fabrics:Woven or knitted textiles with surface resistivity below 10 ohms per square enable signal routing without discrete wiring harnesses.
- Wearable Technology Fabrics:Stretchable conductive substrates integrate physiological monitoring for professional drivers in long-haul fleet applications.
Heating fabrics sit at the top of the volume ranking, with sensor-embedded fabrics climbing the fastest.
Application:
Cost tier differentiation separates premium cabin configurations from standard fleet specifications, with telematics integration commanding hardware-plus-software bundled pricing.
- Vehicle Interiors:Seat covers, headliners, and dashboard wraps incorporate conductive laminates for heating and capacitive control interfaces. German automotive R&D pipelines prioritize these applications for next-generation electric vehicle platforms.
- Safety Equipment:Airbag deployment sensors and seatbelt tension monitors embed conductive threads directly into textile substrates. FAA airworthiness directives for aerospace cabins impose dual certification requirements alongside automotive ECE R14 standards.
- Wearable Devices:Integrated garments for commercial drivers capture biometric data through textile-embedded electrodes.
- Telematics Systems:Antenna-integrated fabrics enable vehicle-to-infrastructure communication without external hardware protrusions.
Vehicle interiors capture the dominant revenue share, while safety equipment gains share fastest on regulatory compliance mandates.
End User:
Customer type determines procurement sophistication, with fleet operators pioneering usage-based feature licensing distinct from upfront hardware acquisition.
- Automotive Manufacturers:Tier 1 seating suppliers specify conductive textiles for electric vehicle thermal management systems. German OEM prototyping pipelines pull adjacent European component makers into conductive yarn development networks.
- Fleet Operators:Rental and shared mobility platforms unbundle sensor calibration from initial fabric supply, demanding firmware update subscriptions separate from hardware purchase. This disintermediation is most visible in German corporate fleet channels.
- Aerospace Companies:Cabin textile specifications in Switzerland and Germany require Swissmedic-equivalent material safety protocols with substance-level traceability.
- Public Transportation:Municipal transit authorities specify durable heating fabrics for cold-climate bus and rail seating on constrained maintenance budgets.
Automotive manufacturers sit at the top of the volume ranking, with fleet operators climbing the fastest on subscription monetization models.
Technology:
Supply concentration in coating chemistry and fiber production shapes competitive positioning across integrated system architectures.
- Integrated Systems:Combined hardware-firmware platforms embed microelectronic components with calibration software for capacitive sensing and thermal control. DuPont de Nemours competes on fluoropolymer coating chemistry for durable sensor integration in these systems.
- Nanotechnology:Silver nanowire dispersions replace continuous metal threads, compressing manufacturing steps while maintaining conductivity specifications. Teijin Limited anchors Asian supply security through captive aramid fiber production for these substrates.
- Textile Electronics:Conductive yarn systems manufactured through warp knitting with embedded bus bars enable signal routing without separate wiring.
- Smart Sensors:Discrete sensing elements integrated into woven or nonwoven substrates capture pressure, temperature, or biometric data.
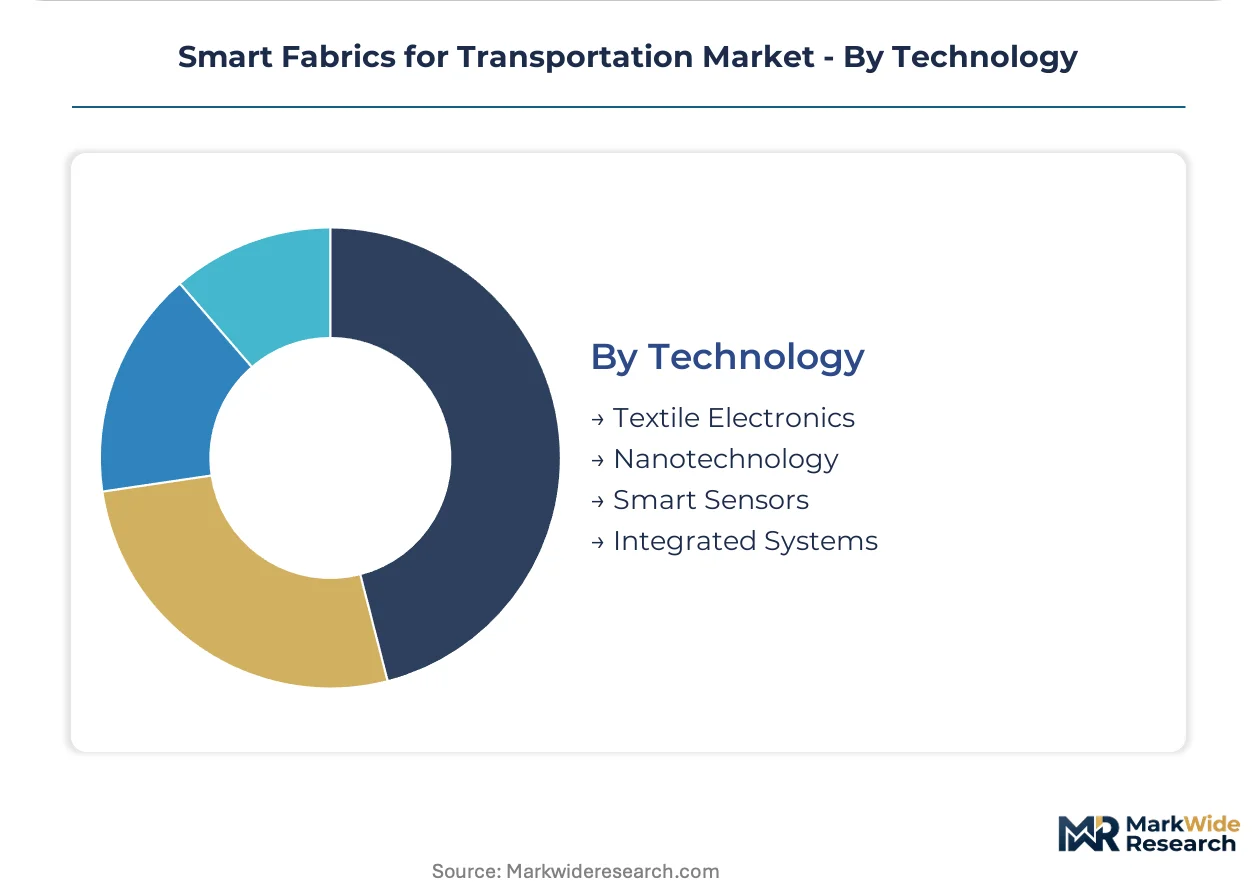
Integrated systems sit at the top of the volume ranking, with nanotechnology climbing the fastest on manufacturing efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more smart textile R&D investment than any other European country, while India scales domestic manufacturing capacity faster through production-linked incentives.
Germany
BMW and Volkswagen supplier networks pull adjacent component makers into conductive yarn development pipelines. ECHA REACH authorization requirements for persistent organic pollutants force halogen-free coating reformulation. Stuttgart and Munich clusters prototype sensor-embedded seat architectures for next-generation electric vehicle platforms.
United States
NHTSA FMVSS 302 flammability testing validates crash-testable textile performance for capacitive pressure matrices. FAA airworthiness directives impose dual certification requirements on aerospace cabin textile suppliers. Detroit automotive seating R&D and Seattle-area aerospace engineering centers drive specification development.
China
Domestic electric vehicle OEMs compress thermal management cycles and force direct integration of heating layers into seat architectures. MIIT standards for vehicle component safety shape textile-integrated electronics protocols. Yangtze River Delta manufacturing bases scale silver nanowire dispersion production for 2027 vehicle platforms.
Switzerland
Swissmedic-equivalent material safety protocols now require substance-level traceability for aerospace cabin textiles. Schoeller Textil AG leverages its domestic manufacturing base to sustain premium positioning in conductive laminates. Zurich and St. Gallen technical textile clusters serve German automotive and aerospace specification channels.
India
PLI scheme incentives for domestic electric vehicle assembly create first-mover openings for conductive textile laminates. BIS standards for automotive component safety gain alignment with ECE R14 frameworks. Tamil Nadu and Gujarat manufacturing corridors attract Tier 1 seating suppliers establishing localized sourcing.
Smart Fabrics for Transportation Market Competitive Landscape
Top-tier vendors anchor integrated system architectures, while mid-scale specialists concentrate on substrate manufacturing and coating chemistry. The vendor base stratifies across three tiers: multinational chemical conglomerates with fluoropolymer expertise, captive fiber producers with aramid supply security, and regional textile engineers with warp-knitting specialization. Dominant competitive moves include backward integration into conductive yarn production and firmware licensing partnerships that convert hardware sales into recurring revenue streams.
Within the premium-tier vector, Schoeller Textil AG and Teijin Limited exemplify divergent supply security strategies. The Swiss manufacturer occupies a position anchored in European aerospace certification pipelines, while the Japanese conglomerate represents captive aramid fiber production models that bypass Western coating chemistry dependencies. DuPont de Nemours sits within the chemical technology tier, competing on fluoropolymer coating chemistry for durable sensor integration.
| Leading Market Players |
|---|
| Schoeller Textil AG |
| Teijin Limited |
| AIQ Smart Clothing Inc. |
| DuPont de Nemours |
| Toray Industries |
| Kolon Glotech Inc. |
| Ohmatex |
| Koninklijke Ten Cate B.V. |
| Interactive Wear AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap textile specialists across Germany and Switzerland maintain pricing discipline through captive certification pipelines that lock OEM buyers into multi-year supply agreements. Their concentrated ownership structures limit price transparency and shield margin pools from commodity volatility in silver-coated nylon feedstocks.
Pricing Analysis
Capacity additions in China are reshaping price floors for conductive yarn substrates as Yangtze River Delta producers scale silver nanowire dispersion output. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant halogen-free systems from legacy fluoropolymer coatings. Pricing pressure stems from fleet operators unbundling firmware subscriptions from hardware procurement. Tier 1 automotive seating buyers exhibit lowest price sensitivity due to crash-test certification requirements, while municipal transit authorities face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Zurich, and Shanghai coordinate hub-and-spoke patterns for conductive textile laminates. Manufacturing concentrates in Germany, Switzerland, and China, with each node serving distinct certification ecosystems. Raw material flows draw from Japanese aramid fiber production, Swiss coating chemistry, and Chinese silver nanowire synthesis. Single-source vulnerability runs through Teijin's captive aramid supply. Distribution runs through Tier 1 seating supplier consolidation points before final vehicle assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart fabrics for transportation represent a late-cycle quality story as automotive electrification shifts procurement specifications toward firmware-integrated thermal systems with recurring revenue profiles.
For Market Incumbents: Hedge against silver-coated nylon input volatility through backward integration into conductive yarn production or long-term offtake agreements with precious metal refiners. Accelerate dual certification investments for FAA airworthiness and ECE R14 compliance to defend specification slots against emerging Asian competitors. Prioritize firmware licensing partnerships that convert one-time fabric sales into subscription revenue streams. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for conductive textile laminates in domestic electric vehicle assembly corridors. Target Tamil Nadu and Gujarat manufacturing clusters where Tier 1 seating suppliers seek localized sourcing alternatives to European imports. Pursue white-label substrate partnerships with established coating chemistry providers to bypass capital-intensive fluoropolymer R&D. For Investors and Strategic Acquirers: Valuations sit cheapest among regional warp-knitting specialists with embedded copper bus bar capabilities but lacking integrated firmware platforms. Five-to-ten year viability hinges on software-defined thermal licensing adoption across German and Chinese OEM fleets. Watch for inflection when NHTSA issues textile-specific electronics test protocols replacing legacy component standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Yarn Production | Captive silver-coated nylon output insulates Schoeller Textil from precious metal price swings. |
| Dual Certification Pipeline Investment | Parallel FAA and ECE R14 testing secures specification slots in aerospace and automotive verticals. |
| Firmware Licensing Partnership | Subscription-based thermal calibration converts DuPont coating chemistry into recurring revenue streams. |
| Regional Manufacturing Footprint Expansion | PLI scheme incentives enable first-mover positioning in Tamil Nadu electric vehicle supply chains. |
| Halogen-Free Coating Reformulation | REACH SVHC compliance opens German OEM procurement channels previously closed to fluoropolymer incumbents. |
Research Methodology
Multiple input streams — procurement leads at Tier 1 seating suppliers, technical textile R&D directors, regulatory affairs specialists at ECHA and NHTSA, and fleet operator sustainability officers — were reconciled against customs records, vehicle production databases, and REACH pre-registration filings. Primary interviews with BMW and Volkswagen supplier network managers informed specification timelines, while secondary validation drew from IHS Markit registration data and SEC 10-K disclosures from chemical conglomerates. Bottom-up unit economics for conductive fabric content per vehicle were triangulated against top-down market sizing from automotive production forecasts.
Historical shipment trajectories for heating fabrics and sensor-embedded systems were cross-referenced against panel input from platform engineers at German and Chinese OEMs across the analysis window. Segmentation modeling incorporated product type, application, end user, and technology dimensions alongside vehicle propulsion architecture and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves calibrated to electric vehicle thermal management redesign cycles and REACH compliance deadlines.
Revisions become necessary when regulatory bodies accelerate textile-specific electronics protocols, when silver nanowire dispersion manufacturing achieves cost parity with continuous metal threads, or when fleet operators abandon subscription models for bundled hardware-software procurement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Webbing Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
US Geotextile Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Absorbent Cover Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Wet-Molded Fibre Market