
 Fire Retardant Fabrics Market | 2026-2036
Fire Retardant Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Retardant Fabrics Market Foresight
China is tilting toward expanded aramid fiber capacity to serve domestic aerospace and military procurement. DuPont de Nemours, Inc. anchors North American supply through integrated Nomex production from raw polymer to finished fabric. Teijin Ltd. leverages its para-aramid technology leadership to dominate Japanese defense and aviation contracts. Asahi Kasei Advance Corporation specializes in flame-resistant non-woven solutions for automotive battery enclosures.
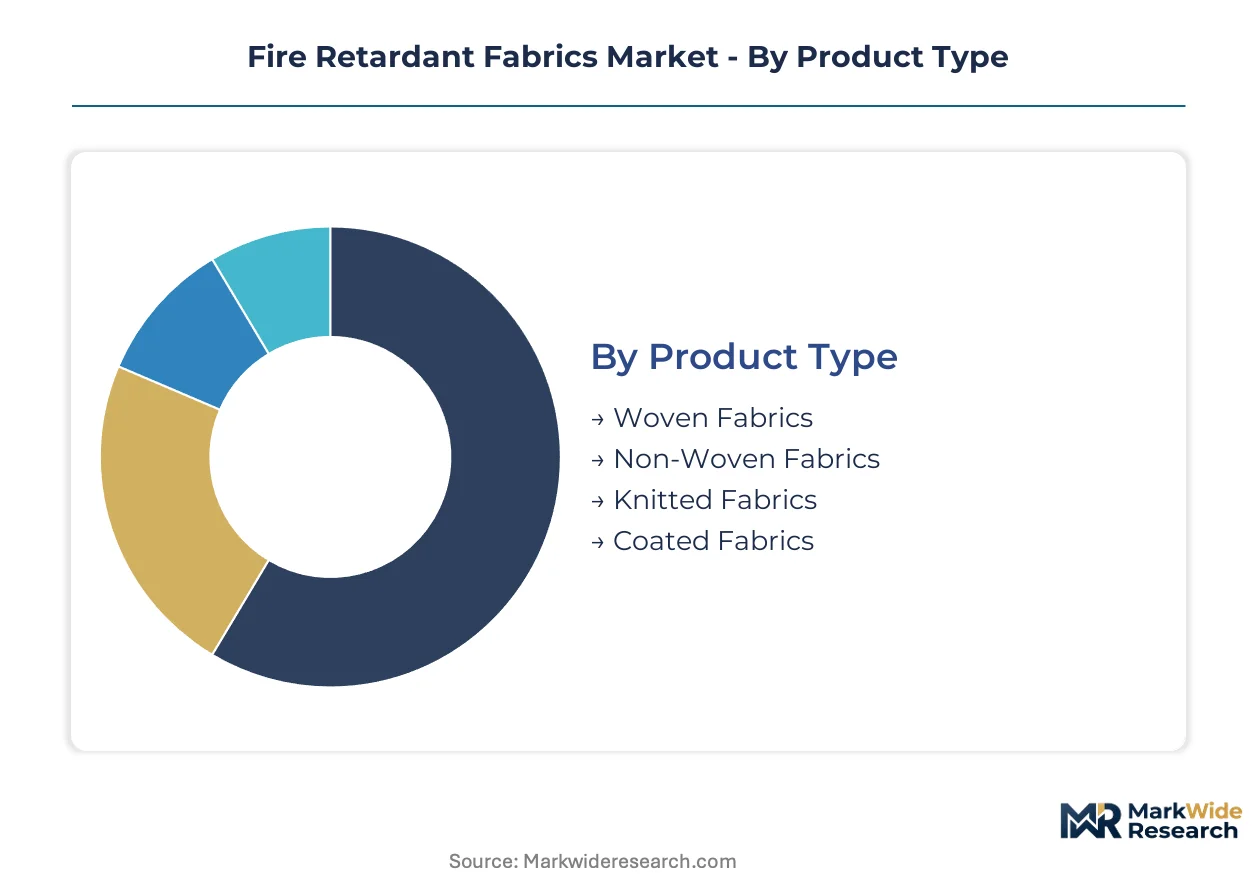
Fire retardant fabrics are engineered textiles treated with halogen-free or phosphorus-based compounds, or constructed from inherently flame-resistant fibers such as aramids and oxidized acrylics, to self-extinguish when exposed to ignition sources and limit heat release rates below regulatory thresholds. These materials primarily protect personnel and structures in high-heat environments across aerospace, defense, and industrial sectors. Woven fabrics occupy the largest value share due to their structural integrity in protective clothing and military uniforms, while coated fabrics represent the fastest-expanding category as electric vehicle thermal barrier specifications tighten. Among end users, aerospace and military procurement commands premium pricing, whereas construction applications face margin compression from commoditized polyester alternatives.
The EU Green Deal and REACH frameworks restrict halogenated flame retardants, forcing reformulation toward phosphorus and nitrogen chemistries. The U.S. FAA and NFPA 2112 standards mandate specific heat-flux performance for aviation and industrial protective garments, creating compliance barriers for new entrants. Stakeholders must monitor evolving battery enclosure standards in automotive and energy storage sectors, where thermal runaway protection is becoming a design-critical specification.
Market Dynamics
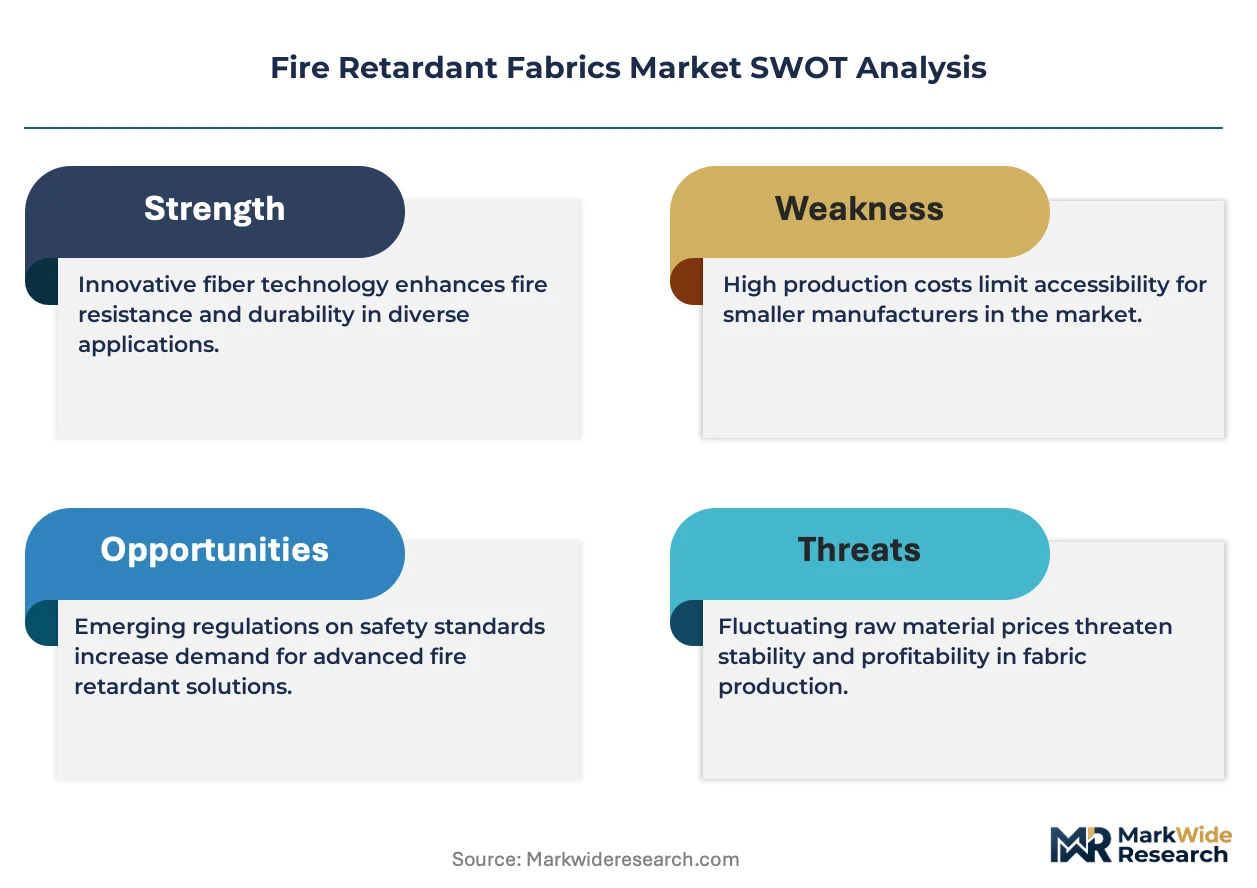
REACH chemical restrictions and the EU Green Deal are forcing wholesale reformulation of flame-retardant chemistries, compressing margins for halogen-dependent producers while opening premium positioning for phosphorus-based and bio-derived alternatives.
Growth Catalysts
- Aerospace manufacturing expansion:Commercial aircraft production rates are climbing, with thermal protection systems for engine nacelles and cabin interiors driving specification-grade fabric procurement.
- EU Green Deal chemical phase-outs:The framework's restriction of halogenated flame retardants is redirecting R&D investment toward nitrogen and phosphorus chemistries with superior environmental profiles.
- German industrial safety textile cluster:Concentrated expertise around Aachen and Chemnitz is accelerating technology transfer from research institutions to protective clothing manufacturers serving automotive and chemical processing sectors.
Market Restraints
- Aramid fiber supply concentration:Para-aramid capacity remains controlled by a handful of polymer producers, exposing fabric converters to input price volatility and allocation constraints during defense procurement surges.
- REACH compliance cost escalation:Registration and authorization requirements for novel flame-retardant chemistries extend development timelines and inflate fixed costs for mid-tier formulators.
- Polyester substitution in construction:Commodity-grade treated polyester fabrics are capturing volume in non-critical building applications, eroding pricing power for engineered solutions.
Strategic Opportunities
- Electric vehicle battery enclosures:Thermal runaway protection specifications are creating demand for coated aramid barriers between battery modules, with automotive OEMs seeking qualified suppliers.
- China's domestic aerospace buildout:Indigenous narrow-body programs are expanding qualified supplier lists for cabin interior fabrics, opening channels for certified foreign producers.
- NFPA 2112 industrial certification:The standard's adoption by oilfield services and petrochemical operators is mandating replacement cycles for legacy protective garments.
Industry Challenges
- Flammability testing bottleneck:Limited accredited laboratories for cone calorimetry and vertical flame testing are extending certification timelines for new product introductions.
- Multi-standard compliance complexity:Simultaneous adherence to FAA heat-flux requirements, NFPA thermal performance thresholds, and REACH chemical restrictions demands specialized regulatory affairs capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Retardant Fabrics Market |
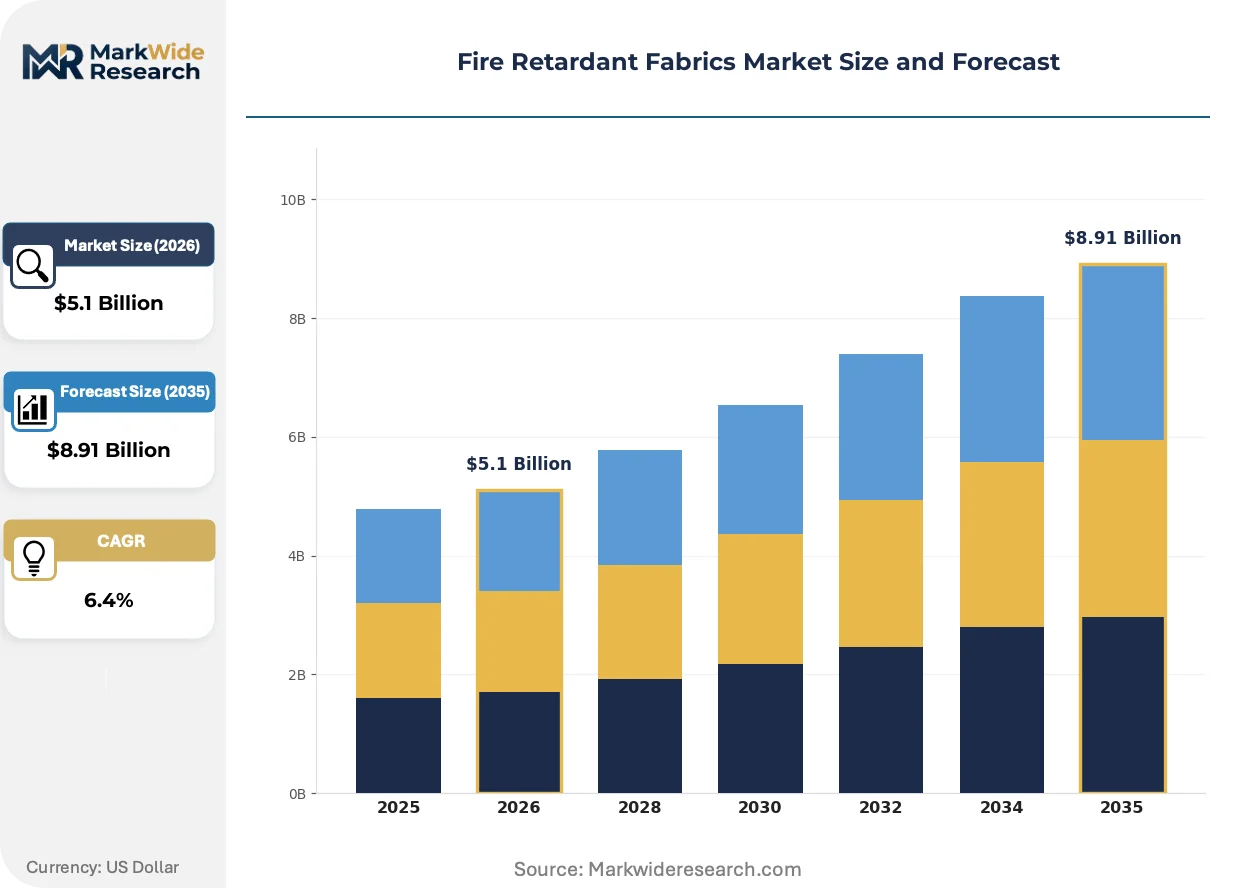
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Fabrics Application: Protective Clothing, Upholstery, Interior Furnishings, Vehicle Covers End User: Aerospace, Automotive, Military, Construction Material: Fiberglass, Nomex, Trevira, Polyester, Others |
| Companies Covered | Asahi Kasei Advance Corporation, Koninklijke Ten Cate bv, DuPont de Nemours, Inc., W. L. Gore & Associates, Inc., Lenzing AG, Huntsman Corporation, Kaneka Corporation, Teijin Ltd., Milliken & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Retardant Fabrics Market Shifts & Advancements
Digital manufacturing tools are penetrating textile engineering workflows, compressing development cycles and enabling mass-customization of protective garments. Three developments are restructuring competitive positioning.
Artificial intelligence-driven weave simulation is digitizing the prototyping phase for multi-layer protective fabrics. Aerospace contractors in Germany and the United States are deploying these platforms to optimize thermal barrier designs before physical sampling. The technology is compressing supplier qualification timelines from eighteen months to under eight months for derivative products.
The EU F-Gas Regulation and associated REACH amendments are accelerating substitution of halogenated flame retardants in coated fabrics. Industrial laundries serving European oil and gas operators are rejecting garments containing restricted substances to avoid downstream liability. Fabric finishers with validated phosphorus-nitrogen systems are capturing specification-driven procurement from integrated energy majors.
Direct contracting between end-use operators and certified fabric producers is displacing traditional distributor intermediaries in North American industrial safety. Large petrochemical and utility employers are establishing approved vendor lists based on NFPA 2112 certification status, bypassing regional safety equipment distributors. The pattern is most pronounced among Fortune 500 operators with centralized procurement functions and dedicated technical safety staff.
Fire Retardant Fabrics Market Segmentation
Fire retardant fabrics serve divergent performance requirements across aerospace thermal barriers, military protective systems, and automotive battery enclosures. Segmentation reveals how material chemistry and construction method determine specification grade and pricing tier in each vertical.
Product Type:
Mature woven constructions dominate procurement volumes while coated and non-woven formats emerge from electrification and filtration demand.
- Woven Fabrics:Interlaced aramid or fiberglass yarns deliver structural integrity for military uniforms and aerospace cabin interiors. German industrial safety textile clusters around Aachen supply specification-grade woven barriers to automotive chemical processing operators facing NFPA 2112 mandates.
- Coated Fabrics:Substrate fabrics impregnated with phosphorus-based flame-retardant polymers create flexible thermal barriers. Electric vehicle battery enclosure specifications from automotive OEMs are accelerating qualified supplier development for coated aramid inter-module separators.
- Non-Woven Fabrics:Entangled fiber mats produced through needle-punch or spunbond processes serve filtration and insulation layers.
- Knitted Fabrics:Loop-structured constructions provide elasticity for form-fitting protective garments in industrial applications.
Woven fabrics retain volume leadership; coated fabrics hold the steepest expansion curve.
Application:
Cost tiers separate specification-driven protective systems from commoditized interior treatments.
- Protective Clothing:Multi-layer aramid assemblies engineered to NFPA 2112 and FAA heat-flux standards protect workers in oilfield services and aircraft maintenance. Replacement cycles mandated by petrochemical operators in the United States are stabilizing demand for certified garment systems.
- Interior Furnishings:Upholstery fabrics for commercial aircraft cabins and rail vehicles must pass vertical flame testing while meeting smoke toxicity thresholds. REACH chemical restrictions are forcing reformulation of back-coating treatments in European supply chains.
- Upholstery:Residential and contract furniture applications face margin pressure from treated polyester alternatives.
- Vehicle Covers:Protective wraps for military and emergency service vehicles require weather resistance combined with ignition resistance.
Protective clothing commands premium pricing; interior furnishings face substitution pressure from lower-cost regions.
End User:
Customer type determines certification burden and procurement centralization.
- Aerospace:Commercial and defense aircraft programs specify thermally protective fabrics for engine nacelles, cargo liners, and seat assemblies. FAA certification requirements and Boeing-Airbus qualified supplier lists create structural barriers for new entrants.
- Military:Defense procurement agencies in Japan and the United States award long-term contracts for flame-resistant uniform and vehicle protection systems. Para-aramid allocation constraints during procurement surges expose fabric converters to input volatility.
- Automotive:Battery electric vehicle thermal runaway protection is emerging as a design-critical specification for coated fabric barriers.
- Construction:Building codes in Germany and France drive demand for fiberglass-based wall coverings and tensioned membrane structures.
Aerospace and military anchor premium tier pricing; automotive represents the fastest-growing trajectory.
Material:
Supply concentration varies sharply across fiber chemistries.
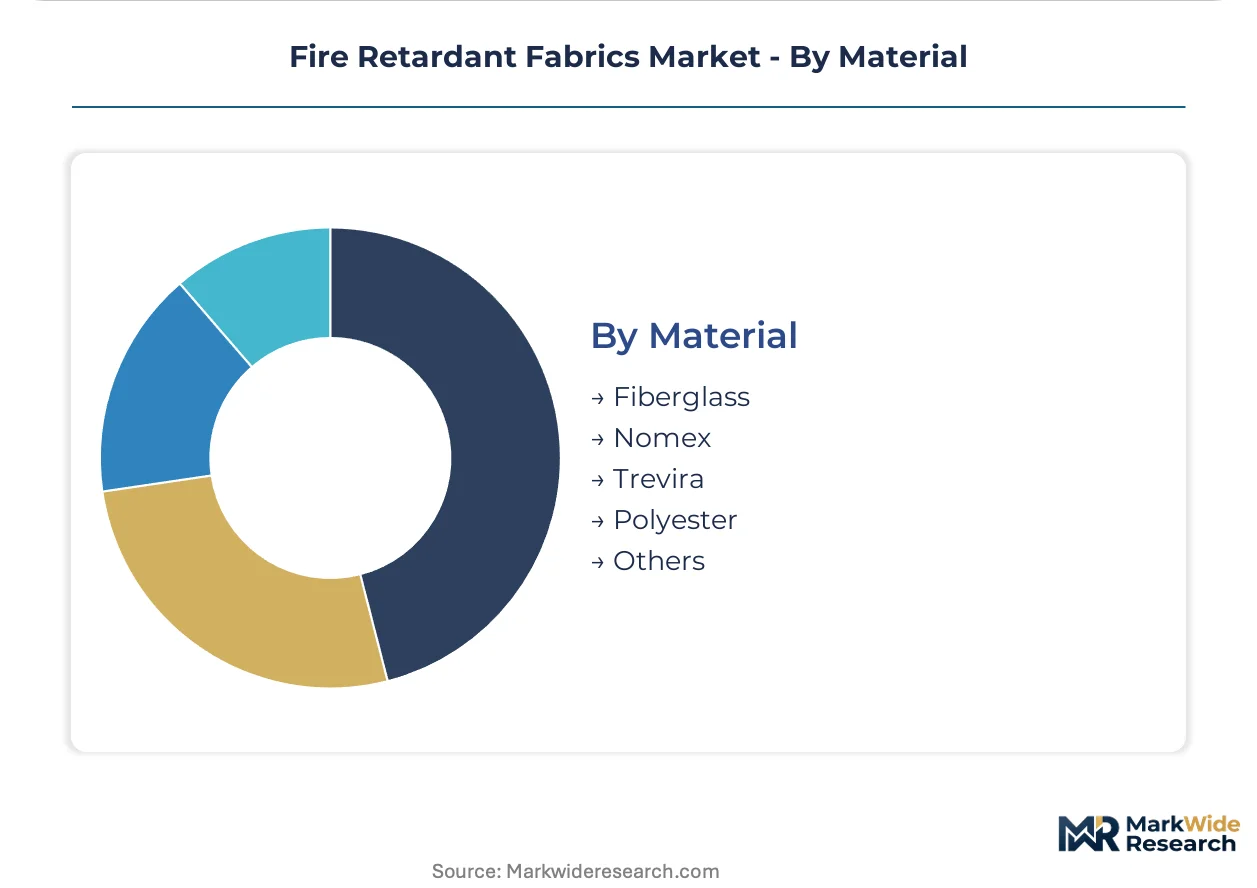
- Nomex:Meta-aramid polymer delivers inherent flame resistance without chemical treatment, maintaining protective properties through industrial laundering cycles. DuPont's integrated production from polymer to finished fabric anchors North American supply for aviation and military procurement.
- Fiberglass:Silica-based continuous filament fabrics withstand extreme temperatures for industrial insulation and construction membranes. Chinese capacity expansion is pressuring pricing in non-specification building applications.
- Polyester:Commodity fiber with topical flame-retardant finishes serves cost-sensitive upholstery and construction markets.
- Trevira:Inherently flame-resistant polyester variant developed through copolymer modification.
- Others:Oxidized acrylics and modacrylics serve niche protective clothing segments.
Fiberglass retains volume leadership; Nomex holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aramid polymer production clusters in the United States, Japan, and Germany shape upstream supply availability for fabric converters worldwide. REACH chemical restrictions in Europe and FAA certification requirements in North America create divergent compliance burdens across major demand centers.
United States
Commercial aircraft production at Boeing facilities in Washington and South Carolina drives specification-grade fabric procurement for engine nacelles and cabin interiors. The FAA mandates heat-flux performance standards under 14 CFR Part 25 that create structural barriers for uncertified suppliers. DuPont operates integrated Nomex production from polymer to finished fabric across southeastern manufacturing sites.
Germany
Industrial safety textile clusters around Aachen and Chemnitz accelerate technology transfer to protective clothing manufacturers serving automotive and chemical processing sectors. The EU Green Deal and ECHA REACH restrictions on halogenated flame retardants force reformulation toward phosphorus-based chemistries. RWTH Aachen University anchors research partnerships between polymer scientists and regional fabric finishers.
China
Indigenous narrow-body aircraft programs at COMAC expand qualified supplier lists for cabin interior fabrics and thermal protection systems. MIIT and GB standards for textile flammability tighten import requirements for foreign producers. Aramid fiber capacity expansion in Jiangsu and Shandong provinces targets domestic aerospace and military procurement.
Japan
Defense procurement agencies award long-term contracts for flame-resistant uniform and vehicle protection systems to certified domestic suppliers. METI industrial standards coordinate with JIS testing protocols for protective garment certification. Teijin leverages para-aramid technology leadership from its Osaka and Matsuyama production bases.
Fire Retardant Fabrics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fiber and chemical supply. The vendor base spans integrated polymer-to-fabric producers, independent converters, and specialty finishers with validated treatment systems. Three archetypes dominate: backward-integrated chemical conglomerates with captive fiber supply, independent fabric converters dependent on merchant aramid purchases, and application-specific specialists in coated barriers for automotive thermal protection. Competitive moves concentrate on qualified supplier list penetration for aerospace OEMs and phosphorus-based chemistry validation under REACH.
Among integrated chemical conglomerates, DuPont de Nemours, Inc. and Teijin Ltd. occupy positions defined by captive meta-aramid and para-aramid polymer supply. Asahi Kasei Advance Corporation exemplifies the specialist archetype through flame-resistant non-woven solutions. These three anchors represent divergent strategic postures: DuPont's North American vertical integration, Teijin's Japanese defense and aviation concentration, and Asahi Kasei's targeted automotive battery enclosure positioning.
| Leading Market Players |
|---|
| Asahi Kasei Advance Corporation |
| Koninklijke Ten Cate bv |
| DuPont de Nemours, Inc. |
| W. L. Gore & Associates, Inc. |
| Lenzing AG |
| Huntsman Corporation |
| Kaneka Corporation |
| Teijin Ltd. |
| Milliken & Company |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese aramid fiber production is compressing input costs for fabric converters while simultaneously eroding pricing power for European and Japanese polymer producers. This utilization imbalance forces specification-grade suppliers to differentiate through REACH-compliant phosphorus chemistry validation rather than volume competition.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across the European procurement landscape, separating validated phosphorus-nitrogen systems from legacy halogenated alternatives facing authorization withdrawal. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with NFPA 2112 and FAA heat-flux compliance commanding 40-60% premia over untreated industrial grades. Cost compression in construction-grade polyester runs through commoditized back-coating treatments as Chinese capacity floods non-specification segments. Oilfield services operators demonstrate lowest price sensitivity due to liability-driven replacement mandates, while residential upholstery buyers gravitate toward economy tiers.
Supply Chain Analysis
Extended payment terms from European automotive OEMs are squeezing working capital for coated fabric specialists developing battery enclosure barriers. Para-aramid polymer supply concentrates in the United States, Japan, and Germany, with fabric conversion capacity clustering in China's Jiangsu province and Germany's Aachen-Chemnitz corridor. Raw material dependencies rest on m-phenylenediamine and isophthaloyl chloride for meta-aramid synthesis, plus phosphorus-based flame-retardant intermediates from Chinese chemical processors. Single-source vulnerability pervades para-aramid supply, with Teijin and DuPont controlling merchant availability. Distribution runs through qualified supplier lists maintained by Boeing, Airbus, and COMAC, bypassing traditional distributor networks for specification-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft production rates are climbing from cyclical lows, with Boeing and Airbus output expansion driving specification-grade fabric procurement for thermal protection systems.
For Market Incumbents: Insulate qualified supplier list positions through captive phosphorus chemistry R&D and backward integration into flame-retardant polymer synthesis. DuPont and Teijin should expand REACH-validation laboratories in Germany to accelerate certification timelines for derivative products. Defend against Chinese aramid capacity by locking long-term offtake agreements with aerospace OEMs.
For New Entrants and Emerging Players: China's domestic aerospace buildout represents the most penetrable geography for certified foreign producers seeking COMAC qualification. Target coated fabric barriers for electric vehicle battery enclosures, where automotive OEMs lack qualified suppliers. Pursue direct contracting with Fortune 500 petrochemical operators bypassing regional safety equipment distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated polymer-to-fabric producers with captive aramid supply and established aerospace certification. Long-term viability hinges on REACH-compliant chemistry portfolios and NFPA 2112 validation infrastructure. Monitor electric vehicle thermal runaway protection specifications as inflection indicator for coated barrier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Validation | ECHA authorization timelines determine market access for European protective clothing procurement. |
| Backward Integration into Para-Aramid | Captive polymer supply insulates fabric converters from Teijin and DuPont allocation constraints. |
| Electric Vehicle Battery Barrier Qualification | Tesla and BYD thermal runaway specifications create first-mover advantage for coated aramid suppliers. |
| Digital Weave Simulation Deployment | AI-driven prototyping compresses Boeing-Airbus supplier qualification from eighteen to eight months. |
| Direct Contracting with Petrochemical Operators | ExxonMobil and Shell centralized procurement functions bypass regional safety equipment distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA REACH registration databases, FAA certification records, and aerospace OEM qualified supplier lists. Primary interviews engaged polymer scientists at RWTH Aachen, procurement directors at German automotive OEMs, technical safety staff at North American petrochemical operators, and regulatory affairs managers at flame-retardant chemical formulators. Secondary validation drew from SEC 10-K filings of integrated aramid producers, COMAC supplier qualification bulletins, and NFPA standards documentation. Bottom-up demand modeling triangulated against top-down capacity assessments across polymer and fabric conversion tiers.
Forecast inputs include commercial aircraft delivery schedules, electric vehicle production trajectories, and REACH chemical authorization timelines across the analysis window. Segmentation dimensions encompass product construction method, application performance tier, end-use industry certification requirements, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections calibrated to OEM procurement patterns. Industry-specific inputs incorporate battery enclosure specification adoption curves and defense procurement surge cycles.
Practitioners should monitor ECHA authorization withdrawals for halogenated flame retardants and COMAC supplier list expansions for early signals of competitive repositioning. Forecasts reflect assumptions regarding aerospace production rate sustainability and automotive thermal protection mandate timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
China Geotextiles Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Buildtech Textiles Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Technical Textile Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Webbing Market
Technical Textiles
Smart Fabrics for Transportation Market