

Wet-Molded Fibre Market Size, Share, and Industry Trends Forecast 2026-2036
Wet-Molded Fibre Market Insights
Subscription-based packaging-as-a-service is pivoting how wet-molded fibre reaches end users. Huhtamaki leverages its European thermoforming network to bundle tray supply with closed-loop collection. Brødrene Hartmann anchors Nordic egg and fruit packaging through captive pulp sourcing and regional mill density. Sonoco Products Company competes on North American industrial part protection with integrated design-to-mold capabilities.
Wet-molded fibre forms three-dimensional cellulose structures from slurried natural fibres pressed into heated molds, typically achieving wall thicknesses of 0.8–3.0 mm and densities of 0.6–1.1 g/cm³ for protective cushioning and rigid containment. The process consumes 70% less energy than expanded polystyrene molding while producing compostable end products. Natural fibre dominates current volume owing to cost parity with plastic alternatives and established pulp supply chains, though carbon fibre variants command premium positioning in aerospace part crating where electrostatic discharge control matters. Compression molding occupies the widest installed base, yet vacuum infusion is gaining share in automotive component applications requiring complex rib geometries and Class A surface finishes.
The EU Green Deal and REACH chemical restrictions are accelerating plastic displacement across European consumer electronics packaging, while China's GB standards on packaging waste push domestic brands toward cellulose alternatives. The US EPA solid waste hierarchy and state-level extended producer responsibility laws in California and Oregon reshape procurement criteria for electronics producers and furniture fabricators. Stakeholders must track how FDA food-contact notifications and compostability certifications from BPI and TÜV Austria evolve as gatekeepers for premium segment access.
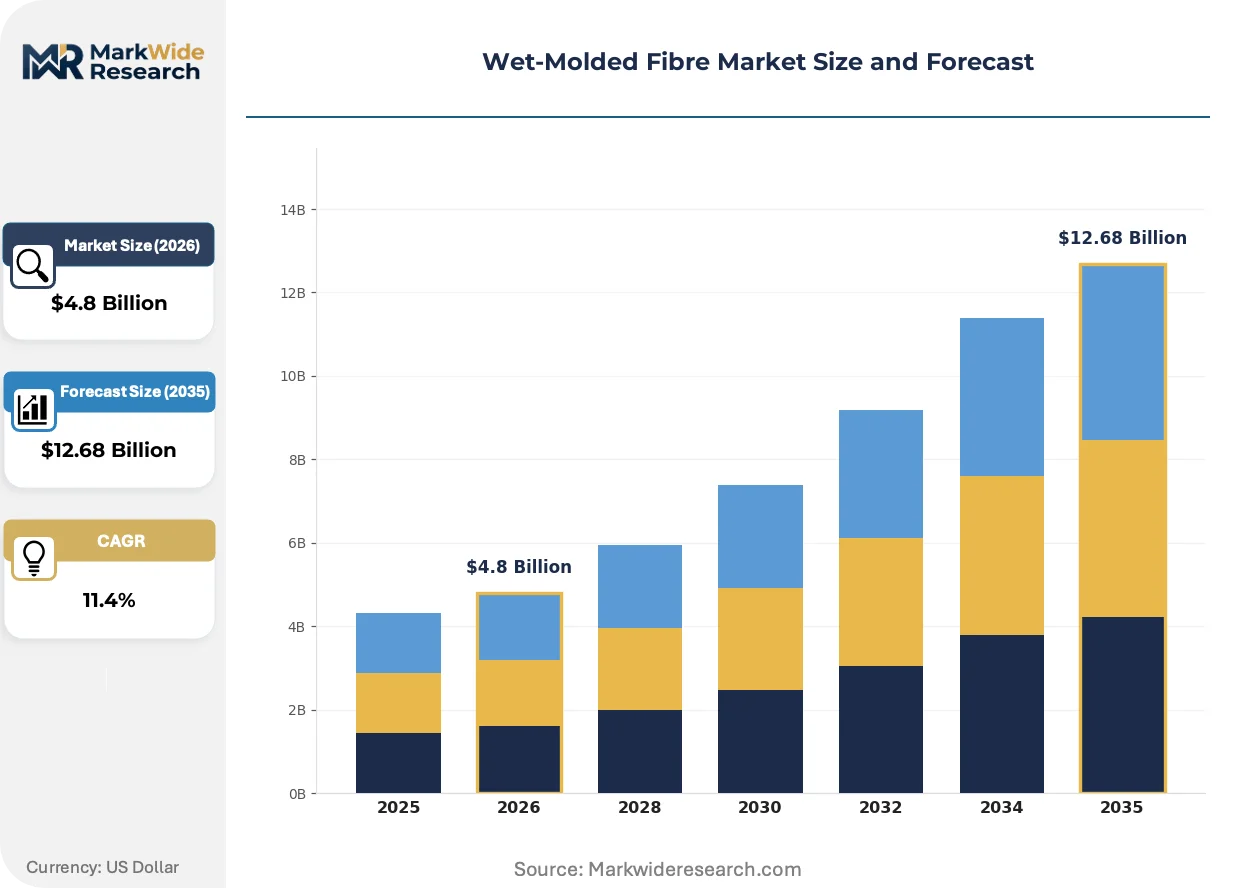
Market Dynamics
EU Green Deal mandates on single-use plastics are compressing adoption timelines for wet-molded fibre, forcing electronics and food packaging converters to requalify supply chains ahead of statutory deadlines.
Growth Catalysts
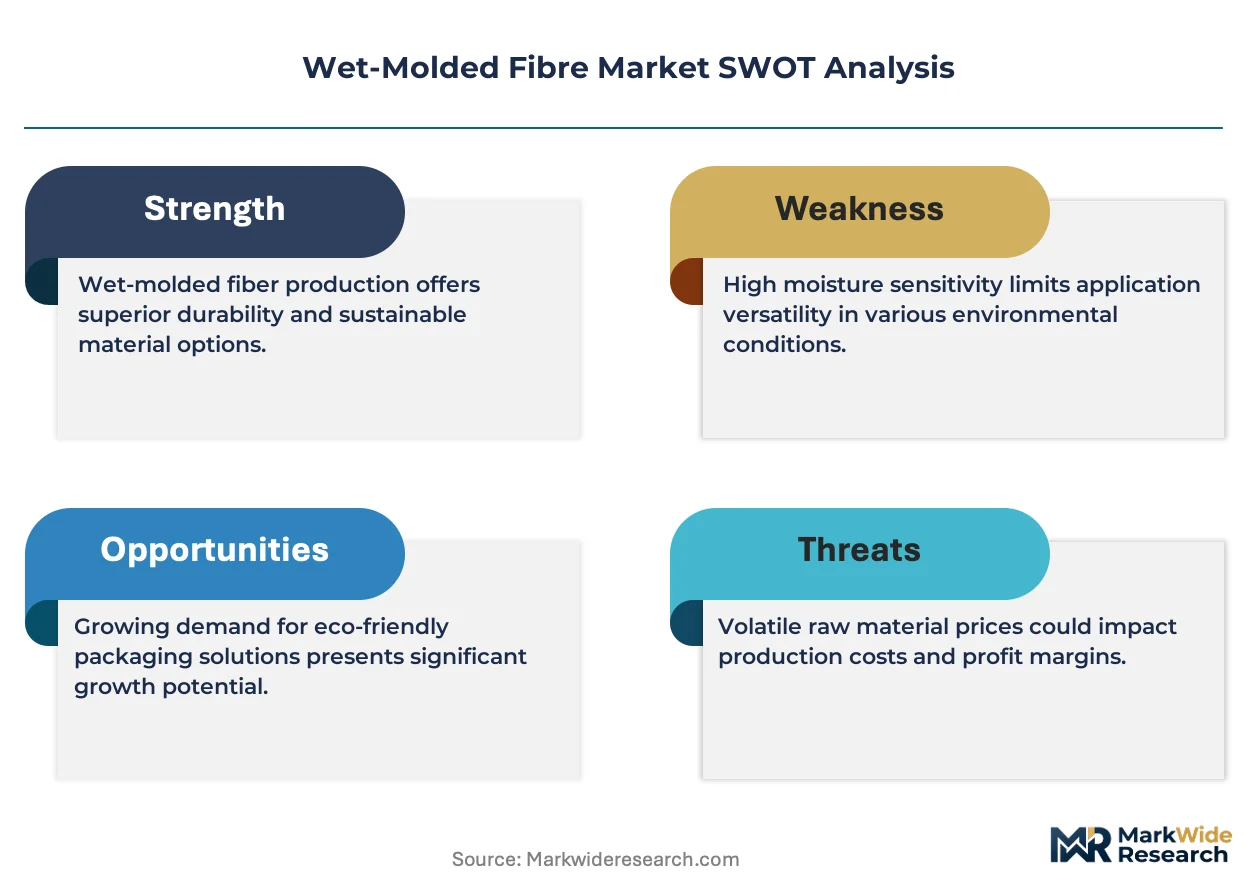
- REACH chemical restrictions:European electronics manufacturers face compulsory phase-out of polystyrene cushioning, redirecting component tray demand toward cellulose-based alternatives with established compostability pathways.
- Yangtze River Delta cluster concentration:Packaging converters serving Apple and Samsung assembly plants are scaling wet-molded fibre capacity to meet OEM sustainability procurement thresholds.
- Vacuum infusion molding:Automotive suppliers adopt this process variant for Class A surface finishes on interior trim components, opening premium positioning beyond traditional protective packaging.
Market Restraints
- Pulp input cost volatility:Recycled fibre pricing tracks OCC (old corrugated containers) commodity swings, compressing converter margins during supply tightness in Nordic and North American pulp markets.
- Mold fabrication lead times:Precision aluminum tooling for complex geometries requires 12-16 week procurement cycles, constraining rapid product development for seasonal electronics launches.
- Performance gap in moisture barrier:Unmodified cellulose exhibits inferior vapor transmission rates versus polyethylene terephthalate, limiting penetration in pharmaceutical blister alternatives.
Strategic Opportunities
- India BIS packaging standards:Pending harmonization with ISO 17088 compostability protocols creates first-mover positioning for certified exporters targeting domestic e-commerce fulfillment.
- Aerospace electrostatic discharge applications:Carbon fibre-reinforced variants command premium positioning for satellite component crating where conductive properties are mandatory.
- Closed-loop collection networks:Packaging-as-a-service models bundle tray supply with reverse logistics, capturing recurring revenue streams from institutional foodservice operators.
Industry Challenges
- BPI and TÜV Austria certification timelines:Compostability validation requires 90-120 day laboratory cycles, delaying product launches for seasonal procurement windows.
- Tooling capex intensity:Multi-cavity heated molds for high-volume electronics trays demand capital deployment exceeding mid-tier converter balance sheet capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet-Molded Fibre Market Trends and Innovations
Process digitization and material hybridization are reconfiguring competitive advantage in wet-molded fibre, compressing the gap between commodity pulp products and engineered performance grades.
Precision drying control systems is converging with inline quality inspection to enable real-time moisture content adjustment during forming cycles. Tier-one automotive suppliers in Germany are piloting these integrated lines for interior trim qualification. This convergence is compressing defect rates and reducing post-mold conditioning time, enabling just-in-sequence delivery to assembly plants.
China's GB standards on packaging waste are mandating cellulose content minimums for express delivery parcels, effective in major metropolitan zones. Domestic e-commerce platforms are pre-qualifying wet-molded fibre suppliers ahead of enforcement expansion. Electronics fulfillment centers in Shenzhen and Chengdu are retrofitting automated handling systems to accommodate variable fibre tray dimensions.
Brand sustainability disclosure requirements are elevating certified compostability from preference to procurement gate. Food retailers in France and the Netherlands now specify BPI or OK Compost INDUSTRIAL markings for private-label egg and produce packaging. This certification-driven preference shift is consolidating supplier selection around converters with established laboratory relationships and documented supply chain traceability.
Wet-Molded Fibre Market Segmentation
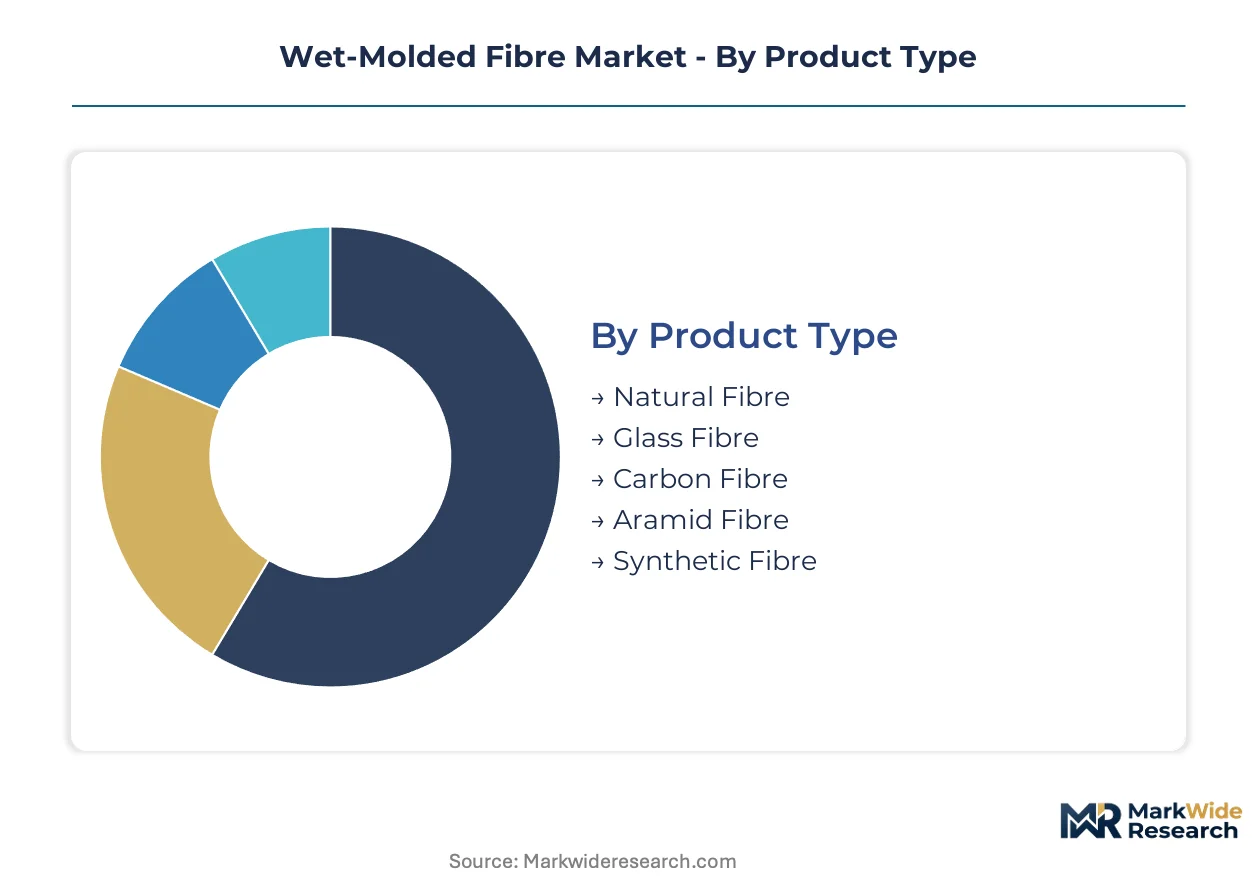
Wet-molded fibre exhibits sharp performance differentiation across material grades and process variants, with specification choices directly determining end-use access and margin capture. Understanding how these axes intersect reveals where converter investments concentrate and where qualification barriers remain highest.
Product Type:
Material selection governs structural performance, surface finish capability, and regulatory compliance pathways across target applications.
- Natural Fibre:Composed of cellulose from wood pulp, bagasse, or agricultural residues, this grade achieves densities of 0.6–1.1 g/cm³ with inherent compostability. Demand concentrates in Germany's electronics packaging sector where EU Green Deal mandates on single-use plastics have forced polystyrene displacement. OCC commodity pricing volatility constrains margin stability for converters.
- Carbon Fibre:Reinforced variants incorporate conductive carbon filaments enabling electrostatic discharge control with surface resistivity below 10^6 ohms/sq. Aerospace part crating for satellite components in Germany and France commands premium positioning where conductive properties are mandatory for flight hardware protection.
- Glass Fibre:E-glass and S-glass reinforcements improve tensile strength to 300-400 MPa for industrial load-bearing applications.
- Aramid Fibre:Kevlar and Twaron variants deliver impact absorption for ballistic and high-performance sporting equipment.
- Synthetic Fibre:Polypropylene and polyester blends offer moisture resistance for outdoor furniture and marine applications.
Mature deployment sits with Natural Fibre. Newer deployment is concentrated in Carbon Fibre.
Application:
End-use requirements dictate mold complexity, surface finish specifications, and volume scale economics for converter capacity planning.
- Automotive Components:Interior trim panels and structural inserts require Class A surface finishes achievable through vacuum infusion molding. German tier-one suppliers are piloting precision drying control systems for just-in-sequence delivery to assembly plants, with qualification cycles compressing defect rates below 2%.
- Consumer Electronics:Protective trays and cushioning for smartphones, laptops, and wearables demand tight dimensional tolerances of ±0.3 mm for automated assembly line compatibility. China's Yangtze River Delta packaging converters are scaling capacity to serve Apple and Samsung procurement thresholds.
- Aerospace Parts:Satellite component crating and engine transport fixtures prioritize electrostatic discharge protection and vibration damping.
- Sporting Goods:Helmet shells and protective gear leverage fibre orientation for directional impact resistance.
- Furniture Manufacturing:Chair shells and table bases utilize compression molding for cost-sensitive contract seating.
Volume leadership belongs to Consumer Electronics. Steepest expansion trajectory is occurring in Automotive Components.
End User Industry:
Customer procurement structures range from centralized OEM qualification to fragmented specification-by-specification bidding.
- Vehicle Manufacturers:Volkswagen, BMW, and Mercedes-Benz enforce IATF 16949 quality systems with PPAP submission requirements. German automotive packaging contracts bundle wet-molded fibre tray supply with closed-loop collection obligations, favoring converters with established thermoforming networks.
- Electronics Producers:Apple and Samsung sustainability scorecards require BPI or TÜV Austria compostability certifications with documented supply chain traceability. Shenzhen and Chengdu fulfillment centers are retrofitting automated handling systems for variable tray dimensions.
- Aircraft Manufacturers:Airbus and Boeing impose AS9100D aerospace standards with material lot traceability.
- Sports Equipment Makers:Decathlon and Nike prioritize lightweighting for performance differentiation.
- Furniture Fabricators:IKEA and Herman Miller specify FSC-certified pulp for sustainability disclosure.
Procurement sophistication peaks with Vehicle Manufacturers. Contract flexibility is greatest with Furniture Fabricators.
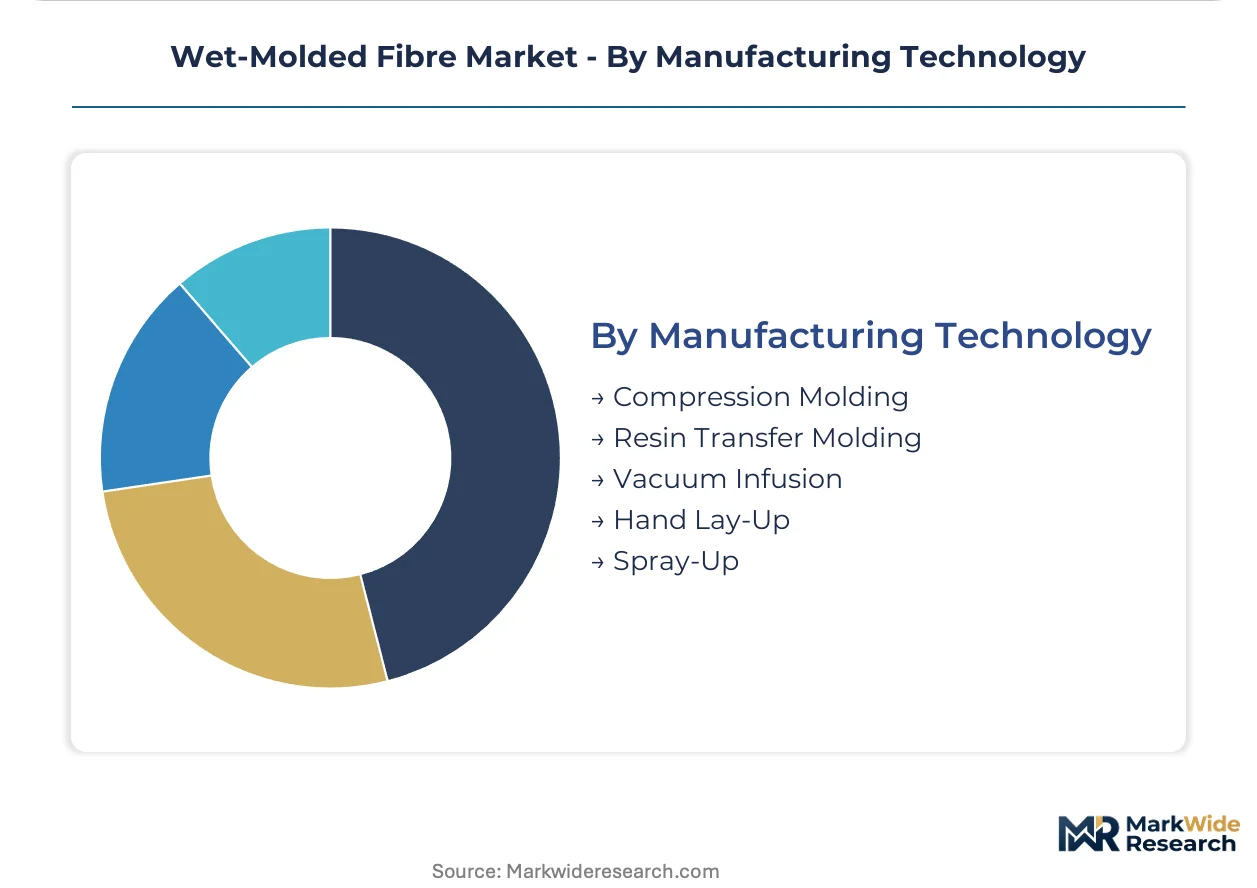
Manufacturing Technology:
Process selection determines capital intensity, cycle time, and geometric complexity achievable for target applications.
- Compression Molding:Heated matched metal molds press slurried fibre at 150-200°C with cycle times of 30-90 seconds. This occupies the widest installed base globally owing to equipment accessibility and operator familiarity, though precision aluminum tooling requires 12-16 week lead times.
- Vacuum Infusion:Negative pressure draws resin through dry fibre preforms enabling complex rib geometries and void-free laminates. German automotive interior trim qualification is driving adoption for Class A surface requirements.
- Resin Transfer Molding:Closed mold injection achieves high fibre volume fractions for structural aerospace components.
- Hand Lay-Up:Manual fibre placement suits prototype and low-volume custom furniture.
- Spray-Up:Chopped fibre deposition offers lowest capital entry for industrial packaging.
Installed capacity concentrates in Compression Molding. Capability investment is accelerating in Vacuum Infusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors electronics packaging demand as the Yangtze River Delta cluster scales wet-molded fibre capacity for Apple and Samsung assembly plants. Germany's automotive corridor drives precision molding qualification, while India's BIS standards reshape South Asian procurement. Nordic pulp supply chains and North American industrial protection needs complete the geographic spread.
Germany
Volkswagen, BMW, and Mercedes-Benz enforce IATF 16949 quality systems with PPAP submission requirements for interior trim components. The EU Green Deal and REACH chemical restrictions mandate polystyrene phase-out by statutory deadlines. Bavarian tier-one suppliers pilot vacuum infusion lines for Class A surface finishes on automotive interior panels.
China
Apple and Samsung sustainability scorecards require documented supply chain traceability for electronics trays. GB standards on packaging waste mandate cellulose content minimums for express delivery parcels in major metropolitan zones. Shenzhen and Chengdu fulfillment centers retrofit automated handling systems for variable fibre tray dimensions.
United States
California and Oregon state-level extended producer responsibility laws reshape procurement criteria for electronics producers. The EPA solid waste hierarchy prioritizes compostable alternatives in federal purchasing guidelines. Industrial part protection demand concentrates around Midwest automotive and Southeast furniture manufacturing clusters.
India
Domestic e-commerce platforms pre-qualify wet-molded fibre suppliers ahead of BIS packaging standards enforcement expansion. Pending harmonization with ISO 17088 compostability protocols creates first-mover positioning for certified exporters. Maharashtra and Gujarat packaging converters scale capacity to serve Flipkart and Amazon fulfillment networks.
France
Food retailers specify BPI or OK Compost INDUSTRIAL markings for private-label egg and produce packaging. ANSM and CNIL oversight extends to packaging material traceability in pharmaceutical supply chains. Île-de-France supermarket chains consolidate supplier selection around converters with established laboratory relationships.
Wet-Molded Fibre Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent capability requirements. The installed base concentrates around integrated pulp-to-mold operators with captive fibre supply, while specialist converters compete on design-to-mold speed for seasonal electronics launches. Three archetypes dominate: Nordic vertically integrated pulp owners, North American industrial protection specialists, and Asian electronics packaging scale players. Competitive moves center on closed-loop collection network expansion and precision aluminum tooling partnerships.
Among Nordic integrated operators, Brødrene Hartmann anchors regional egg and fruit packaging through captive pulp sourcing. Huhtamaki leverages its European thermoforming network to bundle tray supply with reverse logistics capabilities. Sonoco Products Company occupies the North American industrial protection tier with integrated design-to-mold positioning. These three exemplify how geographic pulp access and end-use specialization stratify competitive position.
| Leading Market Players |
|---|
| Huhtamaki |
| Brødrene Hartmann |
| Sonoco Products Company |
| UFP Technologies |
| Pactiv Evergreen |
| Omni-Pac Group |
| ProAmpac |
| Stora Enso |
| PulPac |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BPI/TÜV Austria compostable tiers and uncertified commodity grades splits both pricing power and supply chain sourcing strategies, with EU Green Deal enforcement concentrating procurement around converters with established laboratory partnerships while OCC volatility punishes undifferentiated pulp players.
Pricing Analysis
Margin tightening in natural fibre grades reflects OCC commodity swings and Nordic pulp supply tightness. Three-tier pricing structure across premium certified, standard industrial, and economy bulk levels differentiates converters by certification investment and mold complexity. Electronics producers in Germany exhibit lowest price sensitivity due to sustainability procurement mandates, while furniture fabricators in North America drive hardest unit-cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Nordic recycled fibre supply for European converters. Pulp input draws from Sweden, Finland, and Germany, with aluminum tooling and precision drying equipment anchored in German and Italian manufacturing clusters. Tariff exposure on Chinese mold imports threatens North American converter expansion timelines. Distribution runs through converter-direct OEM contracts and packaging-as-a-service subscription networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet-molded fibre sits at a process-technology transition where vacuum infusion displaces compression molding for Class A automotive surfaces, forcing capital reallocation across the installed base.
For Market Incumbents: Cement captive pulp supply through backward integration into Nordic OCC collection networks or long-term offtake agreements with Stora Enso and Brødrene Hartmann. Accelerate precision aluminum tooling partnerships to compress 12-16 week mold lead times before seasonal electronics procurement windows. Vacuum infusion capability represents the priority defensive investment against tier-one automotive supplier qualification requirements.
For New Entrants and Emerging Players: Capture India BIS packaging standards harmonization window by pre-certifying to ISO 17088 protocols ahead of domestic e-commerce enforcement expansion. Target Maharashtra and Gujarat packaging corridors serving Flipkart and Amazon fulfillment networks. Position through packaging-as-a-service subscription models bundling tray supply with reverse logistics, bypassing capital-intensive mold ownership.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap converters possessing vacuum infusion qualification and established BPI laboratory relationships given automotive interior trim adoption curves. Long-term viability hinges on process digitization and closed-loop collection network density. Watch German tier-one supplier PPAP submission volumes as inflection signal for Class A surface finish demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Nordic pulp supply security buffers margin compression from commodity volatility. |
| Vacuum Infusion Capability Investment | Class A surface qualification opens German automotive interior trim contracts. |
| Closed-Loop Collection Network Expansion | Packaging-as-a-service models capture recurring revenue from institutional foodservice. |
| BPI/TÜV Austria Certification Fast-Track | Compostability validation accelerates access to EU electronics and French retail procurement. |
| Precision Aluminum Tooling Partnership | Compressed mold lead times enable seasonal electronics launch participation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with packaging converter operations managers, OEM sustainability procurement leads, thermoforming equipment specialists, and pulp supply traders cross-validated capacity and pricing intelligence. Secondary sources included EU ECHA REACH restriction updates, China GB standard enforcement notices, US EPA solid waste hierarchy guidance, and BPI certification registry data. Bottom-up facility capacity modeling reconciled against top-down end-use demand estimates across the analysis window.
Data-stream reconciliation applied across material grade, manufacturing technology, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from segmented volume trajectory modeling incorporating OEM sustainability scorecard adoption curves and statutory plastic restriction phase-in schedules. Forecast inputs included Apple and Samsung procurement threshold announcements, German automotive IATF 16949 qualification pipelines, and India BIS standard harmonization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OCC commodity volatility, aluminum tooling capacity constraints, and compostability certification backlog durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.