
 Nonwoven Polyester Fabric Market | 2026-2036
Nonwoven Polyester Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Polyester Fabric Market Analytics
Asian spunbond capacity is expanding across multiple production corridors. DuPont leverages its polymer science heritage to sustain premium positioning in high-performance filtration media. Berry Global Inc. anchors North American supply through extensive converting infrastructure and healthcare channel control. Freudenberg differentiates via integrated nonwoven-to-component systems for automotive interiors.
Nonwoven polyester fabric consists of continuous or staple polyester fibers bonded through thermal, chemical, or mechanical processes without weaving, typically achieving basis weights between 10 and 400 gsm for applications requiring dimensional stability and moisture resistance. Spunbond production dominates volume output due to its speed and cost efficiency in hygiene and geotextile applications. Meltblown grades command specialized margin pools in medical protective apparel and high-efficiency filter media where fiber diameter control determines performance. Needle-punched constructions occupy durable goods segments including automotive upholstery and civil engineering applications where mechanical integrity under load governs specification.
EPA air quality standards and OSHA workplace exposure limits in the United States shape filtration product specifications and replacement cycle frequency. REACH substance restrictions and EU MDR biocompatibility requirements in Europe constrain raw material selection and downstream medical applications. Stakeholders must monitor evolving chemical hazard classifications under ECHA review processes and assess dual sourcing strategies for purified terephthalic acid feedstock before regulatory thresholds tighten.
Market Dynamics
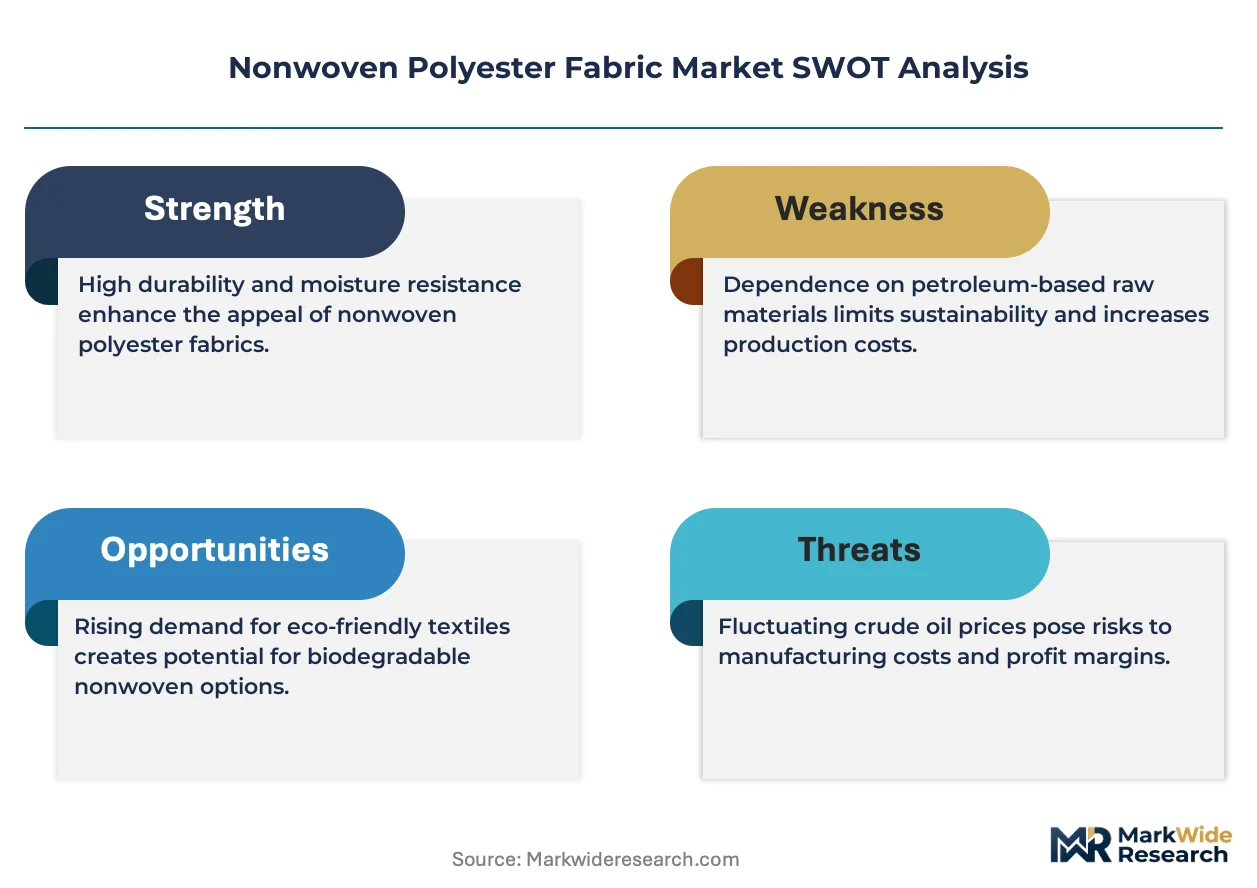
Spunbond capacity expansion across Asian manufacturing corridors is compressing regional cost structures while REACH substance restrictions in Europe force reformulation of legacy polyester grades. This structural tension between volume economics and regulatory compliance is redrawing competitive boundaries across the value chain.
Growth Catalysts
- Hygiene sector volume pull:Baby diaper and adult incontinence manufacturers in Southeast Asia are expanding spunbond offtake for acquisition distribution layers and backsheet substrates.
- EPA filtration mandates:Stricter PM2.5 and industrial emissions standards in the United States are shortening replacement cycles for HVAC and industrial baghouse media.
- Bi-component fiber advances:Sheath-core polyester constructions enable thermal bonding at lower temperatures, reducing energy intensity for hygiene producers.
Market Restraints
- Purified terephthalic acid concentration:Feedstock supply concentrates among integrated petrochemical complexes in China and the Middle East, exposing converters to margin squeeze during upstream volatility.
- REACH substance restrictions:ECHA review of microplastic release and additive classifications is constraining legacy additive packages for hygiene and filtration grades.
- Mechanical recycling limitations:Polyester nonwoven thermal history degrades molecular weight, limiting closed-loop feedstock quality for high-tenacity applications.
Strategic Opportunities
- India industrial filtration:Cement, steel, and power sector expansion under PLI-linked infrastructure investment is creating localized demand for high-temperature filter media.
- Chemical recycling scale-up:Depolymerization technologies for polyester waste streams enable food-contact and medical-grade circular feedstocks.
- EU Green Deal procurement:Public tender specifications for recycled content and carbon footprint disclosure favor suppliers with verified mass-balance certification.
Industry Challenges
- Meltblown specialist scarcity:Fine-diameter fiber production requires polymer rheology expertise and die engineering capabilities concentrated among a limited equipment supplier base.
- EU MDR biocompatibility timelines:Medical device fabric suppliers face extended testing and notification periods for implantable and surgical drape applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Polyester Fabric Market |
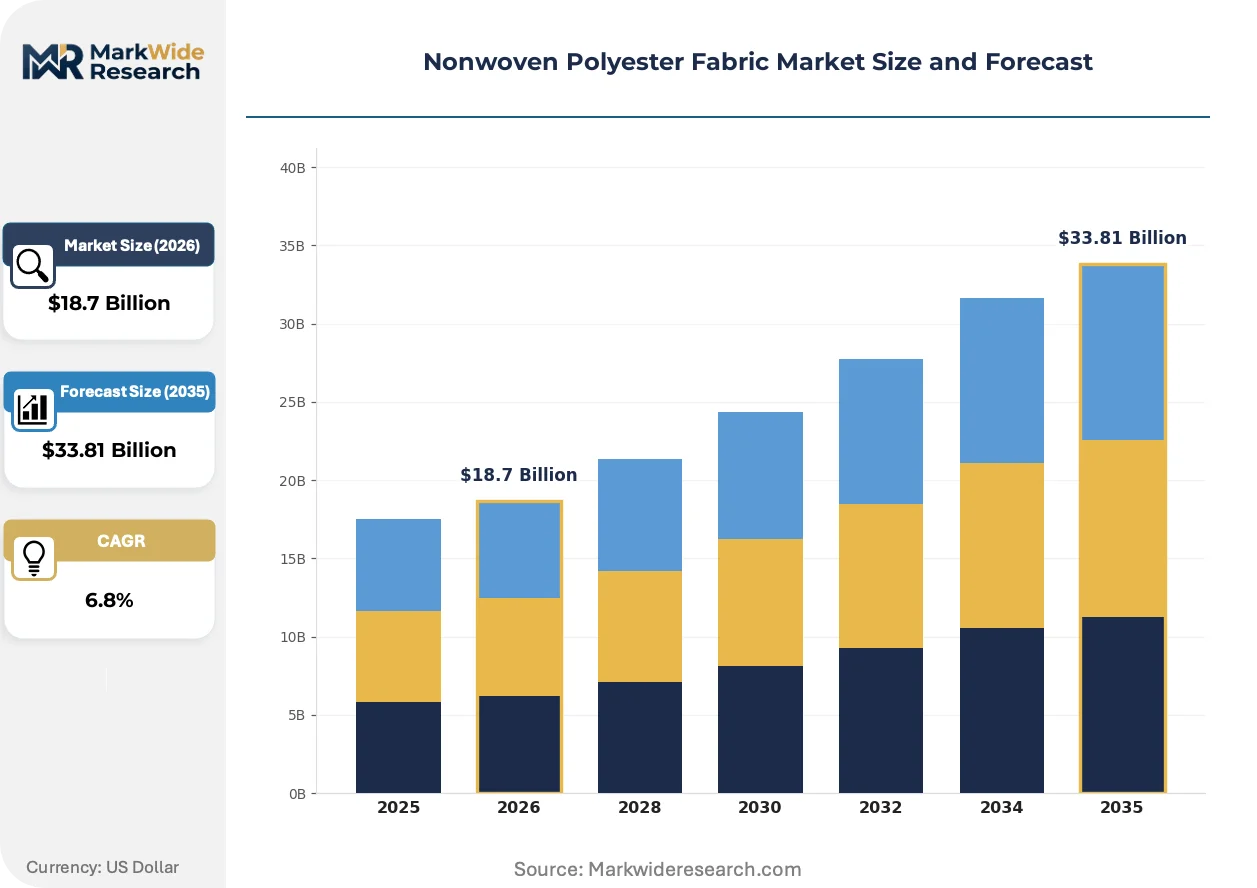
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spunbond, Meltblown, Composite, Needle-punched End User: Medical, Hygiene, Automotive, Geotextiles Application: Protective Apparel, Filter Media, Insulation, Upholstery Manufacturing Process: Thermal Bonding, Chemical Bonding, Mechanical Bonding, Adhesive Bonding |
| Companies Covered | Johns Manville, DuPont, Berry Global Inc., TWE Group, Ahlstrom, Kimberly-Clark Corporation, Glatfelter Corporation, Freudenberg, Fitesa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Polyester Fabric Market Evolving Landscape
Bio-based feedstocks and process intensification are converging to reduce carbon intensity across polyester nonwoven production. Regulatory disclosure requirements and buyer sustainability scorecards are accelerating transparency investments.
Recycled polyethylene terephthalate flake-to-fiber systems are integrating advanced sorting and extrusion filtration to produce spunbond grades meeting hygiene and filtration purity standards. European hygiene producers are adopting these lines fastest, driven by retailer recycled content commitments. This integration is compressing virgin resin premiums and reshaping supplier qualification protocols.
REACH microplastic release restrictions are forcing reformulation of shedding-prone applications including geotextiles and wipes. ECHA dossier evaluation is tightening additive migration limits for products with environmental release pathways. Filtration media and hygiene wipe segments are responding with binder migration testing and alternative fiber entanglement methods.
Hospital procurement consortiums are consolidating supplier panels and demanding life-cycle carbon data for surgical drape and gown fabrics. Group purchasing organizations are displacing fragmented hospital-level contracting with centralized sustainability-weighted awards. This concentration is most visible in Germany and the Netherlands where hospital networks operate at scale.
Nonwoven Polyester Fabric Market Segmentation
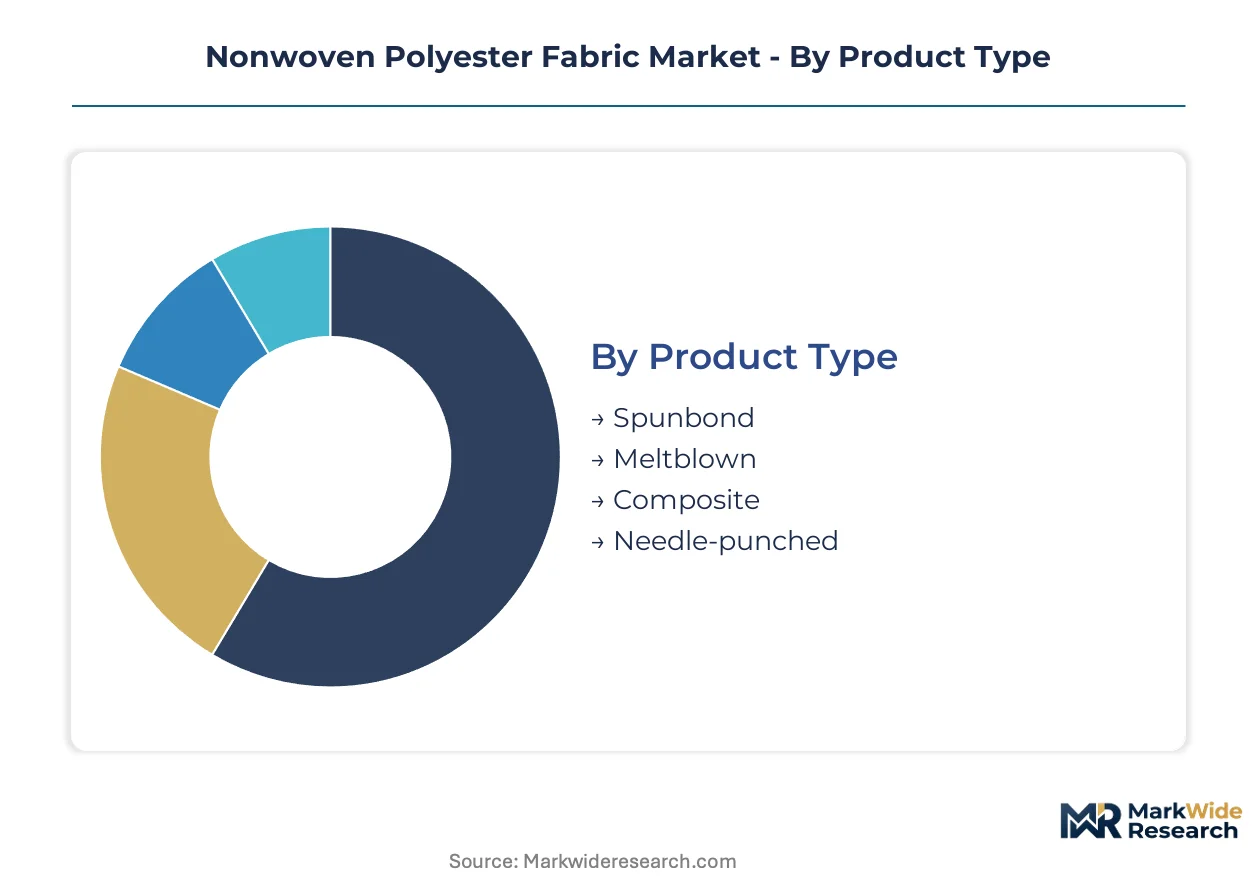
Segmentation in nonwoven polyester fabric reveals how technical specifications and bonding methods determine end-use suitability and margin structure. Buyers select grades based on fiber diameter control, basis weight tolerance, and regulatory compliance requirements for their specific applications.
Product Type:
Cost tier differentiation separates commodity hygiene substrates from specialized medical and filtration media.
- Spunbond:Continuous filaments extruded and thermally bonded create high-strength webs with basis weights from 10 to 150 gsm. Diaper and feminine hygiene manufacturers in Southeast Asia absorb capacity expansions for acquisition distribution layers and backsheet substrates.
- Meltblown:Microfiber webs with diameters below 10 microns achieve HEPA-grade filtration efficiency and liquid barrier properties. Medical protective apparel and HVAC filtration specifications in Germany and the United States command specialized margin pools where polymer rheology expertise limits supplier entry.
- Composite:Laminated spunbond-meltblown-spunbond constructions combine strength with barrier performance for surgical drapes and industrial wipes.
- Needle-punched:Mechanical entanglement of staple fibers produces dimensional stability under load for geotextiles and automotive carpeting.
Spunbond leads volumes today; meltblown is gaining share fastest.
End User:
Application maturity determines whether buyers prioritize volume scale or certification depth.
- Medical:Surgical drapes, gowns, and implantable scaffolds demand biocompatibility testing under EU MDR and FDA 510(k) pathways. Extended notification timelines favor incumbent suppliers with established quality management systems.
- Hygiene:Baby diapers, adult incontinence products, and feminine care items consume the largest tonnage volumes. Southeast Asian converters drive spunbond offtake through expanding regional production corridors.
- Automotive:Interior trim, headliners, and trunk liners require thermal stability and acoustic dampening properties. German OEMs specify recycled content thresholds under EU Green Deal procurement guidelines.
- Geotextiles:Civil engineering applications for erosion control and road stabilization prioritize UV resistance and tensile strength over surface aesthetics.
Hygiene dominates current tonnage; medical applications show the steepest expansion trajectory.
Application:
Performance certification requirements separate specification-grade from commodity purchasing.
- Protective Apparel:Isolation gowns, coveralls, and cleanroom garments balance liquid penetration resistance with breathability. OSHA workplace exposure limits and CDC guidance shape replacement cycle frequency in United States healthcare systems.
- Filter Media:HVAC, industrial baghouse, and liquid filtration applications require precise fiber diameter distribution and electrostatic charging retention. EPA PM2.5 mandates shorten replacement intervals for commercial building ventilation systems.
- Insulation:Building and industrial thermal barriers leverage polyester's moisture resistance and dimensional stability under compression.
- Upholstery:Furniture and automotive seating applications prioritize abrasion resistance and flame retardancy compliance with regional safety codes.
Filter media commands premium pricing today; protective apparel is climbing the fastest.
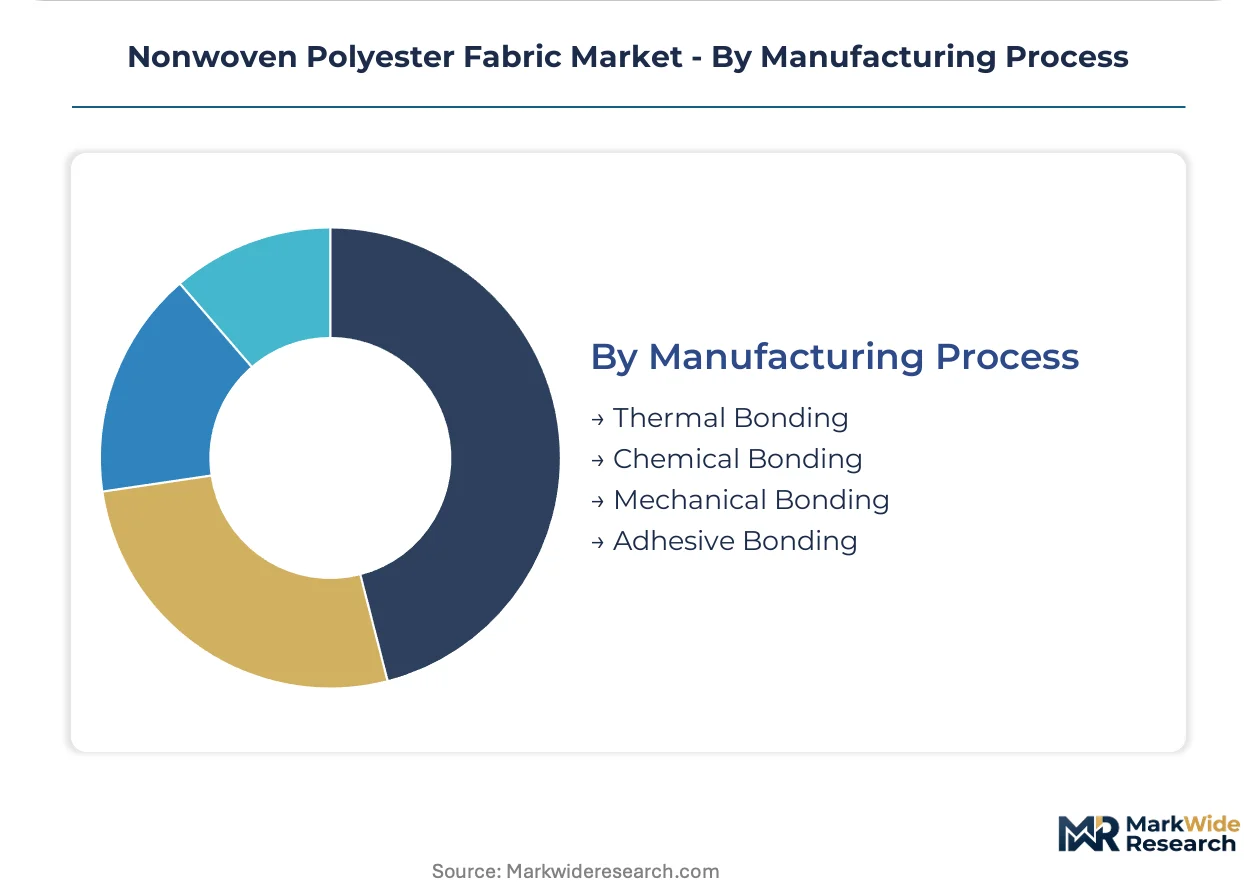
Manufacturing Process:
Energy intensity and capital requirements vary substantially across bonding technologies.
- Thermal Bonding:Calendering or through-air heating melts fiber surfaces to create point bonds without chemical additives. Bi-component sheath-core constructions enable lower processing temperatures, reducing energy costs for high-volume hygiene producers.
- Chemical Bonding:Acrylic or vinyl acetate emulsions bind fibers through adhesive coating and curing. REACH additive migration limits are constraining legacy binder packages for products with environmental release pathways.
- Mechanical Bonding:Needle punching and hydroentanglement entangle fibers through physical displacement without thermal or chemical modification.
- Adhesive Bonding:Hot-melt or spray-applied adhesives laminate multiple web layers for composite structures requiring z-directional strength.
Thermal bonding leads installed capacity today; mechanical bonding is expanding most quickly in sustainable product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capital toward jurisdictions with lower compliance costs while REACH-mandated reformulation expenses concentrate premium production in Western Europe. China and India capture volume migration from hygiene and industrial filtration demand, whereas Germany sustains high-margin medical and automotive specification grades despite elevated operating costs.
China
Spunbond capacity additions in Jiangsu and Zhejiang provinces serve Southeast Asian hygiene converters seeking cost-competitive backsheet substrates. MIIT industrial standards for filtration media are tightening quality benchmarks for domestic cement and steel sector procurement. The Yangtze River Delta cluster hosts integrated PTA-to-fiber complexes that compress raw material premiums for regional nonwoven producers.
Germany
Automotive interior specifications from BMW, Mercedes-Benz, and Volkswagen mandate recycled content thresholds that favor suppliers with mass-balance certification. EU MDR biocompatibility requirements extend notification timelines for surgical drape and implantable scaffold applications. The Baden-Württemberg corridor concentrates meltblown expertise for HEPA-grade filtration media serving industrial and medical end-uses.
India
Cement, steel, and power sector expansion under PLI-linked infrastructure investment is generating localized demand for high-temperature baghouse filter media. BIS standards for geotextile applications in road stabilization and erosion control are accelerating specification-grade adoption. The Gujarat industrial belt hosts needle-punched capacity serving domestic automotive upholstery and civil engineering contractors.
United States
EPA PM2.5 mandates and OSHA workplace exposure limits are shortening replacement cycles for HVAC and industrial filtration installations across commercial building portfolios. FDA 510(k) pathways for medical device fabrics favor incumbent suppliers with established quality management systems. The Southeast manufacturing corridor—spanning Georgia, South Carolina, and North Carolina—converts imported polyester staple into hygiene and wipes substrates for North American consumer goods brands.
Japan
METI carbon neutrality roadmaps are pressuring chemical fiber producers to demonstrate Scope 3 reductions for automotive and electronics supply chain qualification. JIS standards for industrial filtration media maintain stringent performance benchmarks that limit low-cost import penetration. The Chubu region around Nagoya retains specialized meltblown capacity for precision filter applications in semiconductor cleanroom environments.
Nonwoven Polyester Fabric Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling and bio-based feedstock differentiation to bypass virgin resin cost volatility. The vendor base stratifies across three archetypes: integrated petrochemical-to-fiber conglomerates with captive PTA supply; specialized nonwoven converters with healthcare channel control; and regional hygiene substrate suppliers competing on speed-to-market. Dominant competitive moves include backward integration into purified terephthalic acid production and strategic partnerships with hospital procurement consortiums for long-term surgical drape contracts.
Among diversified materials conglomerates, DuPont and Freudenberg exemplify premium-tier positioning through polymer science heritage and integrated nonwoven-to-component systems respectively. Berry Global Inc. occupies a scale-driven position within North American healthcare supply chains. Johns Manville and Ahlstrom represent industrial filtration specialization, while Kimberly-Clark Corporation and Glatfelter Corporation anchor consumer-facing hygiene and specialty paper-adjacent segments. TWE Group and Fitesa sit within the mid-tier converter space serving regional brand owners with flexible capacity allocation.
| Leading Market Players |
|---|
| Johns Manville |
| DuPont |
| Berry Global Inc. |
| TWE Group |
| Ahlstrom |
| Kimberly-Clark Corporation |
| Glatfelter Corporation |
| Freudenberg |
| Fitesa |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement specifications gate qualified supply and premium-tier pricing access by mandating mass-balance certification and carbon footprint disclosure for hospital and automotive procurement panels. REACH substance restrictions simultaneously constrain legacy additive packages, forcing reformulation investments that separate certified suppliers from commodity converters.
Pricing Analysis
Distributor margins for hygiene substrates compress as Asian spunbond capacity floods Southeast Asian markets, while direct-to-OEM contracts for medical grades sustain premiums through EU MDR biocompatibility certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates HEPA-grade meltblown media from commodity spunbond backsheet substrates. Pricing pressure stems from purified terephthalic acid feedstock volatility concentrated in Chinese and Middle Eastern petrochemical complexes. Hygiene converters exhibit highest price sensitivity; medical device fabric buyers prioritize certification depth over unit cost.
Supply Chain Analysis
ISO 13485 and EU MDR quality management certifications gate entry to surgical drape and implantable scaffold supply chains, extending qualification timelines for unproven suppliers. Feedstock supply concentrates in China, India, and Germany for PTA-to-fiber integration, while meltblown equipment engineering capability remains tethered to German and Japanese precision manufacturing bases. Single-source vulnerability runs through specialized die engineering suppliers concentrated in Baden-Württemberg and Nagoya. Distribution runs through hospital procurement consortiums in Germany and the Netherlands, consolidated group purchasing organizations in the United States, and fragmented converter networks across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH-mandated reformulation expenses in Western Europe create cost differentials against Asian volume producers, redirecting capital toward jurisdictions with lower compliance burdens.
For Market Incumbents: Anticipate margin compression from Asian spunbond capacity expansion by securing long-term surgical drape contracts with German and Dutch hospital procurement consortiums. Deepen backward integration into purified terephthalic acid production to offset feedstock volatility from Chinese petrochemical complexes. Prioritize mass-balance certification investment to defend automotive interior specifications from BMW, Mercedes-Benz, and Volkswagen. For New Entrants and Emerging Players: Begin with chemical recycling scale-up targeting food-contact and medical-grade circular feedstocks, where depolymerization technologies bypass virgin resin cost volatility. Target India's industrial filtration segment under PLI-linked infrastructure investment, where cement and steel sector expansion generates localized demand for high-temperature baghouse media. Pursue co-development partnerships with Gujarat-based needle-punched converters for automotive upholstery qualification. For Investors and Strategic Acquirers: Roll-up economics work for specialized nonwoven converters with healthcare channel control because hospital procurement consolidation in Germany and the Netherlands creates captive demand pools for qualified suppliers. Mid-cap targets with established FDA 510(k) and EU MDR quality management systems offer defensive positioning across the analysis window. Monitor ECHA microplastic release restriction enforcement as the inflection indicator for additive reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Captive feedstock supply insulates margin from Chinese petrochemical volatility. |
| Mass-Balance Certification Investment | EU Green Deal procurement thresholds favor verified circular feedstock suppliers. |
| Meltblown Capacity Expansion | Fine-diameter fiber expertise commands specialized margin pools in HEPA filtration. |
| Chemical Recycling Scale-Up | Depolymerization enables food-contact and medical-grade circular polyester feedstocks. |
| Hospital Procurement Consortium Partnerships | Long-term surgical drape contracts with German GPOs secure volume commitments. |
Research Methodology
Multiple input streams — primary interviews with nonwoven plant managers, hygiene procurement leads at consumer goods OEMs, and hospital GPO contracts managers; secondary validation through customs/trade data, SEC 10-K filings, and ECHA regulatory dossiers; plus technical R&D director surveys — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured capacity utilization rates, qualification timeline benchmarks, and channel margin structures across Asian, European, and North American production corridors.
Historical volume trajectories were cross-referenced against panel input from filtration media specification engineers and automotive interior procurement teams to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry, manufacturing process energy intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA PM2.5 mandate compliance cycles and REACH substance restriction phase-in schedules.
Several conditions sit outside the modeled scope, including unforeseen ECHA additive reclassification, abrupt PTA feedstock supply disruptions from Middle Eastern petrochemical complexes, and accelerated mechanical recycling technology breakthroughs. Forecasts reflect assumptions documented in the segmentation and regional outlook sections. A model refresh is warranted upon material change in EU MDR biocompatibility notification timelines or MIIT filtration media standard enforcement intensity in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Flanging Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Nonwoven Geotextiles Market