
 Webbing Market | 2026-2036
Webbing Market Size, Share, and Industry Trends Forecast 2026-2036
Webbing Market Intelligence
Buyer concentration among automotive tier-one suppliers is expanding as vehicle OEMs consolidate safety-component sourcing across fewer approved vendors. Bally Ribbon Mills leverages advanced jacquard weaving capabilities to serve aerospace and defense contracts with engineered textile solutions. National Webbing Products Co anchors its position through vertical control over dyeing and finishing operations in North American manufacturing corridors. E Oppermann GmbH competes by sustaining long-term supply relationships with European automotive seating and restraint system builders.
Webbing denotes a strong woven fabric strip, typically manufactured on narrow-fabric looms with warp yarns held under tension and weft threads interlaced at densities ranging from 20 to 200 picks per inch, engineered to distribute load across broad surface areas in strapping, harnessing, and suspension applications. Polyester webbing dominates industrial safety and cargo-securing applications due to its superior UV resistance and minimal moisture absorption compared to cotton or polypropylene alternatives. Sling webbing commands premium positioning in lifting and rigging markets where break-strength certification dictates procurement decisions, while flat webbing occupies volume-driven segments such as outdoor gear and consumer luggage straps.
The US National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 209 for seatbelt assembly performance, directly shaping tensile-strength and elongation requirements that webbing producers must certify through third-party testing laboratories. The EU REACH regulation restricts phthalate and heavy-metal content in coated webbing formulations, compelling material suppliers to reformulate polymer coatings and validate substitution pathways through ECHA-registered chemical dossiers. Stakeholders must monitor evolving flammability standards from FAA and ISO for technical textile applications in mass transit and aviation seating to anticipate qualification barriers and redirect R&D investment toward inherently flame-resistant yarn constructions.
Market Dynamics
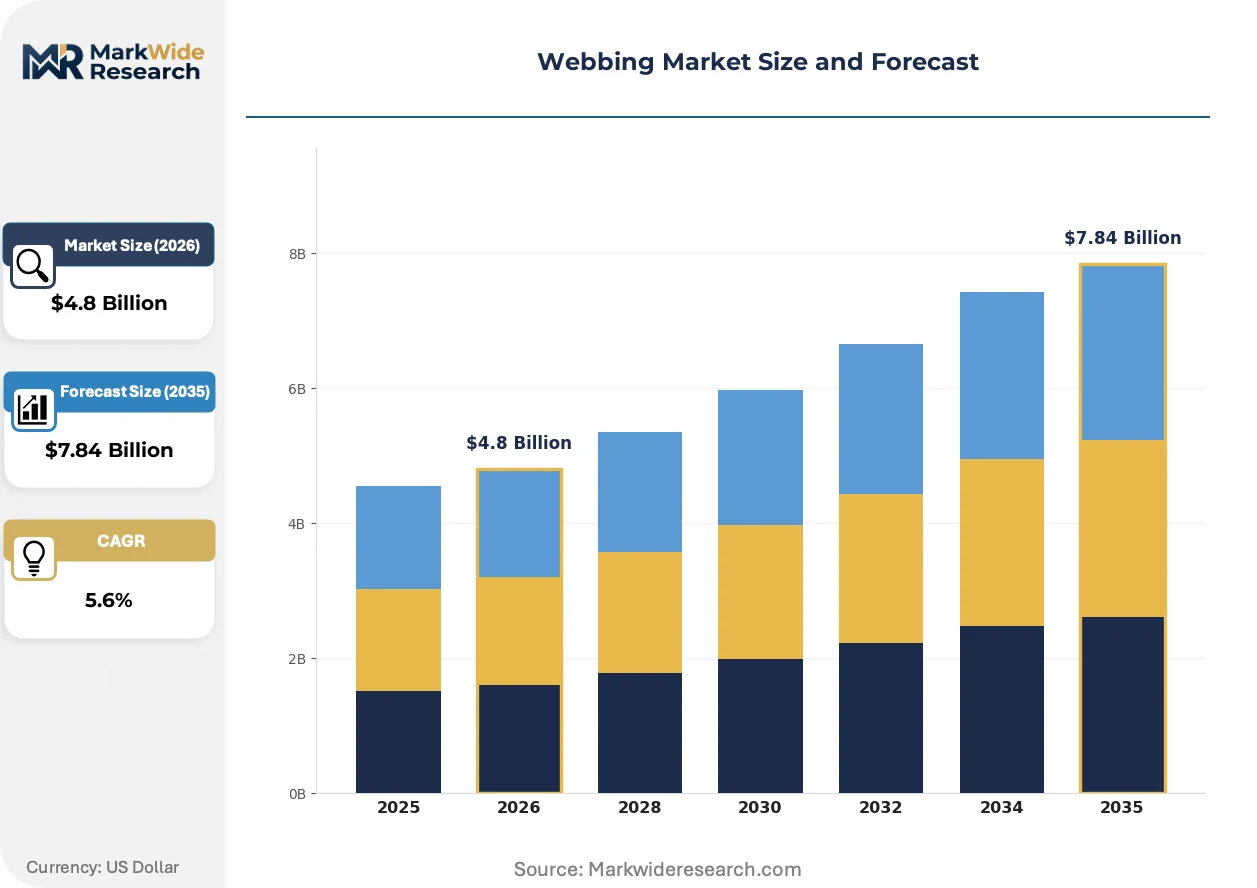
Automotive OEM consolidation of safety-component sourcing is compressing the supplier base for seatbelt webbing, forcing narrow-fabric manufacturers to qualify through fewer tier-one gateways while simultaneously absorbing REACH-mandated coating reformulation costs.
Growth Catalysts
- Federal Motor Vehicle Safety Standard 209:NHTSA enforcement of tensile-strength and elongation specifications sustains certified demand for high-tenacity polyester webbing in US vehicle assembly plants.
- Water-based polymer finishes:ECHA-registered substitution pathways under REACH Article 33 are redirecting coating investments toward compliant aqueous formulations across EU converter networks.
- Aerospace harnessing:FAA flammability qualification requirements for technical textiles are expanding procurement of inherently flame-resistant yarn constructions in aviation seating programs.
Market Restraints
- Petrochemical feedstock volatility:Polyester chip and industrial yarn prices fluctuate with crude oil derivatives, compressing margin predictability for high-volume flat webbing producers.
- German supplier concentration:Specialized narrow-fabric production clusters around E Oppermann GmbH and regional automotive tier suppliers create geographic dependency risk for European OEM qualification.
- Polypropylene substitution:Lower-cost extruded strapping alternatives capture volume-driven cargo-securing segments where UV resistance and moisture absorption specifications permit material downgrade.
Strategic Opportunities
- India automotive expansion:PLI scheme incentives for advanced automotive components are attracting seatbelt webbing investment toward domestic OEM supply chains in Pune and Chennai corridors.
- ISO 12401 marine certification:Sling webbing break-strength protocols for lifting and rigging are extending into offshore wind turbine maintenance harness applications.
- Digital jacquard weaving:Pattern-on-demand capability is converging with short-run customization platforms to serve outdoor gear brands through direct-to-manufacturer channels.
Industry Challenges
- Narrow-fabric loom operator scarcity:Warp tension control and pick-density calibration expertise is aging out of the workforce faster than vocational programs replenish qualified technicians.
- Third-party testing backlog:FMVSS 209 and FAA flammability certification queues at accredited laboratories are extending product qualification timelines for new webbing constructions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Webbing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyester, Nylon, Cotton, polypropylene Application: Safety Harnesses, Outdoor Gear, Medical Devices, Automotive End User: Manufacturers, Retailers, Distributors, Eco-Friendly Brands Form: Flat Webbing, Tubular Webbing, Sling Webbing, Rope |
| Companies Covered | BioThane Coated Webbing Corp, Narrowtex Pty Ltd, American Cord & Webbing Co Inc, Webbing Products Pty Ltd, E Oppermann GmbH, Bally Ribbon Mills, National Webbing Products Co, Leedon Webbing Co Inc, Murdock Webbing Company Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Webbing Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry mandates are simultaneously elevating performance specifications and reformulating coating systems across industrial, automotive, and aerospace webbing applications.
Recycled-content polyester filament yarn is converging with automotive OEM circularity targets to displace virgin petrochemical feedstocks in seatbelt webbing without sacrificing tenacity or elongation performance. European vehicle manufacturers are mandating post-consumer recycled content thresholds in supplier contracts. This convergence is compressing cost premiums between sustainable and conventional yarn grades.
EU REACH Annex XVII restrictions on phthalate plasticizers in coated textiles are compelling polymer suppliers to validate bio-based alternative plasticizers through ECHA substance dossier updates. Industrial safety harness producers must reformulate existing coating lines or qualify entirely new aqueous polymer systems. Sling webbing for lifting applications faces the most acute compliance timeline pressure due to existing inventory certification cycles.
Consolidated procurement through tier-one safety system integrators is displacing direct mill relationships that historically characterized automotive webbing supply chains. OEMs now delegate material qualification to fewer approved subsystem vendors who in turn consolidate yarn and narrow-fabric sourcing. This concentration is most visible in German and US Midwest automotive corridors where seating and restraint system assembly concentrates.
Webbing Market Segmentation
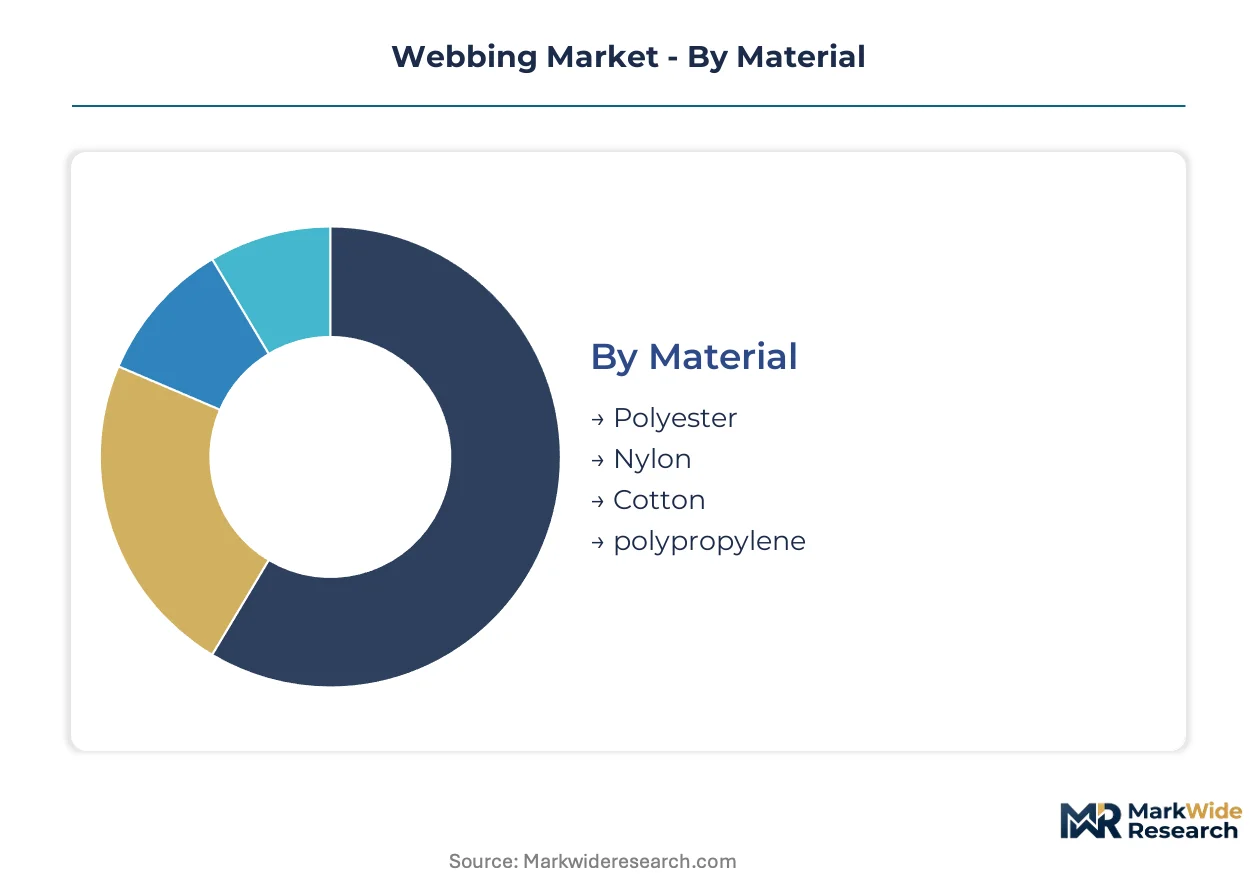
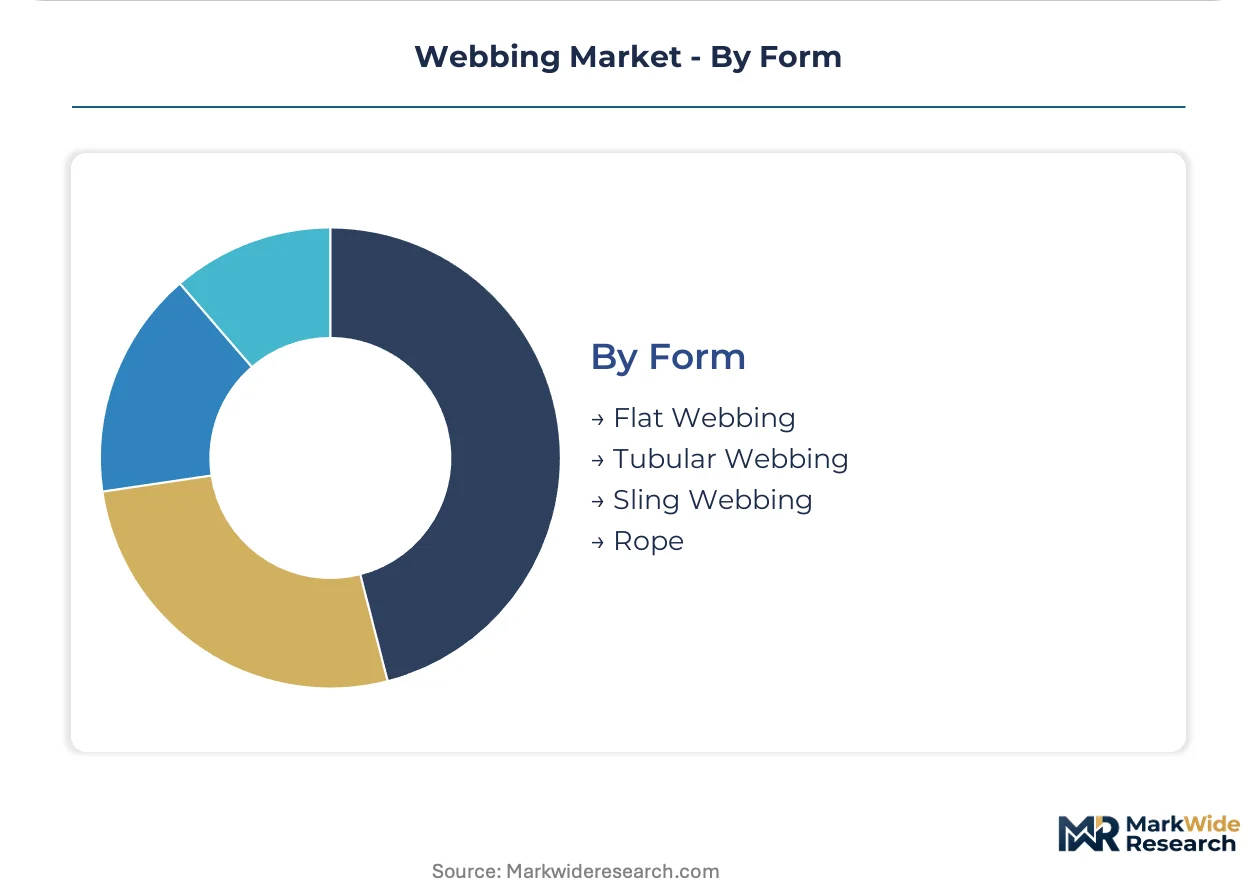
Webbing producers configure looms and finishing lines around material tenacity and end-use certification requirements. Segment selection dictates capital allocation toward high-tenacity filament systems or commodity flat-weave capacity.
Material:
Polyester and nylon filament systems demand the heaviest upfront investment in high-speed narrow-fabric looms and precision tension controls.
- Polyester:High-tenacity filament yarn delivers superior UV resistance and minimal moisture absorption for industrial safety and cargo-securing applications. Demand concentrates in US automotive assembly corridors where NHTSA FMVSS 209 certification requirements filter procurement toward certified narrow-fabric producers.
- Nylon:Superior elasticity and abrasion resistance suit dynamic load applications where energy absorption matters. European automotive seating programs in Germany anchor specialized procurement relationships with regional tier suppliers.
- Cotton:Natural fiber webbing serves heritage outdoor gear and consumer accessory segments where tactile properties outweigh synthetic performance.
- Polypropylene:Lower-density extrusion-grade material captures cost-sensitive cargo-securing segments where UV specifications permit material downgrade.
Most installed capacity flows through polyester. Expansion is steepest in nylon.
Application:
Certification intensity varies sharply across end-use segments, with automotive and aerospace applications demanding multi-year qualification timelines.
- Safety Harnesses:Fall-arrest and industrial rigging systems require break-strength certification through accredited testing laboratories. OSHA workplace safety mandates in the US sustain replacement-cycle demand across construction and utility sectors.
- Outdoor Gear:Backpack suspension, tent straps, and climbing accessories prioritize weight-to-strength ratios. Direct-to-consumer brands in North America drive short-run customization through digital jacquard platforms.
- Medical Devices:Patient lift slings and rehabilitation harnesses demand biocompatibility validation and antimicrobial finishing protocols.
- Automotive:Seatbelt and restraint system webbing must satisfy Federal Motor Vehicle Safety Standard 209 tensile specifications. OEM consolidation of tier-one sourcing compresses the qualified supplier base.
Automotive commands the longest qualification cycles. Outdoor gear is gaining share fastest through e-commerce channel expansion.
End User:
Procurement scale and technical specification authority diverge sharply between integrated manufacturers and arms-length distribution channels.
- Manufacturers:Tier-one automotive seating suppliers and aerospace harness integrators qualify narrow-fabric sources through multi-year engineering validation. Direct mill relationships dominate high-volume safety-component procurement.
- Retailers:Mass-market outdoor and luggage brands source through converter networks with regional dyeing and finishing capabilities. Price competition intensifies in undifferentiated flat webbing grades.
- Distributors:Industrial supply houses aggregate demand across fragmented construction and logistics customers. Inventory carrying costs favor standardized widths and break-strength ratings.
- Eco-Friendly Brands:Post-consumer recycled content mandates from European vehicle OEMs are redirecting yarn procurement toward certified sustainable filament sources.
Manufacturer direct procurement holds the greatest volume concentration. Eco-friendly brands are climbing the fastest as circularity clauses penetrate supplier contracts.
Form:
Weave architecture determines load distribution geometry and fabrication equipment requirements.
- Flat Webbing:Single-layer warp-faced construction dominates volume production for cargo securing and consumer accessories. German and US Midwest automotive corridors concentrate specialized capacity for seatbelt applications.
- Tubular Webbing:Double-layer hollow construction distributes load across both faces for climbing harnesses and rescue equipment. Break-strength redundancy commands premium positioning.
- Sling Webbing:Endless-loop configurations for lifting and rigging require ISO 12401 marine certification. Offshore wind turbine maintenance programs are extending demand into synthetic rope alternatives.
- Rope:Round-braided constructions compete with woven webbing in mooring and tethering applications where torsional flexibility matters.
Flat webbing retains the broadest installed base. Sling webbing shows the steepest expansion trajectory through industrial safety regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized narrow-fabric production for automotive restraint systems, while the United States anchors high-tenacity polyester capacity serving NHTSA-certified seatbelt programs. India and China are expanding domestic webbing manufacturing through automotive component incentives and export-oriented industrial clusters.
Germany
Automotive seating and restraint system builders sustain procurement of high-tenacity woven straps from regional tier suppliers. EU REACH Annex XVII restrictions on phthalate plasticizers compel coating reformulation across converter networks. E Oppermann GmbH anchors specialized production clusters in North Rhine-Westphalia, sustaining long-term supply relationships with European OEM qualification programs.
United States
NHTSA Federal Motor Vehicle Safety Standard 209 enforcement filters procurement toward certified narrow-fabric producers supplying vehicle assembly plants. OSHA workplace safety mandates sustain replacement-cycle demand for fall-arrest and industrial rigging systems. The US Midwest automotive corridor concentrates seatbelt webbing qualification through tier-one safety system integrators.
India
PLI scheme incentives for advanced automotive components attract seatbelt webbing investment toward domestic OEM supply chains. The country's national automotive regulator enforces safety component standards aligned with UN ECE regulations. Pune and Chennai corridors host emerging narrow-fabric production capacity serving Maruti Suzuki, Hyundai, and Tata Motors assembly programs.
China
GB standards for automotive safety belts mandate tensile-strength and elongation specifications comparable to FMVSS 209. The Yangtze River Delta and Pearl River Delta concentrate export-oriented webbing manufacturing for luggage, outdoor gear, and industrial cargo-securing applications. Domestic EV manufacturers are qualifying local narrow-fabric sources for restraint system integration.
Japan
METI industrial policy supports advanced textile manufacturing for aerospace and automotive applications. JIS standards for synthetic fiber webbing govern break-strength certification for lifting and rigging equipment. The Nagoya automotive cluster and Kanto precision manufacturing corridor sustain specialized procurement from domestic narrow-fabric producers.
Webbing Market Key Industry Players
German producers anchor the premium-tier qualification pathway for automotive and aerospace applications; United States specialists hold volume-driven capacity for industrial safety and cargo-securing segments. The supplier base compresses around tier-one safety system integrators who consolidate yarn and narrow-fabric sourcing across fewer approved vendors. Three archetypes dominate: vertically integrated converters with in-house dyeing and finishing, jacquard weaving specialists serving engineered textile contracts, and regional narrow-fabric mills focused on standardized flat-weave production. Competitive positioning hardens through multi-year OEM qualification timelines and ECHA-registered coating reformulation investments.
Among Germany-based fabricators, E Oppermann GmbH exemplifies the long-term supply relationship archetype with European automotive seating programs. Bally Ribbon Mills occupies a position within the engineered textile tier, leveraging advanced jacquard weaving capabilities for aerospace and defense contracts. National Webbing Products Co represents North American vertical integration, with control over dyeing and finishing operations in domestic manufacturing corridors.
| Leading Market Players |
|---|
| BioThane Coated Webbing Corp |
| Narrowtex Pty Ltd |
| American Cord & Webbing Co Inc |
| Webbing Products Pty Ltd |
| E Oppermann GmbH |
| Bally Ribbon Mills |
| National Webbing Products Co |
| Leedon Webbing Co Inc |
| Murdock Webbing Company Inc |
| Others |
Cost & Logistics Intelligence
Polyester chip and industrial yarn feedstock costs cascade through three distinct pricing tiers, with petrochemical volatility compressing margins most acutely at the commodity flat-weave end while certified automotive and aerospace grades retain pricing power through qualification barriers.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade flat webbing, while European and North American producers defend premium positioning through REACH-compliant coating investments and FMVSS 209 certification. Three-tier pricing structure across premium, standard, and economy levels separates aerospace harnessing with FAA flammability validation from industrial safety grades with OSHA alignment and undifferentiated cargo-securing alternatives. Pricing pressure stems from polypropylene substitution in UV-tolerant applications. Distributors and mass-market retailers exhibit highest price sensitivity; tier-one automotive seating suppliers prioritize qualification stability over unit cost.
Supply Chain Analysis
High-tenacity filament yarn supply rests on German, United States, and Japanese petrochemical-to-textile integration corridors, with specialized narrow-fabric weaving capacity concentrating in North Rhine-Westphalia, the US Midwest, and Japan's Kanto precision manufacturing belt. Raw material dependencies span purified terephthalic acid, adipic acid for nylon variants, and ECHA-registered bio-based plasticizers for REACH-compliant coating reformulation. Single-source vulnerability concentrates around German automotive tier supplier clusters where E Oppermann GmbH anchors regional production. Distribution runs through tier-one safety system integrators who consolidate yarn procurement and narrow-fabric qualification across fewer approved vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Annex XVII phthalate restrictions and FMVSS 209 enforcement simultaneously elevate compliance costs and compress the qualified supplier base, concentrating returns among certified incumbents.
For Market Incumbents: Deepen backward integration into high-tenacity filament yarn production to offset petrochemical feedstock volatility, while accelerating ECHA-registered aqueous coating qualification to capture tier-one automotive sourcing consolidation. Polypropylene substitution in cargo-securing segments threatens volume-driven flat webbing margins; defend positioning through ISO 12401 marine certification expansion into offshore wind maintenance harness applications. For New Entrants and Emerging Players: Launch via digital jacquard weaving platforms serving direct-to-consumer outdoor gear brands in North America, where short-run customization demand outstrips incumbent capacity. India's PLI scheme corridors around Pune and Chennai present the most penetrable white-space for seatbelt webbing qualification, leveraging UN ECE-aligned national automotive safety standards to bypass multi-year OEM validation timelines faced by established European suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional narrow-fabric mills with captive dyeing and finishing operations because tier-one safety system integrators are consolidating approved vendor lists and favoring vertically qualified suppliers. Target mid-cap converters with FMVSS 209 or FAA flammability certification already in place; watch for REACH Article 33 compliance timeline pressure as the inflection indicator for distressed acquisition opportunities among coating-dependent European players.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Reformulation | ECHA-registered aqueous polymer validation secures tier-one automotive qualification pathways. |
| Digital Jacquard Weaving Investment | Pattern-on-demand capability captures direct-to-consumer outdoor gear customization demand. |
| India PLI Corridor Expansion | Domestic seatbelt webbing capacity serves Maruti Suzuki and Hyundai assembly programs. |
| ISO 12401 Marine Certification Extension | Break-strength protocols open offshore wind turbine maintenance harness procurement. |
| Recycled-Content Polyester Integration | Post-consumer filament yarn aligns with European OEM circularity mandates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with narrow-fabric plant managers, tier-one automotive seating procurement leads, ECHA regulatory affairs specialists, and aerospace harness integrators with secondary validation through customs trade data, SEC filings of listed textile producers, vehicle production databases, and ECHA substance dossier updates. Bottom-up capacity and demand modeling triangulated against top-down market sizing from automotive safety component forecasts and industrial safety equipment procurement trends.
Historical reference periods anchored the projection horizon to established regulatory milestone timelines and OEM qualification cycle patterns. Segmentation modeling spanned material tenacity grades, application certification intensity, end-user procurement scale, and weave architecture complexity. CAGRs derived from regression analysis against vehicle assembly volumes, construction sector OSHA enforcement patterns, and aerospace seating program deliveries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price volatility extremes or accelerated REACH restriction expansion beyond Annex XVII phthalate scope. Material deviation in REACH compliance timeline enforcement or NHTSA FMVSS 209 testing laboratory accreditation delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
Technical Textile Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Geotextile Tubes Market