
 Geotextile Tubes Market | 2026-2036
Geotextile Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Geotextile Tubes Market Intelligence
Municipal port authorities are rotating procurement toward environmental engineering firms for large-scale dewatering and shoreline reinforcement contracts. Koninklijke TenCate anchors its position through captive supply of high-tenacity polypropylene yarns. NAUE GmbH & Co. KG differentiates via specialized composite tube designs for hydraulic fill applications. TechFab India Industries Ltd competes on manufacturing scale across South Asian infrastructure corridors.
Geotextile tubes are engineered containment structures fabricated from permeable woven or non-woven synthetic textiles, typically polypropylene or polyester, designed to be hydraulically filled with slurry and dewatered through the fabric pores while retaining solids. These structures serve primary functions in coastal defense, sediment management, and environmental containment by providing mechanical stabilization and controlled filtration. Woven products dominate current volume due to established tensile strength benchmarks and lower unit costs in standard dewatering applications. Composite configurations represent the fastest-expanding category as hybrid laminates address demanding hydraulic gradients in flood control and landfill capping projects where puncture resistance governs specification.
The EPA enforces Clean Water Act provisions that mandate turbidity controls during marine construction, directly elevating geotextile tube specifications for sediment containment. The Army Corps of Engineers maintains engineering manual standards for coastal structures that shape product certification and contractor prequalification. ISO 10319 tensile testing protocols and ASTM D4595 provide international material benchmarks that manufacturers must satisfy for cross-border project eligibility. Stakeholders should monitor evolving polymer recycling mandates and bio-based fiber substitutions that could redefine cost structures and supplier qualification criteria.
Market Dynamics
Coastal protection mandates from the EPA and Army Corps of Engineers are compressing contractor qualification timelines while accelerating specification upgrades for high-tenacity woven structures. Procurement officers now prioritize pre-certified suppliers capable of rapid deployment across shoreline stabilization and hydraulic fill projects.
Growth Catalysts
- Clean Water Act enforcement:The EPA's turbidity control mandates during marine construction elevate geotextile tube specifications for sediment containment in port expansion zones.
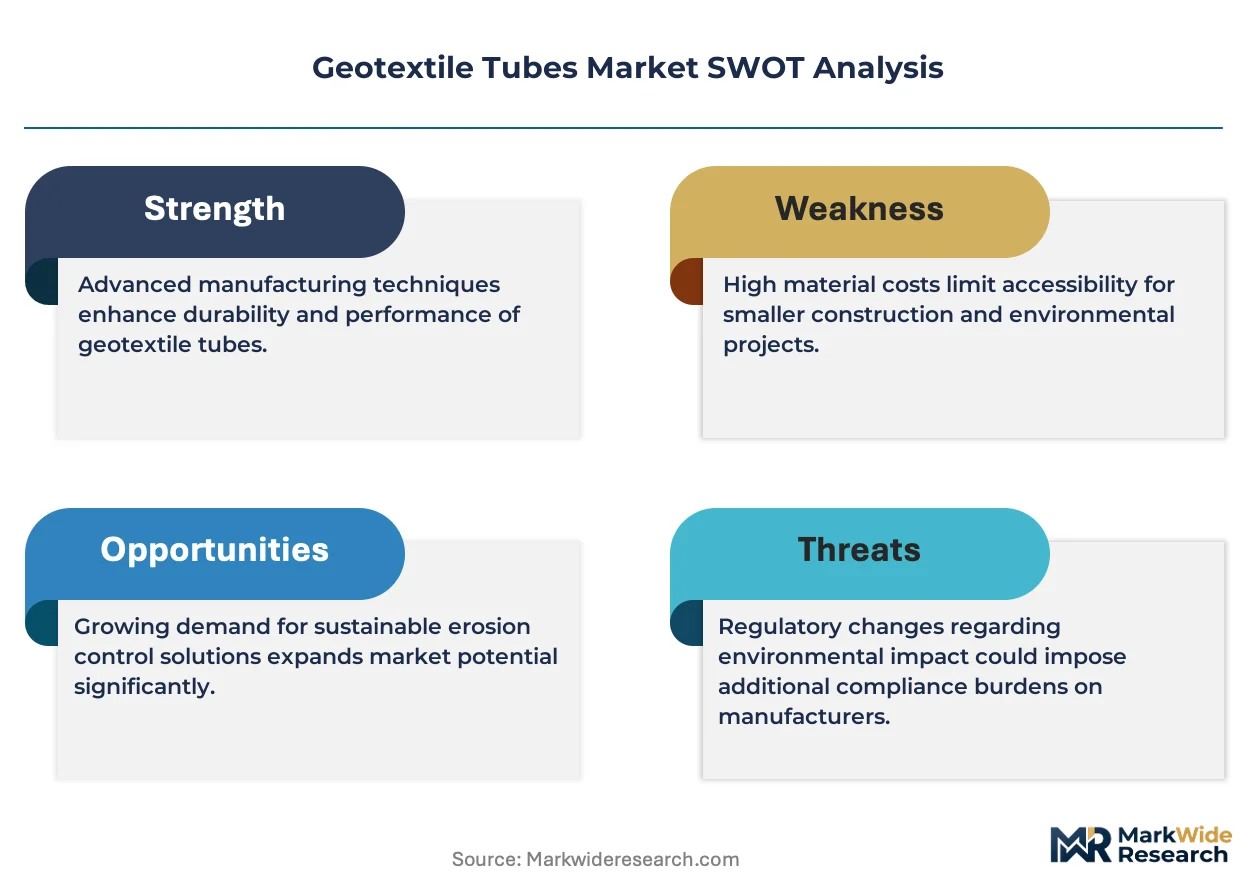
- Polypropylene weaving advances:High-strength yarn production improvements reduce unit costs while maintaining ASTM D4595 tensile benchmarks for standard dewatering contracts.
- Delta protection programs:The Netherlands' Room for the River initiative sustains large-volume deployments for flood control and shoreline reinforcement.
Market Restraints
- Petroleum feedstock volatility:Polypropylene resin prices fluctuate with crude oil markets, compressing margin visibility for tube fabricators.
- Yarn supply concentration:Captive production of high-tenacity polypropylene fibers limits qualified supplier pools to integrated manufacturers.
- Composite laminate complexity:Multi-layer bonding requirements extend quality certification timelines beyond standard woven product cycles.
Strategic Opportunities
- Landfill capping expansion:Stricter leachate containment rules in China create demand for puncture-resistant composite configurations.
- Sludge dewatering diversification:Municipal wastewater authorities in India specify geotextile tubes for biosolid management, opening new procurement channels.
- ISO 10319 harmonization:International tensile testing standardization reduces cross-border certification friction for export-oriented manufacturers.
Industry Challenges
- Geotechnical engineering talent scarcity:Specialized design expertise for hydraulic fill calculations concentrates among aging practitioner cohorts.
- Installation equipment capex:Hydraulic pumping systems and specialized filling apparatus require capital commitments that strain mid-tier contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geotextile Tubes Market |
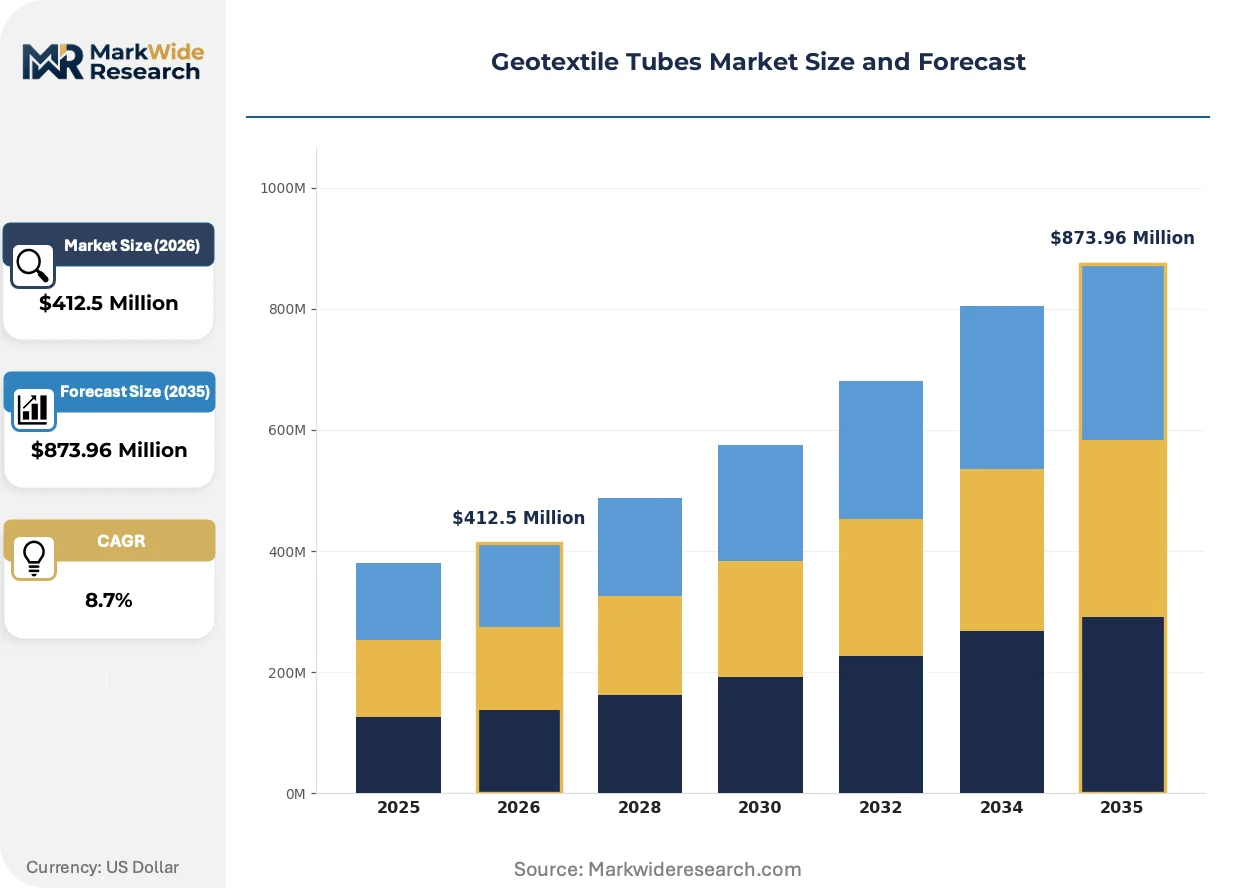
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-Woven, Composite, Specialty Application: Dewatering, Coastal Protection, Flood Control, Landfill End User: Civil Engineering, Environmental Management, Agriculture, Construction Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Ace Geosynthetics, Officine Maccaferri, Low & Bonar, Flexituff Ventures International Limited, TechFab India Industries Ltd, Geofabrics Australasia Pty Ltd, Koninklijke TenCate, NAUE GmbH & Co. KG, Huesker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geotextile Tubes Market Strategic Shifts & Innovations
Material science advances and procurement digitization are restructuring competitive differentiation in geotextile containment systems. Specification authority is migrating from general contractors to environmental engineering firms with direct regulatory relationships.
Composite laminate technology is bifurcating the product hierarchy. Hybrid structures combining woven polypropylene substrates with non-woven filtration layers address demanding hydraulic gradients in flood control and landfill capping where puncture resistance governs selection. Coastal defense agencies in the Netherlands and China specify these configurations for delta protection, compressing demand for basic woven tubes in premium segments while standard dewatering contracts retain commodity-grade procurement.
REACH chemical registration requirements in Europe are tightening polymer additive disclosure for geosynthetic products. Manufacturers must document plasticizer and UV stabilizer compositions to maintain CE marking eligibility for cross-border infrastructure tenders. This regulatory friction favors integrated producers with captive polymer compounding capabilities over converters reliant on third-party resin supply.
Specification authority migration toward environmental engineering firms is consolidating procurement decision-making. Municipal port authorities now delegate shoreline stabilization contract design to specialized consultants with direct Army Corps of Engineers relationships, bypassing traditional general contractor intermediaries. This channel compression concentrates volume with pre-qualified suppliers capable of rapid technical response in United States coastal zones.
Geotextile Tubes Market Segmentation
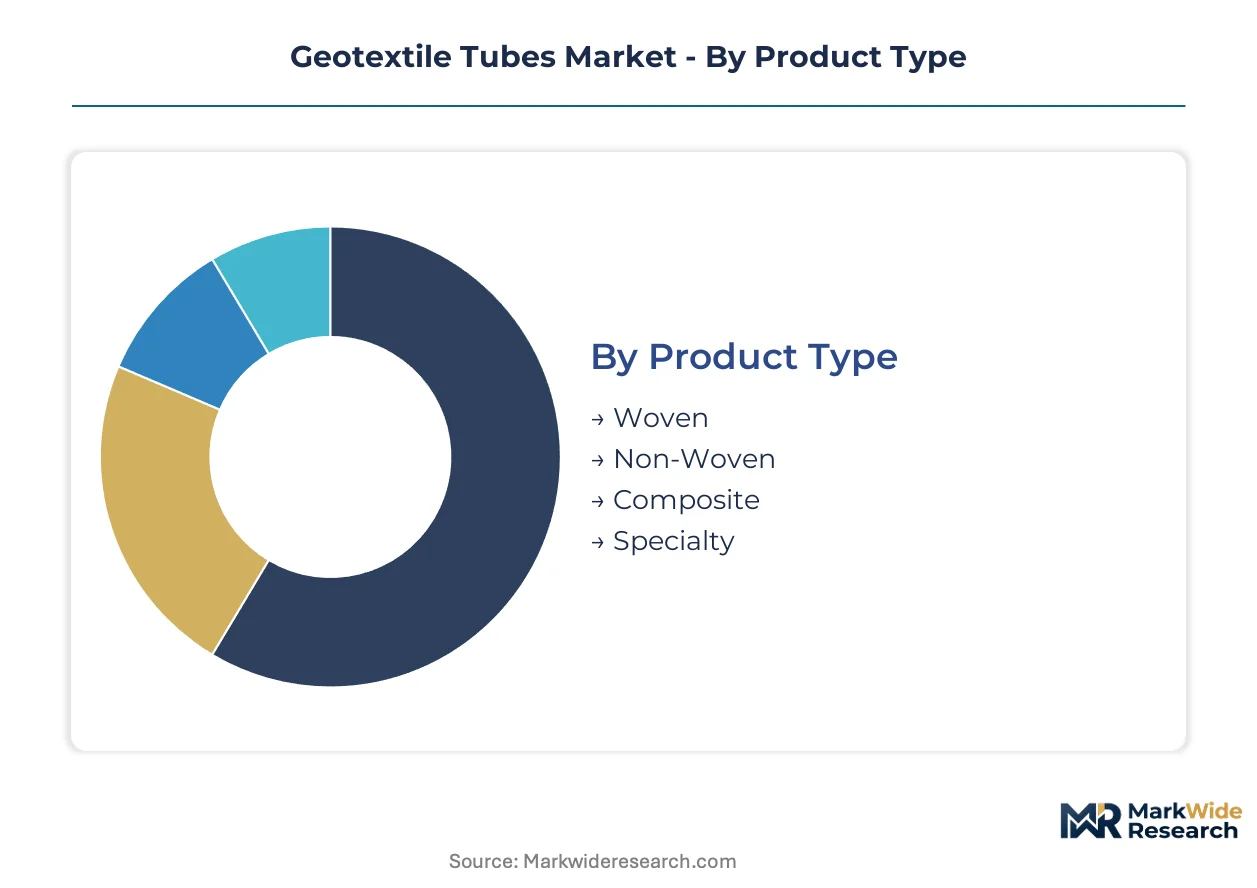
Geotextile tube procurement flows through distinct channel hierarchies shaped by project scale and technical complexity. Specification authority concentrates with environmental engineering firms for coastal defense contracts, while standard dewatering orders route through distributor networks serving mid-tier contractors.
Product Type:
Woven and composite tubes dominate direct sales channels to port authorities and coastal agencies, while non-woven and specialty grades move through distributors serving agricultural and small-scale construction buyers.
- Woven:Polypropylene fabrics meeting ASTM D4595 tensile benchmarks anchor standard dewatering and shoreline stabilization contracts. Demand concentrates in United States coastal zones where Army Corps of Engineers specifications govern procurement, with volume sustained by recurring port maintenance cycles.
- Composite:Hybrid laminates combining woven substrates with non-woven filtration layers command premium positioning for landfill capping and flood control. China's leachate containment rules and Netherlands delta protection programs drive specification upgrades where puncture resistance outweighs unit cost considerations.
- Non-Woven:Needle-punched polyester configurations serve secondary containment and erosion control in agricultural drainage applications.
- Specialty:Custom-engineered configurations with enhanced UV stabilizers target extended-deployment coastal defense projects in high-salinity environments.
By volume, woven leads. By growth pace, composite is ahead.
Application:
Project scale and regulatory scrutiny segment channel access, with direct manufacturer relationships reserved for multi-million dollar coastal defense tenders while distributors capture fragmented dewatering orders.
- Dewatering:Sludge containment for municipal wastewater and industrial sediment management represents the established revenue base. India's biosolid management expansion and United States EPA turbidity mandates sustain procurement velocity through environmental engineering procurement channels.
- Coastal Protection:Breakwater construction and shoreline stabilization command the highest unit values per installed meter. Netherlands Room for the River deployments and United States Gulf Coast restoration programs concentrate demand with pre-qualified suppliers capable of rapid technical response.
- Flood Control:Temporary and permanent embankment structures for riverine and urban flood management.
- Landfill:Leachate collection and capping systems for waste containment facilities.
Dewatering generates the highest shipment volumes. Coastal protection commands the steepest expansion trajectory.
End User:
Customer technical sophistication determines specification authority, with civil engineering firms and environmental management agencies driving standards while construction and agriculture follow commodity procurement patterns.
- Civil Engineering:Infrastructure contractors with direct Army Corps of Engineers relationships specify high-tenacity woven tubes for hydraulic fill and shoreline reinforcement. Procurement concentrates in United States coastal states and Netherlands delta regions where design-build contracts consolidate volume with integrated manufacturers.
- Environmental Management:Remediation specialists and municipal authorities with EPA compliance mandates drive composite tube adoption for sediment containment and leachate control.
- Agriculture:Farm operators and drainage contractors source standard woven configurations through regional distributors for field erosion control.
- Construction:General contractors and site developers purchase commodity-grade tubes for temporary sediment barriers and foundation dewatering.
Civil engineering anchors current revenue. Environmental management is climbing the fastest.
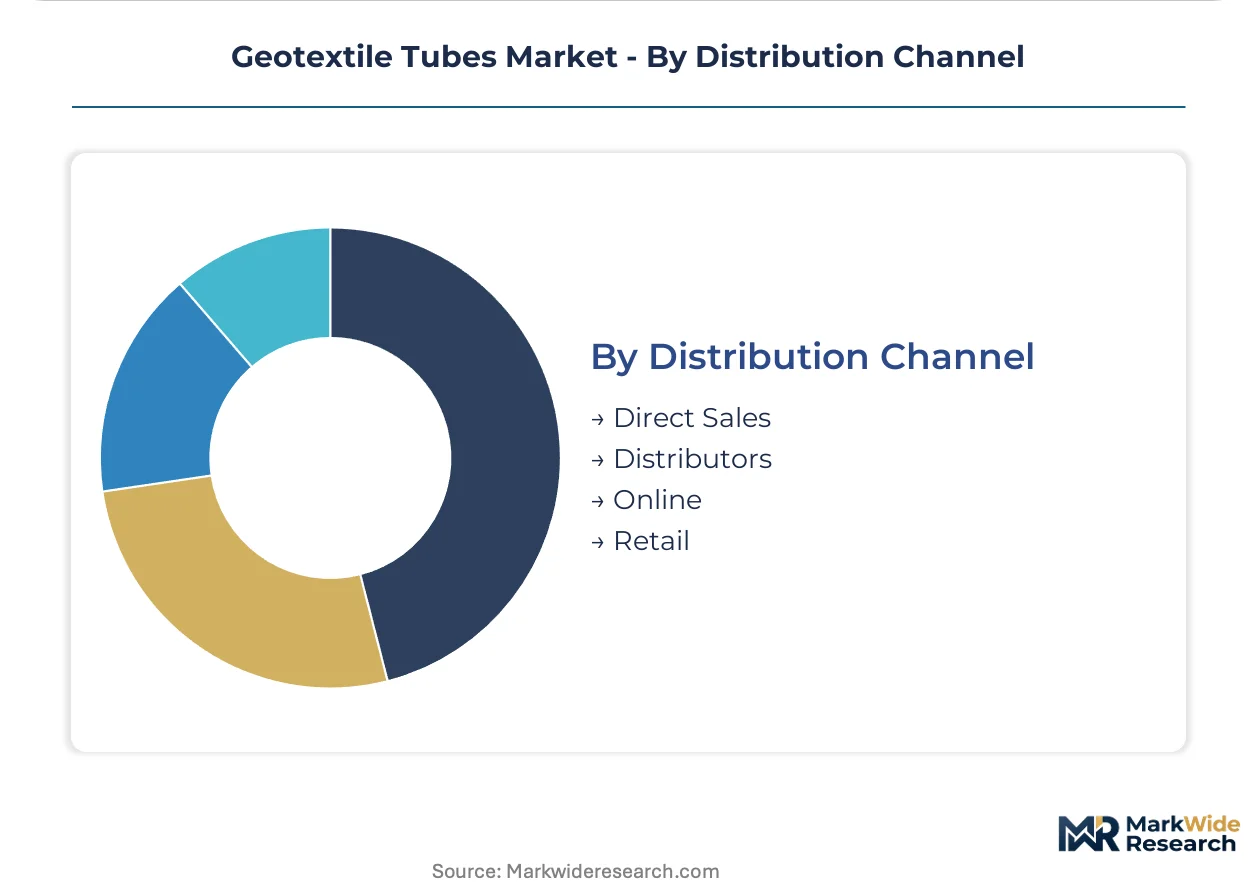
Distribution Channel:
Channel selection tracks project complexity and certification requirements, with direct sales capturing engineered specifications while distributors serve price-sensitive repeat purchases.
- Direct Sales:Manufacturer-direct relationships dominate coastal protection and large-scale dewatering contracts requiring custom specifications and rapid deployment. United States port authorities and Netherlands water management agencies mandate direct technical liaison for certification compliance.
- Distributors:Regional stocking distributors serve mid-tier contractors and agricultural buyers with standard woven products, compressing lead times for recurring orders.
- Online:Digital procurement portals capture small-volume orders from independent contractors and maintenance departments.
- Retail:Limited presence for consumer-grade erosion control products in home improvement channels.
Direct sales commands the premium tier. Distributors handle the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export woven polypropylene tubes to port authorities in the United States and delta protection agencies in the Netherlands, establishing a trans-Pacific trade corridor that channels high-tenacity fabrics toward coastal defense procurement.
United States
Army Corps of Engineers shoreline stabilization contracts and EPA turbidity mandates under the Clean Water Act drive specification upgrades for high-tenacity woven structures. Gulf Coast restoration programs concentrate demand in Louisiana and Texas, where hydraulic fill projects require rapid deployment capabilities.
Netherlands
Room for the River flood control initiatives sustain large-volume deployments of composite laminates for delta protection. Rijkswaterstaat engineering standards mandate puncture-resistant configurations for embankment reinforcement, compressing procurement timelines for pre-qualified suppliers.
China
Port expansion along the Yangtze River Delta and stricter MEE leachate containment rules for landfill capping accelerate composite tube adoption. Shanghai municipal authorities specify hybrid configurations for sediment management in high-hydraulic-gradient environments.
India
Municipal wastewater authorities in Maharashtra and Gujarat specify geotextile tubes for biosolid management under evolving CPCB guidelines. TechFab India Industries anchors manufacturing scale across South Asian infrastructure corridors serving port modernization projects.
Germany
REACH chemical registration requirements tighten polymer additive disclosure for geosynthetic products seeking CE marking. Engineering consultancies in North Rhine-Westphalia specify composite tubes for Rhine flood control, favoring integrated producers with captive polymer compounding capabilities.
Geotextile Tubes Market Key Industry Players
Listed leaders compete with private specialists across certification depth and polymer integration. The vendor base stratifies into three tiers: integrated manufacturers with captive yarn production, regional fabricators sourcing third-party resins, and specialized composite engineers. Strategic moves concentrate on backward integration into high-tenacity polypropylene fiber production and rapid technical response capabilities for Army Corps pre-qualification.
Among European integrated manufacturers, Koninklijke TenCate and NAUE GmbH & Co. KG occupy positions emphasizing polymer control and composite engineering respectively. TechFab India Industries exemplifies scale-driven fabrication serving South Asian infrastructure corridors. These three anchors represent distinct competitive archetypes: captive supply chain integration, specialized laminate design, and regional manufacturing scale.
| Leading Market Players |
|---|
| Ace Geosynthetics |
| Officine Maccaferri |
| Low & Bonar |
| Flexituff Ventures International Limited |
| TechFab India Industries Ltd |
| Geofabrics Australasia Pty Ltd |
| Koninklijke TenCate |
| NAUE GmbH & Co. KG |
| Huesker |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day yarn inventory cycles at integrated polypropylene manufacturers compress pricing power for downstream fabricators while amplifying margin capture for captive producers. This lead-time band concentrates cost pass-through advantages with suppliers controlling high-tenacity fiber production, forcing converters to absorb petroleum feedstock volatility or cede volume to backward-integrated competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates composite laminates meeting ASTM D4595 and ISO 10319 dual certification from commodity woven tubes and non-woven agricultural grades. Certification grade and volume scale drive price differentiation, with EPA pre-qualified suppliers commanding fifteen-to-twenty percent premiums over uncertified competitors. Cost compression in standard woven tiers is intensifying because Chinese manufacturers are expanding export capacity into United States port authority contracts. Municipal wastewater authorities exhibit the highest price sensitivity due to fixed-budget procurement cycles, while Netherlands delta protection agencies prioritize puncture resistance over unit economics.
Supply Chain Analysis
China and India anchor woven polypropylene fabric production, while the Netherlands and Germany concentrate composite laminate engineering and polymer compounding. Raw material dependencies center on polypropylene resin, high-tenacity yarn, and UV stabilizer additives. Single-source vulnerability runs through concentrated high-tenacity fiber production among three integrated European and Asian manufacturers. Distribution runs through direct manufacturer relationships for coastal defense contracts and regional distributors for standard dewatering applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geotechnical engineering expertise for hydraulic fill calculations concentrates among aging practitioner cohorts, creating a capability bottleneck that constrains project execution velocity and elevates contractor qualification premiums.
For Market Incumbents: Shield margin structures by deepening captive supply of high-tenacity polypropylene yarns against petroleum feedstock volatility. Accelerate Army Corps of Engineers pre-certification investments to compress competitor access timelines for Gulf Coast restoration contracts. Consolidate specification authority by embedding technical liaison teams directly with environmental engineering firms. For New Entrants and Emerging Players: Rapid-deployment service capabilities for shoreline stabilization projects represent the most penetrable white-space target, as incumbent response times lag Netherlands Rijkswaterstaat procurement deadlines. Municipal biosolid management authorities in India offer secondary entry points with lower certification barriers. Pursue design-build partnerships with regional civil engineering firms lacking in-house geosynthetic expertise. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority migration toward environmental engineering firms concentrates volume with pre-qualified suppliers possessing rapid technical response capabilities. Target acquisition profiles emphasize integrated manufacturers with captive yarn production and established Army Corps relationships. Monitor EPA turbidity enforcement intensity as the inflection signal for specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Tenacity Fiber Production | Captive polypropylene yarn supply insulates margin structures from petroleum feedstock volatility. |
| Army Corps of Engineers Pre-Certification Investment | EPA turbidity mandates elevate barrier-to-entry for shoreline stabilization contract eligibility. |
| Composite Laminate R&D Partnership | Hybrid configurations address Netherlands delta protection and China landfill capping specifications. |
| Environmental Engineering Firm Technical Liaison Program | Specification authority migration concentrates procurement decision-making with specialized consultants. |
| South Asian Manufacturing Scale Expansion | India port modernization and biosolid management programs sustain regional demand corridors. |
Research Approach
A spread of perspectives from coastal protection agency procurement officers, environmental engineering firm technical directors, geosynthetic fabricators, and polymer compounding specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Army Corps of Engineers engineering manuals, EPA Clean Water Act enforcement records, ISO 10319 testing protocols, and ASTM D4595 material benchmarks. Bottom-up shipment data from regional distributors triangulated against top-down port authority contract disclosures.
Segmentation dimensions modeled include product type tier, application complexity, end-user technical sophistication, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating polymer price scenarios and regulatory enforcement intensity. Industry-specific forecast inputs encompass hydraulic fill project pipelines, delta protection program budgets, and municipal wastewater capital expenditure cycles.
Forecasts assume regulatory continuity in United States EPA turbidity mandates and Netherlands Room for the River funding commitments; material policy shifts would require re-modeling. Petroleum feedstock volatility, geotechnical engineering talent scarcity, and composite laminate certification timelines constitute primary revision risks. Recalibration cycles align with material shifts in coastal erosion regulation stringency and polymer recycling mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
US Geotextile Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Webbing Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Technical Textile Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Construction Textile Market
Technical Textiles
Europe Contract Textiles Market