
 Construction Textile Market | 2026-2036
Construction Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Textile Market Analysis
Performance-based maintenance contracts is broadening what contractors purchase beyond raw textile rolls. Glen Raven leverages its coated fabric expertise to capture higher-margin service relationships with infrastructure operators. Freudenberg Performance Materials anchors European supply through specialized non-woven geotextile manufacturing at scale. DuPont differentiates via advanced polymer science that extends product lifespans in aggressive soil environments.
Construction textiles encompass engineered fiber-based materials—typically polyester, polypropylene, or aramid—manufactured through weaving, knitting, or non-woven bonding to achieve specified tensile strengths, permeability coefficients, and UV resistance for structural reinforcement, drainage, or erosion control. Geosynthetics lead product value pools due to their load-bearing function in civil earthworks, while coated technologies command premium positioning through moisture barriers that protect subgrade integrity over decades. Infrastructure applications dominate volume demand, though environmental protection segments are gaining structural share as regulators mandate sediment containment and landfill liner standards.
ISO 10318 geosynthetic classification standards, the EU Green Deal's embodied carbon tracking requirements, and India's BIS IS 16391 geotextile specifications collectively shape material selection, testing protocols, and cross-border certification burdens. REACH chemical restrictions in Europe and evolving EPA stormwater management rules in the United States further constrain polymer formulations and installation practices. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven margin erosion and supply chain fragmentation.
Market Dynamics
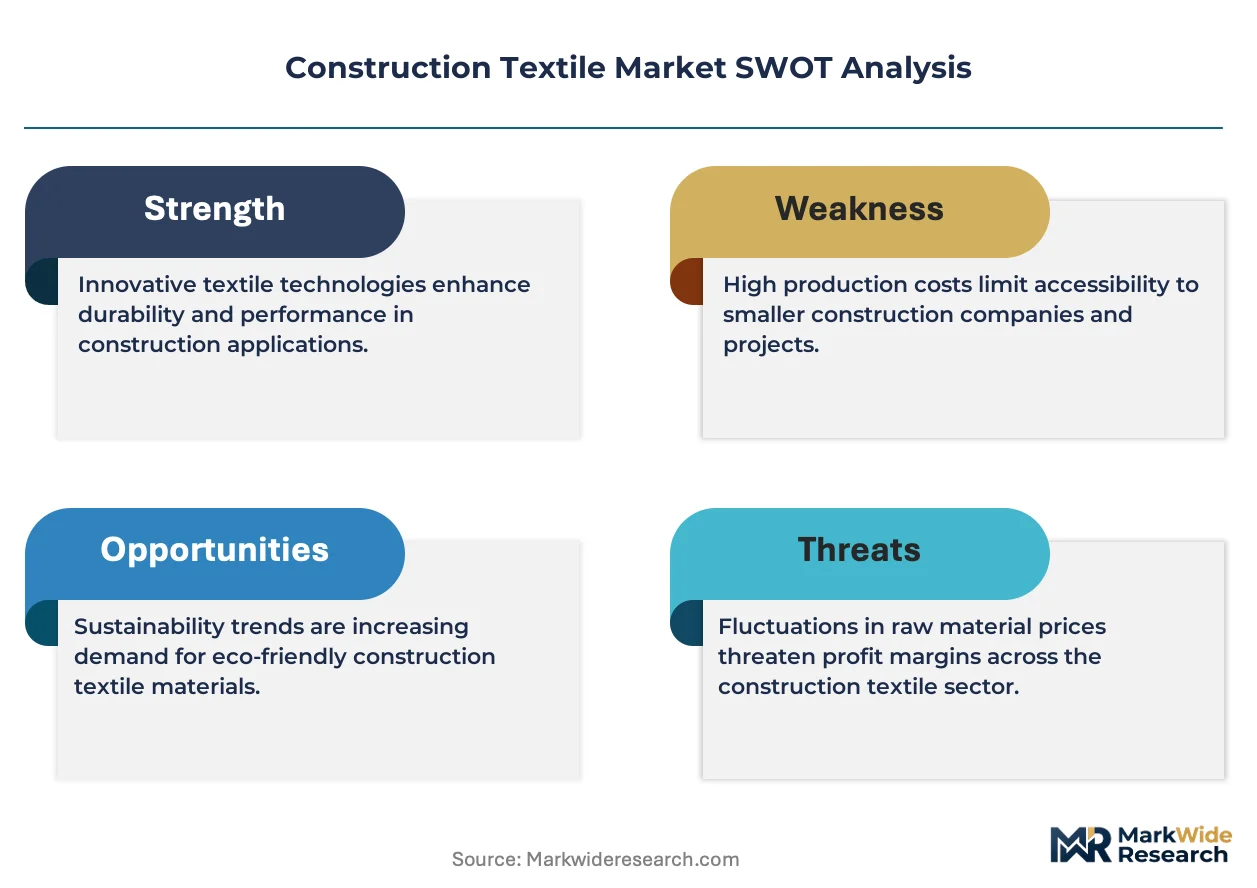
Geosynthetic reinforcement is displacing conventional steel and concrete in civil earthworks as infrastructure operators prioritize lifecycle cost reduction and accelerated construction schedules over upfront material expenditure.
Growth Catalysts
- Highway Infrastructure Modernization:India's National Highways Authority is mandating geotextile stabilization layers in new roadbed construction, creating sustained demand pull for polyester non-woven grades.
- EU Green Deal Embodied Carbon Tracking:Infrastructure tenders across Germany, France, and the Netherlands now require environmental product declarations that favor low-carbon geosynthetics over energy-intensive traditional materials.
- Polypropylene Fiber Advances:Enhanced UV stabilization chemistries are extending product warranties to 50+ years in desert climates, opening arid-zone applications previously reserved to concrete.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyester resin prices fluctuate with crude oil benchmarks, compressing margins for non-integrated textile converters in Gujarat's industrial corridor.
- Technical Performance Gaps in Extreme pH:Standard geotextiles degrade in acid mine drainage and alkaline industrial leachate, limiting penetration in mining tailings and chemical waste containment.
- REACH Chemical Authorization Burdens:European ECHA restrictions on phthalate plasticizers and certain flame retardants force reformulation cycles that delay product certification by 18-24 months.
Strategic Opportunities
- Smart Geosynthetics Integration:Embedding fiber optic strain sensors within geogrid structures is automating real-time structural health monitoring for dam and landfill operators.
- Biopolymer Feedstock Transition:Polylactic acid and bio-based polypropylene from agricultural waste streams offer pathways to carbon-negative certification under emerging EU taxonomy rules.
- Performance-Based Maintenance Contracts:Highway concessionaires in Brazil and Mexico are transferring geosynthetic installation risk to material suppliers through 20-year durability guarantees.
Industry Challenges
- Geotechnical Engineer Shortage:Specialized design expertise for geosynthetic-stabilized slopes and retaining walls remains concentrated among aging practitioners in North American and European consultancies.
- BIS Certification Backlogs:India's Bureau of Indian Standards testing queue for IS 16391 geotextile compliance currently extends 8-10 months, delaying project approvals.
- Legacy System Integration Friction:Digital twin platforms for infrastructure asset management lack standardized data interfaces with geosynthetic sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Textile Market |
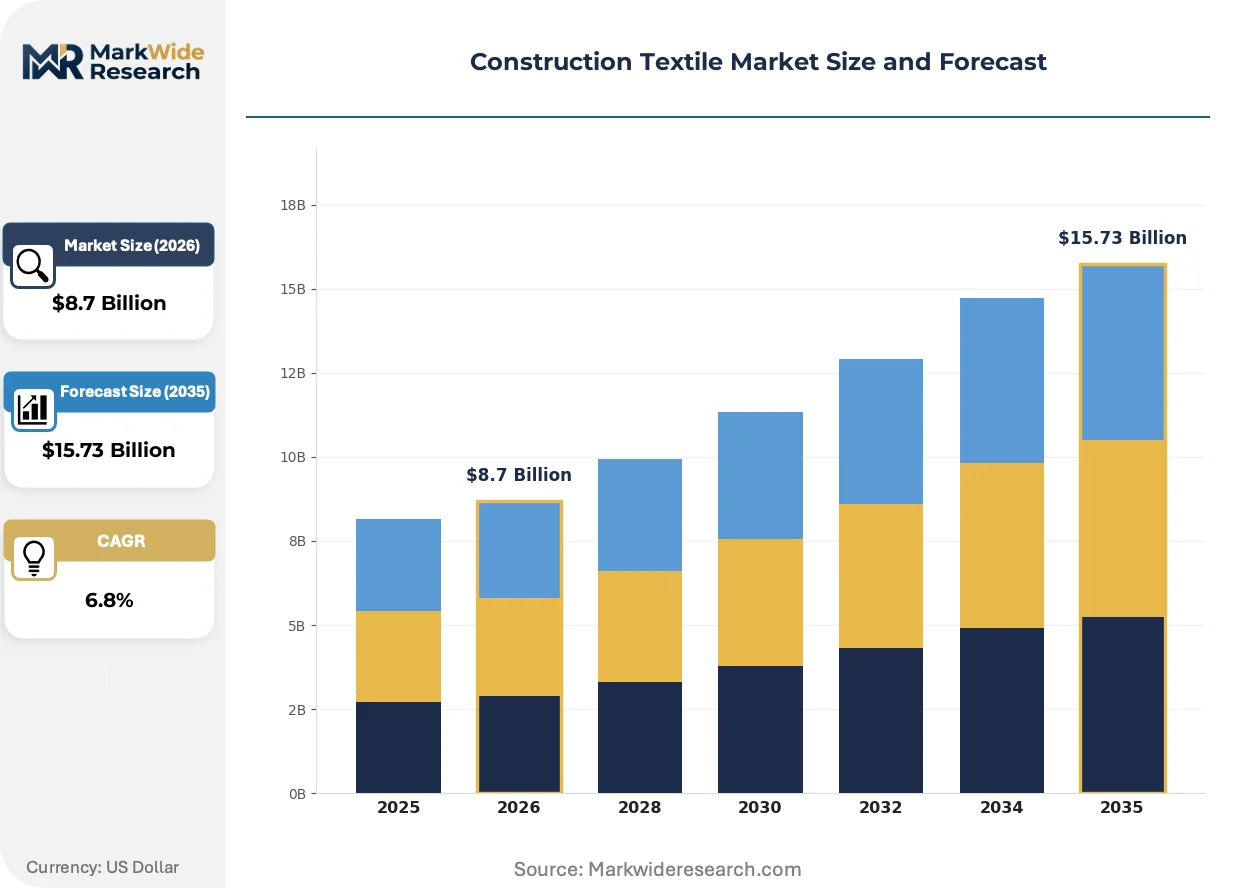
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geosynthetics, Fabrics, Non-wovens, Canvas Application: Infrastructure, Road Construction, Soil Stabilization, Environmental Protection Technology: Knitted, Woven, Braided, Coated End User: Contractors, Engineers, Architects, Project Managers |
| Companies Covered | Glen Raven, Low & Bonar, Milliken & Company, DuPont, Freudenberg Performance Materials, Shaw Industries Group, Mount Vernon Mills, Saint-Gobain, Mohawk Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Textile Market Emerging Trajectories
Material science convergence with digital infrastructure is redefining how construction textiles are specified, installed, and monitored across heavy civil projects.
Automated geosynthetic installation equipment is automating the deployment of large-format geotextile rolls on highway embankments and landfill caps. Contractors in Australia's mining regions are adopting GPS-guided laying machines that reduce labor crews by 60% while improving seam alignment precision. This automation is compressing project timelines and shifting contractor selection criteria toward equipment capability rather than manual labor scale.
REACH chemical restrictions are forcing polymer formulators to eliminate legacy plasticizers and halogenated flame retardants from coated geotextile specifications. ECHA's 2023 authorization list updates have triggered reformulation investments exceeding €50 million across European manufacturing facilities. Technical textiles for tunnel waterproofing and landfill liners are experiencing the steepest compliance cost inflation as substitution timelines compress.
Asset owners are unbundling geosynthetic supply from installation services, creating separate procurement categories for material supply, design verification, and long-term performance monitoring. State transportation departments in the US and provincial authorities in Canada now require independent third-party certification of seam strength and installation quality before final payment release. This bifurcation is most visible in public-private partnership highway contracts where material warranties extend 25-30 years beyond construction completion.
Construction Textile Market Segmentation
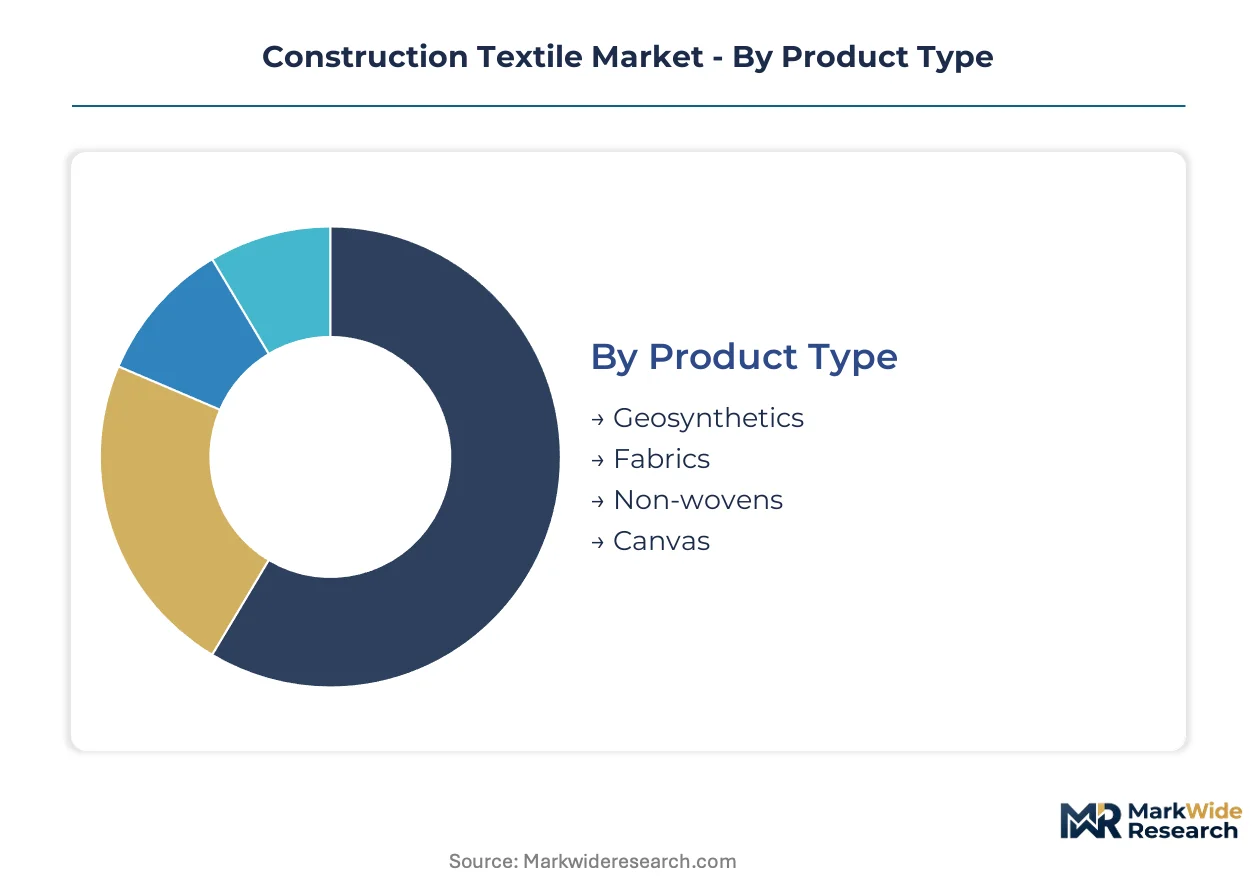
Construction textile specifications vary dramatically across civil engineering applications, with material selection governed by tensile load requirements, soil chemistry, and installation environment. Understanding how demand fragments across product architectures and stakeholder workflows reveals where procurement budgets concentrate and where specification authority resides.
Product Type:
Material architecture determines load-bearing capacity, permeability, and installation methodology across civil earthworks.
- Geosynthetics:Engineered polymer grids and sheets provide soil reinforcement, drainage, and containment functions in highway embankments and landfill liners. India's NHAI mandates geotextile stabilization layers in national highway construction, pulling polyester non-woven grades into sustained procurement cycles.
- Fabrics:Woven and non-woven textile sheets deliver filtration, separation, and protection in roadbed construction and erosion control. Demand clusters in Gujarat's industrial corridor where petrochemical feedstocks support domestic manufacturing scale.
- Non-wovens:Bonded fiber mats offer high permeability and conformability for drainage applications and subgrade protection. These materials dominate environmental protection segments as regulators mandate sediment containment standards.
- Canvas:Heavy-duty cotton or synthetic duck fabrics serve temporary shelters, concrete curing covers, and equipment protection on construction sites. Specifications emphasize tear resistance and reusability for cost-conscious contractors.
Mature deployment sits with geosynthetics in highway infrastructure. Newer deployment is concentrated in environmental protection applications requiring specialized containment properties.
Application:
End-use context dictates performance specifications, certification requirements, and procurement channel selection.
- Infrastructure:Bridges, tunnels, and port facilities demand high-tenacity geosynthetics with decades-long durability guarantees. Brazil and Mexico highway concessionaires now require 20-year material warranties from suppliers.
- Road Construction:Geotextile stabilization layers accelerate subgrade preparation and reduce aggregate thickness in highway embankments. India's BIS IS 16391 certification requirements are tightening material specifications nationwide for these applications.
- Soil Stabilization:Geogrid reinforcement prevents slope failure and retaining wall deformation in challenging terrain. Technical design expertise for these applications remains concentrated among specialized geotechnical consultancies.
- Environmental Protection:Landfill liners, sediment barriers, and remediation caps require chemical-resistant formulations. EU Green Deal embodied carbon tracking requirements now favor low-carbon geosynthetics over traditional materials in these segments.
Volume concentration rests with road construction. Specification complexity and margin expansion are climbing fastest in environmental protection.
Technology:
Fabrication method establishes mechanical properties, production economics, and suitability for automated installation.
- Knitted:Interlooped yarn structures deliver high extensibility and tear resistance for dynamic load applications. These textiles accommodate ground settlement without structural compromise.
- Woven:Orthogonal yarn interlacing provides precise tensile strength and dimensional stability for geogrid reinforcement. Australia's mining contractors deploy GPS-guided laying machines for large-format woven roll installation.
- Braided:Intertwined yarn systems create tubular or flat structures with balanced load distribution. These configurations serve specialized applications in marine and hydraulic engineering.
- Coated:Polymer film lamination imparts moisture barriers, UV resistance, and chemical protection. REACH chemical restrictions are forcing reformulation of legacy plasticizers and flame retardants in European coated textile production.
Established volume sits with woven constructions. Coated technologies command premium positioning through extended warranty terms and aggressive environment performance.
End User:
Professional role determines specification authority, risk tolerance, and procurement decision criteria.
- Contractors:Installation firms prioritize material cost, availability, and compatibility with automated deployment equipment. Performance-based maintenance contracts are shifting risk allocation toward material suppliers.
- Engineers:Design professionals specify products based on ISO 10318 classification standards and project-specific geotechnical calculations. Shortage of specialized geosynthetic design expertise constrains market penetration in complex applications.
- Architects:Building designers incorporate textile membranes and tensile structures for aesthetic and functional building envelopes. These applications emphasize visual finish and long-term color stability.
- Project Managers:Construction oversight roles coordinate material procurement, installation scheduling, and compliance documentation. Third-party certification of seam strength and installation quality now precedes final payment release in public infrastructure contracts.
Specification authority concentrates with engineers. Procurement execution and risk-bearing are migrating toward contractors under evolving contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's industrial corridor anchors geotextile manufacturing capacity, with petrochemical feedstock integration supporting domestic non-woven production at scale.
India
Highway infrastructure modernization drives polyester non-woven procurement, as India's National Highways Authority mandates geotextile stabilization layers in national roadbed construction. BIS IS 16391 certification requirements are tightening material specifications nationwide. Gujarat's petrochemical belt concentrates domestic manufacturing capacity, with feedstock-integrated converters capturing cost advantages.
United States
State transportation departments unbundle geosynthetic supply from installation services, creating separate procurement categories for material and long-term monitoring. EPA stormwater management rules constrain polymer formulations and installation practices. Midwestern highway corridors concentrate demand, with GPS-guided deployment equipment reducing project timelines.
Germany
Infrastructure tenders require environmental product declarations favoring low-carbon geosynthetics over energy-intensive traditional materials under EU Green Deal embodied carbon tracking. ECHA REACH restrictions on phthalate plasticizers force reformulation cycles. The Ruhr industrial region hosts specialized coated fabric manufacturing for tunnel waterproofing applications.
Brazil
Highway concessionaires transfer geosynthetic installation risk to material suppliers through 20-year durability guarantees under performance-based maintenance contracts. ANVISA chemical regulations influence polymer import specifications. São Paulo's infrastructure corridor concentrates demand for geogrid reinforcement in slope stabilization projects.
Australia
Mining contractors adopt automated geosynthetic installation equipment with GPS-guided laying machines reducing labor crews by 60% while improving seam alignment precision. TGA-equivalent infrastructure standards govern material certification. Western Australia's mining regions concentrate deployment of large-format woven roll systems for tailings containment.
Construction Textile Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the construction textile value chain, with integrated polymer manufacturers holding feedstock cost advantages over specialized converters. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive resin supply, regional textile specialists with coating and lamination expertise, and equipment-integrated installation contractors capturing service revenue. Dominant competitive moves include backward integration into polymer production and strategic partnerships with infrastructure operators for long-term performance contracts.
Among North American material science conglomerates, DuPont and Milliken & Company occupy positions emphasizing advanced polymer formulations and specialized non-woven manufacturing. European specialists exemplify regional supply anchoring, with Freudenberg Performance Materials representing scale-driven non-woven geotextile production. Glen Raven sits within the coated fabric tier, leveraging technical textile expertise for higher-margin service relationships with infrastructure operators.
| Leading Market Players |
|---|
| Glen Raven |
| Low & Bonar |
| Milliken & Company |
| DuPont |
| Freudenberg Performance Materials |
| Shaw Industries Group |
| Mount Vernon Mills |
| Saint-Gobain |
| Mohawk Industries |
| Others |
Supply Flow & Price Mechanics
India's BIS IS 16391 certification tightening is forcing domestic converters to absorb extended testing timelines and reformulation costs, compressing margins on polyester non-woven grades while feedstock-integrated Gujarat producers maintain pricing power through captive petrochemical supply.
Pricing Analysis
Margin tightening in standard-grade geotextiles traces to polypropylene resin volatility and REACH-driven reformulation cycles in European coated fabric production. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10318-certified performance grades from uncertified commodity rolls. Price differentiation hinges on certification tier and volume scale, with highway concessionaires in Brazil and Mexico least price-sensitive due to 20-year performance guarantees, while cost-conscious contractors in India's road construction segment drive aggressive procurement negotiations.
Supply Chain Analysis
India's domestic-content mandates for NHAI highway projects are reshaping sourcing patterns toward Gujarat's petrochemical-integrated manufacturing corridor. Supply concentrates in India, Germany, and the United States, with raw material dependencies on polypropylene resin, polyester fiber, and UV stabilization chemistries. Single-source vulnerability sits with European ECHA authorization bottlenecks for flame retardant formulations. Distribution runs through direct mill relationships with infrastructure contractors and specialized geotechnical distributors serving design-engineer specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction textile supply is tightening around certified manufacturing capacity, with India's BIS testing queue extending 8-10 months and European reformulation cycles delaying product launches—structural bottlenecks that prop pricing for qualified suppliers.
For Market Incumbents: Anchor market position through backward integration into polymer production in Gujarat's petrochemical belt, capturing feedstock cost advantages against non-integrated converters. Defend against emerging biopolymer specialists by accelerating carbon-negative certification pathways under EU taxonomy rules. Prioritize capacity addition in India to exploit NHAI procurement localization mandates.
For New Entrants and Emerging Players: Begin with environmental protection applications in Europe, where EU Green Deal embodied carbon tracking creates specification white space for low-carbon geosynthetics. Target landfill liner and sediment containment segments where technical performance gaps in extreme pH environments limit incumbent penetration. Pursue go-to-market partnerships with automated installation equipment providers to bypass established distributor relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with coated fabric specialists possessing ECHA-compliant formulation libraries, given REACH authorization timelines extending 18-24 months as a scarcity catalyst. Long-term viability favors asset-light designers with performance-based maintenance contract expertise over capital-heavy commodity producers. Watch India's BIS certification backlog resolution as an inflection signal for domestic supply normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captures feedstock cost advantages in Gujarat's petrochemical corridor against resin-price volatility. |
| Smart Geosynthetic Sensor Integration | Enables real-time structural health monitoring for dam and landfill operators under performance contracts. |
| Biopolymer Feedstock Transition | Positions suppliers for carbon-negative certification under emerging EU taxonomy classification rules. |
| Automated Installation Equipment Partnership | Compresses project timelines and shifts contractor selection toward equipment-integrated material suppliers. |
| Performance-Based Maintenance Contract Expansion | Transfers 20-year durability risk to material suppliers in Brazil and Mexico highway concessions. |
Methodological Framework
Trade databases, BIS certification registries, and ECHA authorization filings formed the secondary backbone, cross-referenced with primary interviews spanning geotechnical engineering consultants, NHAI procurement officers, European coated fabric plant managers, and Brazilian highway concession operators. Bottom-up and top-down triangulation validated volume estimates against customs data and infrastructure tender disclosures.
Bottom-up modeling built from project-level geotextile specifications across highway, landfill, and mining applications, while top-down analysis anchored total addressable market against national infrastructure spending plans. Segmentation dimensions included product architecture, application context, fabrication technology, and end-user professional role. CAGRs derived from regression against historical procurement cycles and policy-mandated adoption timelines, with inputs from petrochemical feedstock price elasticity and certification queue duration assumptions.
Underlying measurement precision varies by segment; road construction volume estimates carry tighter precision than emerging environmental protection applications. Forecasts reflect assumptions around regulatory enforcement consistency and infrastructure budget execution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
High Temperature Fabric Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
US Geotextile Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Absorbent Cover Market
Technical Textiles
Agro Textiles Market