
 China Geotextiles Market | 2026-2036
China Geotextiles Market Size, Share, and Industry Trends Forecast 2026-2036
China Geotextiles Market Intelligence
A shift from imported virgin resin toward captive recycled-polymer sourcing is restructuring supply economics for domestic geotextile manufacturers. Shandong GEOSINO New Material Co., Ltd. leverages integrated PP granulation lines to control raw material variability across its non-woven lines. Feicheng Lianyi Engineering Plastics Co., Ltd. anchors its position through scale concentration in Taian City, where needle-punch capacity exceeds comparable clusters in Hebei or Jiangsu. Dalian GeoMax Synthetics Co., Ltd. competes on coastal logistics, shipping rolls directly to port-adjacent infrastructure sites in Liaoning and northern Shandong.
China geotextiles are permeable synthetic fabrics manufactured from polypropylene or polyester via needle-punching, weaving, or thermal bonding, with mass per unit area typically ranging from 100 to 1500 grams per square meter and tensile strength calibrated to CJJ/T 239 and GB/T 17639 specifications. These materials separate, filter, reinforce, protect, or drain soils in civil engineering and environmental containment applications. Non-woven geotextiles dominate volume due to lower unit cost and faster installation in road construction subgrade stabilization, while woven grades command margin premiums in mining tailings and landfill liner protection where creep resistance under load governs specification. Composite formats combining drainage cores with filtration layers are gaining specification share in coastal erosion control projects where single-product installation reduces labor hours.
China's Ministry of Ecology and Environment enforces GB standards for geosynthetics in environmental containment, while SAMR administers product quality certification that gates access to state-funded infrastructure tenders. The dual carbon goals are pushing MIIT to tighten energy-intensity benchmarks for polymer extrusion, favoring manufacturers with in-house recycling and combined heat-power systems. Stakeholders must monitor how provincial infrastructure bond allocations and MEE enforcement cycles at prefecture level reshape regional demand patterns and compliance costs.
Market Dynamics
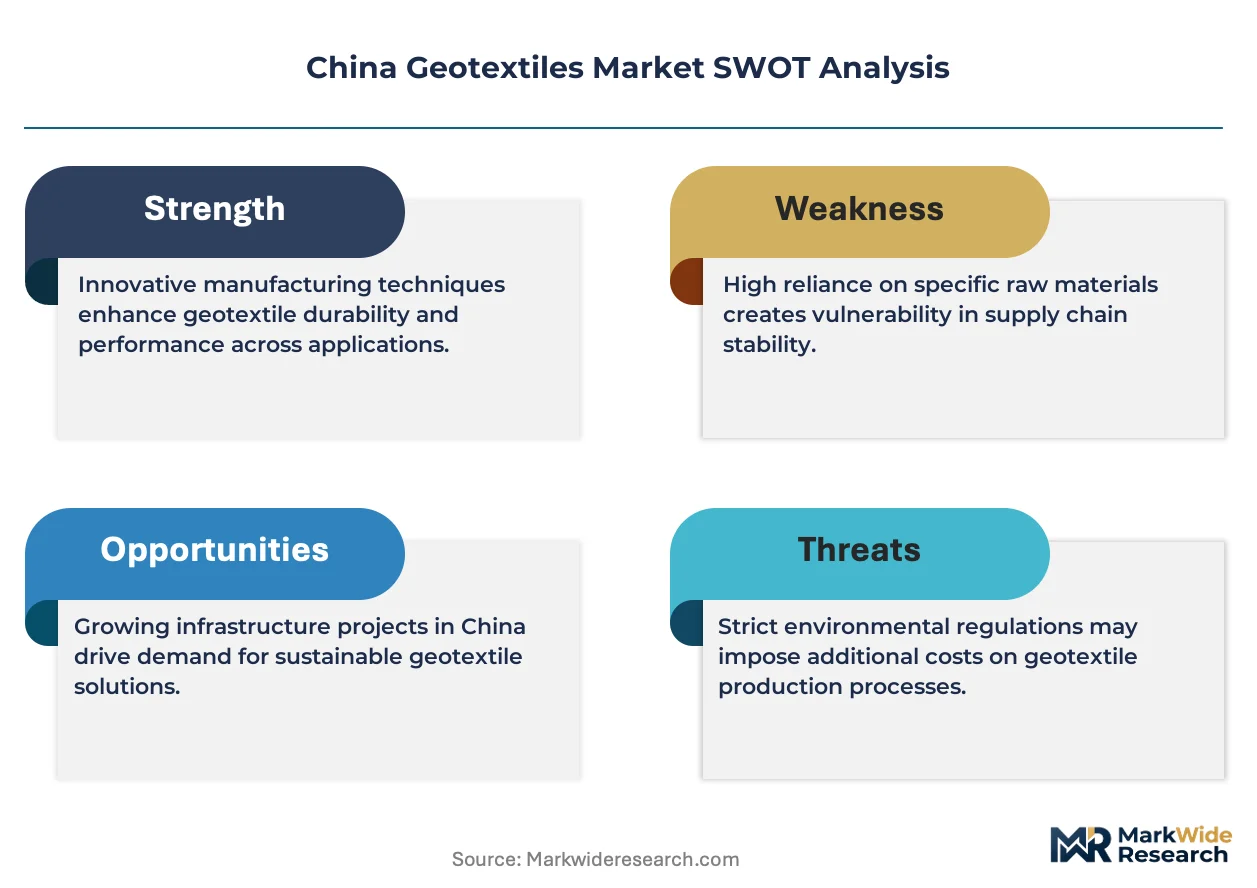
Shandong Province's clustering of extrusion and needle-punch capacity is restructuring competitive economics by compressing logistics costs and raw material access for domestic geotextile manufacturers serving eastern China's infrastructure corridor.
Growth Catalysts
- Dual carbon policy framework:MIIT's tightening energy-intensity benchmarks for polymer extrusion are accelerating manufacturer investment in combined heat-power systems and captive recycled-polymer sourcing.
- Highway subgrade stabilization:Provincial infrastructure bond allocations across Shandong, Jiangsu, and Zhejiang are channeling specification volume toward non-woven geotextiles for road construction applications.
- Coastal erosion control:Composite geotextile formats integrating drainage cores with filtration layers are capturing specification share in shoreline protection projects along the Bohai and Yellow Sea coasts.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings for virgin and recycled PP granules compress margin predictability for extrusion-dependent manufacturers without integrated granulation capacity.
- Shandong supply concentration:Overreliance on Taian City needle-punch clusters creates geographic vulnerability to regional logistics disruptions and prefecture-level environmental enforcement cycles.
- GB/T 17639 compliance friction:SAMR product quality certification requirements for state-funded tenders extend qualification timelines and raise working capital requirements for smaller extrusion lines.
Strategic Opportunities
- Western province penetration:Sichuan and Shaanxi infrastructure corridors remain undersupplied relative to eastern clusters, creating first-mover positioning for manufacturers with rail-logistics capabilities.
- Landfill liner specification:MEE enforcement of GB standards for environmental containment is elevating woven geotextile demand in mining tailings and hazardous waste facilities where creep resistance governs design.
- Recycled PET feedstock integration:Polyester geotextile lines with backward integration into bottle-flake recycling can capture dual carbon compliance premiums and MIIT incentive eligibility.
Industry Challenges
- Polymer processing expertise scarcity:Qualified technicians for extrusion die calibration and melt-blown non-woven formation command wage premiums that strain mid-cap manufacturer labor cost structures.
- Combined heat-power capex intensity:MIIT-mandated energy efficiency upgrades require seven-figure RMB investments that disadvantage unintegrated producers against Shandong's scaled clusters.
- Prefecture-level enforcement variability:MEE inspection cycles differ across Shandong, Jiangsu, and Hebei, complicating multi-site compliance planning for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Geotextiles Market |
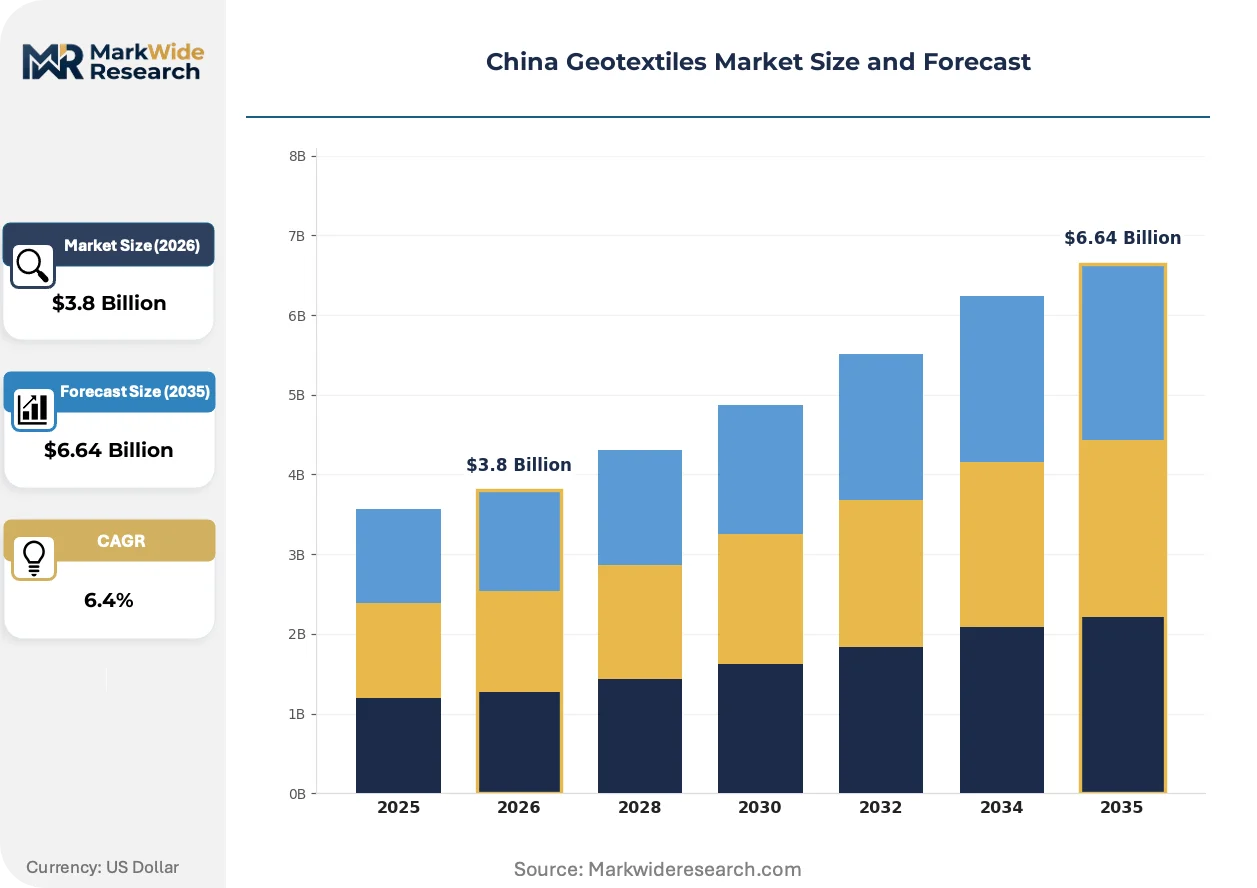
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Non-Woven, Woven, Knitted, Composite Application: Road Construction, Erosion Control, Landfill, Drainage End User: Infrastructure, Environmental, Agricultural, Mining Product Form: Rolls, Sheets, Geocells, Bags |
| Companies Covered | Dalian GeoMax Synthetics Co., Ltd., The Best Project Material Co., Ltd., Shandong GEOSINO New Material Co., Ltd., Huatong Geosynthetics, Shandong Hongxiang Geosynthetics, Feicheng Lianyi Engineering Plastics Co., Ltd., Shandong Xinyu Geosynthetics Engineering Co., Ltd., Xinyu Geosynthetics, GEOSINCERE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Geotextiles Market Strategic Shifts & Innovations
Recycled-polymer feedstock integration and composite product architectures are restructuring manufacturing investment priorities and specification patterns across China's geotextile value chain.
Multi-layer composite geotextiles combining high-strength woven substrates with non-woven filtration layers are electrifying product development pipelines for coastal erosion and landfill containment applications. Infrastructure contractors in Liaoning and northern Shandong are specifying these formats to reduce installation labor hours and seam failure risk. The technology is electrifying margin structures by commanding 15-25% price premiums over single-layer alternatives while compressing total project cost through faster deployment.
MIIT's implementation of granular energy-intensity benchmarks under the dual carbon goals is forcing extrusion line retrofits and captive recycling investments across Shandong and Jiangsu manufacturing bases. Manufacturers without combined heat-power systems face escalating compliance costs and tender disqualification risk for state-funded projects. Woven geotextile producers serving mining tailings applications are most affected, as polyester melt extrusion carries higher energy intensity than polypropylene needle-punch processes.
Direct mill-to-site distribution models are displacing traditional distributor intermediaries for large-scale highway and railway projects in eastern provinces. State-owned construction conglomerates in Shandong and Jiangsu are consolidating procurement through centralized tender platforms that favor manufacturers with rail-adjacent warehousing and roll-to-flatbed logistics capabilities. This pattern is most visible in Taian City, where Feicheng Lianyi and clustered competitors have reconfigured shipping operations to serve port-adjacent infrastructure sites without intermediate handling.
China Geotextiles Market Segmentation
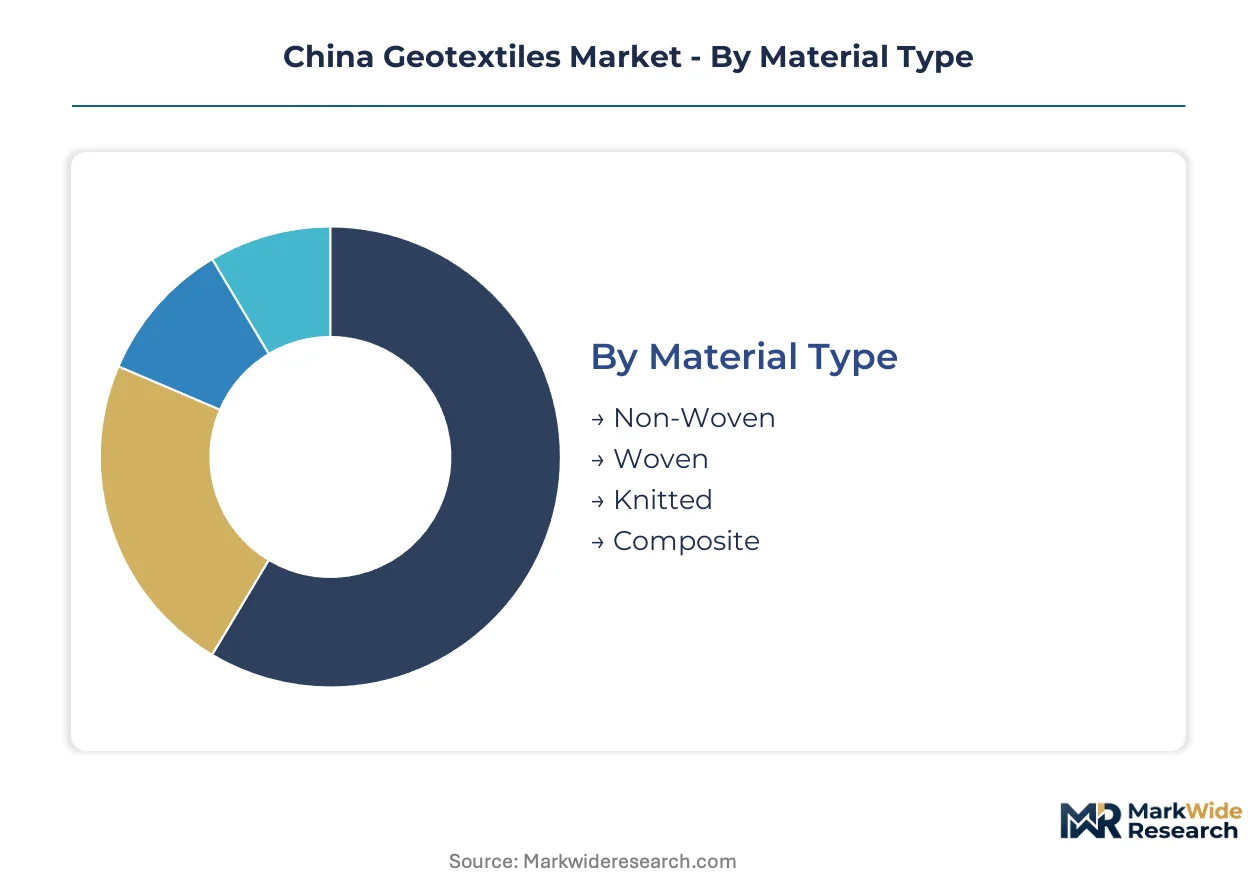
Geotextile specification in China diverges sharply between high-volume road construction and margin-intensive environmental containment. Material selection, product form, and end-user procurement patterns each create distinct competitive arenas with different certification requirements and logistics economics.
Material Type:
Volume concentration favors lower-unit-cost formats, while premium capture rests with engineered grades meeting GB/T 17639 creep-resistance specifications for mining and landfill applications.
- Non-Woven:Needle-punched polypropylene dominates tonnage through highway subgrade stabilization across Shandong and Jiangsu infrastructure corridors. Provincial bond allocations channel specification volume toward 200-600 gsm grades that separate and filter soils at lower installed cost than woven alternatives.
- Woven:High-tenacity polyester or polypropylene tapes deliver calibrated tensile strength for mining tailings and hazardous waste containment where load-bearing capacity governs design. MEE enforcement of environmental GB standards is elevating woven demand in landfill liner protection systems.
- Knitted:Biaxial or multiaxial yarn interlocking provides controlled elongation characteristics for steep slope reinforcement in Sichuan and Shaanxi railway embankments.
- Composite:Multi-layer architectures combining drainage cores with filtration layers command price premiums in Bohai Sea coastal erosion projects.
Mature deployment sits with Non-Woven grades. Newer deployment is concentrated in Composite formats integrating drainage and filtration functions.
Application:
Procurement concentration tracks provincial infrastructure bond flows and MEE enforcement intensity across eastern and northern provinces.
- Road Construction:Subgrade separation and stabilization consumes the largest specification volume through state-funded highway projects in Shandong, Jiangsu, and Zhejiang. Non-woven rolls deploy rapidly, reducing labor hours versus granular subbase alternatives.
- Erosion Control:Shoreline protection along the Yellow Sea and Bohai Sea coasts specifies composite geotextiles with integrated drainage cores to manage hydraulic pressure and prevent scour.
- Landfill:Hazardous waste and municipal solid waste facilities require woven geotextiles meeting stringent GB standards for creep resistance under vertical load.
- Drainage:Geocomposite drainage systems incorporating geotextile filtration layers serve tunnel waterproofing and building foundation applications in coastal cities.
Contractor procurement runs thickest through Road Construction. Regulatory pressure is expanding specification fastest across Landfill containment.
End User:
State-owned infrastructure conglomerates consolidate purchasing through centralized tender platforms, while environmental end-users demand certified compliance with MEE containment standards.
- Infrastructure:Highway and railway construction entities in eastern provinces specify non-woven grades through rail-adjacent warehousing arrangements that compress logistics costs.
- Environmental:Landfill operators and mining tailings managers procure woven and composite grades certified to GB/T 17639 for creep resistance and long-term dimensional stability.
- Agricultural:Greenhouse flooring and drainage applications in Shandong's horticulture belt consume lighter-weight non-woven sheets.
- Mining:Tailings dam construction in northern provinces specifies high-strength woven geotextiles for basal reinforcement and liner protection.
Established procurement patterns center on Infrastructure. Emerging specification growth clusters within Environmental containment driven by MEE enforcement cycles.
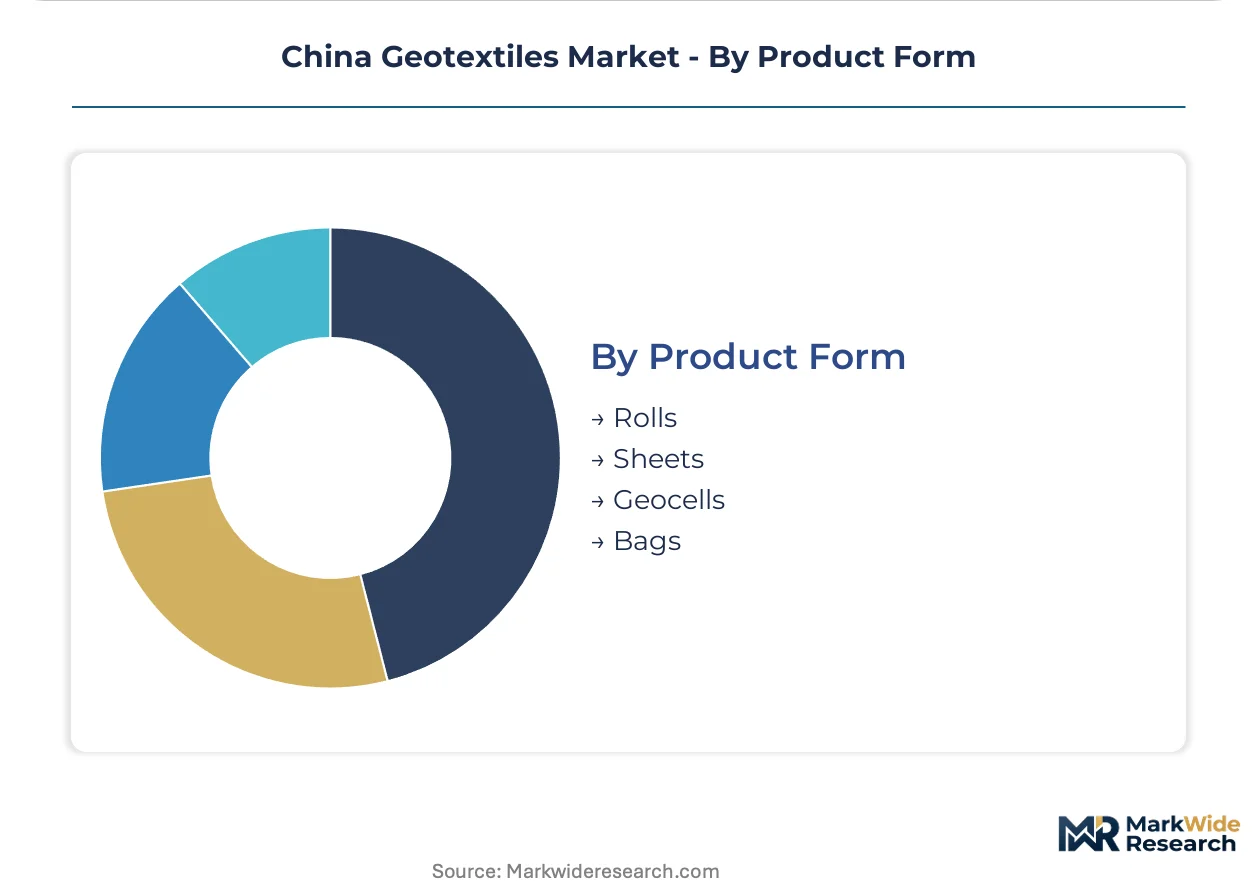
Product Form:
Logistics economics and installation mechanization determine form selection, with roll formats dominating large-scale projects and pre-fabricated cells serving specialized containment.
- Rolls:Standard widths of 4-6 meters enable mechanized deployment across highway subgrades and landfill basal liners. Direct mill-to-site distribution eliminates intermediate handling for Shandong and Jiangsu projects.
- Sheets:Pre-cut dimensions serve smaller agricultural drainage and building foundation applications where on-site fabrication is uneconomical.
- Geocells:Three-dimensional honeycomb structures confine infill materials for steep slope stabilization and load support in railway embankments.
- Bags:Sand-filled geotextile containers construct breakwaters and groins for coastal protection projects along the Bohai Sea rim.
Roll formats command the deepest procurement integration. Geocells represent the steepest expansion trajectory as western province railway construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin supply from Shandong's petrochemical corridor anchors geotextile manufacturing geography across eastern China. Provincial infrastructure bond flows and MEE enforcement intensity reshape demand patterns along coastal and western corridors.
Shandong Province
Highway subgrade stabilization and coastal erosion projects consume the largest specification volume through state-funded tenders. MIIT energy-intensity benchmarks under dual carbon goals accelerate manufacturer investment in combined heat-power systems. Taian City needle-punch clusters concentrate extrusion capacity, giving domestic suppliers logistics advantages for eastern infrastructure corridors.
Jiangsu Province
Railway embankment reinforcement and landfill containment drive woven and composite geotextile demand. SAMR product quality certification gates access to provincial infrastructure tenders, extending qualification timelines for unintegrated producers. Suzhou and Nantong manufacturing bases serve Yangtze River Delta construction sites through rail-adjacent warehousing arrangements.
Zhejiang Province
Port-adjacent infrastructure and tunnel waterproofing applications specify non-woven grades for rapid deployment. Provincial environmental enforcement cycles elevate woven demand in hazardous waste facilities where GB/T 17639 creep resistance governs design. Ningbo and Hangzhou procurement platforms consolidate purchasing through centralized tender systems.
Liaoning Province
Mining tailings dam construction and Bohai Sea shoreline protection anchor high-strength woven and composite specifications. MEE enforcement of geosynthetics standards in environmental containment elevates certified product demand. Dalian coastal logistics clusters enable direct mill-to-site distribution for port-adjacent infrastructure sites.
Sichuan-Chongqing Corridor
Steep slope railway embankments and western infrastructure expansion create undersupplied demand relative to eastern clusters. Prefecture-level bond allocations channel specification toward geocell and biaxial knitted formats for load support applications. Chengdu-based distributors face higher logistics costs sourcing from Shandong manufacturing bases.
China Geotextiles Market Key Industry Players
Capacity expansion dominates the current landscape as Shandong-based manufacturers scale needle-punch and extrusion lines to capture provincial infrastructure bond flows. The vendor base concentrates geographically around Taian City clusters, with mid-cap specialists and state-affiliated construction material divisions occupying distinct competitive tiers. Strategic archetypes include integrated resin-to-fabric producers, coastal logistics specialists, and western corridor distributors. Competitive moves center on captive recycled-polymer sourcing and direct mill-to-site distribution partnerships with state-owned construction conglomerates.
Among Shandong-based integrated manufacturers, Shandong GEOSINO New Material Co., Ltd. and Feicheng Lianyi Engineering Plastics Co., Ltd. exemplify the scale-driven archetype with clustered production capacity. Dalian GeoMax Synthetics Co., Ltd. represents coastal logistics positioning for northern corridor access. These companies occupy positions within a tiered structure where geographic concentration and backward integration into polymer granulation separate cost-competitive suppliers from distribution-dependent competitors.
| Leading Market Players |
|---|
| Dalian GeoMax Synthetics Co., Ltd. |
| The Best Project Material Co., Ltd. |
| Shandong GEOSINO New Material Co., Ltd. |
| Huatong Geosynthetics |
| Shandong Hongxiang Geosynthetics |
| Feicheng Lianyi Engineering Plastics Co., Ltd. |
| Shandong Xinyu Geosynthetics Engineering Co., Ltd. |
| Xinyu Geosynthetics |
| GEOSINCERE |
| Others |
Cost & Logistics Intelligence
Polypropylene resin feedstock costs cascade through three pricing tiers determined by certification grade and volume commitment, with Shandong-based integrated manufacturers capturing margin premiums over distribution-dependent competitors serving state-funded infrastructure tenders.
Pricing Analysis
Warranty-backed installation support and SAMR certification documentation are unbundled from base roll pricing, creating three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to GB/T 17639-certified woven grades for mining tailings applications, while economy tiers serve agricultural drainage with minimal compliance documentation. Price differentiation hinges on dual carbon compliance premiums and rail-adjacent delivery guarantees. Cost compression in standard non-woven grades is intensifying because provincial tender platforms consolidate procurement volume. State-owned construction conglomerates exhibit lowest price sensitivity; mid-cap distributors face margin erosion from working capital requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from state-funded infrastructure tenders force buyers to maintain approved supplier lists across Shandong, Jiangsu, and Hebei manufacturing clusters. Geographic supply concentration centers on Taian City needle-punch capacity, Nantong extrusion bases, and Dalian coastal logistics hubs. Raw material dependencies draw from virgin PP granule suppliers, captive recycled-polymer processors, and polyester melt providers. Single-source vulnerability concentrates in Shandong's petrochemical corridor where environmental enforcement cycles disrupt resin availability. Distribution runs through direct mill-to-site arrangements with rail-adjacent warehousing, displacing traditional distributor intermediaries for large-scale highway projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT energy-intensity benchmarks under dual carbon goals are accelerating manufacturer consolidation, forcing unintegrated extrusion lines into acquisition targets or exit.
For Market Incumbents: Cement market position through backward integration into captive recycled-polymer granulation and combined heat-power system deployment. Scale needle-punch capacity in Taian City clusters to compress logistics costs against Hebei competitors. Defend against mid-cap specialists by locking rail-adjacent warehousing partnerships with state-owned construction conglomerates. For New Entrants and Emerging Players: Begin with undersupplied Sichuan-Chongqing railway corridors where geocell demand outpaces Shandong manufacturing reach. Target landfill liner protection applications where MEE enforcement elevates woven geotextile specifications above commodity non-woven competition. Pursue technical partnership routes with provincial environmental engineering firms lacking certified geosynthetics sourcing. For Investors and Strategic Acquirers: SAMR certification backlog expansion is the leading indicator that qualification timelines will extend working capital requirements beyond unintegrated producer capacity. Five-to-ten year viability favors manufacturers with in-house recycling and combined heat-power infrastructure. Acquisition targets cluster around mid-cap extrusion lines in Jiangsu with partial backward integration. Monitor prefecture-level MEE enforcement intensity as the signal for regional supply disruption and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycled-Polymer Integration | MIIT dual carbon compliance secures state tender eligibility and margin protection against resin volatility. |
| Rail-Adjacent Warehousing Expansion | Direct mill-to-site distribution captures provincial infrastructure bond flows from centralized procurement platforms. |
| Combined Heat-Power System Deployment | Energy-intensity benchmark adherence qualifies manufacturers for premium-tier environmental project specifications. |
| Western Province Logistics Partnership | Sichuan-Chongqing corridor access offsets Shandong supply concentration risk with first-mover positioning. |
| Multi-Layer Composite Product Development | Drainage-filtration integration commands price premiums in Bohai Sea coastal erosion control tenders. |
Research Approach
Multi-period observation of provincial infrastructure bond allocations, MEE enforcement cycles, and manufacturer capacity utilization anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Jiangsu extrusion facilities, procurement leads at state-owned construction conglomerates, technical R&D directors for composite geotextile development, and distribution channel partners serving western provinces. Secondary validation drew from MIIT energy-intensity disclosures, SAMR product certification registries, customs trade data for PP resin flows, and provincial tender platform award records. Bottom-up manufacturing capacity estimates triangulated against top-down infrastructure spending projections.
Segment-weighting across material type, application, and end-user dimensions shaped the analytical framework over the projection horizon. Non-woven, woven, knitted, and composite formats were modeled separately with distinct energy-intensity and certification cost assumptions. Road construction, erosion control, landfill, and drainage applications carried varying tender platform concentration and logistics economics. CAGRs were derived from infrastructure bond flow trajectories and polymer feedstock cost curve expectations. Forecast inputs included MIIT dual carbon policy implementation pace and prefecture-level MEE staffing expansion.
Resin price volatility, enforcement cycle intensity, and provincial bond allocation shifts are the dominant revision risks to the outlook. Deviation in MIIT energy-intensity benchmark stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Absorbent Cover Market
Technical Textiles
US Geotextile Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Smart Sports Textile Market
Technical Textiles
Construction Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Smart Fabrics for Transportation Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Global Agricultural Textiles Market
Technical Textiles
Military Textile Materials Testing Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Smart Fabrics for Sports and Fitness Market