
 Global Geotextile Market | 2026-2036
Global Geotextile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geotextile Market Analysis
Geotextile distribution through civil engineering procurement consortia is tilting toward specification-driven bundling with complementary geosynthetics. Koninklijke Ten Cate leverages its vertical integration across fiber production and finished fabric to sustain margin control in European infrastructure tenders. NAUE GmbH & Co. KG anchors its position through deep specialization in high-strength woven systems for railway embankment reinforcement.
Geotextiles are permeable textile materials manufactured from polypropylene or polyester fibers through needle-punching, weaving, or heat-bonding processes, engineered to perform separation, filtration, drainage, or reinforcement functions when interfacing with soil structures. Their primary commercial purpose centers on extending infrastructure service life while reducing aggregate thickness requirements in roadbase and landfill liner systems. Non-woven geotextiles dominate volume consumption in drainage and filtration applications where puncture resistance and hydraulic conductivity govern specification, while woven products command premium positioning in reinforcement scenarios demanding high tensile modulus. Material-grade polypropylene leads cost-sensitive segments, though polyester gains ground in alkaline soil environments and long-term creep-sensitive installations.
Federal Highway Administration specifications, EN 13249-13257 harmonized standards under CE marking, and ISO 10319 tensile testing protocols collectively shape product qualification barriers and cross-border market access for geotextile manufacturers. The EU Green Deal's embedded carbon disclosure requirements through CSRD reporting are redirecting procurement criteria toward recycled-content and lower-embodied-carbon fabric alternatives. Stakeholders must monitor evolving polymer feedstock volatility and anticipate specification divergence between resilience-focused infrastructure codes and circular-economy material mandates.
Market Dynamics
Infrastructure resilience mandates embedded in the EU Green Deal are compressing specification cycles for geosynthetic materials, forcing manufacturers to requalify products against stricter carbon-disclosure thresholds while road authorities in emerging economies simultaneously expand subgrade stabilization requirements.
Growth Catalysts
- Railway embankment reinforcement:High-strength woven systems are displacing conventional soil nailing in European track renewal programs governed by EN 13249 standards.
- India's National Highway Development:Federal budget allocations prioritize geosynthetic-reinforced pavement layers across corridor expansion zones.
- CSRD reporting mandates:Embedded carbon disclosure requirements redirect procurement criteria toward recycled-content fabric alternatives.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings compress margin stability for cost-sensitive non-woven producers.
- Alkaline soil compatibility gaps:Material-grade polypropylene suffers hydrolysis degradation in high-pH environments, limiting landfill liner service life.
- Specification divergence:Tension between ISO 10319 tensile testing protocols and emerging circular-economy material mandates creates qualification friction.
Strategic Opportunities
- Brazilian infrastructure gaps:Underpenetrated roadbase stabilization demand in the country's northeast corridor offers white-space expansion.
- Heat-bonding convergence:Integration of thermal bonding with needle-punching processes enables thinner drainage composites with equivalent hydraulic conductivity.
- Direct-to-consortium distribution:Bypassing traditional distributor layers through civil engineering procurement consortia captures specification influence earlier in project timelines.
Industry Challenges
- Polymer characterization expertise:Shortage of technicians skilled in long-term creep testing under ISO 13431 protocols delays product validation cycles.
- Multi-standard compliance:Simultaneous adherence to FHWA specifications, CE marking under EN 13249-13257, and site-specific owner-engineer requirements fragments quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geotextile Market |
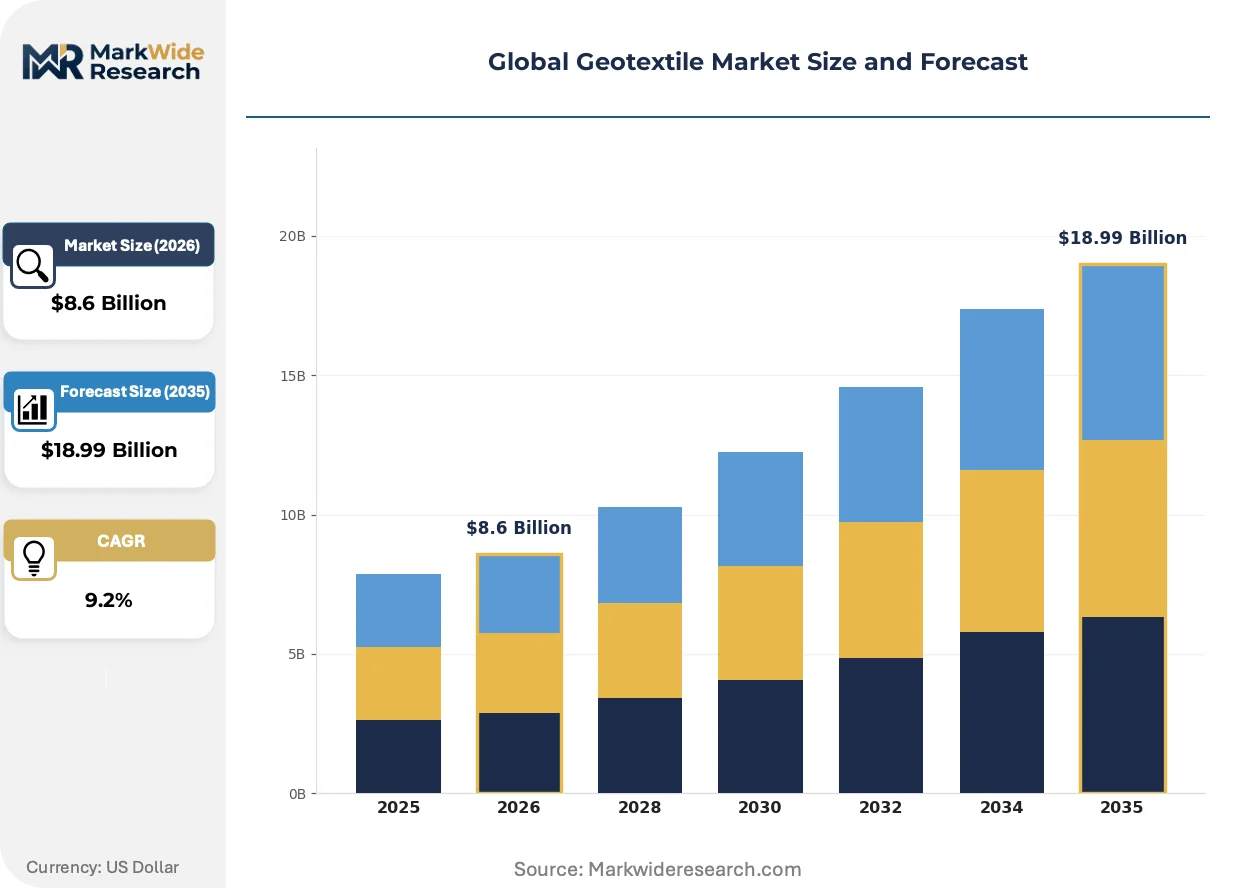
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $18.99 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
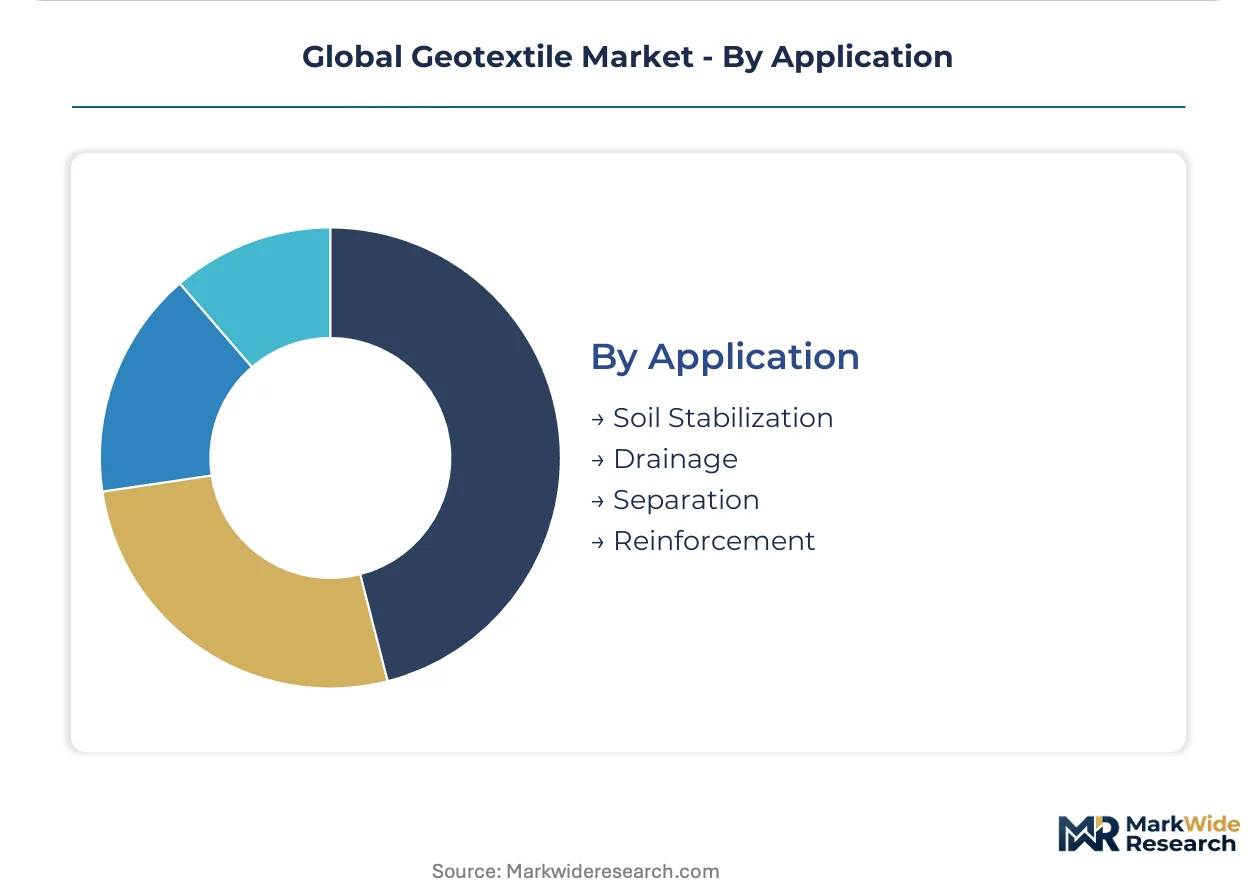
| Segmentation | Product Type: Woven, Non-Woven, Knitted, Hybrid End Use: Transportation, Landfill, Erosion Control, Agriculture Material: Polypropylene, Polyester, Natural Fibers, Geosynthetics Application: Soil Stabilization, Drainage, Separation, Reinforcement |
| Companies Covered | Koninklijke Ten Cate, NAUE GmbH & Co. KG, Officine Maccaferri, Fibertex Nonwovens, GSE Holdings, Low and Bonar, Berry Global, HUESKER Group, Propex Operating Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geotextile Market Emerging Trajectories
Specification-driven bundling with complementary geosynthetics is compressing standalone geotextile procurement, while carbon-accounting pressures and digital quality assurance are reshaping how fabric performance is verified and valued across infrastructure tenders.
Smart geotextiles embedded with fiber-optic strain sensors are digitizing real-time deformation monitoring in railway embankments and landfill slopes. European track operators are piloting these systems in Germany and France for early warning of subgrade settlement. The technology is digitizing predictive maintenance contracts, shifting contractor liability models from periodic inspection to continuous performance guarantees.
The EU Green Deal's CSRD disclosure framework is forcing infrastructure owners to document embodied carbon across geosynthetic supply chains. Project developers in the Netherlands and Denmark now require Environmental Product Declarations for geotextile bids. Polyester recyclate feedstocks are gaining specification share in these markets despite 15-20% tensile modulus trade-offs versus virgin polymer.
Engineering-procurement-consortium frameworks are consolidating buyer power across India's National Highway Development corridors. State road authorities in Maharashtra and Karnataka now bundle geotextile specification with geogrid and drainage composite awards. This concentration is squeezing standalone distributors and rewarding manufacturers with integrated geosynthetic portfolios capable of single-source infrastructure packages.
Global Geotextile Market Segmentation
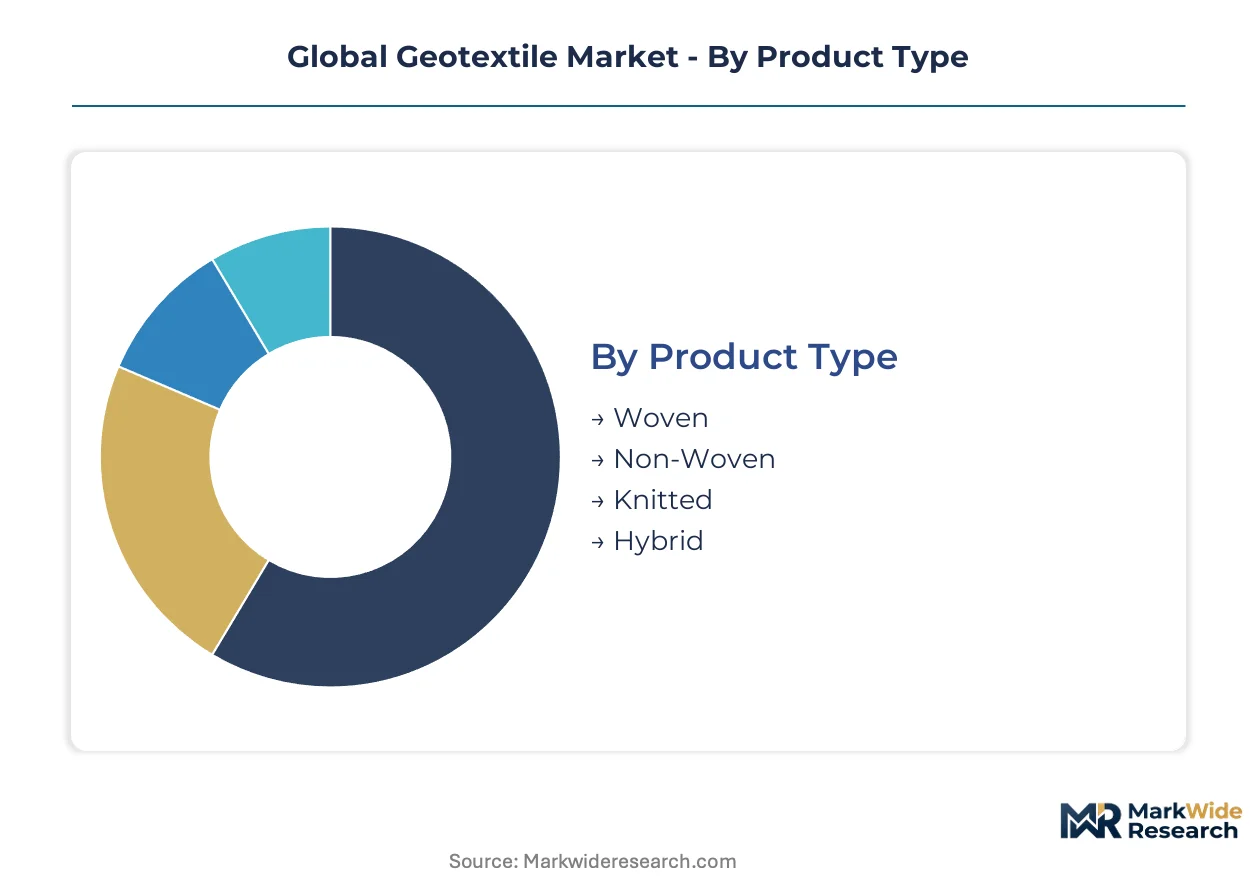
Geotextile procurement decisions hinge on matching fabric architecture to specific soil-structure interactions. Specification engineers weigh hydraulic conductivity against tensile modulus across distinct product categories, material grades, and functional applications.
Product Type:
Needle-punching, weaving, and heat-bonding processes create divergent performance profiles across the use-case spectrum.
- Non-Woven:Manufactured through needle-punching or thermal bonding of polypropylene or polyester staple fibers. Filtration and drainage specifications in European landfill liner systems under ECHA guidance concentrate demand here, though puncture resistance requirements limit load-bearing deployment.
- Woven:Produced via interlacing monofilament or multifilament yarns to achieve high tensile modulus. Railway embankment reinforcement across Germany and France favors these systems for creep resistance under EN 13249 protocols.
- Knitted:Formed through interlocking loop structures that permit multidirectional stretch. Geogrid composite applications in Indian highway corridors utilize knitted substrates for flexibility during thermal cycling.
- Hybrid:Combines woven strength members with non-woven drainage layers in laminated configurations. Composite landfill caps in the Netherlands specify these for simultaneous filtration and reinforcement.
Established volume favors Non-Woven; emerging adoption favors Hybrid.
End Use:
Cost tier differentiation separates infrastructure-grade specifications from environmental containment priorities.
- Transportation:Roadbase stabilization and railway subgrade reinforcement consume high-strength woven systems. India's National Highway Development corridors drive specification bundling with geogrids under federal procurement frameworks.
- Landfill:Composite liner systems demand puncture-resistant non-woven protection layers. EU Green Deal carbon disclosure through CSRD reporting redirects Dutch and Danish tenders toward recycled-content alternatives.
- Erosion Control:Biodegradable natural fiber mats stabilize slopes until vegetation establishes. Coastal protection schemes in Brazil's northeast corridor underutilize these relative to hard armor alternatives.
- Agriculture:Ground cover and greenhouse climate management utilize UV-stabilized polypropylene. Subsurface drainage in high-value crop zones concentrates demand in California's Central Valley and Almería, Spain.
Transportation commands premium pricing; Landfill faces margin compression from circular-economy mandates.
Material:
Supply concentration around polymer feedstock sources shapes geographic manufacturing footprints.
- Polypropylene:Dominates cost-sensitive volume applications through material-grade resin availability. Propylene monomer price volatility from Gulf Coast petrochemical complexes destabilizes margin structures for non-woven producers.
- Polyester:Virgin and recyclate grades gain share in alkaline soil environments and long-term creep-sensitive installations. Recycled PET feedstocks trade 15-20% tensile modulus penalties for embodied carbon reductions under Dutch EPD requirements.
- Natural Fibers:Jute and coir provide temporary erosion control with biodegradation timelines aligned to vegetation establishment. Indian domestic supply chains support cost-competitive deployment in rural road projects.
- Geosynthetics:Encompasses polymer-based geogrids and geomembranes bundled with geotextile specifications. Engineering-procurement consortia in Maharashtra and Karnataka consolidate these into single-source infrastructure packages.
Polypropylene retains volume leadership; Polyester climbs the fastest on sustainability-linked procurement.
Application:
Customer type separation distinguishes owner-engineer specifications from contractor-driven value engineering.
- Soil Stabilization:Separation and filtration functions extend pavement service life while reducing aggregate thickness. Federal Highway Administration specifications govern US state road authority procurement.
- Drainage:Hydraulic conductivity requirements dictate non-woven fabric selection for landfill leachate collection. Heat-bonding convergence with needle-punching enables thinner composites with equivalent flow rates.
- Separation:Prevents intermixing of dissimilar soil layers in roadbase construction. ISO 10319 tensile testing protocols qualify products for cross-border market access.
- Reinforcement:High-strength woven systems mobilize soil tensile capacity in steepened slopes and retaining structures. EN 13249-13257 harmonized standards under CE marking shape European railway embankment specifications.
Reinforcement captures specification premiums; Drainage faces commoditization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's infrastructure resilience mandates anchor European demand, while India's National Highway Development corridors and Brazil's underpenetrated northeast drive emerging economy expansion. Federal procurement frameworks in each geography redirect specification criteria toward carbon-accounting compliance and bundled geosynthetic sourcing.
Germany
Railway embankment reinforcement and landfill liner upgrades consume high-strength woven systems. EN 13249-13257 harmonized standards under CE marking govern product qualification for track renewal programs. The Ruhr industrial cluster concentrates needle-punching capacity serving Dutch and Danish export markets.
India
Federal budget allocations prioritize geosynthetic-reinforced pavement layers across corridor expansion zones. BIS certification requirements and state-level engineering-procurement consortia consolidate buyer power. Maharashtra and Karnataka bundle geotextile specification with geogrid awards through single-source infrastructure packages.
United States
Federal Highway Administration specifications govern state road authority procurement for soil stabilization and drainage applications. Propylene monomer price volatility from Gulf Coast petrochemical complexes destabilizes margin structures for domestic non-woven producers. The Southeast corridor concentrates demand for subgrade stabilization in interstate rehabilitation projects.
Brazil
Underpenetrated roadbase stabilization demand in the northeast corridor offers white-space expansion for drainage and filtration applications. ANVISA environmental containment standards and state-level infrastructure gaps create specification lag versus European benchmarks. São Paulo-based distributors currently dominate import channels for woven reinforcement systems.
Netherlands
CSRD reporting mandates redirect procurement criteria toward recycled-content fabric alternatives with Environmental Product Declaration requirements. Composite landfill caps specify hybrid configurations combining woven strength members with non-woven drainage layers. The Port of Rotterdam cluster serves as a distribution hub for Belgian and German infrastructure tenders.
Global Geotextile Market Vendor Landscape
Polymer-grade specialists and integrated geosynthetic fabricators split the market into technology-tiered competitive bands. The vendor base concentrates around manufacturers with captive fiber production or deep specification influence in civil engineering procurement consortia. Three archetypes dominate: vertically integrated fiber-to-fabric producers, high-strength woven specialists, and diversified geosynthetic portfolio suppliers. Competitive moves center on backward integration into polymer feedstock sourcing and direct-to-consortium distribution bypassing traditional distributor layers.
Among European integrated producers, Koninklijke Ten Cate exemplifies the fiber-to-fabric archetype through upstream control over polypropylene and polyester staple production. NAUE GmbH & Co. KG occupies a position within the high-strength woven tier, anchoring specialization in railway embankment reinforcement systems. Fibertex Nonwovens represents the Scandinavian non-woven concentration, sitting within the drainage and filtration specification band serving landfill and environmental containment applications.
| Leading Market Players |
|---|
| Koninklijke Ten Cate |
| NAUE GmbH & Co. KG |
| Officine Maccaferri |
| Fibertex Nonwovens |
| GSE Holdings |
| Low and Bonar |
| Berry Global |
| HUESKER Group |
| Propex Operating Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Asian polypropylene staple fiber production compresses margin structures for European and North American non-woven geotextile manufacturers, forcing utilization-driven discipline that rewards backward integration into captive polymer supply and punishes merchant-market dependence.
Pricing Analysis
Geographic price spreads of 12-18% separate Indian domestic tenders from European infrastructure awards, reflecting freight differentials and certification burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10319 tensile grade and CE marking tier, with virgin polyester commanding premiums over recycled-content alternatives. Cost compression in standard-grade non-woven segments intensifies because of propylene monomer volatility from Gulf Coast complexes. State road authorities in emerging economies exhibit highest price sensitivity, while Dutch and Danish landfill operators absorb premiums for EPD-documented carbon performance.
Supply Chain Analysis
Upstream polypropylene and polyester staple fiber production concentrates in China, India, and the US Gulf Coast, with European fabricators drawing 60-70% of raw material from these sources. Geotextile manufacturing rests on propylene monomer, PET chip, and UV stabilizer inputs, each exposing producers to commodity cycle amplitude. Single-source vulnerability in high-tenacity polyester yarn for railway reinforcement applications creates qualification risk for EN 13249-certified systems. Distribution runs through civil engineering procurement consortia in India and Germany, bypassing traditional distributor layers and compressing margin capture for standalone traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geotextile market operates as a substitution defense against soil nailing, concrete facing, and conventional aggregate-thickening methods that retain specification share in cost-driven procurement environments. Incumbents must navigate displacement risk from competing ground improvement technologies while embedding carbon-accounting compliance into product positioning.
For Market Incumbents: Entrench specification influence through captive fiber production and early-stage consortium engagement in India's National Highway Development corridors. Secure EN 13249-13257 requalification cycles ahead of CSRD carbon-disclosure thresholds. Counter polymer feedstock volatility through long-term propylene offtake agreements with Gulf Coast complexes. For New Entrants and Emerging Players: Pursue white-space expansion in Brazil's northeast corridor roadbase stabilization, where ANVISA environmental standards lag European benchmarks and distributor channels remain fragmented. Target hybrid geotextile-geogrid bundling opportunities in Maharashtra and Karnataka state procurement frameworks. Lead with recycled-content polyester positioning to capture Dutch and Danish EPD-mandated tenders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification bundling and carbon-accounting compliance are compressing standalone distributor viability and rewarding integrated geosynthetic portfolios. Acquire mid-cap woven specialists with EN 13249 certification depth and Indian BIS accreditation. Monitor CSRD reporting adoption rates across EU infrastructure owners as inflection signal for recycled-content demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Gulf Coast propylene offtake agreements insulate margin structures from monomer volatility. |
| CSRD Compliance Certification | Environmental Product Declaration capability unlocks Dutch and Danish landfill tender participation. |
| Railway Embankment Specialization | EN 13249-13257 qualification anchors premium positioning in German and French track renewal programs. |
| Consortium Direct Distribution | Bypassing distributor layers captures specification influence in Maharashtra and Karnataka state frameworks. |
| Recycled-Content Scale-Up | Recycled PET feedstock investment aligns procurement criteria with EU Green Deal circular-economy mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with civil engineering procurement consortium managers, state road authority specification engineers, polymer feedstock procurement leads, and geosynthetic product technical directors. Secondary validation drew from FHWA specification databases, EN 13249-13257 harmonized standard filings, BIS certification registries, and customs trade data for polypropylene and polyester staple fiber flows. Bottom-up segment sizing triangulated against top-down infrastructure spending forecasts across the analysis window.
Calibration against historical volume-price relationships in polypropylene non-woven and polyester woven categories anchored the analytical framework. Segmentation dimensions modeled encompass product architecture, material grade, functional application, and regional regulatory cluster throughout the forecast period. CAGRs derived from infrastructure investment trajectories, specification upgrade cycles, and polymer feedstock cost curve projections. Railway embankment reinforcement intensity and landfill liner replacement schedules served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in infrastructure budget allocations, propylene monomer pricing, or EU carbon-border adjustment implementation would shift the trajectory. Cross-checking against EPC contractor order backlogs and state-level tender award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Webbing Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Global Cooling Fabric Market
Technical Textiles
Construction Textile Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Absorbent Cover Market