
 Active Smart Textiles Market | 2026-2036
Active Smart Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Active Smart Textiles Market Insights
Performance-grade fabric certification is redrawing competitive boundaries in active smart textiles. DuPont leverages its polymer science heritage to supply advanced conductive fibers that anchor premium intelligent fabric lines. Gentherm competes through thermal regulation expertise that extends into heated wearable segments for military and medical end users. Nike dominates brand-driven consumer adoption by integrating Sensoria's biometric sole technology into connected athletic footwear.
Active smart textiles are engineered materials that embed electronic components, conductive yarns, or micro-sensors directly into fabric substrates to enable real-time data capture, energy transfer, or environmental responsiveness. These systems typically incorporate silver-coated nylon circuits, printed graphene traces, or conductive polymer blends to achieve signal fidelity while maintaining washability and tensile performance comparable to conventional technical apparel. Sports applications lead volume consumption as professional teams and amateur athletes demand continuous physiological feedback during training and competition. Healthcare represents the fastest-expanding segment, where remote patient monitoring applications are pulling intelligent fabrics and embedded biometric sensors into chronic disease management protocols.
FDA clearance requirements for wearable medical devices are elevating development costs but simultaneously creating market access barriers that favor established suppliers with regulatory infrastructure. The EU MDR and REACH chemical compliance frameworks are reshaping material selection across the value chain, pushing manufacturers toward halogen-free conductive coatings and recyclable substrate alternatives. Stakeholders must monitor convergence between consumer fitness wearables and regulated medical devices, as classification ambiguity threatens to delay commercialization timelines for products positioned at this boundary.
Market Dynamics
EU MDR compliance deadlines are compressing development cycles for wearable health fabrics, forcing manufacturers to revalidate conductive coating chemistries and biocompatibility profiles ahead of notified body audits.
Growth Catalysts
- Remote patient monitoring protocols:Veterans Affairs programs in the United States are standardizing biometric garment procurement for post-operative recovery tracking, creating institutional demand pull.
- REACH-compliant conductive polymers:Halogen-free silver-nylon hybrids are replacing legacy halogenated coatings in EU-bound production lines, opening substitution-led volume expansion.
- Military thermal regulation contracts:Heated wearable segments are absorbing advanced fabric output as defense procurement prioritizes soldier physiological management systems.
Market Restraints
- Silver price volatility:Conductive yarn feedstock costs fluctuate with precious metals markets, compressing margin stability for mid-tier fabric processors.
- FDA 510(k) backlog:Wearable medical device clearances face extended review timelines, freezing commercialization for products crossing the wellness-medical boundary.
- Polymer substrate concentration:Advanced conductive fiber supply clusters in German and Japanese chemical corridors, creating geographic single-source exposure.
Strategic Opportunities
- Chronic disease management expansion:Diabetes and cardiovascular protocols in India are piloting intelligent fabric integration, opening volume scale in price-sensitive healthcare systems.
- GB standard harmonization:China's NMPA is aligning wearable medical device classifications with ISO frameworks, reducing dual-certification burden for export-oriented suppliers.
- Athletic footwear biometric convergence:Sensor-embedded sole-fabric systems are pulling textile-electronics integration into performance apparel adjacent categories.
Industry Challenges
- Wash-cycle durability validation:Conductive trace integrity after industrial laundering remains unstandardized, forcing proprietary test protocol development per OEM.
- Cross-functional talent scarcity:Textile engineering and embedded systems expertise rarely co-reside in single hires, inflating R&D team assembly costs.
- Biocompatibility certification timelines:ISO 10993 testing sequences for skin-contact wearables extend 14-18 months, delaying revenue recognition for novel material introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Smart Textiles Market |
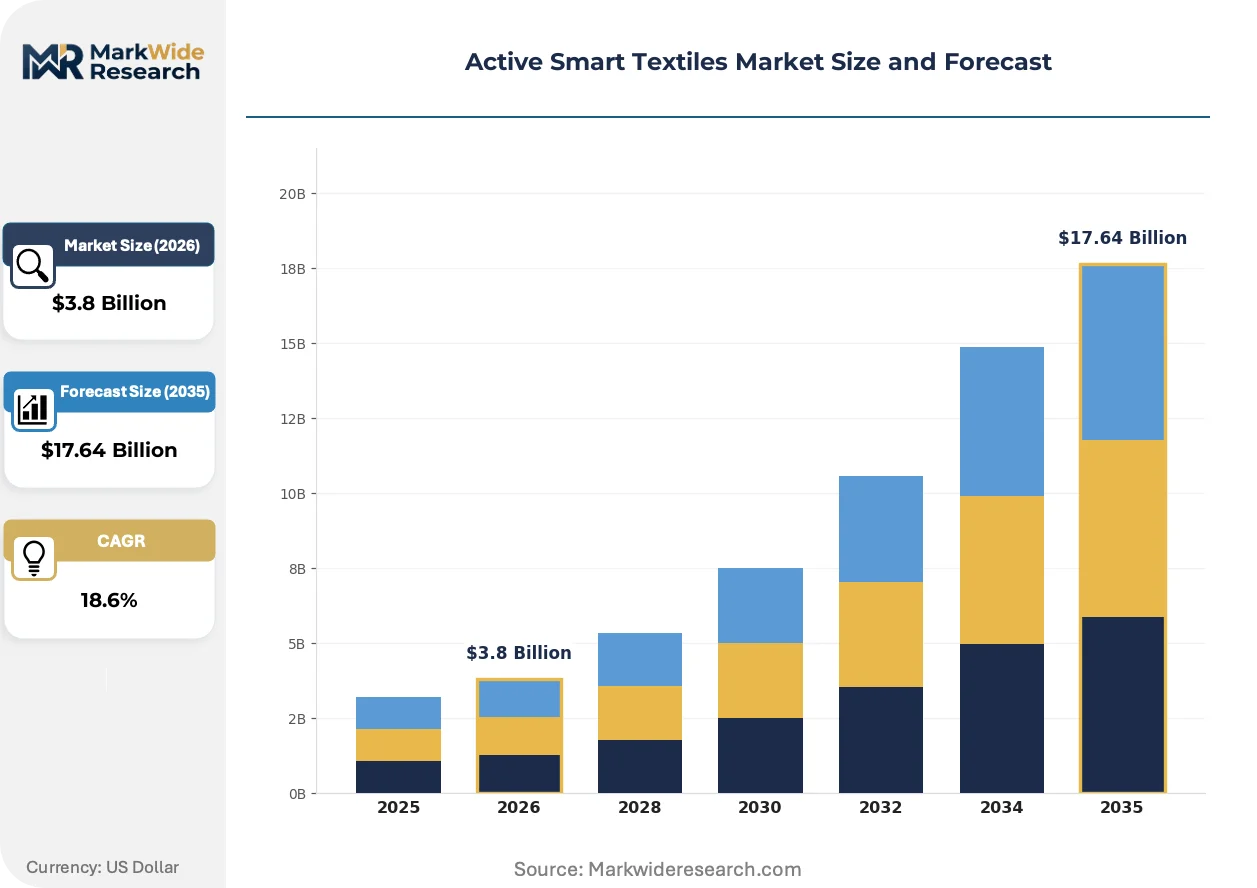
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Intelligent Fabrics, E-Textiles, Sensors Application: Sports, Healthcare, Fashion, Military Technology: Bluetooth, NFC, RFID, Biometric Monitoring End User: Athletes, Patients, Fashion Designers, Military Personnel |
| Companies Covered | DuPont, Jabil Inc., Gentherm, AiQ Smart Clothing, Sensoria, Nike, Adidas, Hexoskin, Clothing+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Smart Textiles Market Trends and Innovations
Printed graphene traces are displacing woven conductive yarns as the dominant signal pathway architecture, compressing manufacturing complexity while preserving stretchability. This materials transition is reshaping capital allocation across substrate processing equipment.
Graphene inkjet printing onto elastomer substrates is displacing traditional silver-coated nylon weaving for high-fidelity biometric signal capture. Sports medicine clinics in Germany and the United States are piloting these garments for continuous ECG monitoring during exertion. The shift is compressing lead times from textile finishing to functional prototype from months to weeks.
EU MDR Article 10 technical documentation requirements are forcing wearable health fabric manufacturers to maintain design dossiers traceable to raw material batch records. Notified bodies in the Netherlands and Germany are rejecting applications lacking polymer biocompatibility data extending back to monomer synthesis. Medical-grade intelligent fabric lines are segregating production workflows to isolate CE-marked from consumer wellness SKUs.
Hospital procurement departments are consolidating vendor lists around FDA-cleared and CE-marked suppliers, squeezing uncertified fitness-wearable brands from clinical pilot programs. United States health system buying cooperatives now require 510(k) documentation for any garment billed to remote patient monitoring reimbursement codes. This certification-driven preference shift is most visible in Medicare Advantage plan contracting, where biometric garment coverage decisions hinge on regulatory status rather than consumer brand recognition.
Active Smart Textiles Market Segmentation
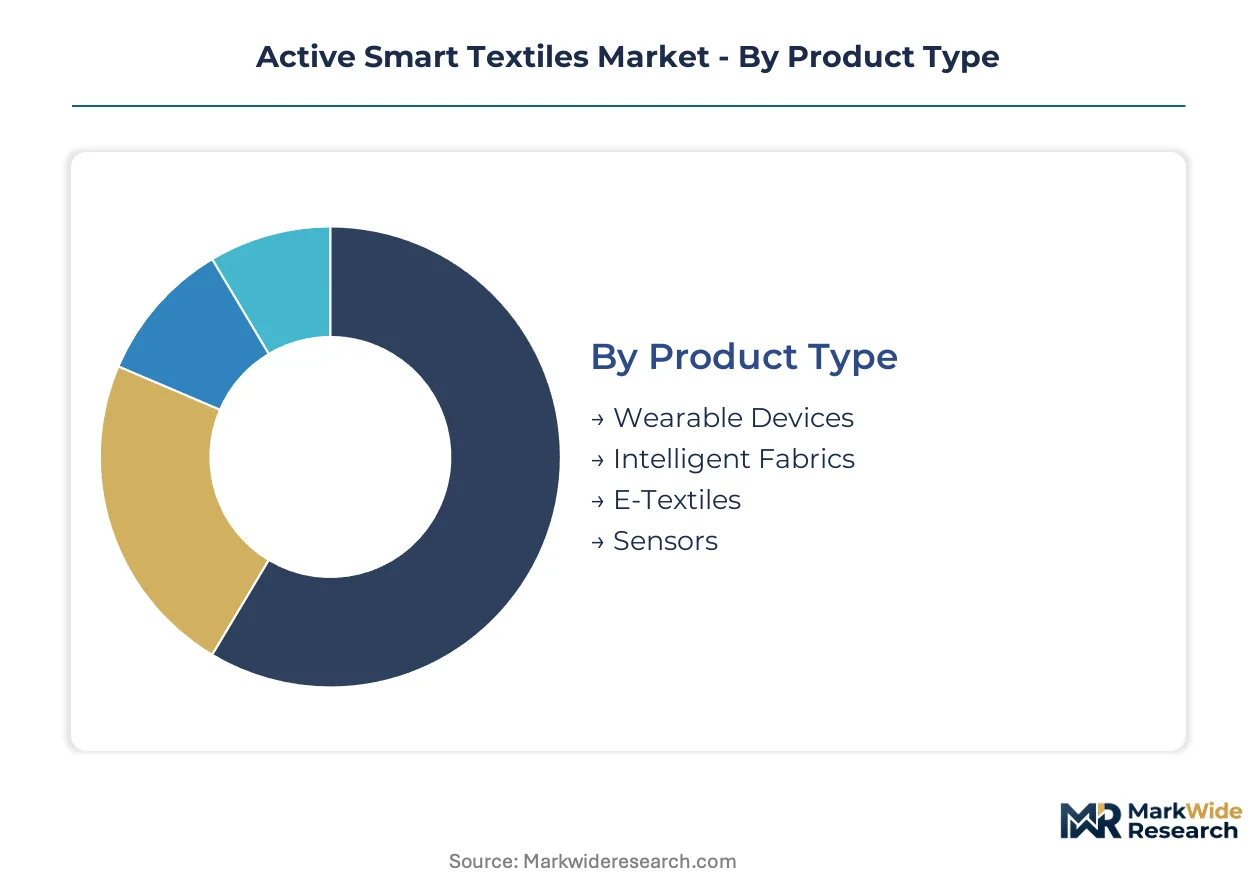
Active smart textiles fragment across four intersecting dimensions that determine pricing power and regulatory burden. Product type governs material science complexity, while application verticals dictate certification requirements and procurement channels.
Product Type:
Margin pools concentrate in sensor-integrated systems where biocompatibility validation creates defendable pricing tiers.
- Wearable Devices:Garment-integrated electronics combining conductive fiber networks with detachable microcontroller units. Veterans Affairs programs in the United States are standardizing procurement specifications for post-operative recovery garments, pulling volume through institutional reimbursement codes.
- Intelligent Fabrics:Woven substrates embedding printed graphene traces or silver-nylon conductive pathways that maintain signal fidelity across industrial wash cycles. Sports medicine clinics in Germany pilot these for continuous ECG monitoring during athletic exertion.
- E-Textiles:Flexible circuit integration achieving stretchability comparable to conventional technical apparel through elastomer substrate bonding.
- Sensors:Discrete biometric capture modules—temperature, motion, electrophysiological—designed for seamless fabric embedding.
The dominant share belongs to Intelligent Fabrics, while Sensors are closing the gap fastest.
Application:
Volume concentration tracks regulatory clarity, with cleared medical applications commanding premium pricing over consumer wellness positioning.
- Sports:Professional teams and amateur athletes drive consumption of physiological feedback garments for training optimization. Nike's integration of biometric sole technology into connected athletic footwear exemplifies brand-driven consumer adoption at scale.
- Healthcare:Remote patient monitoring applications pull intelligent fabrics into chronic disease management protocols. FDA 510(k) clearance requirements elevate development costs but create market access barriers favoring established suppliers with regulatory infrastructure.
- Fashion:Aesthetic-forward implementations prioritizing design flexibility over clinical-grade signal fidelity.
- Military:Heated wearable segments absorb advanced fabric output as defense procurement prioritizes soldier physiological management systems.
Healthcare captures the steepest expansion trajectory, though Sports retains volume leadership.
Technology:
Connectivity protocol selection determines interoperability scope and power consumption profiles that shape battery life specifications.
- Bluetooth:Dominant protocol for continuous data streaming to paired smartphones and clinical monitoring platforms. United States health system buying cooperatives now require documented wireless security protocols for any garment billed to remote patient monitoring codes.
- NFC:Short-range authentication and localized data exchange without persistent power draw.
- RFID:Passive identification for inventory tracking and supply chain authentication rather than biometric capture.
- Biometric Monitoring:Integrated electrophysiological signal processing architectures enabling raw sensor data conversion to clinical-grade outputs.
Bluetooth maintains installed base dominance, while Biometric Monitoring is gaining share fastest.
End User:
Procurement authority and reimbursement access separate institutional buyers from discretionary consumer segments.
- Athletes:Individual and team-based purchasers seeking performance optimization through continuous physiological feedback. Amateur segment price sensitivity constrains margin expansion despite volume scale.
- Patients:Chronic disease management protocols in India pilot intelligent fabric integration, opening volume scale in price-sensitive healthcare systems where Medicare Advantage-style reimbursement models are emerging.
- Fashion Designers:Creative professionals prioritizing aesthetic integration and wash durability over clinical validation.
- Military Personnel:Defense procurement channels with extended qualification timelines but multi-year contract visibility.
Patients represent the largest addressable population, while Military Personnel deliver the most stable contract profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced conductive fiber supply clusters in German and Japanese chemical corridors anchor upstream material availability. Healthcare procurement standardization in the United States and EU MDR compliance deadlines are compressing development cycles. Sports medicine pilot programs in Germany and veterans affairs contracting in the United States are pulling differentiated demand patterns.
United States
Veterans Affairs programs standardize biometric garment procurement for post-operative recovery tracking, creating institutional demand pull through reimbursement codes. FDA 510(k) clearance requirements elevate development costs but favor established suppliers with regulatory infrastructure. Boston and San Diego clusters host sports medicine clinics piloting continuous ECG monitoring garments during athletic exertion.
Germany
Sports medicine clinics pilot intelligent fabrics for continuous ECG monitoring during athletic exertion, pulling volume through clinical validation channels. EU MDR Article 10 technical documentation requirements force manufacturers to maintain design dossiers traceable to raw material batch records. Notified bodies in Munich and Hamburg reject applications lacking polymer biocompatibility data extending back to monomer synthesis.
China
Chronic disease management protocols in diabetes and cardiovascular care pilot intelligent fabric integration, opening volume scale in price-sensitive healthcare systems. NMPA alignment of wearable medical device classifications with ISO frameworks reduces dual-certification burden for export-oriented suppliers. Yangtze River Delta manufacturing clusters absorb printed graphene trace production as textile-electronics integration accelerates.
Japan
METI prioritization of soldier physiological management systems drives heated wearable segment procurement through defense channels. JIS standards for conductive yarn wash-cycle durability remain unstandardized, forcing proprietary test protocol development per OEM. Osaka and Nagoya industrial corridors concentrate polymer substrate processing equipment for advanced fabric output.
India
Diabetes and cardiovascular protocols pilot intelligent fabric integration, opening volume scale in emerging Medicare Advantage-style reimbursement models. CDSCO regulatory pathways for wearable medical devices are harmonizing with ISO frameworks, reducing dual-certification burden. Maharashtra and Karnataka textile engineering clusters face cross-functional talent scarcity as textile and embedded systems expertise rarely co-reside in single hires.
Active Smart Textiles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the active smart textiles value chain. Premium positioning concentrates among polymer science heritage suppliers with regulatory infrastructure depth, while mid-tier fabric processors compete on REACH-compliant material substitution and volume scale. Two strategic archetypes dominate: integrated material-to-garment suppliers leveraging conductive fiber captive supply, and brand-driven consumer platforms integrating licensed biometric sensor technology. Competitive moves center on M&A for regulatory infrastructure acquisition and capacity expansion into halogen-free coating production lines.
Within the polymer science heritage tier, DuPont anchors upstream conductive fiber supply through advanced material science capabilities. Gentherm occupies a position exemplifying thermal regulation specialization extending into heated wearable segments for institutional end users. Nike represents brand-driven consumer adoption at scale through integration of licensed biometric technologies into connected athletic footwear systems.
| Leading Market Players |
|---|
| DuPont |
| Jabil Inc. |
| Gentherm |
| AiQ Smart Clothing |
| Sensoria |
| Nike |
| Adidas |
| Hexoskin |
| Clothing+ |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85% in German polymer substrate facilities anchor price floors for conductive fiber feedstock, compressing margin flexibility for mid-tier fabric processors while concentrating bargaining power among integrated suppliers with captive silver-nylon hybrid production. This scale asymmetry shapes procurement negotiations for Veterans Affairs garment contracts and sports medicine clinic pilot programs alike.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across active smart textiles, separating CE-marked medical-grade garments from consumer wellness SKUs through biocompatibility validation costs. Three-tier pricing stratifies across premium intelligent fabrics with full regulatory dossiers, standard conductive yarn systems with partial certification, and economy e-textiles lacking clinical validation. Pricing pressure stems from silver price volatility in precious metals markets, compressing processor margins. Amateur athlete segments exhibit highest price sensitivity, while institutional buyers in United States health system cooperatives prioritize regulatory status over cost.
Supply Chain Analysis
Strategic stockpiling of silver-coated nylon feedstock dominates inventory strategy as processors buffer against precious metals price swings and polymer substrate lead time variability. Supply concentrates in German and Japanese chemical corridors for advanced conductive fibers, with Yangtze River Delta clusters absorbing printed graphene trace production. Raw material dependencies center on silver bullion, elastomer substrates, and halogen-free coating chemistries. Single-source vulnerability persists in monomer synthesis for biocompatible polymers. Distribution runs through hospital procurement departments and defense contracting channels for institutional volumes, with direct-to-consumer platforms serving fitness wearable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printed graphene ink systems pose a credible substitution threat to woven silver-nylon architectures, forcing incumbents to defend material science positioning while new entrants exploit certification fast-tracks in harmonizing regulatory jurisdictions.
For Market Incumbents: Shield market position by deepening captive supply of REACH-compliant conductive polymers and accelerating FDA 510(k) dossier expansion for chronic disease management applications. DuPont and Gentherm exemplify defensive consolidation through polymer science heritage leverage and thermal regulation specialization respectively. Regulatory infrastructure depth remains the critical lever against emerging graphene ink suppliers. For New Entrants and Emerging Players: CDSCO regulatory harmonization with ISO frameworks offers the fastest certification pathway for wearable medical device market entry. Target diabetes and cardiovascular pilot programs in India where Medicare Advantage-style reimbursement models are emerging and price-sensitive healthcare systems absorb volume scale. Go-to-market execution should emphasize institutional procurement channel relationships over consumer brand building. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated material-to-garment suppliers with FDA-cleared and CE-marked product lines serving hospital procurement consolidations. Long-term viability across the projection horizon favors targets with regulatory infrastructure depth and halogen-free coating production capacity. Monitor EU MDR notified body audit rejection rates as the critical inflection signal for commercialization timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks hospital procurement vendor list access in Germany and Netherlands. |
| Backward Integration into Conductive Polymers | Captive silver-nylon hybrid production insulates margin stability against precious metals volatility. |
| Hospital System Partnership | United States health system buying cooperatives require 510(k) documentation for reimbursement code eligibility. |
| Software Companion Development | Bluetooth security protocol documentation satisfies institutional procurement requirements for remote patient monitoring. |
| Reimbursement Strategy | Medicare Advantage plan contracting hinges on regulatory status rather than consumer brand recognition. |
Research Methodology
Cross-validation between primary interviews with textile engineering directors and secondary analysis of FDA 510(k) filings anchors the qualitative findings in this study. Conversations with biomedical engineers at German sports medicine clinics, procurement managers at United States Veterans Affairs programs, and regulatory affairs leads at conductive fiber manufacturers informed material substitution dynamics. Secondary validation drew from EMA MDR submission databases, ISO 10993 biocompatibility test records, and REACH chemical compliance filings. Bottom-up segmentation modeling triangulated against top-down market sizing across product type, application, and technology dimensions.
Sensitivity analysis around silver price volatility assumptions and EU MDR compliance timeline scenarios stress-tested projection robustness across the analysis window. The analytical framework modeled volume and value outputs through four intersecting segmentation dimensions: product type governing material science complexity, application verticals dictating certification requirements, technology selection determining interoperability scope, and end user procurement authority separating institutional from consumer segments. CAGRs derived from regression analysis of historical adoption curves in remote patient monitoring and sports performance optimization. Industry-specific forecast inputs included notified body audit capacity constraints and NMPA-ISO harmonization progress in China.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 510(k) review timelines and REACH-compliant material substitution trajectories; material deviation would warrant model refresh. Specific risk factors include silver bullion price spikes exceeding historical volatility bands, EU notified body capacity bottlenecks extending CE marking delays, and graphene ink durability validation breakthroughs disrupting conductive yarn incumbent positions. Revision becomes warranted when FDA clearance backlog durations or polymer substrate supply concentration metrics cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Construction Textile Market
Technical Textiles
Global PTFE Fabric Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
E-Textile Market
Technical Textiles
Fire Retardant Fabrics Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Waterproof Fabrics Market
Technical Textiles
Global Conductive Textiles Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Agri Textiles Market