
 Airbag Textiles Market | 2026-2036
Airbag Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Airbag Textiles Market Outlook
Nylon 6,6 multifilament yarn is pivoting toward higher-tenacity variants as polyester gains share in cost-sensitive airbag cushion applications. Teijin Limited leverages its aramid expertise to supply high-performance inflator housing fabrics. Kolon Industries sustains dominant positions in South Korean OEM supply chains through captive polymerization capacity. Toray Industries anchors Japanese passenger vehicle programs with ultra-fine denier woven substrates engineered for compact steering-wheel modules.
Airbag textiles are high-performance technical fabrics engineered from synthetic multifilament yarns—typically nylon 6,6 with linear densities of 210–840 denier—woven into plain or twill constructions with tear strengths exceeding 400 N and heat-set calendering to control air permeability between 0.5–5.0 L/cm²/s at 500 Pa, serving the critical function of containing high-pressure gas discharge during pyrotechnic inflator deployment within milliseconds. Passenger vehicle applications dominate volume consumption as side-curtain and knee-protection systems proliferate across B-segment and above platforms, while commercial vehicle categories represent a concentrated margin pool due to severe-duty durability specifications and lower supplier density. Weaving remains the foundational production method for base fabric construction, though coating and laminating processes command premium pricing tiers where silicone or neoprene barriers enable single-layer designs that reduce module weight and packaging volume.
NHTSA Federal Motor Vehicle Safety Standard 208, ECE R94/R95, and China's GB/T requirements collectively mandate minimum occupant protection performance that directly determines yarn tenacity specifications, seam-slippage thresholds, and post-deployment fragmentation limits. FMVSS 226 ejection mitigation standards in the United States have extended textile coverage to side-window curtain geometries, expanding fabric area per vehicle. Stakeholders must monitor how evolving UN R135 pole-side-impact protocols and anticipated updates to Indian AIS-098 standards recalibrate the balance between nylon cost efficiency and aramid performance premiums in next-generation module designs.
Market Dynamics
Multi-chamber airbag configurations are proliferating across mid-range passenger vehicle platforms, forcing textile suppliers to recalibrate weaving capacity for complex three-dimensional cushion geometries while maintaining seam integrity under 200 kPa deployment pressures.
Growth Catalysts
- NHTSA FMVSS 226 ejection mitigation:United States mandates extend textile coverage to side-window curtain geometries, expanding fabric area requirements per vehicle platform and sustaining volume pull through 2035.
- China GB standards localization:Domestic OEMs accelerate captive sourcing programs for nylon 6,6 substrates, reducing import dependency and creating dedicated supply corridors for regional vehicle production clusters.
- Polyester cost arbitrage:Cost-sensitive cushion applications in emerging-market vehicle lines adopt high-tenacity polyester multifilament, opening incremental volume pools previously locked to nylon specifications.
Market Restraints
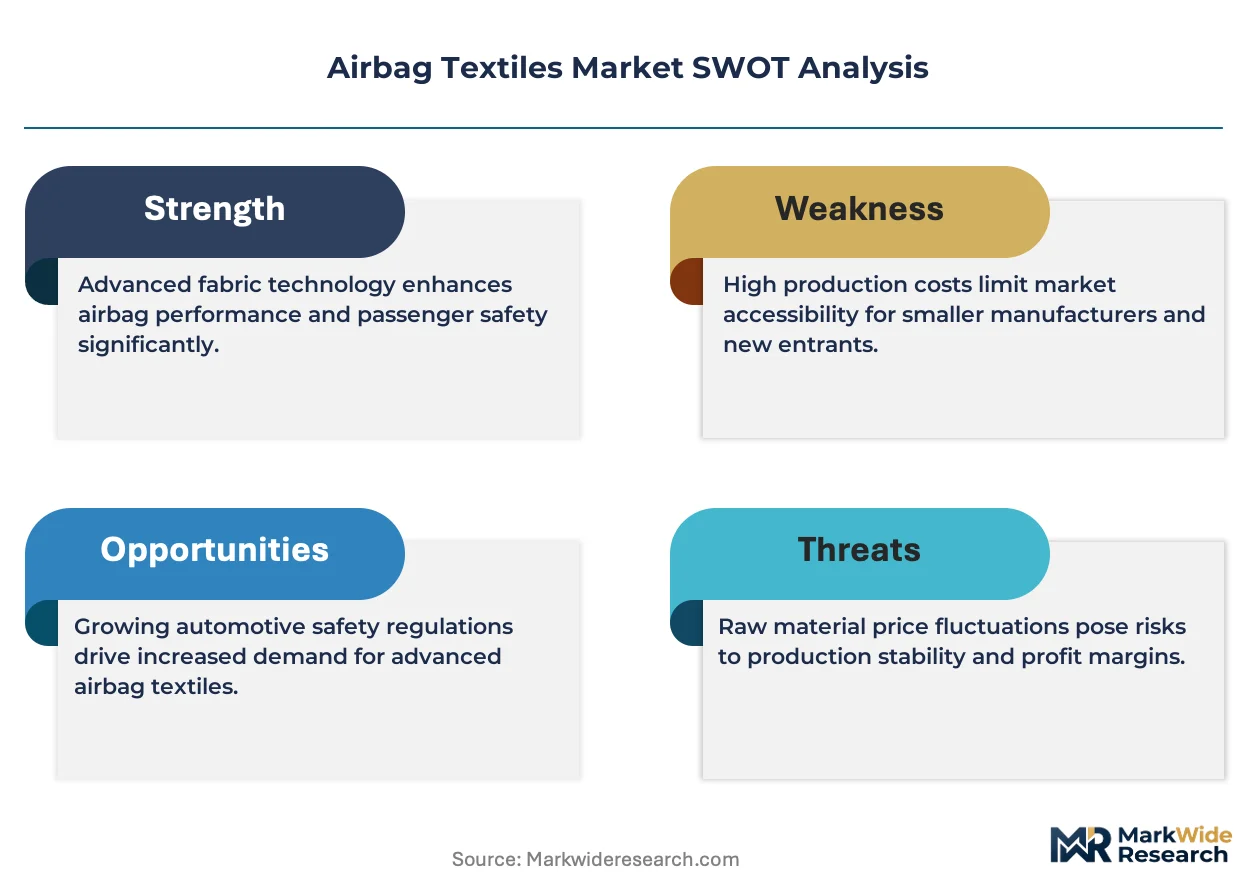
- Caprolactam price volatility:Nylon 6,6 polymer feedstock costs fluctuate with benzene derivative markets, compressing margin stability for non-integrated weaving operations.
- Aramid supply concentration:Inflator housing fabric production clusters among three specialty fiber suppliers, creating single-source vulnerability for Tier-1 module assemblers.
- ECE R94 seam-slippage thresholds:European regulatory friction elevates testing cycle duration, delaying platform approval timelines and freezing working capital in certification pipelines.
Strategic Opportunities
- India AIS-098 alignment:Anticipated updates to occupant protection standards create first-mover positioning for suppliers establishing localized calendering and coating operations ahead of enforcement.
- Silicone barrier single-layer designs:Coating-laminating convergence enables module weight reduction of 15-20 percent, targeting electric vehicle packaging constraints where every kilogram commands premium value.
- Commercial vehicle severe-duty segment:Lower supplier density and durability specifications 3x passenger thresholds generate concentrated margin pools for weaving operations with aramid-Nylon 6,6 hybrid capability.
Industry Challenges
- Heat-set calibration expertise:Air permeability control within 0.5–5.0 L/cm²/s tolerances requires specialized technicians scarce in emerging manufacturing regions.
- UN R135 pole-side-impact recertification:Updated test protocols force simultaneous revalidation of yarn tenacity and fragmentation limits, extending development cycles for next-generation modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airbag Textiles Market |
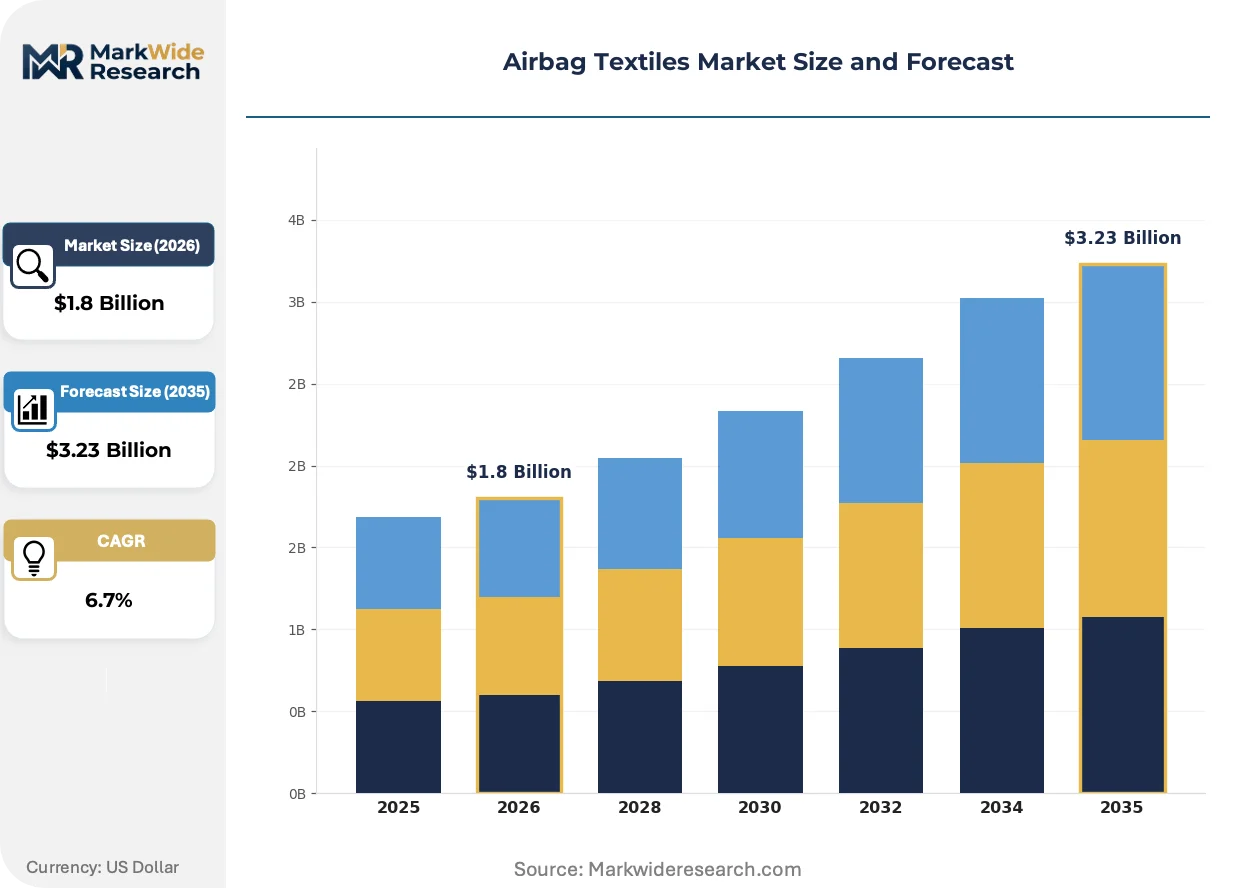
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Nylon, Polyester, Aramid, Cotton End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Manufacturers Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Vehicles Production Method: Weaving, Knitting, Coating, Laminating |
| Companies Covered | Teijin Limited, Kolon Industries, Toray Industries, Global Safety Textiles, Indorama Ventures, Hyosung Advanced Materials, Asahi Kasei Corporation, HMT (Xiamen) New Technical Materials Co., Ltd., Toyobo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airbag Textiles Market Strategic Shifts
Technical textile engineering is pivoting from commodity substrate supply toward integrated module-level solutions, with coating technologies and hybrid yarn constructions commanding disproportionate value capture relative to base weaving operations.
Ultra-fine denier woven substrates are absorbing the packaging constraints of compact steering-wheel modules. Japanese passenger vehicle programs deploy 210-denier Nylon 6,6 constructions to minimize folded volume while maintaining 400 N tear strength. This material trajectory is absorbing design space previously allocated to thicker multi-layer assemblies, compressing module stack height by 30 percent.
REACH substance restrictions are tightening chemical compliance burdens for silicone coating formulations. European textile finishers reformulate barrier chemistries to eliminate candidate list substances, extending qualification timelines but securing long-term market access. Side-curtain programs for German OEM platforms absorb the compliance overhead fastest, converting regulatory friction into supplier consolidation pressure.
Buyer concentration among mega-supplier module assemblers is compressing negotiation leverage for independent weaving operations. Tier-1 procurement teams consolidate qualified vendor lists to three preferred partners per geography, replacing fragmented multi-source arrangements. This pattern concentrates most visibly in United States supply chains, where NHTSA documentation requirements amplify switching costs.
Airbag Textiles Market Segmentation
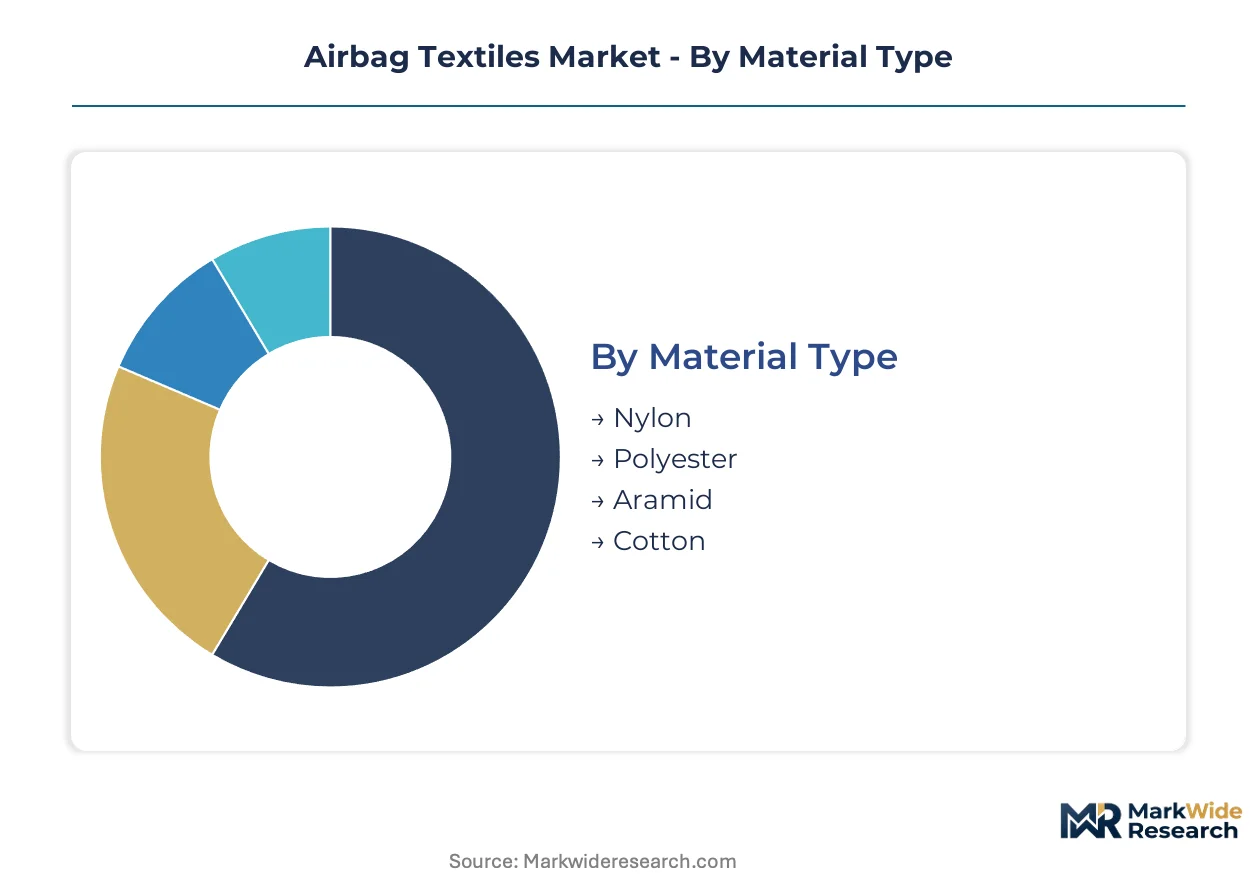
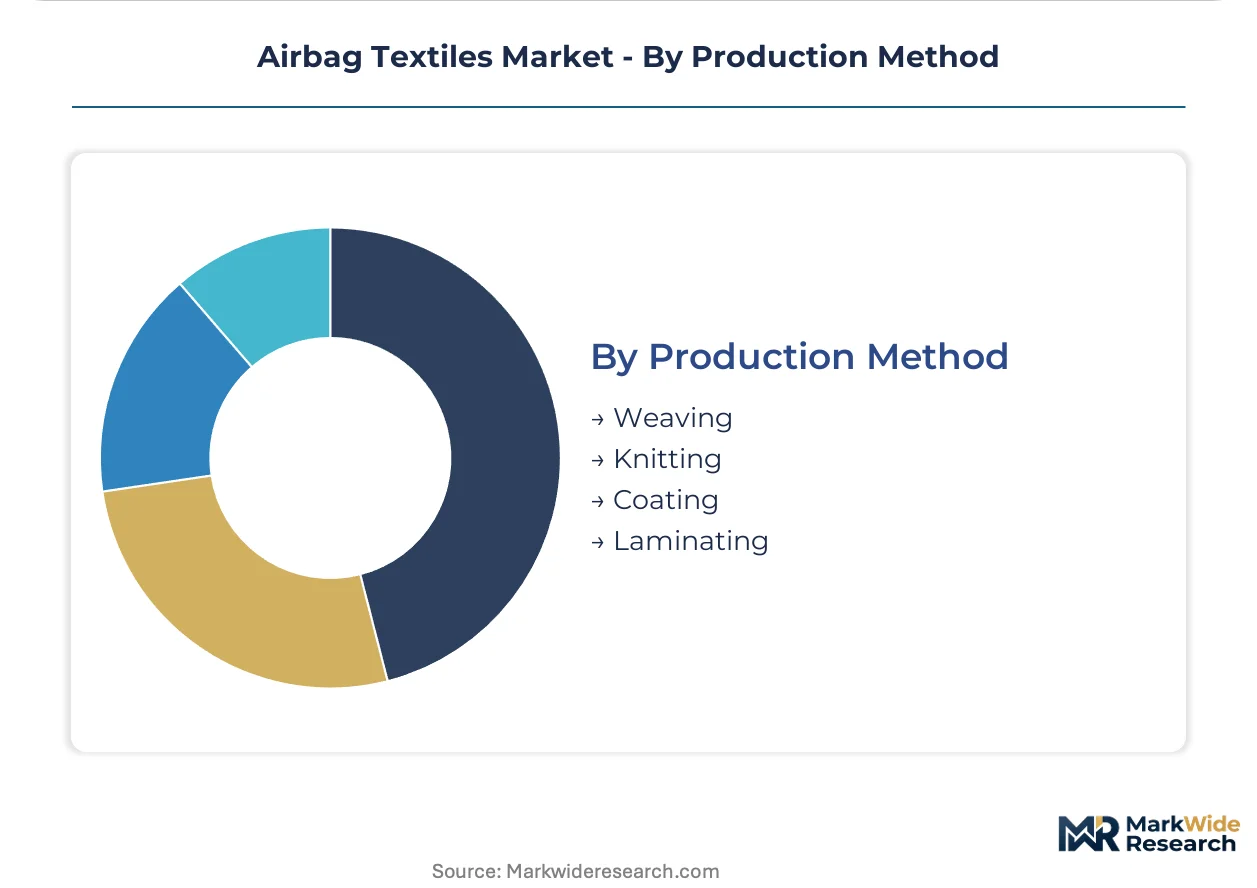
Airbag textile segmentation reflects the tension between cost efficiency and performance thresholds. Material chemistry, production method sophistication, and end-user procurement power determine margin distribution across the value chain.
Material Type:
Nylon 6,6 tenacity specifications anchor the technical hierarchy, with alternative polymers carving distinct cost-performance niches.
- Nylon:Multifilament yarns in 210–840 denier ranges dominate passenger vehicle cushion applications. China GB standards localization drives captive polymerization investments near Shanghai and Guangzhou vehicle production clusters.
- Polyester:High-tenacity variants displace nylon in cost-sensitive emerging-market platforms. Indian OEMs expanding B-segment production absorb polyester substrates for knee-protection modules where tenacity thresholds permit substitution.
- Aramid:Meta-aramid and para-aramid constructions serve inflator housing fabrics requiring thermal stability above 300°C.
- Cotton:Limited deployment in specialty vintage vehicle restoration and military surplus applications.
Nylon leads on scale; polyester leads on momentum.
End User:
Procurement concentration among module assemblers reshapes supplier qualification requirements.
- OEMs:Direct material specifications for steering-wheel and side-curtain programs. German OEMs enforce REACH-compliant silicone coating formulations through qualified vendor lists limited to three partners per geography.
- Aftermarket Providers:Replacement cushion and cover assemblies for collision repair channels. United States NHTSA documentation requirements amplify switching costs and consolidate procurement toward certified weavers.
- Tier-1 Suppliers:Module-level integration of woven substrates with inflator hardware. Japanese Tier-1s source ultra-fine denier constructions from Toray Industries for compact packaging.
- Vehicle Manufacturers:Captive weaving operations in South Korea through Kolon Industries' integrated polymerization-to-fabric production.
Tier-1 suppliers lead on scale; OEMs lead on momentum.
Application:
Vehicle category determines durability specifications and supplier density.
- Passenger Vehicles:Side-curtain and knee-protection systems proliferate across B-segment and above platforms. Multi-chamber configurations force weaving capacity recalibration for three-dimensional cushion geometries.
- Commercial Vehicles:Severe-duty durability specifications three times passenger thresholds generate concentrated margin pools. Lower supplier density rewards weavers with aramid-nylon hybrid capability.
- Motorcycles:Compact module packaging for handlebar and fuel-tank deployments.
- Heavy-Duty Vehicles:Mining and construction equipment airbag systems requiring abrasion-resistant outer layers.
Passenger vehicles lead on scale; commercial vehicles lead on momentum.
Production Method:
Process sophistication determines value capture relative to commodity substrate supply.
- Weaving:Plain and twill constructions form the foundational base fabric. Heat-set calendering controls air permeability within 0.5–5.0 L/cm²/s tolerances.
- Coating:Silicone barrier formulations enable single-layer designs reducing module weight 15-20 percent. European finishers reformulate to eliminate REACH candidate list substances.
- Laminating:Multi-layer assemblies combining woven substrates with film barriers for severe-duty applications.
- Knitting:Limited deployment for stretchable cushion geometries in specialized motorcycle applications.
Weaving leads on scale; coating leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Guangzhou vehicle production corridor anchors the airbag textiles demand map, with localized nylon 6,6 polymerization investments accelerating captive sourcing programs. Regulatory mandates from NHTSA, ECE, and China's GB standards are redrawing supplier qualification requirements across major automotive clusters.
China
Domestic OEMs are expanding multi-chamber airbag configurations across B-segment and above vehicle lines, pulling nylon 6,6 substrate volumes upward. GB standards enforcement tightens performance thresholds for occupant protection systems, forcing recalibration of yarn tenacity specifications. Shanghai and Guangzhou production clusters host integrated polymerization-to-fabric operations that reduce import dependency for regional vehicle programs.
United States
NHTSA FMVSS 226 ejection mitigation mandates extend textile coverage to side-window curtain geometries, expanding fabric area requirements per vehicle platform. Federal Motor Vehicle Safety Standard 208 maintains baseline occupant protection performance that determines seam-slippage thresholds. Detroit-area module assemblers consolidate qualified vendor lists to three preferred partners per geography, amplifying switching costs for independent weaving operations.
Germany
ECE R94 and R95 protocols govern minimum occupant protection performance for European vehicle programs, with ECE R94 seam-slippage thresholds elevating testing cycle duration. REACH substance restrictions tighten chemical compliance burdens for silicone coating formulations used in single-layer designs. Stuttgart and Munich OEM procurement teams enforce qualified vendor lists limited to three partners per geography, converting regulatory friction into supplier consolidation pressure.
Japan
Ultra-fine denier woven substrates for compact steering-wheel modules absorb packaging constraints in Japanese passenger vehicle programs. METI industrial standards intersect with JIS specifications to calibrate heat-set calendering tolerances for air permeability control. Nagoya and Tokyo automotive clusters source 210-denier nylon 6,6 constructions that minimize folded volume while maintaining tear strength thresholds.
India
Anticipated updates to AIS-098 occupant protection standards create first-mover positioning for suppliers establishing localized calendering and coating operations. BIS certification requirements intersect with automotive safety regulations to determine post-deployment fragmentation limits. Pune and Chennai production corridors absorb polyester substrates for cost-sensitive knee-protection modules where tenacity specifications permit nylon substitution.
Airbag Textiles Market Competitive Environment
Capacity expansion dominates the current landscape as integrated polymerization-to-fabric operations capture margin stability from volatile caprolactam feedstock markets. The supplier base concentrates around three strategic archetypes: captive polymerization specialists with backward integration into nylon 6,6 monomer supply, coating-laminating convergents targeting single-layer module designs, and aramid hybrid weavers serving severe-duty commercial vehicle specifications. Geographic expansion and technology licensing represent the dominant competitive moves, with South Korean and Japanese players leveraging regional OEM relationships to anchor preferred supplier status.
Among Asia-Pacific material science conglomerates, Teijin Limited, Kolon Industries, and Toray Industries exemplify distinct competitive positioning archetypes. Teijin occupies a position within the high-performance fiber tier, leveraging aramid expertise for thermal stability applications. Kolon Industries anchors the captive integration archetype through polymerization-to-fabric production control. Toray Industries sits within the ultra-fine denier specialization vector, supplying woven substrates engineered for compact module packaging constraints.
| Leading Market Players |
|---|
| Teijin Limited |
| Kolon Industries |
| Toray Industries |
| Global Safety Textiles |
| Indorama Ventures |
| Hyosung Advanced Materials |
| Asahi Kasei Corporation |
| HMT (Xiamen) New Technical Materials Co., Ltd. |
| Toyobo Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions gate both qualified supply and premium-tier pricing access for European airbag textile programs, as silicone coating reformulation costs convert regulatory compliance into supplier consolidation pressure that rewards pre-qualified vendors with pricing power while excluding uncertified competitors from high-margin single-layer module contracts.
Pricing Analysis
Caprolactam price pass-through from benzene derivative markets compresses margin stability for non-integrated weaving operations, forcing contract-based long-term offtake agreements to dominate procurement between Tier-1 module assemblers and nylon 6,6 substrate suppliers. Price differentiation hinges on certification grade—NHTSA documentation tiers versus economy-grade emerging-market specifications—and volume scale, with OEM direct contracts commanding premiums over aftermarket channels. Pricing pressure stems from polyester substitution in cost-sensitive cushion applications, eroding nylon's historical pricing floor. Aftermarket providers exhibit highest price sensitivity due to fragmented collision repair demand, while German OEM procurement teams show lowest sensitivity where REACH compliance secures sole-source positioning.
Supply Chain Analysis
NHTSA documentation requirements and ECE R94 seam-slippage certification gate entry into qualified vendor lists, concentrating supply among China, Germany, and South Korea where integrated polymerization-to-fabric operations anchor regional production clusters. Raw material dependencies center on caprolactam monomer, high-tenacity multifilament yarn, and silicone barrier formulations, with aramid fiber supply resting on three specialty producers. Single-source vulnerability in inflator housing fabrics creates structural risk for Tier-1 module assemblers. Distribution runs through captive OEM supply corridors and consolidated Tier-1 procurement hubs, with direct mill relationships replacing fragmented multi-source arrangements in United States and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA FMVSS 226 ejection mitigation mandates sustain volume pull through expanded side-curtain fabric coverage, converting compliance thresholds into durable demand visibility for qualified suppliers.
For Market Incumbents: Deepen backward integration into caprolactam supply to defend margin stability against feedstock volatility, while expanding calendering and coating capacity in India ahead of AIS-098 enforcement to capture first-mover positioning in emerging regulatory corridors. Kolon Industries' captive polymerization model demonstrates how upstream control insulates weaving operations from benzene derivative price swings. Reinforce qualified vendor list status through NHTSA documentation investment, as switching costs amplify procurement concentration among three preferred partners per geography.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium aramid inflator housings and economy polyester cushions offers white-space entry for hybrid nylon-polyester weavers targeting Indian B-segment knee-protection modules where tenacity specifications permit material substitution. Commercial vehicle severe-duty specifications present a second penetrable segment given 3x passenger durability thresholds and lower incumbent density. Establish localized coating operations with silicone barrier capability as the go-to-market anchor, positioning for electric vehicle single-layer module demand where 15-20 percent weight reduction commands premium value.
For Investors and Strategic Acquirers: Roll-up economics work for regional coating-laminating specialists because Tier-1 procurement consolidation is compressing qualified vendor lists to three partners per geography, creating scalable platform value through certification aggregation and geographic coverage expansion. Target weaving operations with aramid-nylon hybrid capability serving commercial vehicle specifications, where concentrated margin pools and lower competitive intensity support durable cash flow generation. Watch UN R135 pole-side-impact recertification timelines as the inflection signal, as revalidation cycles extending development timelines will favor incumbent scale and freeze out undercapitalized competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Captive polymerization insulates margin stability from benzene derivative volatility affecting non-integrated weavers. |
| Silicone Coating Capacity Expansion | Single-layer module designs targeting electric vehicle packaging constraints command 15-20 percent weight reduction premiums. |
| India Calendering Localization | AIS-098 alignment creates first-mover positioning ahead of enforcement in Pune and Chennai production corridors. |
| Aramid Hybrid Weaving Capability | Commercial vehicle severe-duty specifications generate concentrated margin pools with durability thresholds 3x passenger levels. |
| NHTSA Documentation Investment | FMVSS 226 compliance amplifies switching costs and consolidates procurement toward certified vendors in Detroit-area supply chains. |
Study Parameters
Multiple input streams—primary interviews with Tier-1 procurement directors, OEM platform engineers, and textile plant managers; secondary validation through NHTSA filing databases, ECE regulatory submissions, and vehicle production registries; and customs trade data on caprolactam and multifilament yarn flows—were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates.
Data-stream reconciliation across material type, production method sophistication, and end-user procurement concentration enabled analytical framework construction across the projection horizon. Segmentation dimensions modeled include yarn chemistry tiers, coating-laminating process depth, vehicle category durability specifications, and regional regulatory clusters. CAGRs were derived from production volume trajectories and content-per-vehicle expansion in multi-chamber configurations, with forecast inputs incorporating NHTSA mandate timelines and GB standards localization velocity.
Caveats apply where caprolactam price volatility, UN R135 recertification delays, or REACH substance restriction expansion could materially shift the outlook for supplier qualification timelines and margin structures. Forecasts reflect assumptions regarding regulatory enforcement consistency and OEM platform standardization patterns. A model refresh is warranted upon material change in NHTSA documentation requirements or AIS-098 enforcement scheduling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Bivy Sacks Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Webbing Market
Technical Textiles
Absorbent Cover Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
US Geotextile Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
E-Textile Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Global PTFE Fabric Market