
 Agro Textiles Market | 2026-2036
Agro Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Agro Textiles Market Analysis
Capital-intensity divergence between integrated fiber producers and downstream converters is redrawing competitive boundaries in agro textiles. Belton Industries leverages captive polypropylene resin capacity to sustain margin control across its shade net portfolio. Garware Technical Fibres anchors its position through specialized insect netting formulations that dominate India's horticulture belt. Neo Corp International competes on jute-based erosion control mats, occupying a niche where European sustainability procurement favors biodegradable alternatives.
Agro textiles are engineered woven or non-woven fabrics, typically manufactured from polypropylene, polyester, or natural fibers with specified tensile strength and UV stabilization ratings, designed to modify microclimate conditions, exclude pests, or stabilize soil in agricultural environments. Crop covers and shade nets command the largest revenue pools due to their deployment across high-value protected cultivation, while insect netting registers the fastest structural expansion as pesticide reduction mandates intensify. Polypropylene dominates material throughput because of its cost-performance ratio and recyclability profile, though jute segments attract premium positioning where EU Green Deal procurement criteria apply.
FDA food-contact standards for agricultural plastics, EU REACH restrictions on chemical additives in polypropylene, and India's BIS durability certification for agro-textiles collectively constrain formulation choices while creating compliance-based segmentation. These frameworks elevate testing costs for new entrants but reward incumbent manufacturers with established certification infrastructure. Stakeholders must monitor evolving biodegradability standards and polymer recycling mandates, as these will determine which material platforms retain market access across major procurement jurisdictions.
Market Dynamics
Protected cultivation acreage expansion in China and the Netherlands is compressing shade net replacement cycles from five years to three years as greenhouse operators intensify microclimate control investments.
Growth Catalysts
- EU REACH additive restrictions:Chemical compliance mandates are filtering out low-grade polypropylene suppliers and consolidating procurement around certified manufacturers with established testing infrastructure.
- India's horticulture belt:Maharashtra and Gujarat cooperatives are replacing conventional polyethylene with UV-stabilized agro-textiles for vegetable and flower cultivation, creating concentrated demand pull.
- Biodegradable jute matting:European sustainability procurement under EU Green Deal criteria is opening premium positioning for natural fiber erosion control products in public infrastructure tenders.
Market Restraints
- Polypropylene resin volatility:Crude-linked feedstock costs create margin compression for converters without captive resin capacity or long-term supply contracts.
- Chinese supply concentration:Raw fiber and woven fabric production clusters in Zhejiang and Jiangsu provinces expose downstream buyers to single-geography disruption risk.
- UV stabilization technical ceiling:Current additive packages max out at 36-month field life in tropical high-UV zones, limiting product replacement cycle extension.
Strategic Opportunities
- India's BIS certification gap:Durability standards enforcement is creating first-mover advantage for domestic manufacturers with accredited testing facilities against unorganized sector imports.
- Precision agriculture convergence:Integration of sensor-embedded crop covers with drip irrigation systems is opening bundled service contracts in Dutch greenhouse clusters.
- Direct-to-cooperative distribution:Maharashtra horticulture federations are bypassing traditional dealer networks for volume procurement, compressing channel margins and rewarding scale logistics.
Industry Challenges
- Polymer formulation chemist scarcity:UV stabilization and anti-fungal additive expertise is concentrated among legacy technical textile engineers nearing retirement.
- Multi-jurisdiction certification timelines:Simultaneous EU REACH, FDA food-contact, and India BIS testing extends product launch cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agro Textiles Market |
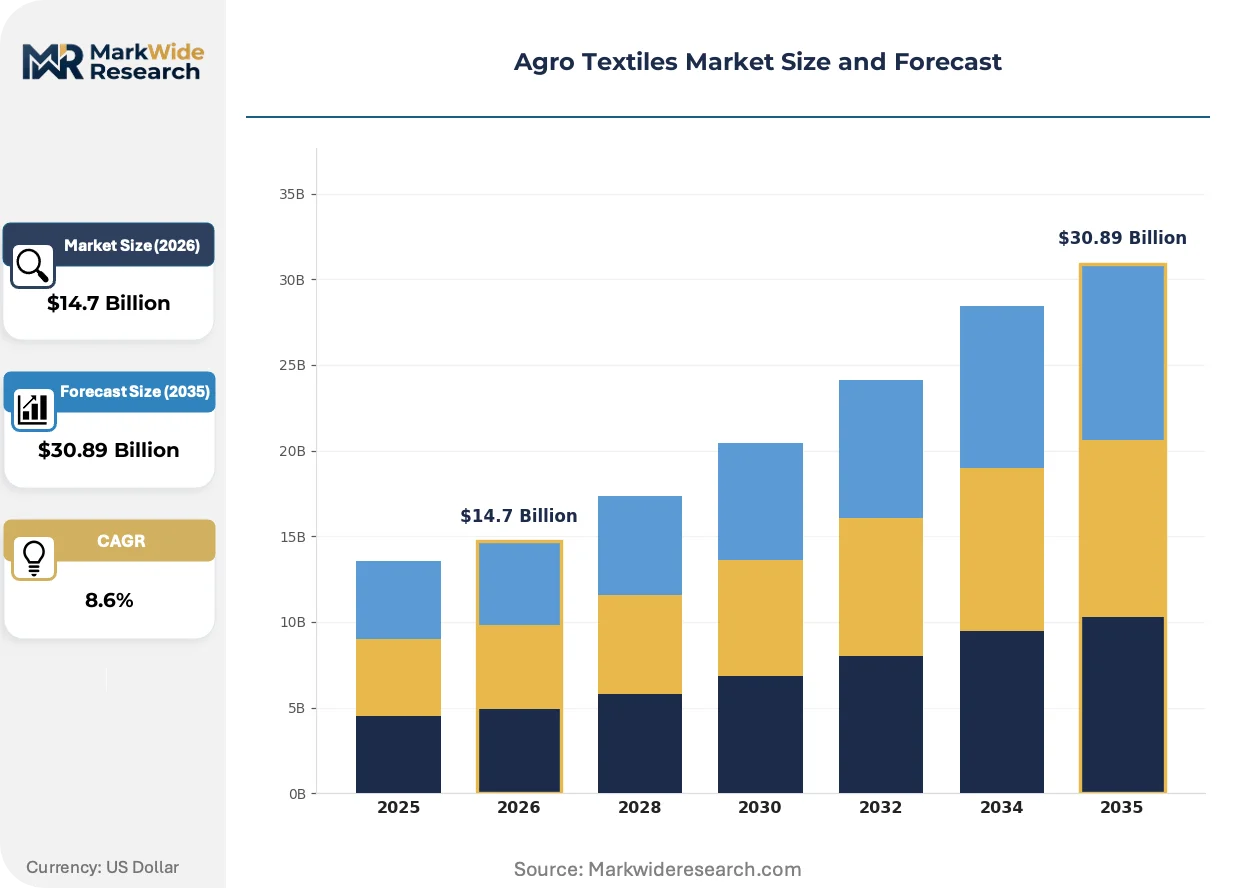
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Covers, Shade Nets, Mulch Films, Insect Netting Material: Polypropylene, Polyester, Jute, Cotton Application: Agricultural Production, Horticulture, Aquaculture, Erosion Control End User: Farmers, Greenhouses, Nurseries, Agricultural Cooperatives |
| Companies Covered | Belton Industries, Inc., Neo Corp International Limited, Beaulieu Technical Textiles, Garware Technical Fibres Ltd., SRF Ltd., Hy-Tex Ltd., TenCate Industrial Fabrics, Zhongshan Hongjun Nonwovens Co. Ltd., B&V Agro Irrigation Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agro Textiles Market Emerging Trajectories
Material science advances and regulatory stringency are converging to fragment the competitive landscape between commodity polypropylene suppliers and specialized natural fiber formulators serving divergent procurement criteria.
Multilayer non-woven crop covers with integrated moisture-wicking and thermal buffering layers are decomposing the traditional single-function product architecture. Dutch greenhouse operators are piloting these covers across tomato and pepper cultivation zones. The technology is decomposing price competition around basic shade percentage into performance-based contracts tied to yield outcomes.
EU REACH restrictions on heavy metal stabilizers in polypropylene are forcing reformulation toward calcium-zinc and organic additive packages. Manufacturers with existing ECHA registration dossiers are capturing specification lock-in from risk-averse buyers. Shade net and ground cover segments face the steepest compliance cost escalation, accelerating supplier consolidation.
Certification-driven purchasing is restructuring procurement authority within agricultural cooperatives. Technical specifications teams in Maharashtra horticulture federations now override traditional procurement officers on material selection. This shift is most visible in vegetable seedling operations where BIS durability certification has become a mandatory tender precondition.
Agro Textiles Market Segmentation
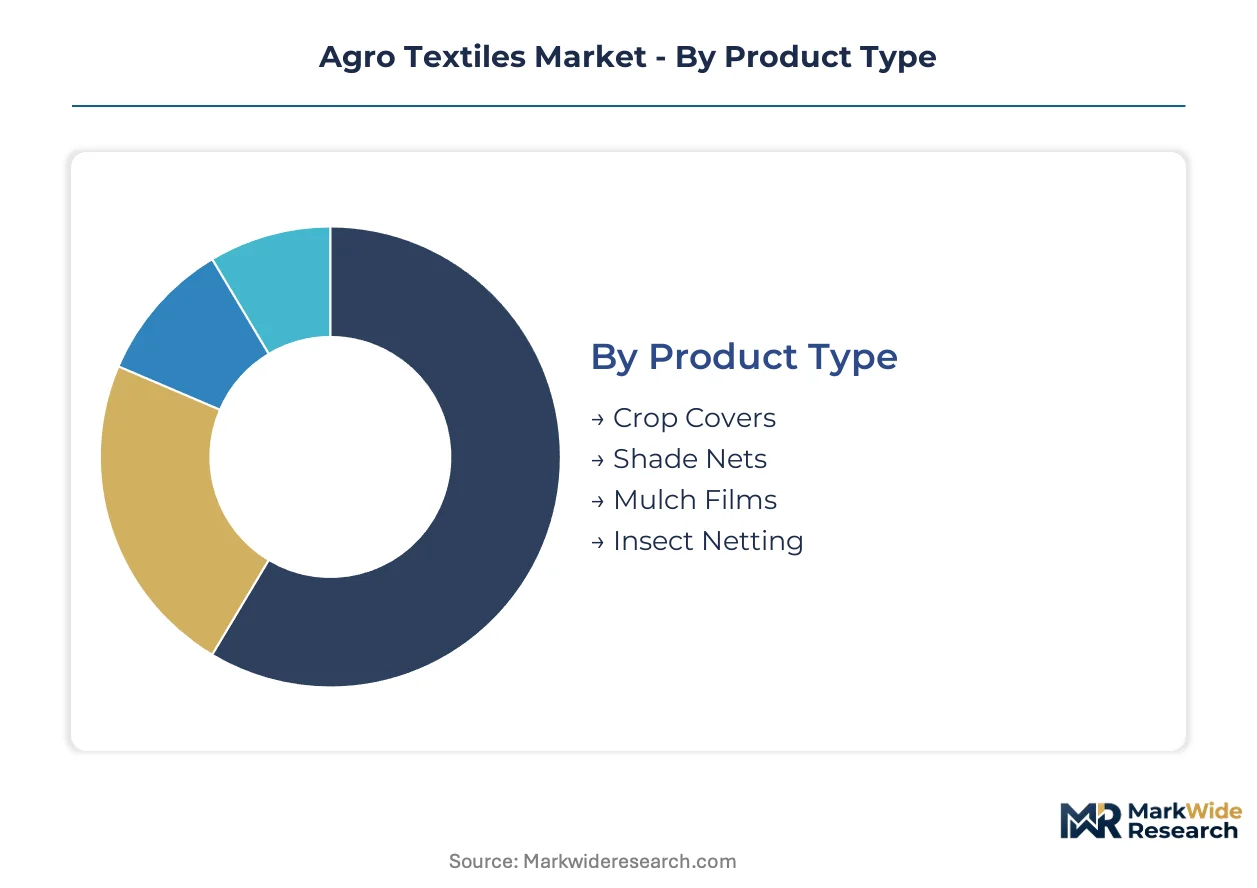
Agro textiles fragment across multiple technical dimensions where specification choices determine compliance pathways and procurement authority. Material selection locks in regulatory obligations, while product architecture dictates replacement cycles and bundled service potential.
Product Type:
EU REACH additive restrictions on heavy metal stabilizers have bifurcated shade net and crop cover specifications between legacy formulations and calcium-zinc organic packages.
- Crop Covers:Multilayer non-woven fabrics with integrated moisture-wicking and thermal buffering layers are displacing single-function architectures. Dutch greenhouse operators across tomato and pepper zones are piloting performance-based contracts tied to yield outcomes rather than shade percentage alone.
- Shade Nets:Woven polypropylene fabrics with specified UV stabilization ratings dominate protected cultivation procurement. Chinese and Netherlands greenhouse operators are compressing replacement cycles from five years to three years as microclimate control investments intensify.
- Mulch Films:Ground cover segments face steep compliance cost escalation under EU REACH, accelerating supplier consolidation around manufacturers with existing ECHA registration dossiers.
- Insect Netting:Specialized formulations dominate India's horticulture belt as Maharashtra cooperatives mandate BIS durability certification for vegetable seedling operations.
Crop covers and shade nets handle the majority of throughput; insect netting is expanding most quickly on share as pesticide reduction mandates intensify.
Material:
Cost-performance ratios separate commodity resin suppliers from premium natural fiber positioning where sustainability procurement criteria apply.
- Polypropylene:Cost-performance ratio and recyclability profile dominate material throughput. Crude-linked feedstock volatility creates margin compression for converters without captive resin capacity or long-term supply contracts.
- Polyester:Higher tensile strength specifications serve erosion control and aquaculture applications where mechanical durability outweighs cost sensitivity.
- Jute:Biodegradable erosion control mats occupy a niche where EU Green Deal procurement favors natural fiber alternatives in public infrastructure tenders.
- Cotton:Limited penetration restricted to organic certification schemes where synthetic polymer exclusion is mandatory.
Polypropylene commands volume leadership; jute posts the steepest expansion trajectory where European sustainability mandates create premium positioning.
Application:
Customer procurement authority is restructuring around technical specification teams rather than traditional purchasing officers.
- Agricultural Production:Broad-acre deployment of ground covers and mulch films across row crop systems where cost minimization dominates specification.
- Horticulture:Maharashtra and Gujarat cooperatives are replacing conventional polyethylene with UV-stabilized agro-textiles, creating concentrated demand pull for certified products.
- Aquaculture:Pond lining and predator netting applications where polyester mechanical properties justify material cost premiums.
- Erosion Control:European public infrastructure tenders under EU Green Deal criteria are opening premium positioning for biodegradable jute matting.
Horticulture concentrates the fastest share gains; agricultural production retains the largest installed base.
End User:
Distribution channel compression is rewarding scale logistics as cooperatives bypass traditional dealer networks.
- Farmers:Individual procurement remains price-sensitive and specification-light, concentrated in unorganized sector imports vulnerable to BIS enforcement.
- Greenhouses:Netherlands and China operators are driving sensor-embedded crop cover integration with drip irrigation systems, opening bundled service contracts.
- Nurseries:Seedling operations where BIS durability certification has become mandatory tender precondition in Maharashtra federations.
- Agricultural Cooperatives:Maharashtra horticulture federations are executing direct volume procurement, compressing channel margins and consolidating supplier relationships.
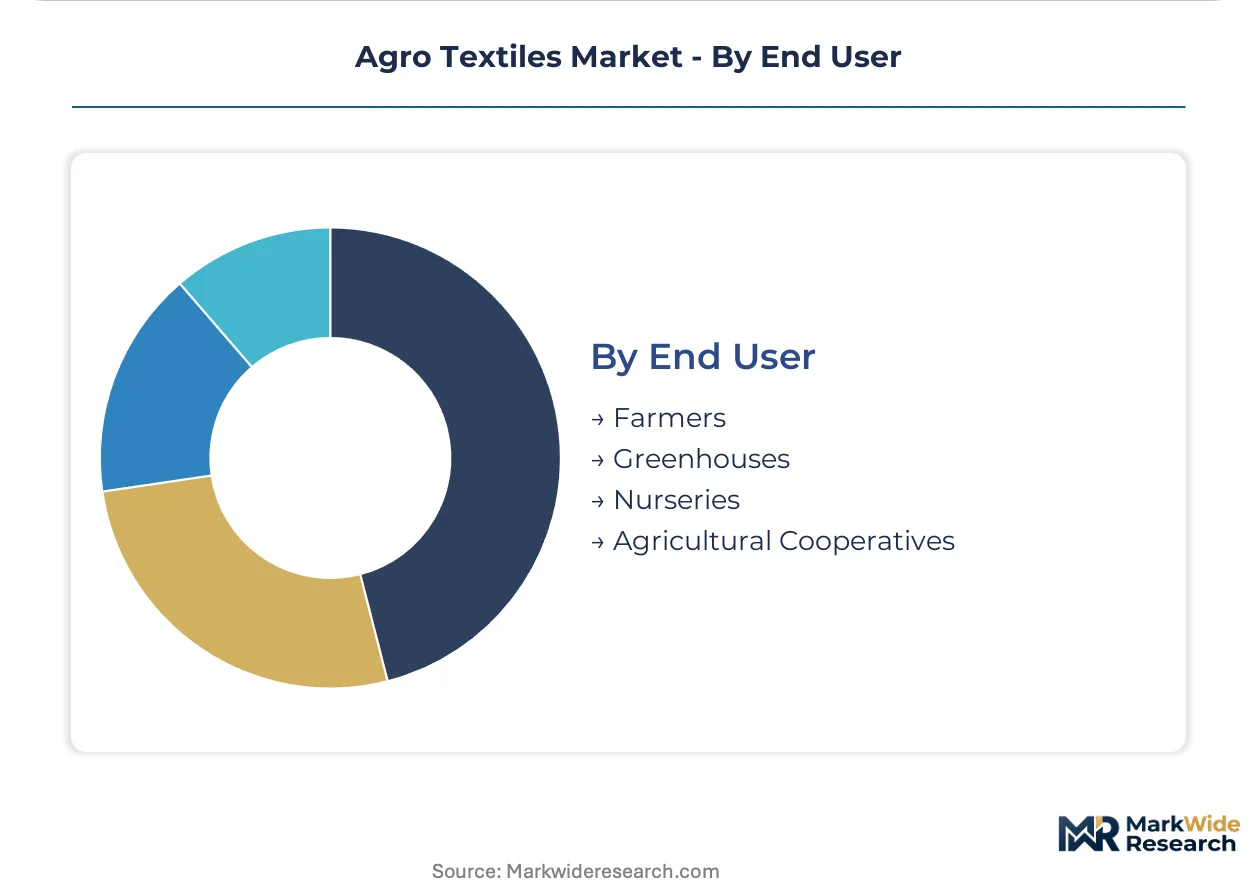
Agricultural cooperatives are climbing the fastest on procurement influence; greenhouses retain the highest technical specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Dutch greenhouse operators specifying performance-based contracts while Chinese manufacturers absorb feedstock volatility. Indian state-level procurement mandates are compressing margins for uncertified imports. Brazilian broad-acre operators remain price-takers in polypropylene ground cover markets.
China
Zhejiang and Jiangsu province clusters supply woven fabric and raw fiber for global shade net production. GB standards on agricultural plastics and MIIT industrial policy guide domestic manufacturer consolidation. Greenhouse operators in Shandong province are intensifying microclimate control investments and compressing replacement cycles.
Netherlands
Westland and Aalsmeer greenhouse clusters drive specification intensity for sensor-embedded crop covers. EU REACH additive restrictions on heavy metal stabilizers filter procurement toward ECHA-registered suppliers. Rotterdam logistics hubs facilitate bundled service contracts linking technical textile provision to precision irrigation systems.
India
Maharashtra and Gujarat horticulture cooperatives mandate BIS durability certification for vegetable seedling operations. BIS enforcement and DGFT import monitoring filter out unorganized sector polyethylene substitutes. Nashik and Pune industrial corridors concentrate domestic agro-textile manufacturing capacity.
United States
California Central Valley and Florida vegetable producers deploy ground covers across large-scale row crop systems. FDA food-contact standards constrain polymer formulation choices for agricultural plastics. Georgia and North Carolina textile manufacturing clusters supply southeastern nursery and greenhouse operations.
Germany
Baden-Württemberg specialty crop growers specify high-performance mulch films under EU Green Deal procurement criteria. ECHA registration dossiers and REACH compliance create specification lock-in from risk-averse buyers. Bavaria agricultural cooperatives pilot biodegradable erosion control matting in public infrastructure tenders.
Agro Textiles Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding margin control while specialized formulators capture premium positioning. The vendor base separates into three tiers: captive polypropylene suppliers with upstream resin capacity, technical textile specialists with additive formulation expertise, and regional converters serving price-sensitive broad-acre markets. Consolidation pressures concentrate among shade net and ground cover segments where EU REACH compliance costs escalate. Dominant competitive moves include backward integration into resin production and geographic expansion through direct-to-cooperative distribution channels.
Among integrated manufacturers, Belton Industries anchors the resin-captive archetype with polypropylene supply chain control. Garware Technical Fibres occupies a specialist position serving India's horticulture belt with certified durability products. Neo Corp International exemplifies the natural fiber premium tier where EU Green Deal procurement favors biodegradable alternatives.
| Leading Market Players |
|---|
| Belton Industries, Inc. |
| Neo Corp International Limited |
| Beaulieu Technical Textiles |
| Garware Technical Fibres Ltd. |
| SRF Ltd. |
| Hy-Tex Ltd. |
| TenCate Industrial Fabrics |
| Zhongshan Hongjun Nonwovens Co. Ltd. |
| B&V Agro Irrigation Co. |
| Others |
Supply Flow & Price Mechanics
Polyethylene replacement by UV-stabilized agro-textiles in Maharashtra and Gujarat horticulture belts simultaneously shifts procurement geography toward Nashik-Pune manufacturing corridors and compresses price premiums for certified durability grades as BIS enforcement filters out unorganized imports.
Pricing Analysis
Configured-to-order pricing for multilayer crop covers with integrated moisture-wicking layers commands 40-60% premiums over standard shade percentage specifications. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered REACH-compliant formulations from uncertified commodity polypropylene. Price differentiation hinges on certification grade and volume scale, with Maharashtra cooperatives driving bundled procurement discounts. Margins are tightening due to crude-linked resin volatility for converters lacking captive supply. Individual farmers remain most price-sensitive, while Dutch greenhouse operators exhibit lowest sensitivity given yield-outcome contract structures.
Supply Chain Analysis
Zhejiang-Jiangsu province clusters function as the dominant chokepoint for woven polypropylene fabric and raw fiber throughput serving global shade net production. Supply geography draws from China, India, and the Netherlands for differentiated manufacturing capabilities. Raw material dependencies center on propylene feedstock, calcium-zinc stabilizer packages, and specialized UV additive formulations. Single-source vulnerability concentrates in Chinese fiber production clusters exposed to MIIT industrial policy shifts. Distribution runs through direct-to-cooperative channels in India and bundled service contracts in Dutch greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agro textiles are approaching a platform-economics inflection where sensor-embedded crop covers interoperate with precision irrigation systems, creating bundled service ecosystems that restructure procurement authority around technical specification teams rather than traditional purchasing officers.
For Market Incumbents: Fortify certification infrastructure against REACH additive restriction escalations and BIS durability enforcement waves. Prioritize backward integration into polypropylene resin production to absorb feedstock volatility that threatens converter margins. Defensive positioning requires ECHA registration dossier maintenance and accredited testing facility expansion in Nashik-Pune corridors.
For New Entrants and Emerging Players: Anchor in biodegradable jute matting segments where EU Green Deal procurement criteria create premium positioning unavailable to synthetic competitors. Target erosion control applications in Bavarian public infrastructure tenders and aquaculture pond lining in Southeast Asian markets. Go-to-market execution should leverage direct-to-cooperative distribution bypassing traditional dealer networks.
For Investors and Strategic Acquirers: Capital is best deployed toward technical textile specialists with additive formulation expertise and established multi-jurisdiction certification infrastructure. Long-term viability favors manufacturers bridging commodity polypropylene throughput with specialized natural fiber premium positioning. Watch for inflection signals in biodegradability standard evolution and polymer recycling mandate enforcement across major procurement jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive polypropylene supply insulates Belton Industries from crude-linked feedstock volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous EU REACH, FDA, and BIS compliance reduces product launch cycles for Garware Technical Fibres. |
| Direct-to-Cooperative Distribution Expansion | Maharashtra horticulture federation volume procurement compresses channel margins and consolidates supplier relationships. |
| Sensor-Embedded Crop Cover Development | Dutch Westland greenhouse clusters pilot performance-based contracts tied to yield outcomes. |
| Biodegradable Natural Fiber Formulation | EU Green Deal procurement criteria open premium positioning for Neo Corp International jute erosion control mats. |
Methodological Framework
Operator-level perspectives from greenhouse technical managers, horticulture cooperative procurement directors, polypropylene plant engineers, and agro-textile distribution channel partners anchored the qualitative base. Primary interview insights combined with secondary validation from customs trade databases, BIS certification registries, ECHA substance dossiers, and SEC filings from integrated textile manufacturers. Bottom-up demand modeling across crop cover, shade net, mulch film, and insect netting segments triangulated against top-down macroeconomic drivers.
Sensitivity analysis frameworks tested forecast robustness across resin price volatility scenarios and regulatory enforcement intensity variations. Segmentation dimensions modeled include product architecture, material platform, application intensity, and end-user procurement authority. CAGRs derived from replacement cycle compression patterns in protected cultivation acreage expansion zones. Industry-specific inputs incorporated UV stabilization technical ceilings and biodegradability standard evolution timelines.
Material uncertainties — crude oil price trajectory shifts, REACH additive restriction scope expansions, and BIS enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding protected cultivation investment continuity and cooperative procurement centralization trends. Practitioners should keep alternative scenarios live as EU Green Deal procurement criteria and polymer recycling mandate enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
E-Textile Market
Technical Textiles
Geotextiles and Geogrids Market
Technical Textiles
Construction Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
US Geotextile Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
China Geotextiles Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Agri Textiles Market
Technical Textiles
Fire Retardant Fabrics Market