
 Nonwoven Geotextiles Market | 2026-2036
Nonwoven Geotextiles Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Geotextiles Market Outlook
Project finance for large-scale infrastructure is tilting competitive dynamics toward capital-backed suppliers capable of multi-year material commitments. TenCate Geosynthetics leverages its integrated manufacturing footprint across multiple continents to sustain cost-competitive bidding for drainage and stabilization contracts. Fibertex Nonwovens A/S anchors its position through specialized needle-punch capacity serving Scandinavian road authorities. NAUE GmbH & Co. KG differentiates via geogrid-geotextile composite systems that dominate German rail embankment specifications.
Nonwoven geotextiles are permeable synthetic fabrics manufactured through needle-punching, thermal bonding, or spunbonding of polypropylene or polyester fibers, typically specified by mass per unit area ranging from 100 to 1500 grams per square meter and designed to provide filtration, separation, drainage, or reinforcement in civil engineering applications. Geotextile fabrics and geotextile composites lead current volume shipments, with the latter capturing margin pools in high-strength containment and coastal defense projects where multi-layer construction commands specification premiums. Among end users, transportation infrastructure and landfill containment represent the most structurally entrenched demand verticals, while agriculture applications show faster growth in controlled-environment water management systems.
The US Federal Highway Administration and the EPA shape domestic demand through AASHTO M-288 specifications for subsurface drainage and landfill liner systems, while the EU Construction Products Regulation mandates CE marking and harmonized EN 13249-13257 testing for all geotextiles deployed in member state public works. India's BIS certification requirements and the Ministry of Road Transport's standardized bidding documents for national highway projects are tightening product traceability and performance documentation obligations. Stakeholders must monitor how evolving polymer recycling mandates and embodied carbon disclosure rules will reshape material selection criteria across public procurement frameworks.
Market Dynamics
Specification-grade procurement for Southeast Asian road and railway projects is consolidating purchasing power around suppliers capable of multi-year polymer commitments and certified EN 13249-13257 documentation. This structural concentration is compressing margins for spot-market vendors while rewarding integrated manufacturers with captive needle-punch and spunbond capacity.
Growth Catalysts
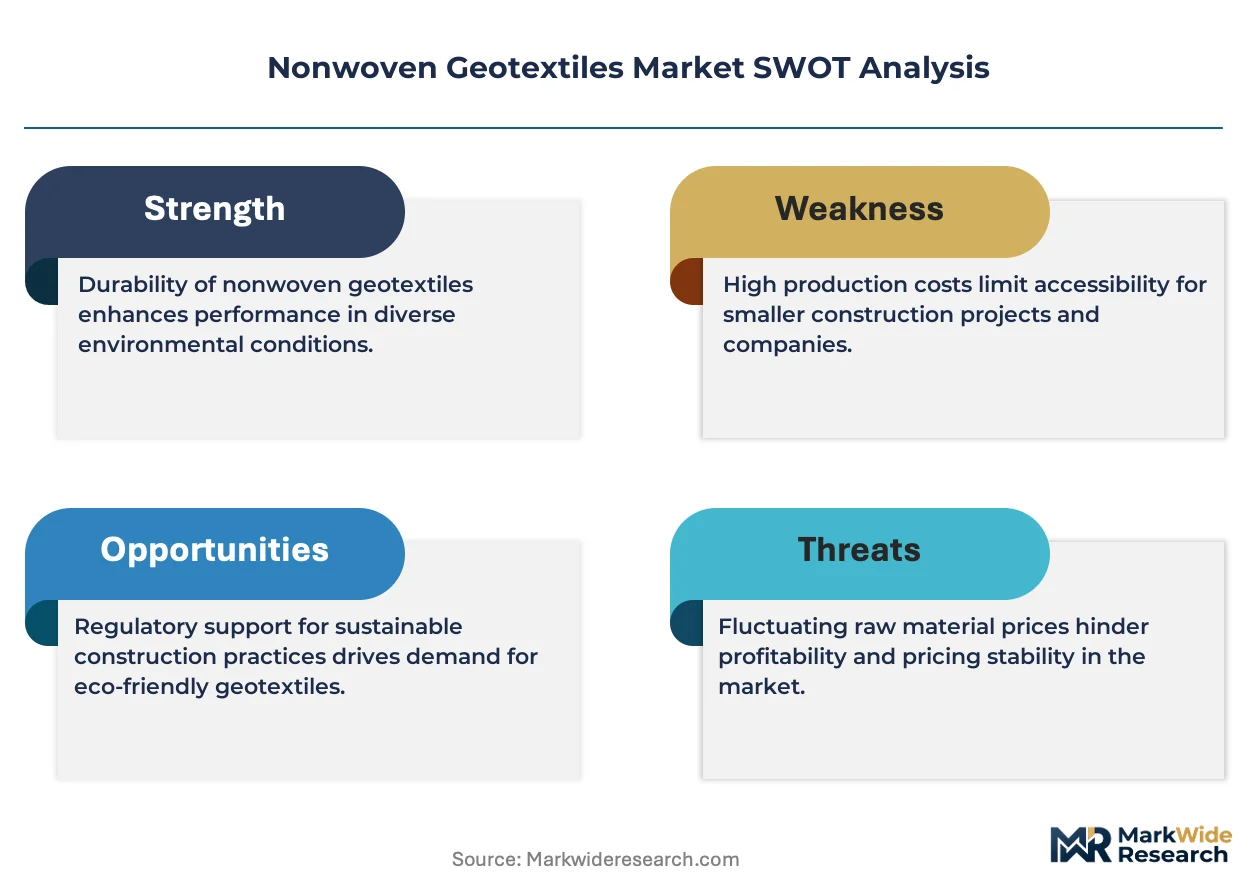
- EU Construction Products Regulation:CE marking mandates under harmonized EN standards are accelerating substitution of uncertified materials in German rail embankment and Scandinavian road authority contracts.
- India's coastal protection programs:Ministry of Road Transport standardized bidding documents for national highway and riverbank restoration projects are tightening performance documentation obligations.
- Needle-punch specification premiums:Multi-layer geotextile composites for high-strength containment applications command durable margin pools in landfill liner and coastal defense verticals.
Market Restraints
- Polypropylene feedstock volatility:Crude-linked polymer pricing swings compress margin predictability for non-integrated converters lacking backward integration into resin production.
- East Asian supply concentration:Spunbond capacity clusters in select coastal manufacturing zones create vulnerability to regional logistics disruptions and tariff friction.
- Mechanical performance ceilings:Thermal bonding yields lower tensile strength than needle-punching, limiting specification access to high-load reinforcement applications.
Strategic Opportunities
- Embodied carbon disclosure mandates:EU CSRD and emerging public procurement rules are creating specification preference for recycled-content and lower-carbon-footprint geotextile alternatives.
- Controlled-environment agriculture:Water management systems in greenhouse and hydroponic installations represent an underpenetrated end-use with faster growth trajectories than traditional civil engineering.
- Geogrid-geotextile convergence:Composite systems integrating drainage fabrics with soil reinforcement grids capture premium positioning in rail and heavy haul road specifications.
Industry Challenges
- BIS certification timelines:India's Bureau of Indian Standards product traceability requirements extend qualification cycles for new market entrants by 12-18 months.
- Polymer recycling integration:Post-consumer polypropylene feedstock quality variability complicates specification compliance for mass-per-unit-area requirements in drainage applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Geotextiles Market |
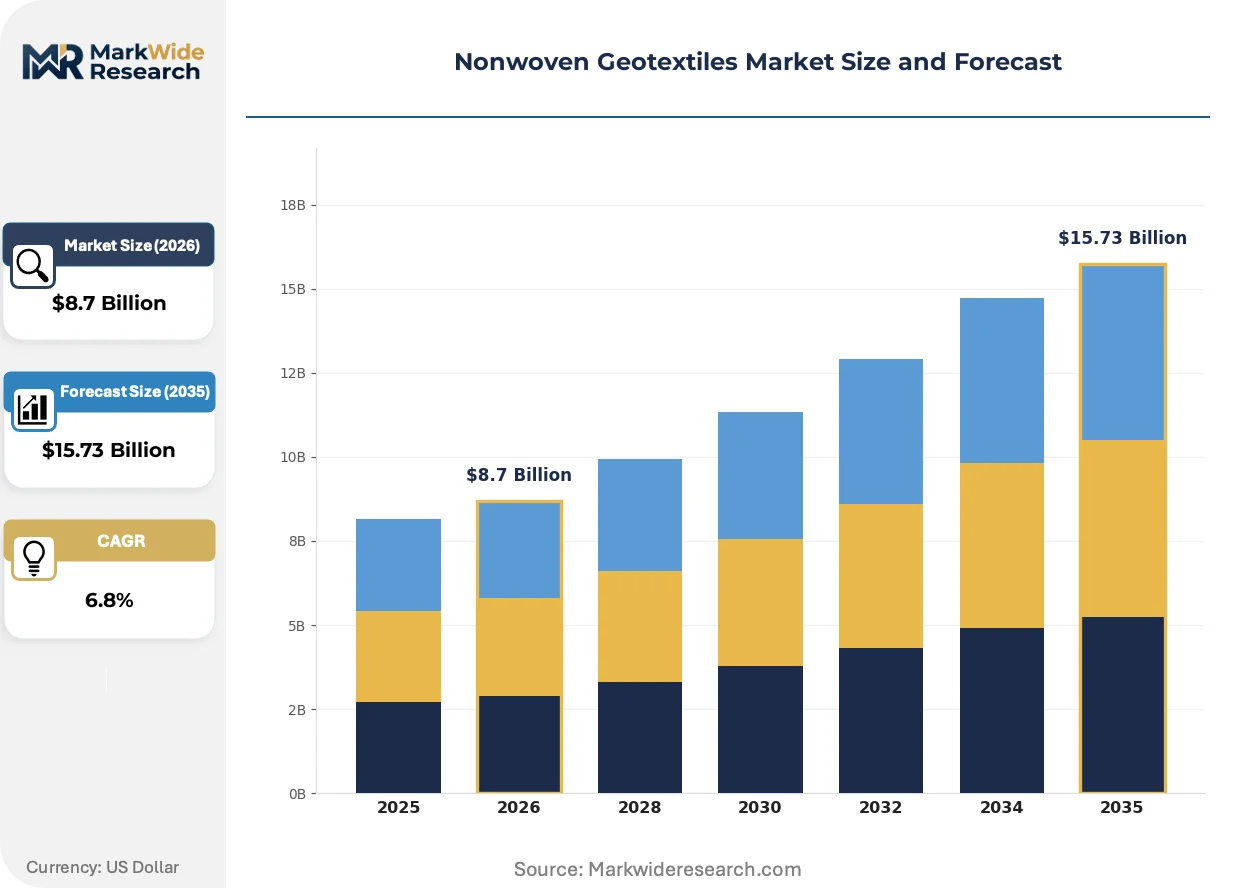
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextile Fabrics, Geotextile Mats, Geotextile Composites, Geotextile Tubes Application: Erosion Control, Drainage, Ground Stabilization, Separation End User: Construction, Landfill, Agriculture, Transportation Material: Polypropylene, Polyester, Natural Fibers, Biodegradable Polymers |
| Companies Covered | TenCate Geosynthetics, Fibertex Nonwovens A/S, NAUE GmbH & Co. KG, Berry Global Inc., HUESKER Synthetic GmbH, GSE Environmental, Low & Bonar, Officine Maccaferri, Terram Geosynthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Geotextiles Market Strategic Shifts
Digital specification tools and polymer traceability platforms are compressing traditional procurement cycles while elevating certified material transparency to a competitive differentiator in public infrastructure bidding.
Spunbond-meltblown-spunbond (SMS) multilayer fabrics are virtualizing conventional needle-punch specifications in drainage and filtration applications. German rail authorities and Dutch water management agencies have adopted SMS composites for subsurface drainage projects. This virtualization is compressing the addressable market for commodity-grade needle-punch products while opening margin pools for precision-calibrated permeability specifications.
REACH substance restrictions and EU Green Deal embodied carbon thresholds are mandating recycled-content verification across Construction Products Regulation compliance documentation. Manufacturers must now maintain polymer chain-of-custody records from resin pellet to finished roll. High-strength containment and coastal defense segments face the steepest compliance cost escalation, driving consolidation toward integrated producers with in-house recycling capabilities.
Public procurement portals in India and Southeast Asia are disintermediating traditional distributor networks for specification-grade material. State highway authorities now issue tender documents with embedded AASHTO M-288 and EN 13249-13257 testing protocols, enabling direct mill-to-contractor relationships. This channel compression is most advanced in India's national highway program, where standardized e-procurement platforms have reduced distributor margins by half.
Nonwoven Geotextiles Market Segmentation
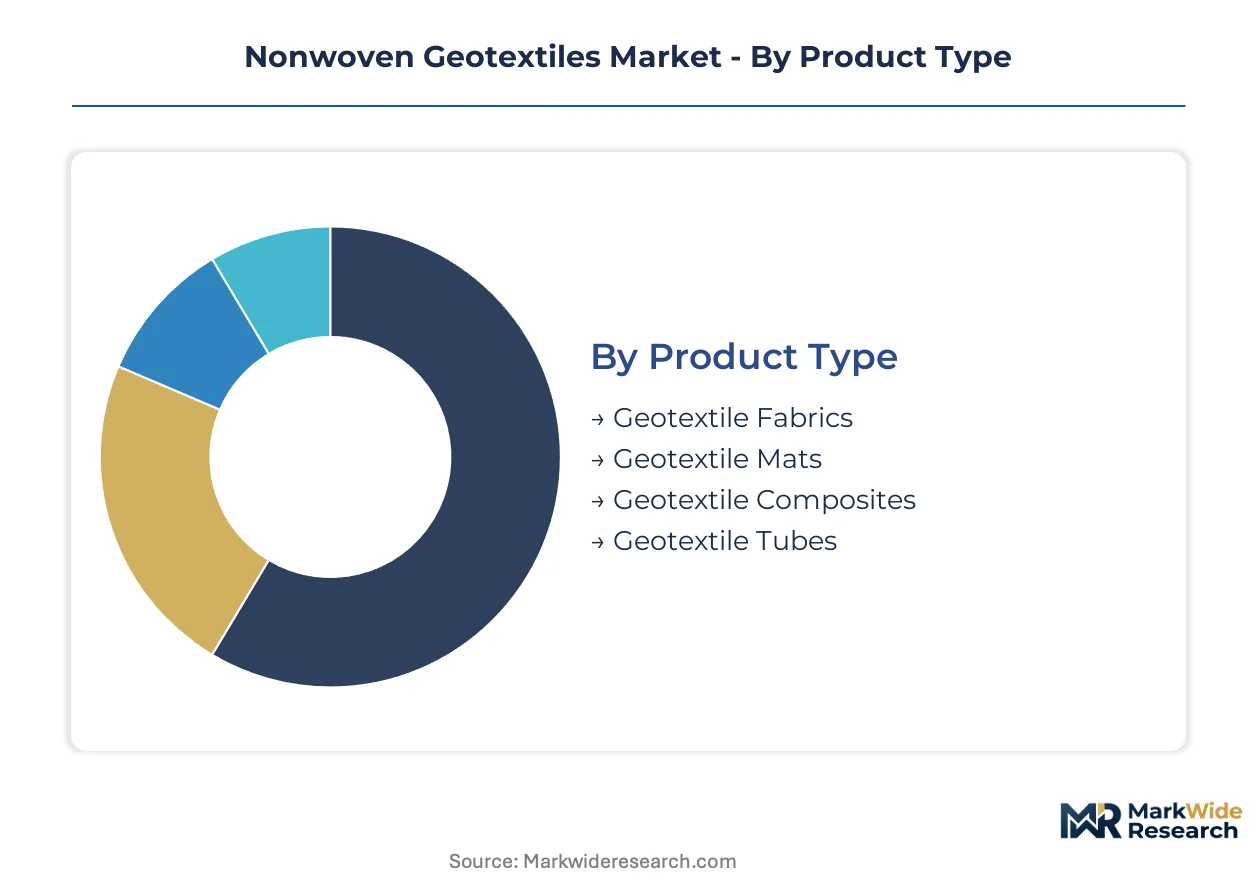
Specification-grade procurement demands precise alignment between polymer composition, mechanical performance, and end-use requirements. Material selection directly determines compliance pathways under EN 13249-13257 and AASHTO M-288 frameworks across transportation and containment verticals.
Product Type:
Mature needle-punch formats dominate volume shipments while spunbond-meltblown-spunbond laminates emerge in precision drainage specifications.
- Geotextile Fabrics:Permeable synthetic sheets manufactured through needle-punching or thermal bonding of polypropylene fibers, typically specified by mass per unit area from 100 to 1500 grams per square meter. German rail embankment contracts and Scandinavian road authority specifications concentrate demand for certified EN 13249-compliant rolls.
- Geotextile Composites:Multi-layer constructions integrating drainage fabrics with geogrids or geomembranes, commanding premium positioning in high-strength containment and coastal defense projects where multi-layer construction requires traceable polymer chain-of-custody documentation.
- Geotextile Mats:Pre-formed erosion control blankets of natural or synthetic fibers deployed on steep slopes and riverbanks.
- Geotextile Tubes:Hydraulically filled containment structures for coastal protection and dewatering applications.
Geotextile fabrics retain volume leadership; geotextile composites hold the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade drainage systems from commodity erosion control deployments.
- Drainage:Subsurface filtration and fluid transmission systems requiring precise permeability calibration and clogging resistance under sustained hydraulic loads. Dutch water management agencies and US Federal Highway Administration projects specify SMS composites for longitudinal roadway drainage.
- Erosion Control:Surface protection applications on slopes and shorelines using biodegradable or photodegradable fiber matrices. India's coastal protection programs and riverbank restoration initiatives under the Ministry of Road Transport are tightening performance documentation obligations for mat-based installations.
- Ground Stabilization:Load distribution layers beneath rail tracks and heavy haul roads.
- Separation:Interface barriers preventing subgrade contamination by overlying aggregates.
Drainage commands the premium tier; erosion control is climbing fastest on infrastructure program expansion.
End User:
Customer type determines certification intensity and contract duration, with public infrastructure requiring multi-year polymer commitments.
- Transportation:Road and railway authorities specifying AASHTO M-288 and EN 13249-13257 compliant materials for subsurface drainage, separation, and reinforcement. Southeast Asian procurement consolidation favors suppliers with captive needle-punch capacity and certified documentation systems.
- Construction:Civil engineering contractors deploying geotextiles across building foundations, retaining walls, and site drainage.
- Landfill:Containment system integrators requiring multi-layer composite liners with verified chemical resistance and seam strength.
- Agriculture:Controlled-environment water management in greenhouse and hydroponic installations.
Transportation anchors procurement scale; agriculture is gaining share fastest on greenhouse infrastructure buildout.
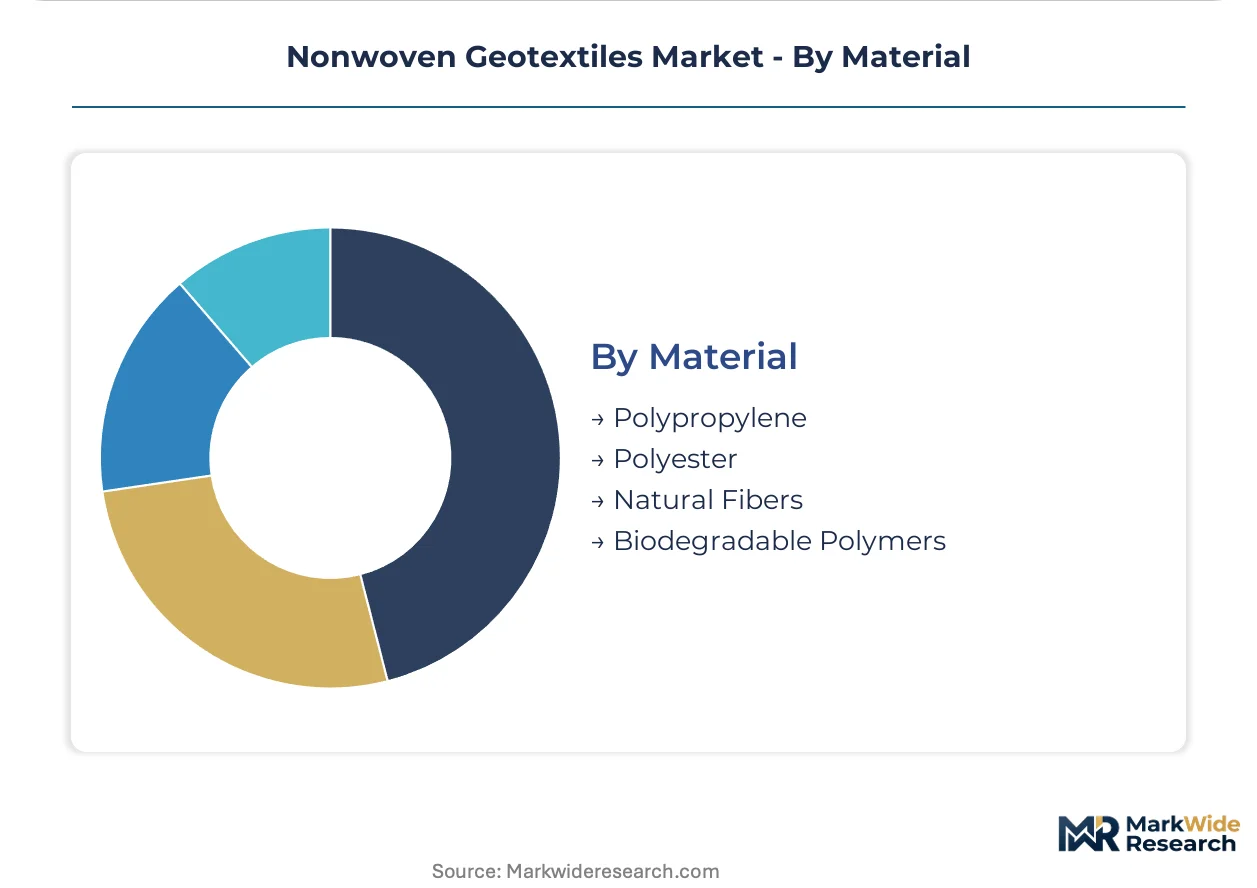
Material:
Supply concentration in polypropylene resin production shapes converter sourcing strategies and margin stability.
- Polypropylene:Dominant polymer for needle-punch and spunbond fabrics, offering chemical resistance and mechanical durability in drainage and separation applications. Crude-linked pricing volatility compresses margin predictability for non-integrated converters lacking backward integration into resin production.
- Polyester:Higher tensile strength alternative for reinforcement and high-load applications.
- Natural Fibers:Biodegradable options for temporary erosion control where vegetation establishment supersedes long-term durability.
- Biodegradable Polymers:Emerging feedstocks for EU Green Deal compliance and embodied carbon disclosure mandates.
Polypropylene retains volume leadership; biodegradable polymers hold the steepest expansion curve on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in needle-punch and spunbond grades concentrate in Germany, China, and the United States, while India and Southeast Asian markets absorb inbound material flows for infrastructure buildout. Trade balances shift as polymer feedstock costs and certification documentation requirements reshape sourcing decisions.
United States
Federal highway appropriations through the Infrastructure Investment and Jobs Act sustain specification-grade procurement for subsurface drainage and landfill liner systems. The EPA and AASHTO M-288 frameworks mandate certified material traceability for federal-aid road projects. Manufacturing clusters in the Southeast and Ohio River Valley supply domestic transportation and containment verticals.
Germany
Rail embankment stabilization and Dutch water management export demand anchor European production volumes. CE marking under EN 13249-13257 and REACH substance restrictions tighten compliance documentation for cross-border shipments. Industrial concentration in North Rhine-Westphalia and Bavaria serves Central European public works procurement.
China
Spunbond capacity expansion along coastal manufacturing zones supplies domestic high-speed rail and Belt and Road infrastructure exports. MIIT industrial standards and GB testing protocols govern material specifications for state-owned contractor procurement. Yangtze River Delta production clusters export standardized drainage fabrics to Southeast Asian markets.
India
Ministry of Road Transport national highway programs and coastal protection initiatives drive specification-grade import substitution. BIS certification requirements and standardized e-procurement platforms extend qualification timelines while compressing distributor margins. Gujarat and Maharashtra industrial corridors host emerging domestic needle-punch capacity.
Vietnam
North-South Expressway and trans-Asian railway projects concentrate multi-year material commitments from regional suppliers. Public procurement portals with embedded EN testing protocols enable direct contractor sourcing. Ho Chi Minh City and Hanoi logistics hubs intermediate Chinese and Thai material flows.
Nonwoven Geotextiles Market Competitive Environment
On the supply side, the industry is consolidating around integrated manufacturers with captive needle-punch and spunbond capacity. Tiered competitive positioning separates specification-grade certified suppliers from spot-market converters. Two strategic archetypes dominate: capital-backed multi-continent producers and specialized regional fabricators. Competitive moves center on polymer recycling integration and composite system development.
Among European integrated producers, TenCate Geosynthetics and Fibertex Nonwovens A/S occupy positions spanning certification-intensive transportation and containment verticals. NAUE GmbH & Co. KG exemplifies the specialized engineering tier with composite system capabilities. These anchors represent divergent scale-specialization strategies within a market rewarding both geographic breadth and specification depth.
| Leading Market Players |
|---|
| TenCate Geosynthetics |
| Fibertex Nonwovens A/S |
| NAUE GmbH & Co. KG |
| Berry Global Inc. |
| HUESKER Synthetic GmbH |
| GSE Environmental |
| Low & Bonar |
| Officine Maccaferri |
| Terram Geosynthetics |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin production clusters in Saudi Arabia, South Korea, and the US Gulf Coast concentrate feedstock pricing power among integrated petrochemical majors, leaving non-integrated geotextile converters exposed to crude-linked volatility while specification-grade certified suppliers capture durable margin pools in EN 13249-13257-intensive transportation contracts.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that separates specification-grade certified suppliers from spot-market converters. Price differentiation hinges on CE marking tier and volume scale, with multi-year polymer commitments commanding preferential terms. Cost compression in commodity needle-punch grades is intensifying because spunbond-meltblown-spunbond laminates displace conventional specifications in Dutch water management and German rail drainage projects. Municipal procurement officers exhibit highest price sensitivity due to fixed-budget constraints, while landfill containment integrators prioritize chemical resistance documentation over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated petrochemical suppliers have become critical working capital tools for mid-scale converters lacking backward integration. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta and North Rhine-Westphalia serving as export hubs for Southeast Asian infrastructure procurement. Raw material dependencies center on polypropylene homopolymer, polyester staple fiber, and calcium carbonate fillers. Single-source vulnerability runs through Saudi Arabian feedstock supply to European converters. Distribution runs through direct mill-to-contractor relationships enabled by India's standardized e-procurement portals and Vietnam's public tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital specification platforms and polymer traceability systems are reconfiguring this market toward platform-economics dynamics, with interoperability between contractor procurement portals and manufacturer certification databases becoming the critical ecosystem battleground.
For Market Incumbents: Build certification moats through captive EN 13249-13257 testing laboratory investments and polymer chain-of-custody documentation systems. SMS composite capacity expansion in Germany and the Netherlands defends against spunbond virtualization in drainage specifications. Backward integration into post-consumer polypropylene recycling secures feedstock against virgin resin volatility. For New Entrants and Emerging Players: Pursue controlled-environment agriculture water management systems in India's greenhouse infrastructure belt and Vietnam's high-tech agricultural zones, where specification-grade geotextile penetration remains underdeveloped. Direct contractor relationships through embedded AASHTO M-288 testing protocols in public procurement portals offer a go-to-market angle bypassing traditional distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite system manufacturing due to multi-layer lamination equipment requirements and in-house recycling capability investments. Acquisition targets should exhibit integrated needle-punch and spunbond capacity with established rail authority certifications. The signal to watch is BIS certification timeline compression in India, which would accelerate import substitution and domestic capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Post-consumer polypropylene feedstock secures specification compliance under EU Green Deal embodied carbon thresholds. |
| Composite System Development | Geogrid-geotextile laminates capture premium positioning in German rail embankment and Scandinavian road authority specifications. |
| Digital Specification Platform Deployment | Polymer traceability databases align with India's standardized e-procurement portal requirements for national highway tenders. |
| Regional Capacity Expansion | Gujarat and Maharashtra manufacturing corridors serve India's coastal protection and riverbank restoration program demand. |
| Certification Laboratory Investment | In-house EN 13249-13257 testing capability compresses qualification cycles for Southeast Asian infrastructure procurement. |
Study Parameters
Operator-level perspectives from civil engineering procurement officers, geosynthetics plant managers, polymer supply specialists, and public works contract administrators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs trade data, BIS certification registries, SEC 10-K filings of listed materials companies, and EU Construction Products Regulation compliance databases. Bottom-up volume modeling across product types, applications, and end-user segments triangulated with top-down macroeconomic absorption rates.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product format, mechanical performance tier, polymer composition, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand modeling incorporated infrastructure appropriation cycles, polymer feedstock cost trajectories, and certification documentation intensity by end-use vertical. Industry-specific inputs included AASHTO M-288 specification adoption curves and EN 13249-13257 harmonization progress across member state procurement frameworks.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands, federal highway appropriation levels, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding polymer recycling technology maturation and public procurement digitization timelines. Regulatory acceleration in India's BIS certification requirements, REACH substance restriction expansion, or breakthroughs in biodegradable polymer mechanical performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Nonwoven Weed Control Fabric Market