
 Genetically Modified Food Safety Testing Market | 2026-2036
Genetically Modified Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Genetically Modified Food Safety Testing Market Analysis
Buyer concentration across the genetically modified food safety testing landscape is broadening beyond traditional export regulators toward downstream food manufacturers and private-label retailers. SGS S.A. leverages its agricultural inspection heritage to dominate port-of-entry testing corridors in South America. Eurofins Scientific SE anchors its position through high-throughput PCR laboratory networks that serve multinational grain traders. Bureau Veritas S.A. competes on accreditation breadth, holding ISO 17025 recognition across multiple jurisdictions that traders require for cross-border acceptance.
Genetically modified food safety testing encompasses analytical verification of recombinant DNA presence, protein expression, and event-specific identification in agricultural commodities and derived products, with PCR-based methods detecting target sequences at thresholds below 0.1% w/w for regulatory compliance. The primary commercial purpose centers on trade facilitation—ensuring shipments meet importer tolerance thresholds while protecting IP associated with proprietary biotech traits. PCR-based testing methods command the largest revenue share due to their codification in EU and Brazilian reference protocols, though whole genome sequencing represents the fastest-expanding category as event authorization pipelines diversify beyond single-trait insertions. Agricultural products applications generate the deepest margin pools because pre-harvest and elevator-stage testing commands premium pricing compared with post-manufacturing verification.
The European Food Safety Authority (EFSA) and Brazil's CTNBio enforce divergent approval catalogs, forcing testing laboratories to maintain dual validation matrices that inflate operational complexity. The U.S. FDA's voluntary consultation framework contrasts with China's mandatory GMO labeling law administered by SAMR, creating asymmetric compliance burdens that laboratories must navigate. Stakeholders should monitor how asynchronous trait approvals between the EU and major producing regions reshape testing volume geography.
Market Dynamics
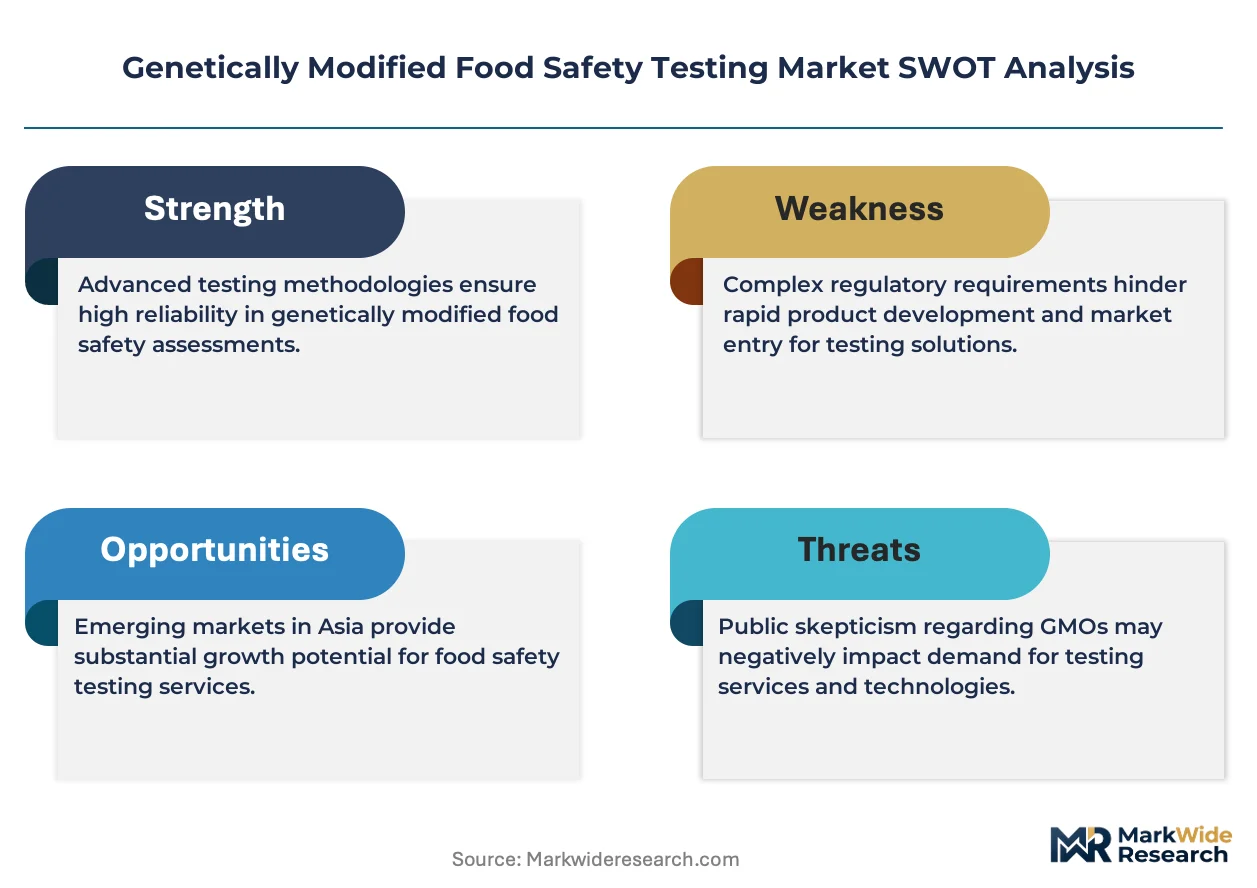
Regulatory asynchrony between major importing blocs is fragmenting testing protocols and forcing laboratories to maintain redundant validation matrices for cross-border compliance.
Growth Catalysts
- EU zero-tolerance enforcement:The European Union's unapproved GMO event prohibition drives pre-shipment screening volume at South American export terminals.
- Biotech soybean pipeline expansion:Brazil's accelerating trait authorization schedule multiplies event-specific identification requirements for commodity traders.
- PCR codification in reference protocols:Regulatory adoption of polymerase chain reaction methods standardizes detection thresholds below 0.1% w/w across major corridors.
Market Restraints
- Dual validation burden:Divergent EFSA and CTNBio approval catalogs force laboratories to maintain parallel certification systems, inflating fixed costs.
- Reagent supply concentration:Specialty PCR primer synthesis concentrates among limited European and North American chemical suppliers, exposing margins to input volatility.
- Whole genome sequencing skill scarcity:Advanced bioinformatics capabilities required for next-generation detection methods outpace technical training pipelines.
Strategic Opportunities
- Downstream manufacturer penetration:Private-label retailers and processed food producers are internalizing testing capabilities previously outsourced to port laboratories.
- Digital chain-of-custody integration:Blockchain-verified sample tracking converges with automated PCR workflows to compress certification timelines.
- China mandatory labeling compliance:SAMR-administered GMO disclosure requirements create service demand for exporters previously serving voluntary-consultation markets.
Industry Challenges
- ISO 17025 accreditation timelines:Multi-jurisdiction recognition processes delay market entry for emerging laboratory operators by twelve to eighteen months.
- Legacy LIMS integration:Agricultural elevators and grain traders operate decades-old data systems that resist API connectivity with modern sequencing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetically Modified Food Safety Testing Market |
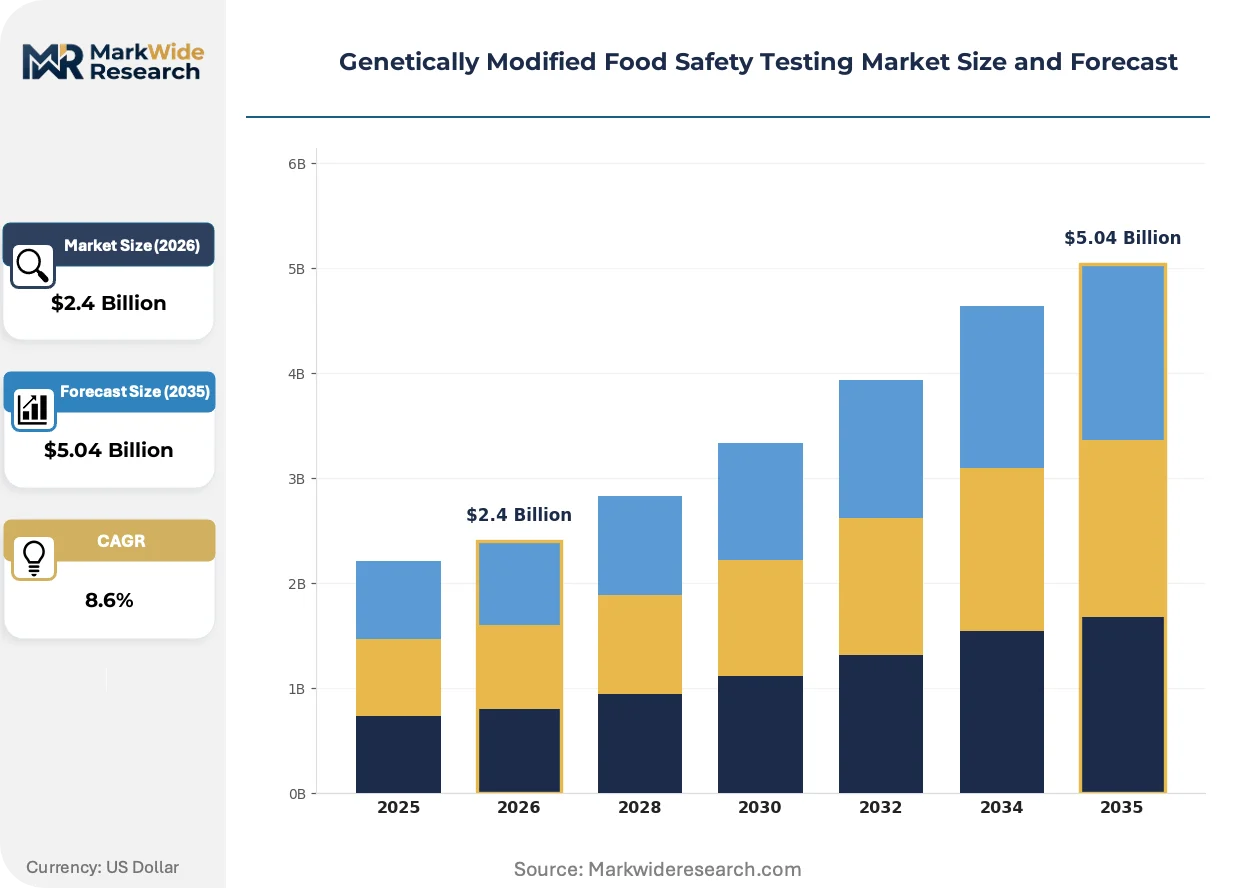
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.04 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: PCR, ELISA, Rapid Tests, Whole Genome Sequencing Application: Agricultural Products, Processed Foods, Animal Feed, Research End User: Food Manufacturers, Research Institutions, Regulatory Bodies, Laboratories Technology: Biotechnological Methods, Optical Methods, Immunological Methods, Microbial Methods |
| Companies Covered | Intertek Group plc, SGS S.A., Eurofins Scientific SE, TUV SUD AG, Thermo Fisher Scientific Inc., Bureau Veritas S.A., ALS Limited, Mérieux NutriSciences Corp., Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetically Modified Food Safety Testing Market Emerging Trajectories
Detection technology is fragmenting from standardized PCR workflows toward event-specific whole genome methods as biotech trait complexity outpaces single-target screening capacity.
Whole genome sequencing is modularizing laboratory service offerings by enabling customizable detection panels that adapt to asynchronous national approval catalogs. Multinational grain traders in Brazil and Argentina are adopting modular sequencing contracts that scale with seasonal export volumes. This modularity compresses the traditional fixed-cost structure of dedicated PCR infrastructure.
REACH-aligned substance traceability requirements are extending into agricultural commodity documentation, pressuring testing providers to expand chemical contaminant screening alongside GMO detection. Eurofins and Bureau Veritas have reconfigured their European laboratory networks to bundle these services. The combined protocol most affects soy and maize shipments entering Rotterdam and Hamburg.
Certification-driven supplier selection is displacing price-based contracting among downstream food manufacturers facing retailer ESG audits. Third-party non-GMO verification now functions as a de facto procurement prerequisite for European and North American private-label supply agreements. This preference shift concentrates contract value with laboratories holding multi-jurisdiction accreditation breadth.
Genetically Modified Food Safety Testing Market Segmentation
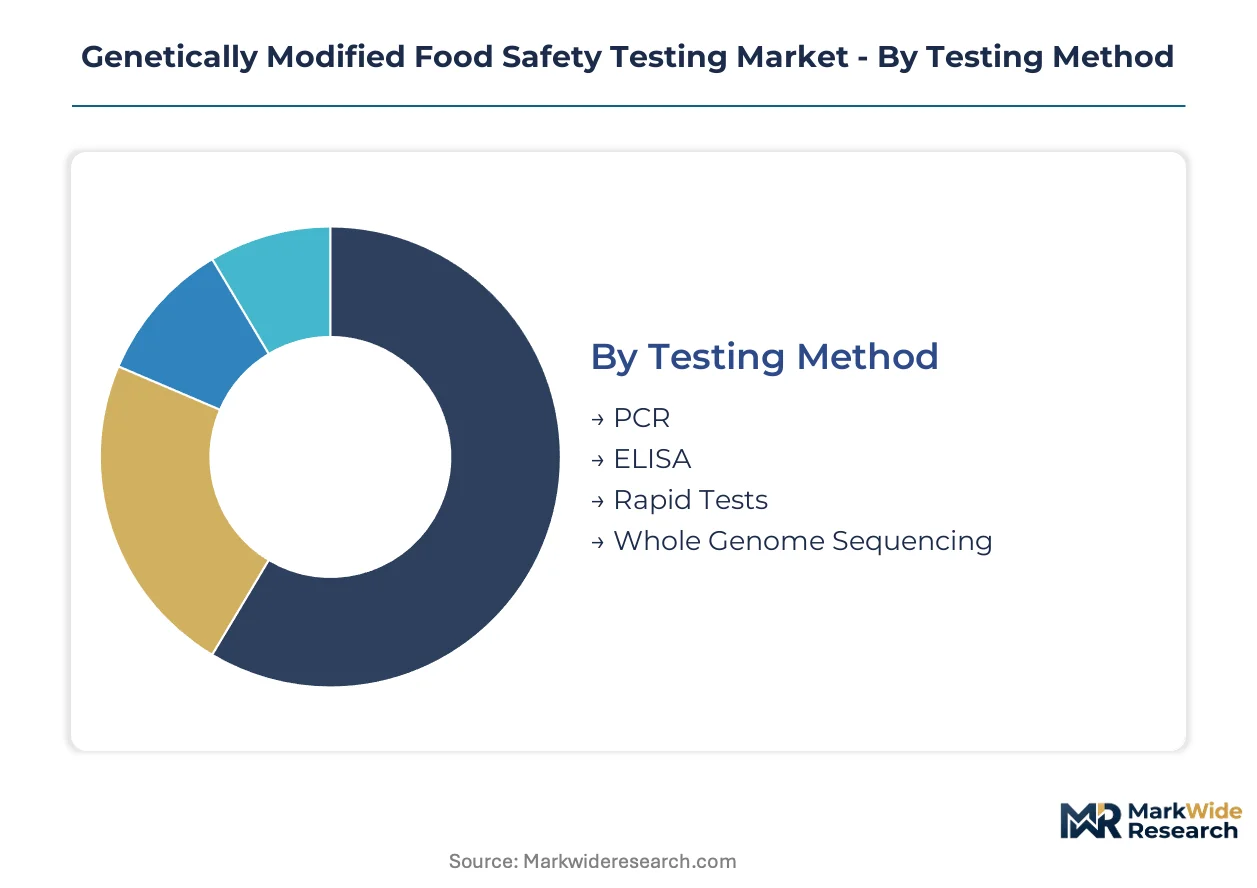
Testing demand fragments across methodological, application, and user dimensions as regulatory thresholds diverge between importing blocs. Laboratories configure service portfolios around specific detection sensitivities and accreditation requirements rather than pursuing undifferentiated coverage.
Testing Method:
Commercial buyers differentiate by detection threshold, throughput capacity, and protocol codification status in target export corridors.
- PCR:Polymerase chain reaction amplifies target DNA sequences with sensitivity below 0.1% w/w, meeting EU and Brazilian reference protocol mandates. Grain traders in Brazil deploy PCR at elevator terminals for pre-shipment verification against CTNBio and EFSA approval catalogs.
- Whole Genome Sequencing:Next-generation sequencing identifies event-specific insertions across complex stacked-trait varieties without prior sequence knowledge. Multinational traders in Argentina adopt modular sequencing contracts that scale with seasonal export volumes.
- ELISA:Enzyme-linked immunosorbent assays detect expressed proteins in bulk commodity screening where DNA degradation limits PCR utility.
- Rapid Tests:Lateral flow and dipstick formats enable point-of-use screening at grain elevators with qualitative results in under thirty minutes.
PCR leads volumes today; whole genome sequencing is gaining share fastest.
Application:
Margin structures vary sharply between upstream agricultural verification and downstream processed product certification.
- Agricultural Products:Pre-harvest and elevator-stage testing commands premium pricing due to shipment value at risk and time pressure. Soybean exporters in Brazil pay elevated rates for same-day PCR turnaround at port terminals.
- Processed Foods:Post-manufacturing verification serves private-label retailers conducting ESG audits of supplier non-GMO claims. European supermarkets require batch-specific documentation for processed maize ingredients.
- Animal Feed:Compound feed manufacturers verify ingredient streams to meet country-specific tolerance thresholds for meat and dairy export eligibility.
- Research:Trait developers and academic institutions employ reference-grade methods for event characterization and regulatory submission support.
Agricultural products dominate revenue pools; processed foods is expanding most quickly.
End User:
Procurement authority is migrating from centralized regulators toward distributed private-sector quality functions.
- Food Manufacturers:Processors of soy, maize, and canola derivatives internalize testing to secure retailer supply agreements and protect against contamination liability. North American cereal producers now operate captive PCR laboratories.
- Laboratories:Third-party service providers anchor port-of-entry and export-terminal testing corridors with multi-jurisdiction ISO 17025 accreditation. SGS and Bureau Veritas maintain dedicated facilities at Santos and Rotterdam.
- Regulatory Bodies:National enforcement agencies conduct surveillance sampling and reference method validation rather than routine commercial screening.
- Research Institutions:Universities and biotech developers purchase high-complexity sequencing services for novel event characterization.
Laboratories capture the largest contract value; food manufacturers are internalizing capabilities fastest.
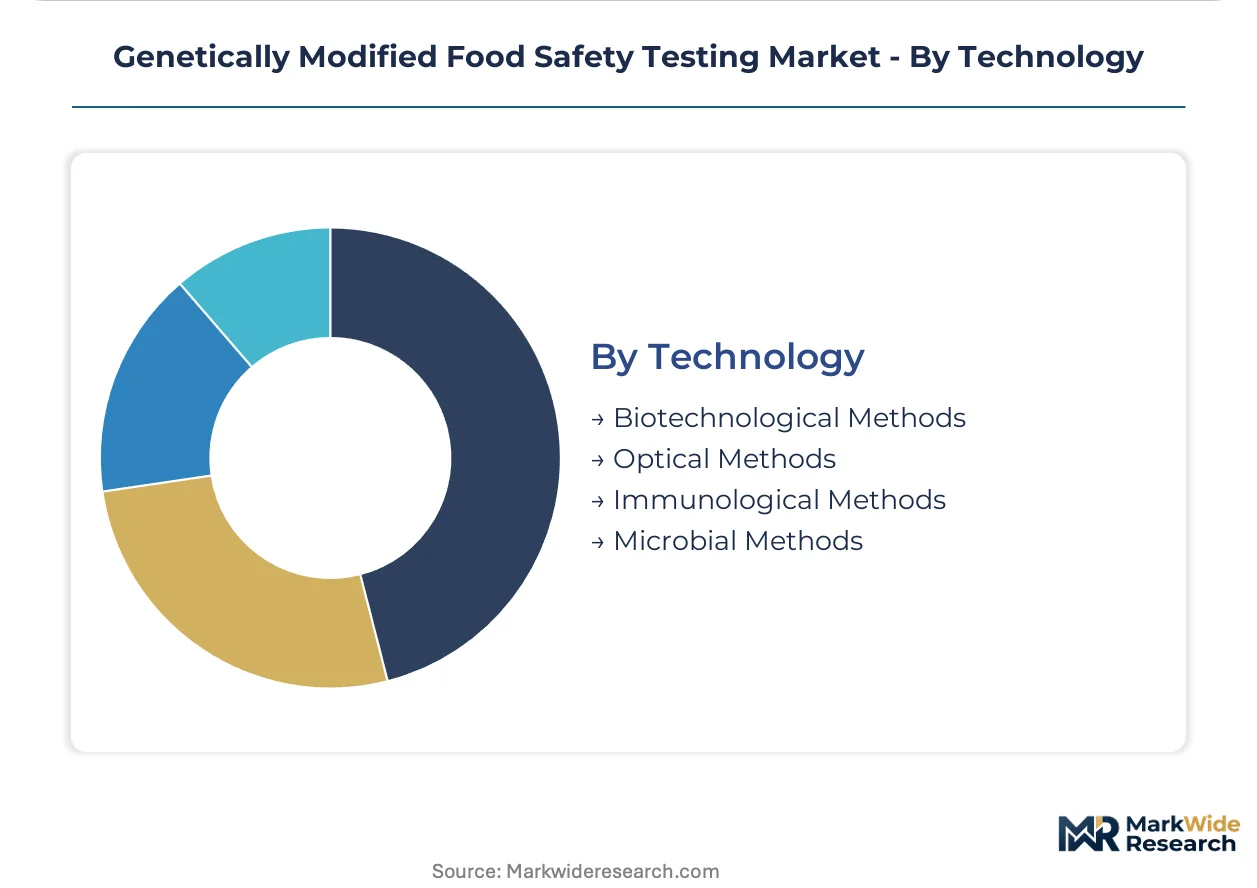
Technology:
Detection modality selection tracks the biological target—DNA, protein, or metabolite—and the required specificity level.
- Biotechnological Methods:DNA amplification and sequencing platforms deliver event-specific identification required for regulatory compliance across asynchronous approval catalogs.
- Immunological Methods:Antibody-based detection provides cost-effective protein screening for bulk commodities where trait expression confirmation suffices.
- Optical Methods:Spectroscopic and imaging techniques enable non-destructive screening at grain handling facilities with emerging sensitivity improvements.
- Microbial Methods:Culture-based and biosensor approaches serve niche applications in fermentation-derived products and probiotic verification.
Biotechnological methods anchor current infrastructure; immunological methods retain cost advantages in high-volume bulk screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's biotech soybean pipeline generates more pre-shipment testing volume than any other single country, while the European Union's zero-tolerance enforcement creates the strictest compliance corridor for exporters worldwide.
Brazil
Expanding trait authorization schedules at CTNBio multiply event-specific identification requirements for commodity traders. The National Technical Commission on Biosafety maintains approval catalogs that diverge from EFSA standards, forcing dual validation protocols. Port terminals at Santos and Paranaguá anchor South America's densest concentration of elevator-stage PCR laboratories serving soybean export corridors.
European Union
EFSA's unapproved GMO event prohibition drives systematic pre-shipment screening at Rotterdam and Hamburg entry points. REACH-aligned substance traceability requirements extend into agricultural commodity documentation, bundling chemical contaminant screening with GMO detection. Eurofins and Bureau Veritas have reconfigured laboratory networks across Germany, the Netherlands, and Belgium to capture this combined protocol demand.
United States
Voluntary FDA consultation frameworks contrast with mandatory regimes elsewhere, creating asymmetric compliance burdens for exporters. North American cereal producers now operate captive PCR laboratories to secure retailer supply agreements. Midwest grain elevators in Illinois and Iowa deploy rapid lateral flow tests for qualitative screening before elevator intake.
China
SAMR-administered mandatory GMO labeling law generates service demand for exporters previously serving voluntary-consultation markets. The State Administration for Market Regulation enforces disclosure thresholds that reshape documentation requirements for soy and maize shipments. Yangtze River Delta testing facilities in Shanghai and Jiangsu province handle peak volumes during North American harvest seasons.
Argentina
Multinational grain traders adopt modular whole genome sequencing contracts that scale with seasonal export volumes. The country's biosafety commission operates approval catalogs requiring event-specific identification for stacked-trait varieties. Rosario and Buenos Aires terminals concentrate the densest laboratory infrastructure outside Brazil for pre-shipment verification.
Genetically Modified Food Safety Testing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure characterized by multi-jurisdiction accreditation breadth rather than scale concentration alone. The vendor base organizes around three strategic archetypes: agricultural inspection heritage operators, high-throughput laboratory network operators, and accreditation-breadth competitors. Dominant competitive moves include geographic co-location with export terminals and technology licensing for next-generation sequencing capabilities.
Within the agricultural inspection tier, SGS S.A. and Bureau Veritas S.A. exemplify port-proximate positioning strategies, while Eurofins Scientific SE occupies a position representing high-throughput PCR network scale. These three entities anchor the competitive set through ISO 17025 recognition across multiple jurisdictions that traders require for cross-border acceptance. Thermo Fisher Scientific Inc. sits within the instrumentation supply tier, providing amplification platforms that underpin laboratory service delivery.
| Leading Market Players |
|---|
| Intertek Group plc |
| SGS S.A. |
| Eurofins Scientific SE |
| TUV SUD AG |
| Thermo Fisher Scientific Inc. |
| Bureau Veritas S.A. |
| ALS Limited |
| Mérieux NutriSciences Corp. |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
Multinational grain traders concentrated at Brazilian and Argentine export terminals anchor pricing power for pre-shipment PCR verification, compressing margins for laboratories competing on turnaround speed rather than accreditation breadth. Contract structures bifurcate between premium fixed-fee arrangements for elevator-stage testing and transactional spot pricing for post-manufacturing batch verification.
Pricing Analysis
Capacity additions in Brazil and Argentina are reshaping price floors for PCR-based verification services as competing laboratories crowd port-proximate locations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025 multi-jurisdiction holders from single-accreditation operators and rapid-test dipstick providers. Pricing pressure stems from reagent supply concentration among European and North American chemical suppliers. Food manufacturers internalizing captive laboratories exhibit lowest price sensitivity; commodity traders at harvest peak face acute cost pressure.
Supply Chain Analysis
Bioinformatics specialists in Germany, the United Kingdom, and Singapore face acute scarcity as whole genome sequencing adoption outpaces technical training pipelines. Specialty PCR primer synthesis draws from concentrated European chemical suppliers and North American oligonucleotide foundries. Single-source vulnerability in reagent supply exposes laboratory margins to input volatility. Distribution runs through accredited third-party service networks co-located with export terminals rather than direct manufacturer-to-buyer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genetically modified food safety testing market functions as a stable compounder, with regulatory asynchrony between major importing blocs generating durable demand for multi-jurisdiction compliance services.
For Market Incumbents: Deploy blockchain-verified sample tracking to compress certification timelines against emerging digital-native competitors. Expand ISO 17025 recognition into China's SAMR-administered jurisdiction before mandatory labeling enforcement intensifies. Backward integration into reagent synthesis reduces exposure to European chemical supplier concentration. For New Entrants and Emerging Players: Capture modular sequencing contract demand from Argentine grain traders seeking seasonal volume flexibility. Target processed food manufacturers in North America internalizing testing capabilities previously outsourced to port laboratories. Position around rapid lateral flow format deployment at Midwest grain elevators lacking legacy LIMS connectivity. For Investors and Strategic Acquirers: Agricultural inspection conglomerates are the most active acquirer in this space, consolidating ISO 17025-accredited laboratories to deepen port-proximate coverage. Five-to-ten year viability rests on laboratories holding multi-jurisdiction recognition breadth as de facto procurement prerequisites expand. Monitor asynchronous trait approval announcements between EFSA and CTNBio as volume inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Accreditation Expansion | ISO 17025 recognition across EFSA, CTNBio, and SAMR jurisdictions secures cross-border contract eligibility for grain traders. |
| Blockchain Chain-of-Custody Integration | Digital sample tracking converges with automated PCR workflows to compress certification timelines for soybean exporters. |
| Whole Genome Sequencing Capability Buildout | Next-generation detection methods address stacked-trait variety complexity outpacing single-target PCR screening capacity. |
| Downstream Manufacturer Laboratory Acquisition | Captive PCR infrastructure internalization by North American cereal producers redirects contract value from third-party providers. |
| Reagent Supply Backward Integration | In-house primer synthesis reduces margin exposure to concentrated European and North American chemical supplier pricing. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory operations directors, regulatory affairs managers at grain trading houses, certification body accreditation leads, and biotech trait development scientists with secondary validation. Regulatory filing databases including EFSA opinions, CTNBio authorization catalogs, and SAMR disclosure requirements anchored policy trajectory assessment. Trade flow data, customs documentation, and port authority throughput statistics informed volume calibration. Bottom-up laboratory capacity estimates and top-down commodity export value projections were triangulated for coherence.
Segment-weighting approaches distributed analytical focus across PCR, whole genome sequencing, ELISA, and rapid test methodologies, with additional stratification by agricultural products, processed foods, animal feed, and research applications. End-user segmentation differentiated food manufacturers, third-party laboratories, regulatory bodies, and research institutions. CAGRs were derived from regression analysis of historical testing volume against export corridor regulatory threshold changes, incorporating biotech trait pipeline authorization schedules and asynchronous approval catalog divergence as key inputs.
Underlying measurement precision varies by segment; PCR-based methods carry tighter precision than emerging whole genome sequencing categories where protocol standardization remains incomplete. Forecasts reflect assumptions regarding continued regulatory asynchrony between major importing blocs and sustained biotech soybean pipeline expansion. Material deviation in EFSA-CTNBio approval synchronization or reagent supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Shelf-Life Testing Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Food Testing Services Market