
 Europe Food Safety Testing Market | 2026-2036
Europe Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Safety Testing Market Analysis
European contract laboratory capacity is consolidating as mid-tier facilities merge to meet rising batch-testing volumes. SGS leverages its pan-European network to sustain turnaround advantages for perishable goods. Eurofins Scientific anchors its position through specialized pathogen detection protocols. Bureau Veritas differentiates via integrated certification and testing bundles for export-ready food processors.
Food safety testing encompasses analytical verification of biological, chemical, and physical hazards in food matrices using methods with detection limits at parts-per-billion sensitivity. Its primary purpose is preventing consumer exposure to pathogens, toxins, and undeclared allergens before products enter distribution. Microbiological testing leads service revenues as Salmonella and Listeria screening remains mandatory across EU member states. Molecular diagnostics represents the fastest-expanding technology segment as PCR-based methods displace slower culture techniques in high-throughput laboratories. Certification services command premium margins where exporters require dual EU-third country compliance documentation.
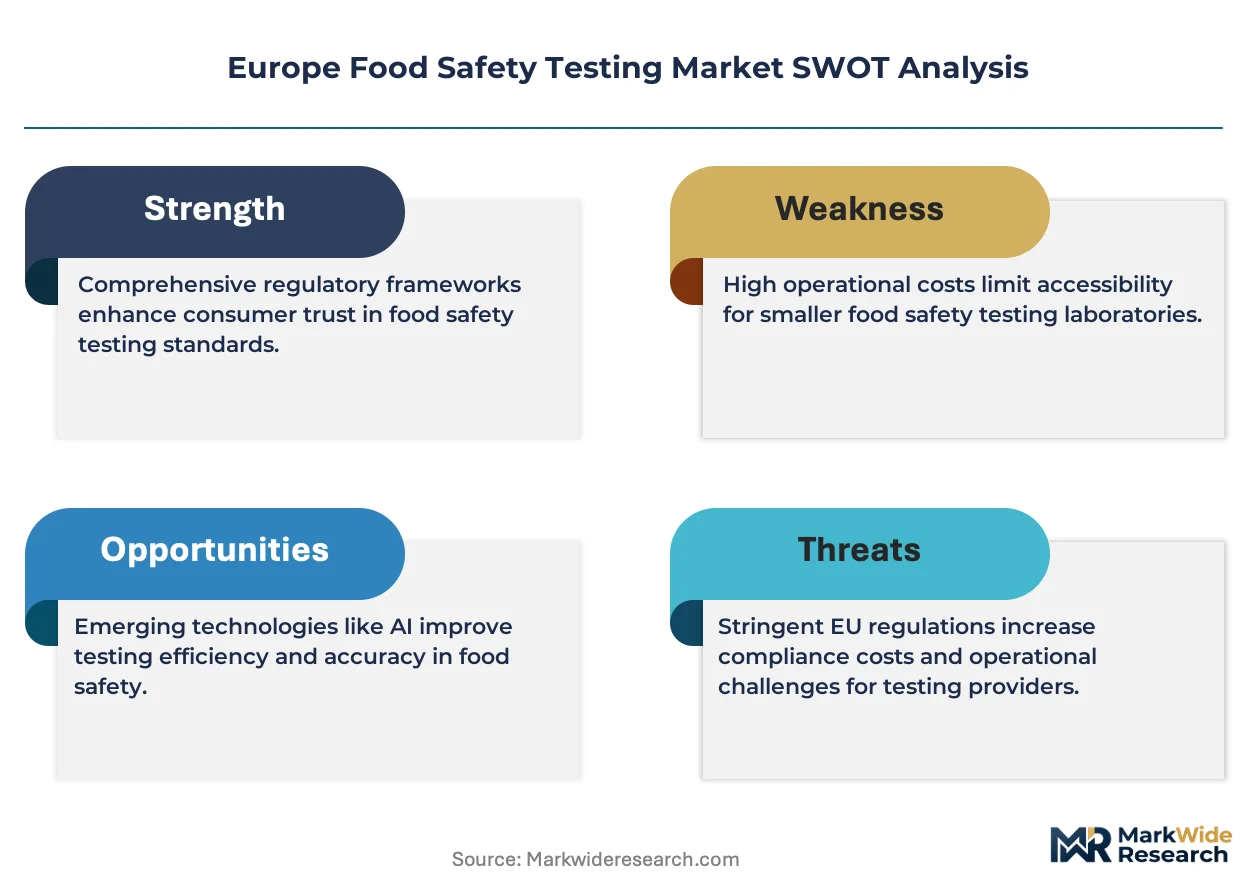
EMA coordination on veterinary drug residues, EFSA scientific opinions on emerging contaminants, and EU Green Deal pesticide reduction targets collectively tighten testing obligations for producers and importers. REACH chemical standards extend into food contact material migration testing, adding analytical scope beyond direct food matrices. Stakeholders must monitor how the EU AI Act shapes automated pathogen detection system validation requirements.
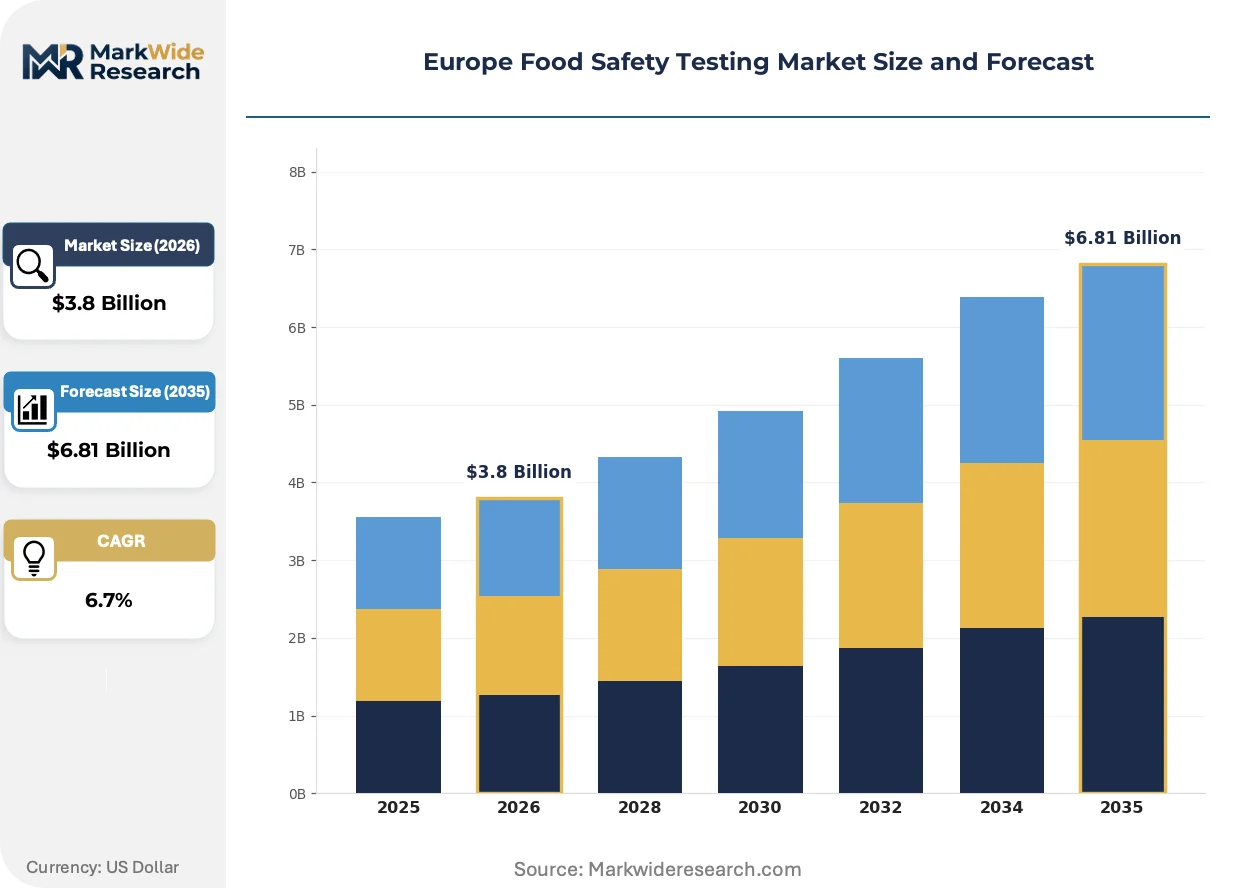
Market Dynamics
PCR-based molecular diagnostics is compressing turnaround times for pathogen screening across European contract laboratories, forcing consolidation among mid-tier facilities unable to absorb capital requirements for high-throughput automation.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory pesticide reduction targets and tightened contaminant thresholds expand mandatory testing panels for fresh produce importers and domestic growers.
- Cross-border supply chain complexity:German and French packaged food manufacturers are expanding third-party testing contracts to satisfy divergent national enforcement practices under shared EU baseline standards.
- Next-generation sequencing:Whole-genome pathogen tracing is penetrating reference laboratories, enabling outbreak source attribution that strengthens brand protection for retail chains.
Market Restraints
- Reference material scarcity:Certified reference materials for emerging mycotoxins and process contaminants face supply bottlenecks from limited European producers, inflating analytical costs.
- Capital intensity of automation:High-throughput PCR and mass spectrometry platforms require seven-figure euro investments that exclude independent laboratories from high-margin contract bidding.
- Regulatory fragmentation:EFSA scientific opinions on novel contaminants often precede harmonized enforcement by 18-24 months, creating compliance uncertainty for multi-national processors.
Strategic Opportunities
- Eastern European laboratory capacity:Poland and Romania present underpenetrated markets where EU accession-aligned regulatory infrastructure supports greenfield contract laboratory development.
- EU AI Act validation protocols:Automated pathogen detection systems require certified algorithmic transparency, creating first-mover advantage for laboratories with established machine learning quality management.
- Blockchain-integrated certification:Immutable testing documentation is penetrating premium retail and export channels, commanding margin premiums for laboratories with digitized chain-of-custody systems.
Industry Challenges
- Bioinformatics talent scarcity:Shortage of trained personnel for genomic data interpretation limits expansion of whole-genome sequencing services beyond flagship facilities.
- Legacy LIS integration:Older laboratory information systems require costly middleware development to interface with automated sample handling and regulatory reporting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Safety Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Testing, Chemical Testing, Allergen Testing, Nutritional Analysis Technology: Molecular Diagnostics, Immunoassays, Chromatography, Spectroscopy End User: Food Manufacturers, Retailers, Laboratories, Regulatory Agencies Service Type: Consulting Services, Verification Services, Training Services, Certification Services |
| Companies Covered | SGS, Eurofins Scientific, Intertek Group plc, ALS Limited, Bureau Veritas, Mérieux NutriSciences, TÜV SÜD, Thermo Fisher Scientific, Bio-Rad Laboratories, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Safety Testing Market Emerging Trajectories
Digitalization of analytical workflows and convergence of detection technologies are restructuring competitive advantage around speed, traceability, and predictive risk modeling rather than raw analytical capacity.
Digital PCR platforms are expanding into routine Salmonella and Listeria screening previously dominated by culture-based methods. Large retail-owned laboratories in the Netherlands and Belgium are adopting these systems to compress batch-release timelines for perishable goods. The technology is expanding into smaller contract laboratories through rental and service-based procurement models that circumvent upfront capital barriers.
REACH chemical standards now extend mandatory testing obligations to food contact material migration, adding analytical scope beyond direct food matrices for importers of packaging-intensive products. ECHA enforcement prioritization on per- and polyfluoroalkyl substances is redirecting laboratory capacity toward fluorinated compound detection in coated food packaging. German processors with integrated packaging operations are responding by bringing migration testing in-house to control documentation timelines.
Retailers are unbundling certification from testing services, directly accrediting preferred laboratories while maintaining separate relationships with certification bodies for dual EU-third country compliance. This disintermediation compresses margins for bundled service providers and rewards laboratories with standalone analytical excellence reputations. The pattern is most visible in Scandinavian markets where ICA and Coop chains maintain approved laboratory lists with strict turnaround penalties.
Europe Food Safety Testing Market Segmentation
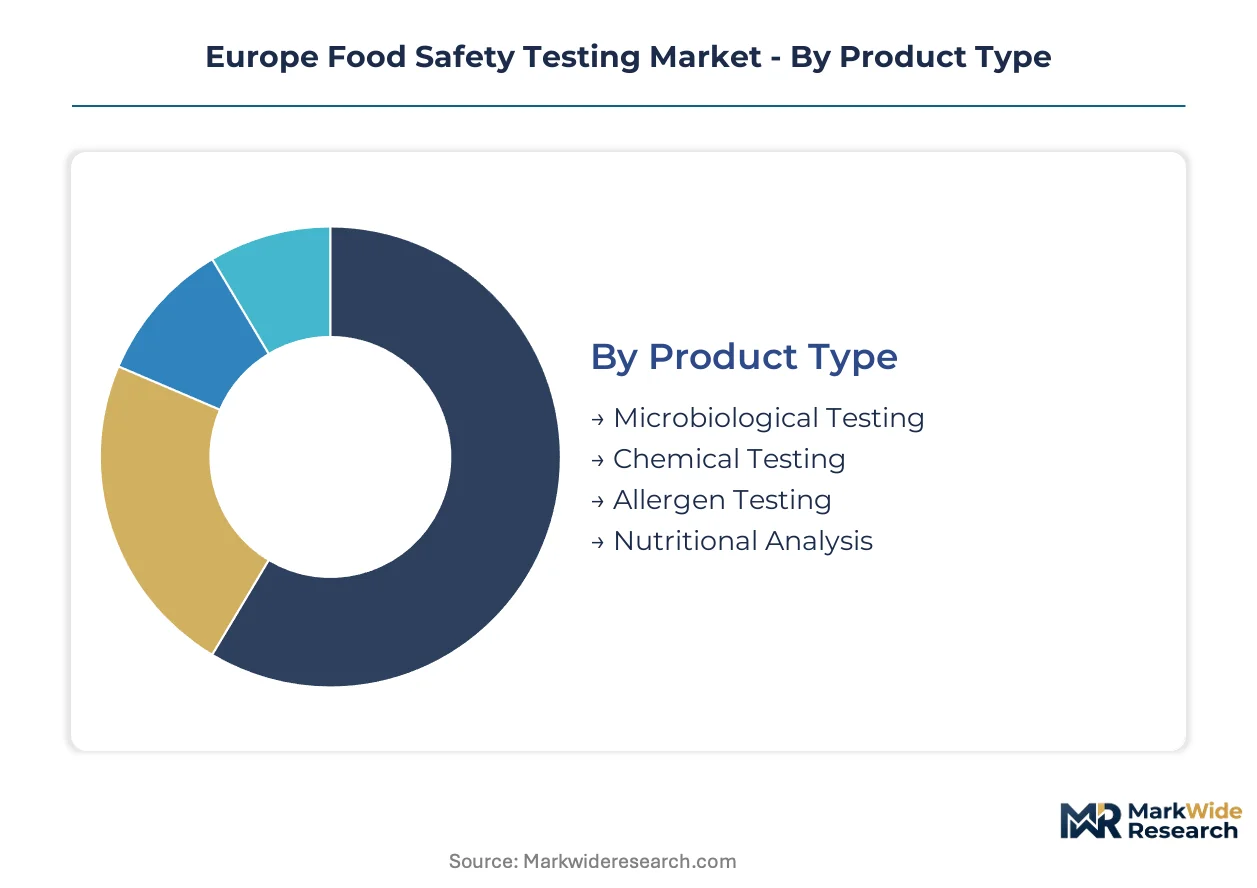
Segmentation in the Europe Food Safety Testing Market reflects divergent buyer priorities across supply chain positions. Laboratories select technologies based on throughput requirements, while manufacturers prioritize compliance breadth against per-unit testing economics.
Product Type:
Buyer-decision drivers center on regulatory mandate intensity and batch-release velocity for perishable goods.
- Microbiological Testing:Pathogen screening for Salmonella, Listeria, and E. coli using culture-based and molecular methods. German and French packaged food manufacturers concentrate demand here due to mandatory EU-wide batch testing requirements for ready-to-eat products.
- Chemical Testing:Residue analysis for pesticides, veterinary drugs, and heavy metals at parts-per-billion detection limits. Fresh produce importers in the Netherlands and Spain drive expansion as EU Green Deal pesticide reduction targets tighten maximum residue limits.
- Allergen Testing:Detection of undeclared milk, egg, peanut, and gluten proteins in processed foods. Retail chains in Scandinavia mandate supplier adherence to strict labeling verification protocols.
- Nutritional Analysis:Quantification of macronutrients, vitamins, and minerals for label compliance. Functional food producers in Italy and Switzerland utilize these services for health claim substantiation.
Volume sits with Microbiological Testing; growth tilts toward Chemical Testing.
Technology:
Capital intensity and detection sensitivity differentiate procurement tiers across laboratory scale.
- Molecular Diagnostics:PCR-based and digital PCR platforms enabling rapid pathogen identification with same-day turnaround. High-throughput contract laboratories in Belgium and the Netherlands are displacing slower culture methods for perishable goods release.
- Immunoassays:Enzyme-linked immunosorbent assays for allergen and mycotoxin screening at moderate sensitivity. Mid-tier facilities in Poland and Romania rely on these for cost-effective routine monitoring.
- Chromatography:Liquid and gas chromatography coupled with mass spectrometry for complex chemical residue identification. Reference laboratories in Germany and France anchor multi-residue pesticide panels.
- Spectroscopy:Infrared and Raman techniques for rapid compositional screening. Portable implementations are penetrating field-based inspection workflows at border control points.
Adoption concentrates in Molecular Diagnostics; margin expansion favors Chromatography.
End User:
Testing volume correlates with supply chain position and regulatory exposure surface.
- Food Manufacturers:In-house and contracted testing for HACCP verification and batch release. Large German processors maintain captive laboratories while mid-tier firms outsource to pan-European networks.
- Retailers:Approved laboratory lists with strict turnaround penalties for private-label suppliers. ICA and Coop chains in Scandinavia directly accredit preferred testing facilities.
- Laboratories:Contract service providers serving cross-border supply chains. SGS and Eurofins Scientific anchor capacity in Western European clusters.
- Regulatory Agencies:Official control laboratories enforcing EU harmonized standards. EFSA scientific opinions inform national enforcement prioritization.
Procurement authority rests with Food Manufacturers; contract expansion tilts toward Retailers.
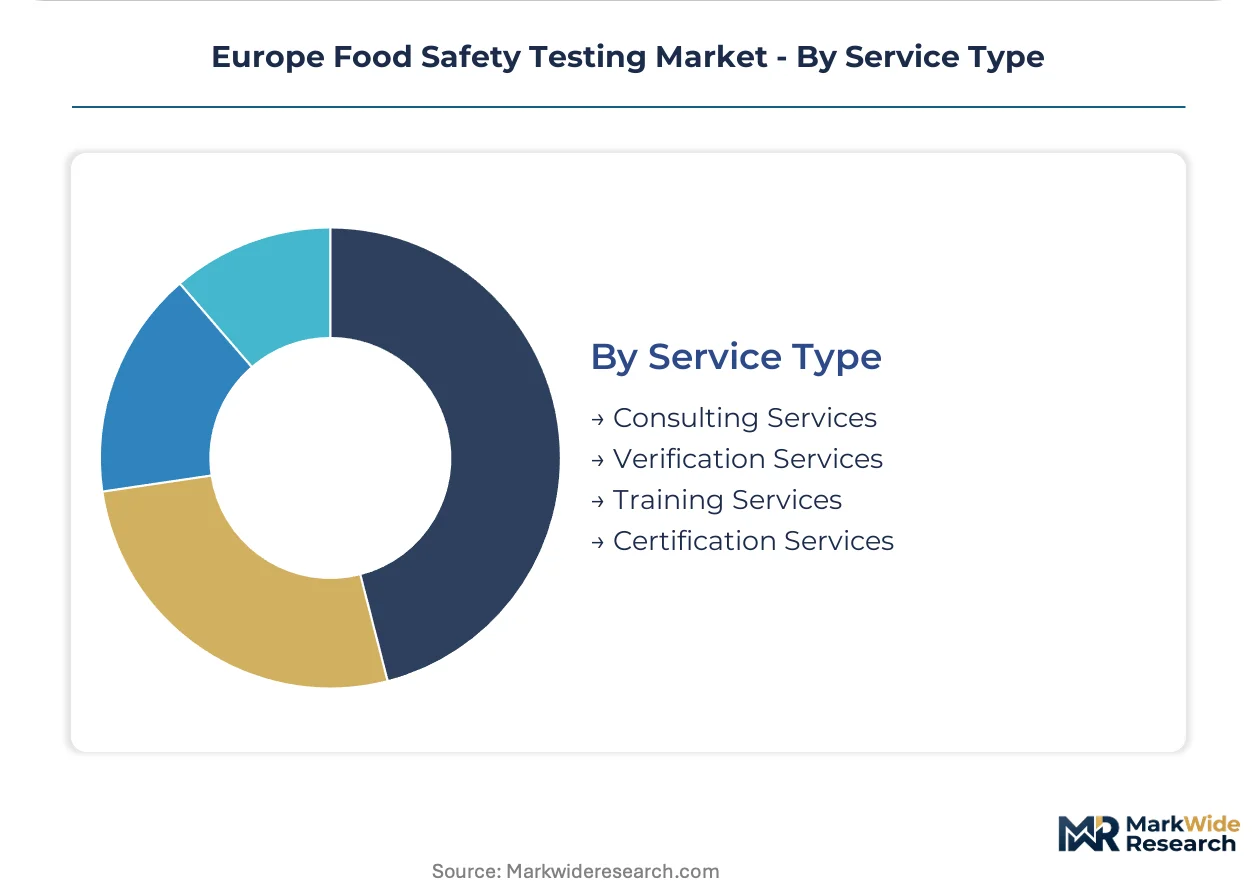
Service Type:
Margin structure separates transactional testing from recurring compliance relationships.
- Consulting Services:Risk assessment and HACCP system design for facility qualification. Exporters to dual-jurisdiction markets require specialized guidance on EU-third country alignment.
- Verification Services:Batch-specific analytical confirmation against specification. High-frequency perishable goods testing commands premium pricing for compressed turnaround.
- Training Services:Personnel certification for sampling and analytical technique. Laboratory accreditation maintenance drives recurring demand.
- Certification Services:Third-party attestation for BRC, IFS, and organic standards. Disintermediation trends compress bundled margins as retailers separate testing from certification relationships.
Revenue stability characterizes Certification Services; growth velocity favors Verification Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European laboratory clusters anchor capacity concentration, with feedstock proximity to major food processing zones driving testing demand intensity across the continent.
Germany
Packaged food manufacturers in Bavaria and North Rhine-Westphalia expand third-party testing contracts for Salmonella and Listeria screening under mandatory EU batch-release rules. The country's national food safety regulator enforces strict HACCP verification protocols. Berlin-Brandenburg hosts reference laboratories specializing in multi-residue pesticide panels for fresh produce importers.
France
Fresh produce growers in Provence-Alpes-Côte d'Azur face tightened contaminant thresholds from the EU Green Deal Farm to Fork Strategy. EFSA scientific opinions on emerging mycotoxins inform national enforcement prioritization. The Île-de-France cluster concentrates chromatography capacity for complex chemical residue identification serving cross-border supply chains.
Netherlands
Large retail-owned laboratories in the Randstad region adopt digital PCR platforms to compress batch-release timelines for perishable goods. REACH chemical standards extend testing obligations to food contact material migration. Rotterdam's border inspection infrastructure deploys portable spectroscopy for rapid field-based screening of incoming shipments.
Belgium
High-throughput contract laboratories in Flanders displace slower culture methods with PCR-based molecular diagnostics for pathogen screening. The EU AI Act shapes automated detection system validation requirements for facilities serving pan-European clients. Brussels anchors certification services for dual EU-third country compliance documentation.
Poland
Mid-tier facilities in the Warsaw and Kraków metropolitan areas rely on immunoassays for cost-effective routine allergen and mycotoxin monitoring. EU accession-aligned regulatory infrastructure supports greenfield contract laboratory development. Eastern European capacity expansion targets underpenetrated markets with lower automation barriers.
Europe Food Safety Testing Market Vendor Landscape
Global majors compete with regional champions across certification and testing bundles, creating a tiered structure where pan-European networks face pressure from specialized national facilities. Consolidation accelerates among mid-tier laboratories unable to absorb seven-figure euro investments in high-throughput automation. Three archetypes dominate: integrated certification-testing providers, pure-play analytical specialists, and retail-captive laboratory operations. M&A activity concentrates on molecular diagnostics capability acquisition, while capacity expansion targets Eastern European greenfield sites.
Within the integrated services tier, SGS and Bureau Veritas occupy positions spanning certification and analytical verification, with SGS leveraging its network breadth and Bureau Veritas emphasizing bundled export-readiness documentation. Eurofins Scientific exemplifies the pure-play analytical specialist archetype, anchoring reputation through pathogen detection protocol development. These three entities represent contrasting strategic postures toward retailer disintermediation trends and automation capital requirements.
| Leading Market Players |
|---|
| SGS |
| Eurofins Scientific |
| Intertek Group plc |
| ALS Limited |
| Bureau Veritas |
| Mérieux NutriSciences |
| TÜV SÜD |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Others |
Supply Flow & Price Mechanics
Bioinformatics talent concentration in Belgium and the Netherlands widens pricing-tier spreads between genomic-capable reference laboratories and routine testing facilities, compressing margins for mid-tier operators unable to absorb automation capital requirements.
Pricing Analysis
Warranty and service-bundling unbundling reshapes contract structures as retailers separate testing from certification relationships. Three-tier pricing structure across premium, standard, and economy levels differentiates by turnaround velocity and detection sensitivity, with PCR-based molecular diagnostics commanding premium positioning. Cost compression in standard-tier immunoassay services is intensifying because digital PCR platform rentals erode volume-based economies. Small Polish and Romanian contract laboratories exhibit highest price sensitivity; pan-European networks with integrated certification maintain pricing power.
Supply Chain Analysis
Certification and qualification gating through ISO 17025 and EU AI Act validation protocols concentrates analytical instrument supply among German, Swiss, and Dutch manufacturers. High-throughput PCR and mass spectrometry platforms draw from specialized optical component foundries and rare-earth magnet suppliers. Single-source vulnerability in certified reference materials for emerging mycotoxins inflates analytical costs. Distribution runs through pan-European logistics networks serving cross-border supply chains with temperature-controlled sample integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Food Safety Testing Market operates as a cost-of-compliance story where EU Green Deal Farm to Fork Strategy mandates create barrier-to-entry moats for laboratories with accredited contaminant detection protocols.
For Market Incumbents: Deepen vertical integration into food contact material migration testing to capture REACH chemical standards expansion. Acquire bioinformatics talent pools in Warsaw and Kraków to offset genomic data interpretation bottlenecks threatening whole-genome sequencing service expansion. Consolidate mid-tier facilities in Eastern Europe before automation capital requirements exclude independent competitors from high-margin contract bidding.
For New Entrants and Emerging Players: The price-point gap between premium digital PCR pathogen screening and economy-tier culture methods opens white-space in rental and service-based procurement models for smaller contract laboratories. Target Poland and Romania for greenfield development where EU accession-aligned regulatory infrastructure supports lower automation barriers. Pursue retail-direct accreditation relationships bypassing bundled certification intermediaries.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play analytical specialists given retailer disintermediation trends compressing integrated certification-testing margins. Five-to-ten year viability favors laboratories with established machine learning quality management for EU AI Act validation protocols. Watch EFSA scientific opinion-to-enforcement lag times as inflection indicator for compliance uncertainty creating acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Molecular Diagnostics Capability Acquisition | PCR platform deployment accelerates pathogen screening turnaround for perishable goods release. |
| Eastern European Greenfield Expansion | Poland and Romania laboratory development captures underpenetrated markets with lower capital barriers. |
| Blockchain-Integrated Certification Investment | Immutable testing documentation commands margin premiums in premium retail channels. |
| EU AI Act Validation Protocol Development | Certified algorithmic transparency creates first-mover advantage for automated detection systems. |
| Food Contact Material Migration Testing Integration | REACH chemical standards extension adds analytical scope beyond direct food matrices. |
Methodological Framework
Document review covered EFSA scientific opinions, EU Green Deal policy frameworks, and REACH chemical standards enforcement prioritization, complemented by interviews with contract laboratory operations directors, food manufacturer quality assurance leads, retail chain procurement managers, and regulatory agency enforcement officers. Secondary validation drew from EMA veterinary drug residue guidelines, customs import inspection data, and laboratory accreditation body records. Bottom-up testing volume estimates triangulated against top-down market sizing across technology and service type segments.
Market value and volume outputs synthesize analytical frameworks spanning microbiological, chemical, allergen, and nutritional testing categories across molecular diagnostics, immunoassay, chromatography, and spectroscopy technology tiers. CAGRs derive from regression analysis of historical contract laboratory expansion patterns and regulatory mandate intensity trajectories. Forecast inputs incorporate EU AI Act implementation timelines and digital PCR platform adoption curves in perishable goods supply chains.
Inputs from EFSA scientific opinion databases and national enforcement agency inspection records were available through the study window; gaps in emerging mycotoxin reference material production data introduce uncertainty bands around chemical testing segment projections. Forecasts reflect assumptions regarding EU Green Deal pesticide reduction target adherence and cross-border supply chain complexity evolution. A model refresh is warranted upon material change in EFSA scientific opinion-to-harmonized enforcement lag times.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Tester Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Global Dairy Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Fruit & Vegetable Wash Market