
 Food Safety Testing Services Market | 2026-2036
Food Safety Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Food Safety Testing Services Market Foresight
Subscription-based pathogen monitoring is decoupling food safety testing from one-off laboratory contracts. Eurofins Scientific leverages its laboratory network to anchor recurring revenue streams across North American and European food processors. SGS competes through specialized allergen testing programs that sustain long-term client relationships with multinational dairy and meat producers.
Food safety testing services encompass analytical procedures that detect biological, chemical, and physical hazards in food products using methods such as polymerase chain reaction for pathogen identification and high-performance liquid chromatography for contaminant quantification, ensuring compliance with health standards before products reach consumers. Microbiological testing dominates service revenue due to persistent salmonella and listeria concerns in meat and poultry supply chains, while allergen testing commands premium pricing as undeclared ingredient liability drives manufacturer investment. Chemical analysis remains a mature segment with steady volume but compressed margins as standard pesticide residue panels commoditize across quality assurance labs.
The FDA enforces Hazard Analysis Critical Control Point mandates that shape testing frequency and documentation requirements for domestic and imported food shipments. EFSA and national regulators under EU regulation 2073/2005 define microbiological limits that directly determine which analytical methods laboratories must validate for market access. China's SAMR implements GB standards that require localized testing partnerships for foreign brands entering domestic retail channels. Stakeholders must monitor evolving detection technology thresholds and regulatory reciprocity agreements that will determine which laboratories retain cross-border testing authorization.
Market Dynamics
Regulatory reciprocity agreements are fragmenting laboratory authorization networks, forcing testing providers to establish redundant in-country facilities rather than serving cross-border clients from centralized hubs.
Growth Catalysts
- EU Regulation 2073/2005:Microbiological criteria mandates for ready-to-eat foods compel meat processors to triple validation testing frequency at critical control points.
- Polymerase chain reaction (PCR) platforms:Pathogen detection cycle times have collapsed from days to hours, enabling real-time release decisions at poultry slaughter facilities.
- China:SAMR enforcement of GB standards for imported dairy products requires foreign brands to contract domestic testing partnerships, creating captive demand for accredited laboratories.
Market Restraints
- Reference material costs:Certified pathogen strains and matrix-matched standards for method validation consume 15-25% of operational budgets at mid-sized laboratories.
- Technical limitation:Rapid detection methods for viable but non-culturable pathogens remain unvalidated for regulatory acceptance, forcing parallel cultural confirmation.
- Regulatory friction:Divergent FDA and EFSA approval timelines for novel diagnostic platforms delay commercial deployment by 18-36 months.
Strategic Opportunities
- India:FSSAI modernization of food testing infrastructure creates first-mover advantage for laboratories establishing ISO 17025-accredited facilities in Maharashtra and Gujarat.
- Blockchain-integrated testing:Immutable chain-of-custody records are modularizing audit trails, enabling premium pricing from organic and specialty food exporters.
- Cell-based meat:Novel protein production methods lack established safety frameworks, opening method development contracts for early regulatory engagement.
Industry Challenges
- PhD-level microbiologists:Shortage of method validation specialists extends ISO 17025 accreditation timelines and inflates recruitment costs.
- Laboratory information management systems (LIMS):Legacy data architectures resist integration with cloud-based client portals, delaying automated reporting deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Safety Testing Services Market |
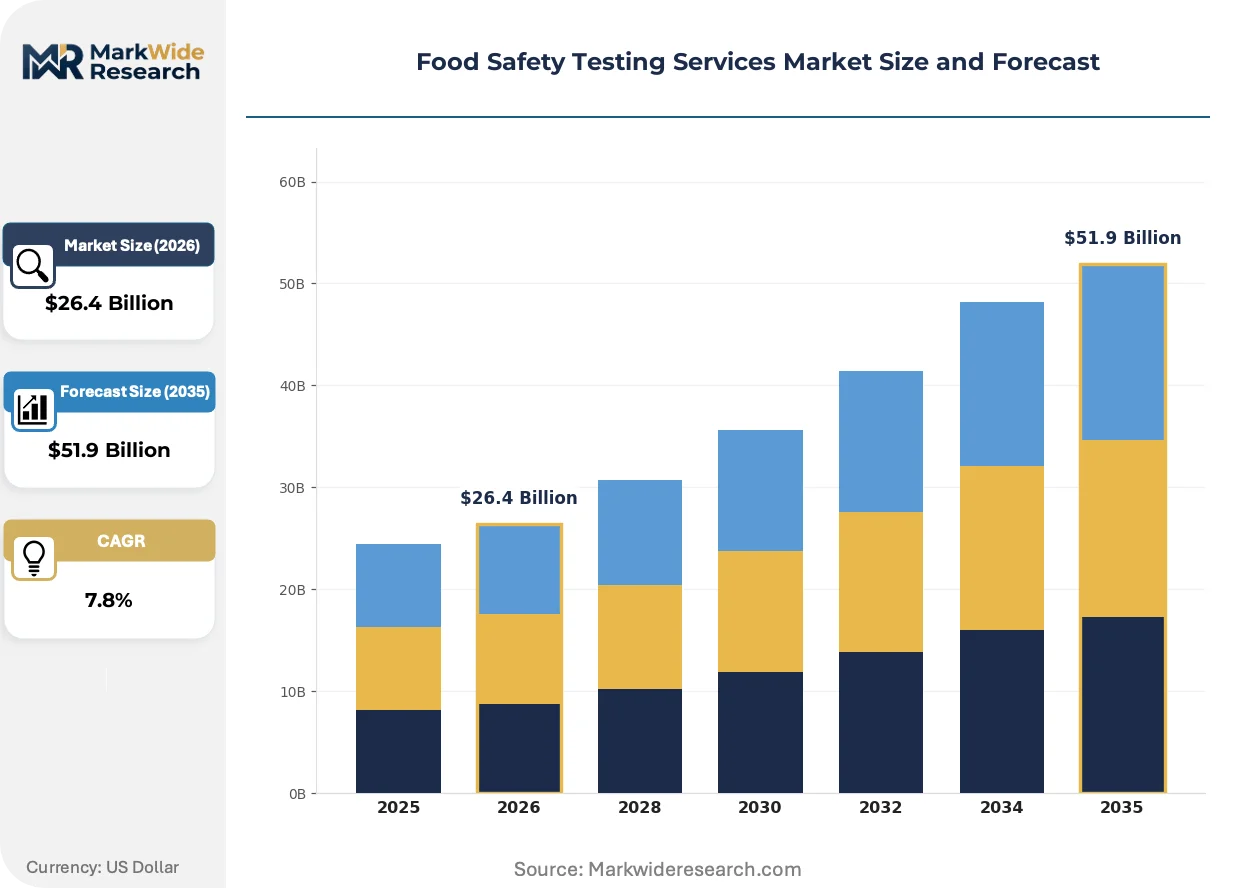
| Market Size in 2026 | $26.4 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Chemical Analysis, Allergen Testing, Nutritional Assessment, Sensory Evaluation Application: Dairy Products, Meat & Poultry, Seafood, Fruits & Vegetables, Beverages End User: Food Manufacturers, Food Processors, Packaged Food Producers, Quality Assurance Labs, Government Agencies Testing Technology: Polymerase Chain Reaction, Chromatography, Spectrometry, Immunoassays, High-Performance Liquid Chromatography |
| Companies Covered | Intertek Group, TÜV SÜD, Eurofins Scientific, NSF International, Thermo Fisher Scientific, SGS, ALS, AsureQuality Limited, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Safety Testing Services Market Shifts & Advancements
Next-generation sequencing and artificial intelligence are converging to compress detection thresholds while expanding the scope of hazards identifiable in single analytical runs.
Whole-genome sequencing for pathogen subtyping is modularizing outbreak investigation workflows. Public health laboratories and large poultry integrators are adopting this technology within 24-48 hour response windows. The shift is collapsing epidemiological confirmation from weeks to same-day genetic clustering.
EFSA guidance on next-generation sequencing for foodborne pathogen monitoring is mandating harmonized data formats across member states. Laboratories must reconfigure reporting outputs to comply with centralized European surveillance databases. German and Dutch testing facilities are investing in bioinformatics capacity to maintain market access.
Subscription-based pathogen monitoring programs are displacing transactional laboratory contracts among mid-sized meat processors. Fixed-fee arrangements covering scheduled sampling and expedited turnaround are replacing per-test invoicing. This model concentrates in the United States where FSMA preventive control rules require documented environmental monitoring frequencies.
Food Safety Testing Services Market Segmentation
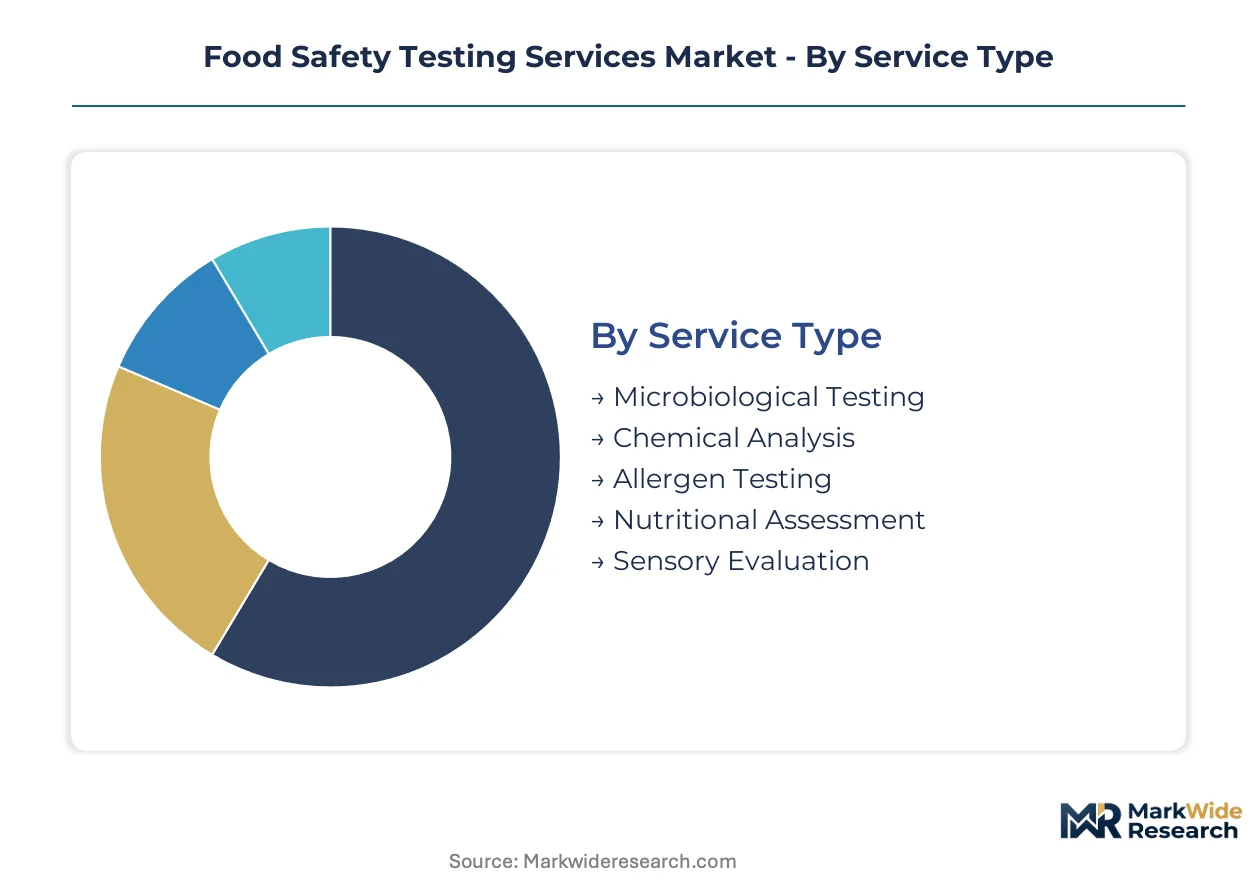
Testing service providers configure laboratory capacity around distinct hazard categories and client risk profiles. Capital allocation decisions hinge on which segments demand specialized equipment versus standardized protocols.
Service Type:
Capital intensity varies sharply across service categories, with molecular platforms requiring seven-figure instrument investments while classical methods run on depreciated assets.
- Microbiological Testing:Pathogen detection employs culture-based methods and rapid molecular assays for salmonella, listeria, and E. coli screening. Meat and poultry processors in the United States drive volume under FDA preventive control mandates, with slaughter facilities requiring 24-hour turnaround contracts.
- Chemical Analysis:Pesticide residue panels and mycotoxin quantification use chromatography and mass spectrometry for contaminant identification. Fruit and vegetable exporters in Germany face EFSA maximum residue level enforcement, compressing margins as standard test bundles commoditize.
- Allergen Testing:ELISA and PCR methods detect undeclared milk, peanut, and gluten proteins with litigation-avoidance premiums.
- Nutritional Assessment:Macro and micronutrient profiling supports label claim verification for fortified foods.
- Sensory Evaluation:Trained panels assess organoleptic properties for product development and shelf-life determination.
Microbiological testing absorbs the bulk of installed capacity; allergen testing is expanding most quickly.
Application:
Different food matrices impose distinct technical challenges, with high-moisture products demanding modified extraction protocols.
- Dairy Products:Pathogen screening targets listeria in soft cheeses and raw milk, with China's SAMR GB standards requiring domestic laboratory partnerships for imported infant formula brands.
- Meat & Poultry:Salmonella and campylobacter monitoring dominates regulatory sampling at slaughter and further processing stages. The United States FSIS performance standards compel integrated processors to maintain on-site or contracted laboratory capacity.
- Seafood:Histamine and Vibrio species detection addresses scombroid poisoning risks and raw consumption hazards.
- Fruits & Vegetables:Pesticide residue panels and microbial load testing support fresh-cut and ready-to-eat salad production.
- Beverages:Spoilage organism detection and chemical stability testing protect extended shelf-life claims.
Meat and poultry command the deepest laboratory relationships; seafood is climbing the fastest as aquaculture integration accelerates.
End User:
Procurement sophistication separates large-scale manufacturers from smaller operators, with volume thresholds determining in-house versus outsourced testing economics.
- Food Manufacturers:Integrated quality systems combine incoming ingredient verification, in-process monitoring, and finished product release. Multinational dairy and meat producers in Germany and the Netherlands negotiate multi-year testing contracts with accredited laboratory networks.
- Food Processors:Co-manufacturers and ingredient suppliers face customer-mandated testing specifications without dedicated laboratory infrastructure.
- Packaged Food Producers:Brand owners prioritize label claim verification and supplier audit documentation.
- Quality Assurance Labs:Third-party providers aggregate demand across multiple clients, achieving scale in reference material procurement and method validation.
- Government Agencies:Public health laboratories conduct surveillance sampling and outbreak investigation with standardized protocols.
Food manufacturers concentrate the highest testing spend per account; quality assurance labs are gaining share fastest through consolidation.
Testing Technology:
Platform selection determines sensitivity, specificity, and throughput, with regulatory acceptance timelines creating technology lock-in effects.
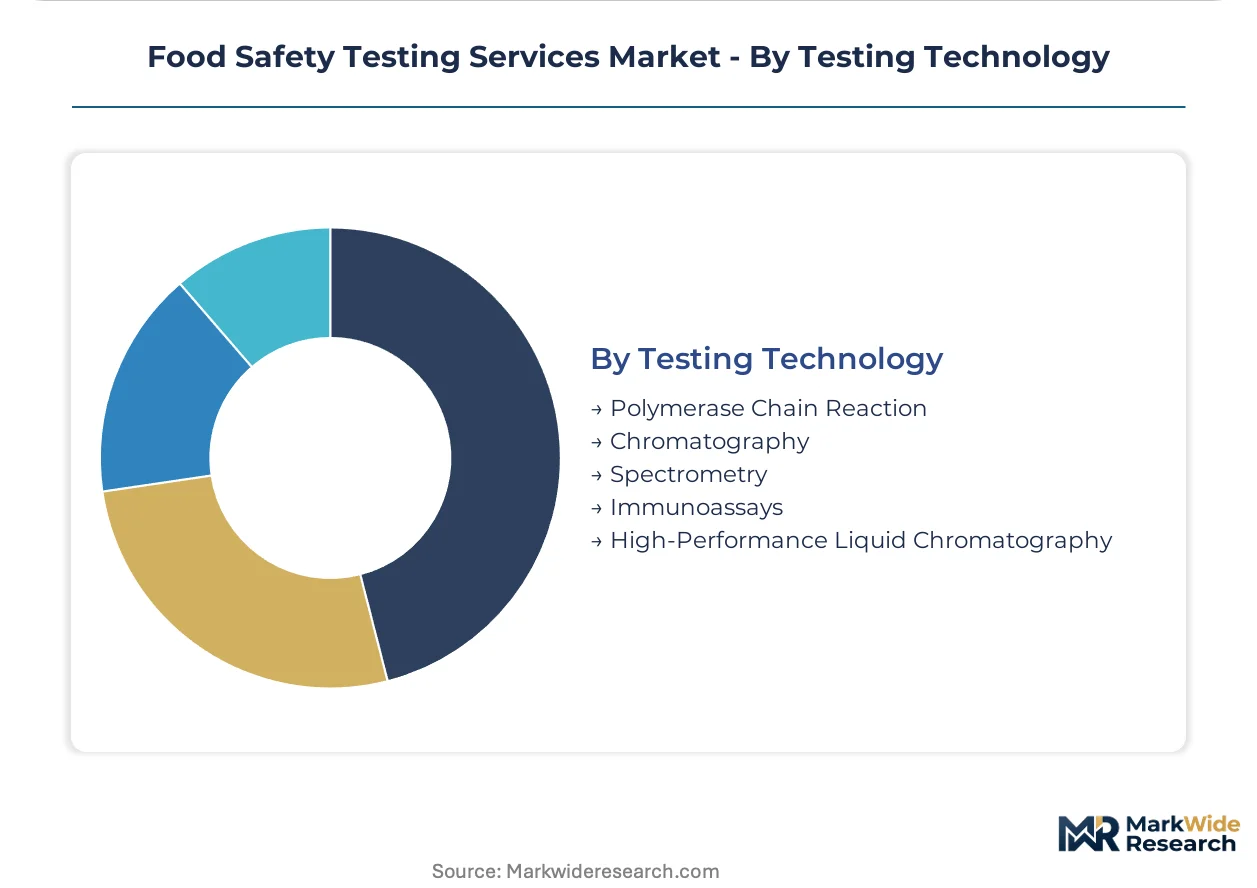
- Polymerase Chain Reaction:Nucleic acid amplification delivers species-specific pathogen identification in four to eight hours. Poultry integrators in the United States deploy real-time PCR for same-day release decisions at slaughter facilities.
- Chromatography:Gas and liquid chromatography separate complex chemical mixtures for contaminant quantification. Pesticide and mycotoxin panels in European Union member states require EFSA-validated methods for enforcement action.
- Spectrometry:Mass spectrometry and atomic absorption techniques enable elemental analysis and molecular identification.
- Immunoassays:Antibody-based detection provides cost-effective allergen and pathogen screening for high-volume monitoring.
- High-Performance Liquid Chromatography:HPLC remains the reference method for vitamin quantification and additive verification in fortified foods.
PCR platforms dominate pathogen detection capacity; chromatography systems are expanding most quickly as chemical contaminant panels multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American food safety testing demand through its concentration of meatpacking headquarters and third-party laboratory networks serving the Midwest protein corridor.
United States
Poultry integrators in Georgia and Arkansas drive PCR platform adoption for same-day slaughter release decisions. FDA enforcement of FSMA preventive controls mandates documented environmental monitoring frequencies that sustain subscription-based laboratory contracts. Omaha and Sioux Falls host dense clusters of beef and pork processors maintaining captive or contracted testing capacity.
Germany
Dairy exporters in Bavaria and Baden-Württemberg face EFSA maximum residue level enforcement that compresses margins on standard pesticide panels. ECHA and EFSA validation requirements for novel diagnostic platforms create 18-36 month commercialization delays. The Rhine-Main corridor concentrates accredited laboratories serving multinational meat and dairy producers with multi-year testing agreements.
China
SAMR enforcement of GB standards for imported infant formula brands forces foreign manufacturers into domestic laboratory partnerships. Yangtze River Delta food manufacturers in Shanghai and Jiangsu province drive demand for ISO 17025-accredited pathogen screening. Qingdao and Dalian seafood processors invest in Vibrio and histamine detection capacity for export certification.
India
FSSAI modernization of food testing infrastructure creates first-mover opportunities in Maharashtra and Gujarat dairy clusters. Mumbai and Ahmedabad processors face escalating customer-mandated specifications without dedicated laboratory infrastructure. Karnataka's packaged food manufacturers in Bengaluru drive allergen testing premiums as undeclared ingredient liability concerns intensify.
Netherlands
Rotterdam and Wageningen anchor European food safety research and commercial testing capacity for export-oriented agriculture. EFSA guidance on next-generation sequencing mandates harmonized data formats that force bioinformatics investments. Dutch poultry integrators adopt whole-genome sequencing for 24-48 hour outbreak response windows.
Food Safety Testing Services Market Competitive Landscape
Capital-heavy laboratory networks compete with specialized boutique providers in a market structure favoring scale in reference material procurement and method validation. Consolidation pressures concentrate among mid-sized quality assurance laboratories seeking ISO 17025 accreditation breadth. Three archetypes dominate: integrated multinational networks with reciprocal regulatory authorization, regional specialists capturing cell-based meat method development contracts, and technology-agnostic third-party aggregators. Competitive moves center on M&A for geographic coverage and strategic partnerships for blockchain-integrated audit trail deployment.
Within the integrated network tier, Eurofins Scientific and SGS exemplify archetypes leveraging laboratory density for recurring revenue streams across North American and European food processors. Bureau Veritas occupies a position representing the regulatory compliance-focused segment serving multinational dairy and meat producers. Intertek Group anchors the quality assurance lab aggregation model through third-party provider consolidation.
| Leading Market Players |
|---|
| Intertek Group |
| TÜV SÜD |
| Eurofins Scientific |
| NSF International |
| Thermo Fisher Scientific |
| SGS |
| ALS |
| AsureQuality Limited |
| Bureau Veritas |
| Others |
Supply & Pricing Matrix
Certified reference material price indices cascade through food safety testing supply chains, compressing margins at mid-sized laboratories while concentrating pricing power with multinational networks holding captive strain libraries. Three-tier pricing structure across premium, standard, and economy levels segments buyers by ISO 17025 accreditation breadth and turnaround urgency.
Pricing Analysis
Margin tightening in standard pesticide panels reflects EFSA method validation commoditization across European quality assurance labs. Subscription-based pathogen monitoring commands premium positioning through FSMA-mandated documentation frequencies, while per-test transactional contracts face cost-down pressure from high-volume meat processors. Certification tier and geographic accreditation density drive price differentiation, with FDA-registered laboratories capturing litigation-averse dairy manufacturers least sensitive to unit pricing.
Supply Chain Analysis
Direct-to-laboratory channels serve multinational food manufacturers requiring integrated quality systems across multiple facilities. Reference strain supply concentrates in the United States, Germany, and Japan, with matrix-matched standard production anchored in ISO 17043-accredited facilities. Laboratory equipment and consumables draw from specialized chromatography and mass spectrometry OEMs in the United States and Germany. Single-source vulnerability in certified pathogen strain distribution creates supply chain risk during accreditation renewal cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food safety testing services market functions as a cost-of-compliance arena where FDA Food Safety Modernization Act preventive control mandates erect accreditation barriers that protect incumbent laboratory networks from unqualified competition.
For Market Incumbents: Extend ISO 17025 accreditation breadth into emerging cell-based meat method development before regulatory frameworks solidify. Acquire regional specialists in Maharashtra and Gujarat to capture FSSAI modernization infrastructure spending. Blockchain-integrated audit trail capabilities represent a critical lever against technology-agnostic third-party aggregators consolidating mid-tier quality assurance labs. For New Entrants and Emerging Players: Mid-sized meat processors without captive laboratory infrastructure present the most penetrable buyer archetype for subscription-based environmental monitoring programs. India's packaged food manufacturers in Bengaluru face escalating allergen liability without domestic testing partnerships, creating white-space for ISO 17025-accredited facilities. A cell-based meat method development specialization offers regulatory-first-mover positioning ahead of established safety frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with ISO 17025 breadth in Germany and the Netherlands facing EFSA next-generation sequencing compliance costs. Long-term viability hinges on bioinformatics capacity investments harmonizing with centralized European surveillance database requirements. Laboratories demonstrating whole-genome sequencing outbreak response capabilities signal readiness for public health contract migration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | Regulatory authorization breadth determines cross-border client eligibility under FDA and EFSA reciprocity agreements. |
| Blockchain-Integrated Audit Trail Deployment | Immutable chain-of-custody records command premium pricing from organic and specialty food exporters. |
| Next-Generation Sequencing Bioinformatics Investment | EFSA harmonized data format mandates force laboratories to reconfigure reporting outputs for market access. |
| Cell-Based Meat Method Development | Novel protein production lacks established safety frameworks, opening early regulatory engagement contracts. |
| Regional Laboratory Network Consolidation | Mid-sized quality assurance labs seek acquisition to achieve scale in reference material procurement. |
Research Methodology
Document review covered FDA FSMA guidance documents, EFSA scientific opinions, SAMR GB standards, and ISO 17025 accreditation registers, complemented by interviews with laboratory operations directors, food manufacturer quality assurance managers, regulatory affairs specialists at testing service providers, and procurement leads at multinational dairy and meat processors. Secondary validation drew from customs trade data, SEC filings of publicly traded laboratory networks, and national food safety surveillance reports. Bottom-up demand modeling and top-down market sizing triangulated segment-level outputs.
Segmented projections across service type, application, end user, testing technology, and regional regulatory cluster dimensions informed value and volume estimates across the analysis window. CAGRs derived from regression analysis of historical accreditation expansion rates, regulatory enforcement intensity indices, and technology adoption curves for PCR and next-generation sequencing platforms. Method validation timeline compression and reference material cost trajectories served as industry-specific forecast inputs.
Revisions become necessary when regulatory reciprocity agreements fragment laboratory authorization networks or when novel detection platforms achieve accelerated FDA and EFSA approval timelines. Forecasts reflect assumptions regarding sustained FSMA preventive control enforcement and EFSA microbiological criteria expansion. Periodic stress-testing of base assumptions against SAMR GB standard implementation pace and FSSAI infrastructure modernization disbursement rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Food Tester Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Europe Food Safety Testing Market