
 Food Testing Services Market | 2026-2036
Food Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Food Testing Services Market Analysis
The shift from in-house laboratories toward outsourced multi-source testing arrangements is repositioning how food manufacturers manage quality assurance across dispersed supply chains. Eurofins Scientific SE leverages its decentralized laboratory network to sustain proximity advantages in key agricultural zones. Bureau Veritas S.A. anchors its competitive stance through specialized certification services that integrate with retailer audit programs.
Food testing services encompass analytical verification of microbiological safety, chemical composition, nutritional content, and allergen presence in commercial food products, employing methodologies such as chromatography for pesticide residue quantification and polymerase chain reaction for pathogen detection. These services function as gatekeeping mechanisms that prevent contaminated or mislabeled products from reaching consumers and triggering regulatory enforcement. Microbiological testing occupies the largest service-type revenue pool due to persistent Salmonella and Listeria monitoring requirements across dairy and meat processing facilities. Chemical testing, including heavy metal and mycotoxin screening, registers the fastest expansion as import jurisdictions tighten maximum residue limits on grains and spices.
The U.S. FDA enforces Hazard Analysis Critical Control Point mandates that compel food manufacturers to document preventive controls through verified laboratory testing. The EU's REACH framework and EFSA scientific opinions establish evolving contaminant thresholds that laboratories must calibrate against to maintain accreditation validity. China's SAMR implements GB national standards that foreign exporters must satisfy through certified third-party analysis. Stakeholders should monitor how regulatory divergence between major import markets fragments testing protocols and inflates compliance costs for multinational food suppliers.
Market Dynamics
Food testing services are pivoting toward multi-source verification architectures as manufacturers fragment supply chains across jurisdictions with non-aligned residue standards. This structural dispersion forces laboratories to maintain parallel accreditation portfolios while realigning analytical protocols to satisfy divergent import market requirements.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened traceability mandates and reduced pesticide residue ceilings are compelling exporters to seek certified third-party validation before shipment clearance.
- China's SAMR accreditation surge:Domestic food safety incidents have accelerated laboratory certification requirements, expanding addressable demand for foreign testing providers with GB standard compliance.
- PCR pathogen detection:Molecular diagnostics are displacing culture-based methods in meat and dairy processing facilities, shortening detection windows from days to hours.
Market Restraints
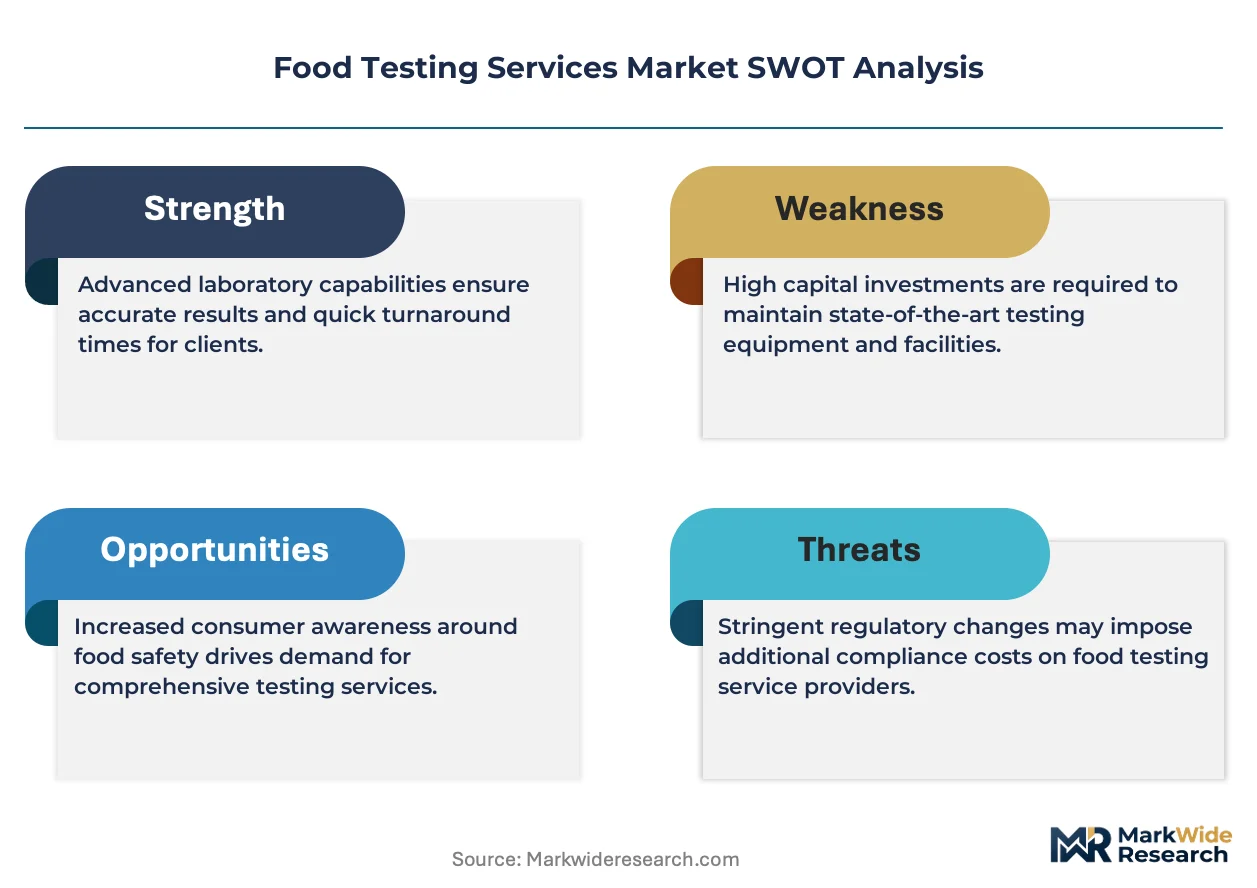
- Reference material scarcity:Certified reference standards for novel contaminants and mycotoxin variants face supply bottlenecks from limited producers in Germany and the United States.
- Equipment import tariffs:Chromatography and mass spectrometry instruments face duties in several Asian markets, inflating capital requirements for laboratory establishment.
- Regulatory fragmentation:Divergent maximum residue limits between FDA, EFSA, and SAMR jurisdictions force redundant testing runs on identical product batches.
Strategic Opportunities
- Cell-cultured protein testing:Novel food categories lack standardized safety protocols, creating first-mover advantage for laboratories developing validated analytical frameworks.
- Blockchain-integrated verification:Immutable chain-of-custody records are attracting premium pricing from organic and specialty food exporters seeking differentiation.
- India's FSSAI expansion:Strengthened domestic food safety enforcement is opening third-party testing demand previously captured by informal local laboratories.
Industry Challenges
- Multi-jurisdiction accreditation maintenance:Laboratories face recurring audit cycles across ISO 17025, FDA GLP, and EU BCR requirements, consuming technical management bandwidth.
- Specialized technician scarcity:Mass spectrometry operation and mycotoxin method development require expertise that outpaces vocational training program output in key agricultural regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Testing Services Market |
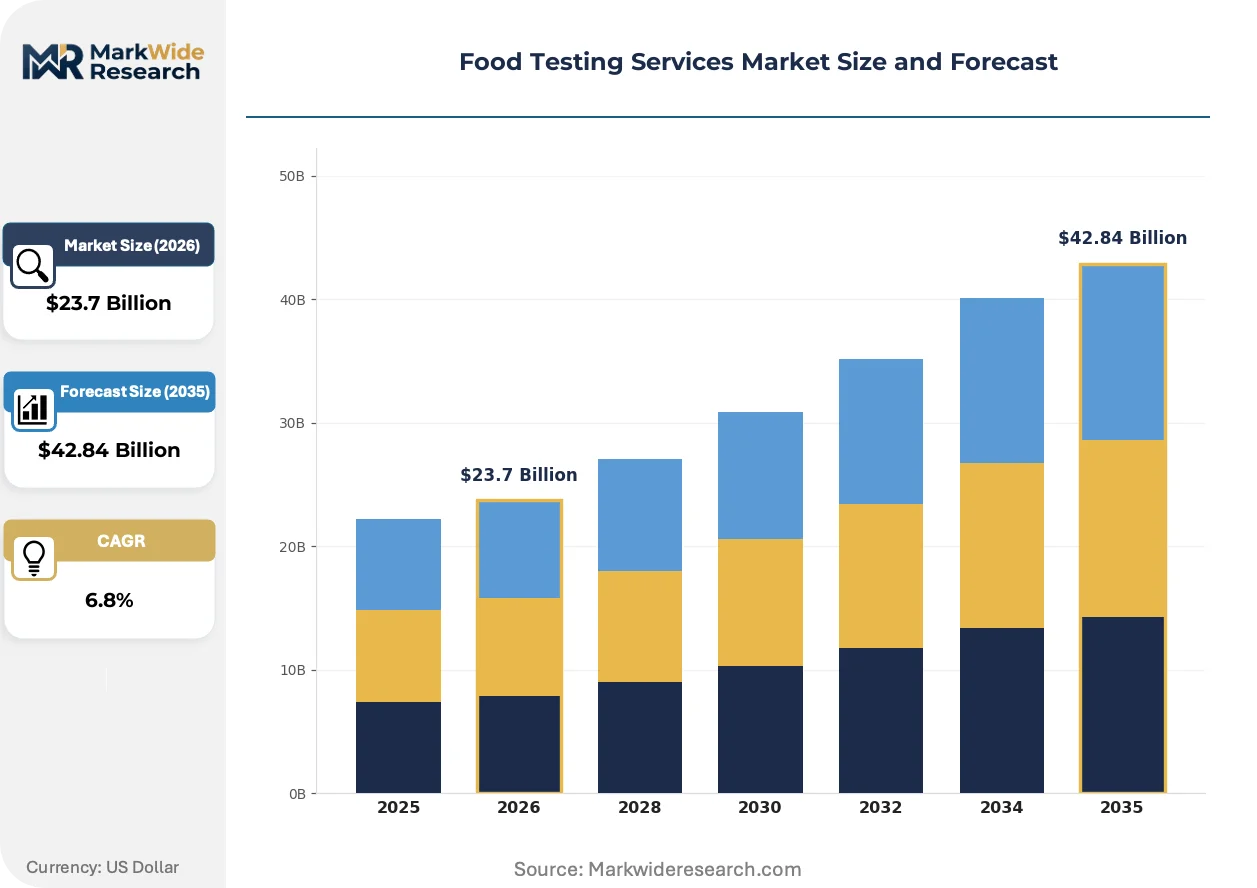
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Chemical Testing, Nutritional Analysis, Allergen Testing Product Type: Dairy Products, Meat, Processed Foods, Beverages Technology: Chromatography, Mass Spectrometry, PCR, ELISA End User: Food Manufacturers, Food Retailers, Restaurants, Government Agencies |
| Companies Covered | Intertek Group plc, ALS Limited, Eurofins Scientific SE, TÜV SÜD AG, Element Materials Technology Ltd., Mérieux NutriSciences Corporation, Bureau Veritas S.A., Neogen Corporation, Société Générale de Surveillance S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Testing Services Market Emerging Trajectories
Next-generation sequencing and portable diagnostics are compressing detection timelines while fragmenting where testing occurs along the food supply chain. These technologies are redistributing analytical capacity from central laboratories toward point-of-production and point-of-import verification nodes.
Rapid on-site PCR systems are electrifying pathogen surveillance workflows in poultry and seafood processing plants. Medium-scale processors in the United States and Brazil are deploying handheld devices for same-shift Salmonella screening, collapsing the feedback loop between sampling and production hold decisions. This decentralization is compressing demand for high-throughput central laboratory microbiology in commodity protein segments.
REACH framework amendments and EFSA scientific opinions are continuously recalibrating contaminant thresholds for processed foods entering European markets. Laboratories must perpetually revalidate analytical methods against evolving reference points, raising compliance overhead for multi-market service providers. Grain and spice importers face particular exposure due to tightening mycotoxin and heavy metal ceilings.
Retailer audit unbundling is reshaping how food manufacturers procure verification services. Large grocery chains in Germany and the United Kingdom are decoupling their proprietary audit programs from laboratory testing, creating openings for independent certification bodies to capture bundled testing and inspection contracts. This procurement model change is most visible in private-label dairy and ready-meal categories where brand risk concentrates with the retailer.
Food Testing Services Market Segmentation
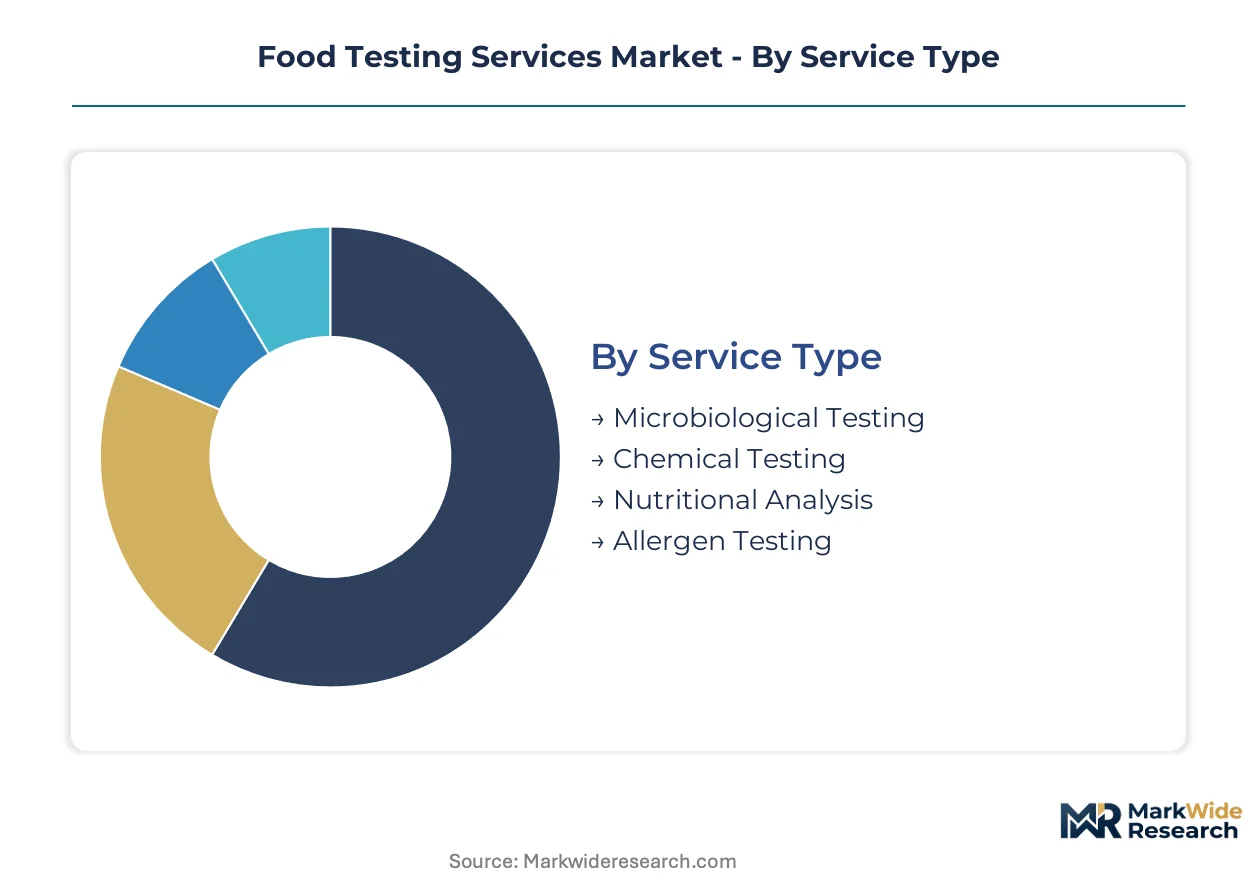
Segmentation in food testing services reveals how certification burdens and regulatory scopes vary across analytical methods, product categories, and customer types. Laboratories calibrate accreditation portfolios against the specific residue limits and pathogen thresholds governing each segment's compliance pathway.
Service Type:
ISO 17025 accreditation requirements intensify for segments handling novel contaminants or multi-jurisdiction residue limits, with audit cycles varying by analytical complexity and regulatory exposure.
- Microbiological Testing:Culture-based and molecular methods detect Salmonella, Listeria, and E. coli in perishable supply chains. Demand concentrates in dairy and meat processing facilities across the United States and Germany, where FDA and EFSA mandates enforce continuous environmental monitoring and finished-product verification.
- Chemical Testing:Chromatographic and spectrometric techniques quantify pesticide residues, heavy metals, and mycotoxins in grains and spices. Import jurisdictions in China and the European Union are tightening maximum residue limits, forcing exporters to seek certified third-party validation before shipment clearance.
- Nutritional Analysis:Macronutrient and micronutrient profiling supports label claims and fortification verification.
- Allergen Testing:ELISA and PCR methods detect gluten, peanut, and dairy proteins to prevent mislabeling incidents.
Microbiological Testing sits at the top of the volume ranking, with Chemical Testing climbing the fastest.
Product Type:
Cost tiers for testing scale with supply chain complexity, where fragmented sourcing and perishability elevate verification expenses.
- Processed Foods:Multi-ingredient formulations require layered screening for contaminants, allergens, and nutritional accuracy. Manufacturers in the Netherlands and Italy are expanding outsourced testing programs to manage complex supplier verification across dispersed ingredient networks.
- Meat:Pathogen surveillance dominates, with slaughterhouses and cutting plants facing continuous regulatory inspection. Brazil and the United States deploy rapid on-site PCR systems for same-shift Salmonella screening, compressing feedback loops between sampling and production decisions.
- Dairy Products:Raw milk and finished goods undergo antibiotic residue and microbial load testing.
- Beverages:Bottled water, juices, and alcoholic drinks require chemical and sensory evaluation.
Processed Foods command the highest testing expenditure per unit, with Meat gaining share fastest on regulatory enforcement intensity.
Technology:
Capital requirements and technician specialization create distinct competitive moats across analytical platforms.
- PCR:Polymerase chain reaction amplifies pathogen DNA for detection windows shortened from days to hours. Poultry and seafood processors in the United States and Brazil are electrifying surveillance workflows through handheld deployment, collapsing central laboratory demand in commodity protein segments.
- Mass Spectrometry:High-resolution identification of unknown contaminants and mycotoxin variants requires scarce expertise and expensive instrumentation. Reference material bottlenecks from limited producers in Germany and the United States constrain method validation throughput.
- Chromatography:Gas and liquid chromatography separate chemical mixtures for residue quantification.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective allergen and toxin screening.
PCR leads deployment velocity, with Mass Spectrometry expanding most quickly on novel contaminant detection demand.
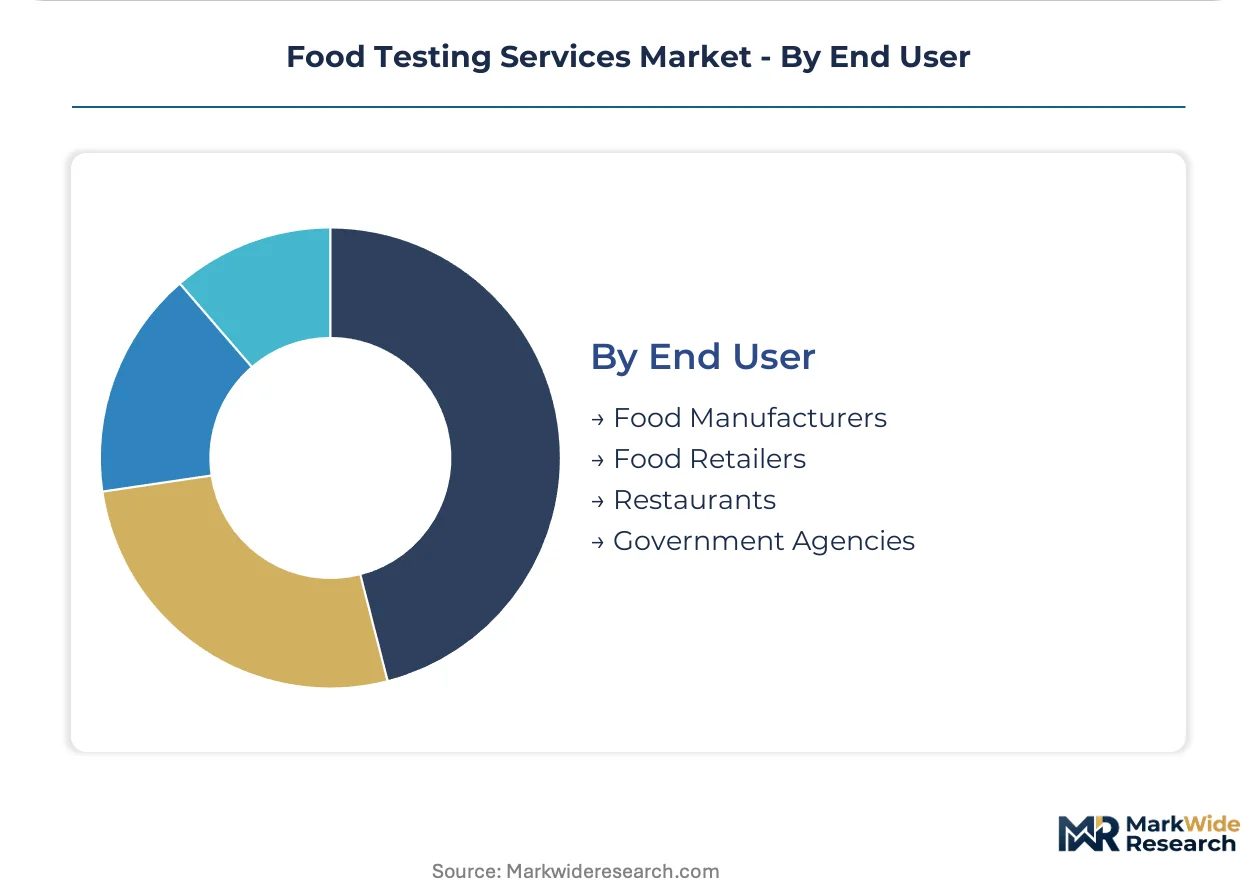
End User:
Procurement authority and audit integration shape how verification services are bundled and priced.
- Food Manufacturers:Brand owners bear primary liability for contaminated or mislabeled products, driving investment in preventive controls. Large processors in Germany and the United Kingdom are decoupling proprietary audit programs from laboratory testing, creating openings for independent certification bodies to capture bundled contracts.
- Government Agencies:National regulators including China's SAMR and the U.S. FDA enforce compliance through inspection, reference laboratory oversight, and third-party accreditation mandates. Domestic food safety incidents in China have accelerated laboratory certification requirements, expanding addressable demand for GB standard compliance.
- Food Retailers:Grocery chains impose private-label testing specifications that concentrate risk with the retailer.
- Restaurants:Food service operators face localized health department inspection and supply chain verification.
Food Manufacturers anchor service revenue, with Government Agencies steepest in compliance-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's laboratory corridor anchors third-party food testing capacity expansion as China's SAMR accelerates GB standard enforcement. Testing demand concentrates in jurisdictions with tightening import residue limits and domestic safety incident exposure.
United States
Poultry and beef processors drive rapid on-site PCR deployment for same-shift Salmonella screening. FDA Hazard Analysis Critical Control Point mandates compel documented preventive controls through verified laboratory testing. Nebraska and Iowa meatpacking clusters are electrifying surveillance workflows, collapsing feedback loops between sampling and production hold decisions.
Germany
Private-label dairy and ready-meal manufacturers are decoupling proprietary audit programs from laboratory testing. EFSA scientific opinions continuously recalibrate contaminant thresholds for processed foods entering European markets. North Rhine-Westphalia's food processing belt is absorbing expanded third-party verification contracts as retailer risk concentration intensifies.
China
Domestic food safety scandals have accelerated laboratory certification requirements under SAMR oversight. GB national standards force foreign exporters to seek certified third-party analysis before shipment clearance. Yangtze River Delta agricultural zones are expanding accredited testing infrastructure to manage complex supply chain verification across dispersed ingredient networks.
Brazil
Meat slaughterhouses and cutting plants face continuous regulatory inspection driving pathogen surveillance investment. Medium-scale processors are deploying handheld diagnostic devices for commodity protein screening. São Paulo state's protein processing corridor is compressing central laboratory demand through decentralized rapid testing adoption.
India
FSSAI expansion is opening third-party testing demand previously captured by informal local laboratories. Strengthened domestic food safety enforcement targets mislabeling and adulteration in processed food categories. Maharashtra and Gujarat food manufacturing clusters are transitioning toward accredited multi-source verification architectures.
Food Testing Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized certification niches and blockchain-integrated verification. The market structure concentrates around decentralized laboratory networks and bundled testing-inspection contracts. Three archetypes dominate: proximity-based agricultural zone specialists, retailer audit-integrated certification bodies, and rapid diagnostics technology deployers. Competitive moves center on multi-jurisdiction accreditation portfolio expansion and point-of-production testing capacity placement.
Within the integrated certification tier, Bureau Veritas S.A. and Eurofins Scientific SE exemplify divergent positioning strategies. Bureau Veritas S.A. anchors retailer audit program integration, while Eurofins Scientific SE occupies proximity-based agricultural zone coverage. Mérieux NutriSciences Corporation sits within the specialized pathogen diagnostics archetype. These three entities represent how service providers calibrate accreditation portfolios against specific residue limits and pathogen thresholds governing compliance pathways.
| Leading Market Players |
|---|
| Intertek Group plc |
| ALS Limited |
| Eurofins Scientific SE |
| TÜV SÜD AG |
| Element Materials Technology Ltd. |
| Mérieux NutriSciences Corporation |
| Bureau Veritas S.A. |
| Neogen Corporation |
| Société Générale de Surveillance S.A. |
| Others |
Supply Flow & Price Mechanics
Outsourced laboratory networks anchor supply positioning and pricing power for food testing providers, with decentralized accreditation portfolios enabling proximity premiums in agricultural zones while centralized reference material production constrains cost pass-through flexibility.
Pricing Analysis
Input-cost pass-through from certified reference standards and chromatography instrumentation flows unevenly across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited multi-jurisdiction providers from single-market laboratories and informal local testers. Price differentiation rests on accreditation breadth and turnaround speed. Pricing pressure stems from rapid on-site PCR deployment collapsing central laboratory demand in commodity protein segments. Small and medium meat processors exhibit highest price sensitivity, while multinational food manufacturers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and United States producers of certified reference materials for novel contaminants and mycotoxin variants. Equipment supply concentrates in Germany, the United States, and Japan for mass spectrometry and chromatography systems. Raw material dependencies include high-purity solvents, analytical columns, and pathogen DNA primers. Tariff exposure on instrumentation imports into Asian markets inflates capital requirements for laboratory establishment. Distribution runs through direct sales to large food manufacturers, with bundled testing-inspection contracts capturing retailer audit program integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food testing services function as a stable compounder, with regulatory ratchet effects from FDA, EFSA, and SAMR jurisdictions driving steady compliance expenditure growth regardless of economic cycles.
For Market Incumbents: Cement multi-jurisdiction accreditation portfolios through ISO 17025, FDA GLP, and EU BCR audit cycle synchronization. Expand point-of-production PCR deployment in Brazil and United States meatpacking corridors to defend against rapid diagnostics technology deployers. Prioritize technician retention programs addressing mass spectrometry operation scarcity. For New Entrants and Emerging Players: Begin with cell-cultured protein safety protocol development, where standardized analytical frameworks remain undefined. Target India's FSSAI expansion corridor, where informal laboratory displacement creates white-space demand. Pursue blockchain-integrated verification go-to-market positioning for organic and specialty food exporters seeking chain-of-custody differentiation. For Investors and Strategic Acquirers: Roll-up economics work for decentralized agricultural zone specialists because proximity advantages in key growing regions resist commoditization. Long-term viability rests on recurring accreditation maintenance revenue streams rather than transactional project volume. Target laboratories with established SAMR GB standard compliance for China market exposure. Watch EFSA scientific opinion velocity as inflection indicator for European compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Accreditation Expansion | ISO 17025, FDA GLP, and EU BCR portfolio breadth captures cross-border food manufacturer contracts. |
| Point-of-Production Testing Deployment | Handheld PCR systems in Nebraska and São Paulo protein corridors collapse central laboratory feedback loops. |
| Cell-Cultured Protein Protocol Development | First-mover validated analytical frameworks for novel protein categories attract premium pricing from alternative protein startups. |
| Blockchain-Integrated Verification Launch | Immutable chain-of-custody records differentiate organic exporters in German and United Kingdom retailer audit programs. |
| Technician Training Program Investment | Mass spectrometry and mycotoxin method development expertise scarcity creates competitive moats in grain and spice testing. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory operations directors, food manufacturer quality assurance leads, regulatory affairs specialists at certification bodies, and retailer procurement managers with secondary validation. Sources included FDA warning letter databases, EFSA scientific opinion archives, SAMR GB standard publications, and customs data on chromatography equipment imports. Bottom-up service-type demand modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across microbiological testing, chemical testing, nutritional analysis, and allergen testing service types, with further stratification by PCR, mass spectrometry, chromatography, and ELISA technology platforms. CAGRs were derived from regression analysis against regulatory enforcement intensity metrics and processed food export volume trends. Forecast inputs incorporated EFSA threshold recalibration schedules and SAMR laboratory certification expansion targets.
Several conditions sit outside the modeled scope, including unforeseen pathogen emergence requiring entirely new detection protocols, trade policy disruptions affecting reference material cross-border flows, and quantum leap advances in portable diagnostic sensitivity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Global Meat Speciation Testing Market