
 Allergen Testing Market | 2026-2036
Allergen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Allergen Testing Market Insights
Food manufacturing is pivoting toward integrated allergen management programs that span supplier verification through finished-product release. Eurofins Scientific leverages its laboratory network to anchor food safety testing across European processing hubs. SGS S.A. competes through specialized immunoassay services that sustain compliance margins for multinational brands. Thermo Fisher Scientific Inc. dominates analytical instrument supply to hospital laboratories seeking in-house allergen panels.
Allergen testing encompasses immunological and molecular methods that detect specific Immunoglobulin E antibodies or allergen proteins in biological specimens or food matrices, with sensitivity thresholds typically reaching picogram-per-milliliter concentrations for ELISA-based food allergen kits. The primary commercial purpose centers on clinical diagnosis of hypersensitivity disorders and food industry verification of allergen-free claims. Immunoassay technology leads diagnostic volume due to established automation platforms, while Lateral Flow Assay formats capture point-of-care growth where rapid environmental and food screening reduces hold times. Serum Allergy Test products command premium positioning through quantitative specific-IgE multiplexing that replaces single-analyte workflows.
FDA enforcement of the Food Safety Modernization Act preventive controls pushes food processors toward validated allergen verification methods. EFSA guidance on precautionary labeling and EU Food Information for Consumers Regulation mandate clear quantitative thresholds that shape test kit performance requirements. ISO 17025 accreditation demands filter laboratory eligibility for pharmaceutical and food industry contracts. Stakeholders must monitor evolving threshold harmonization between FDA and EFSA frameworks to align R&D pipelines with divergent compliance specifications.
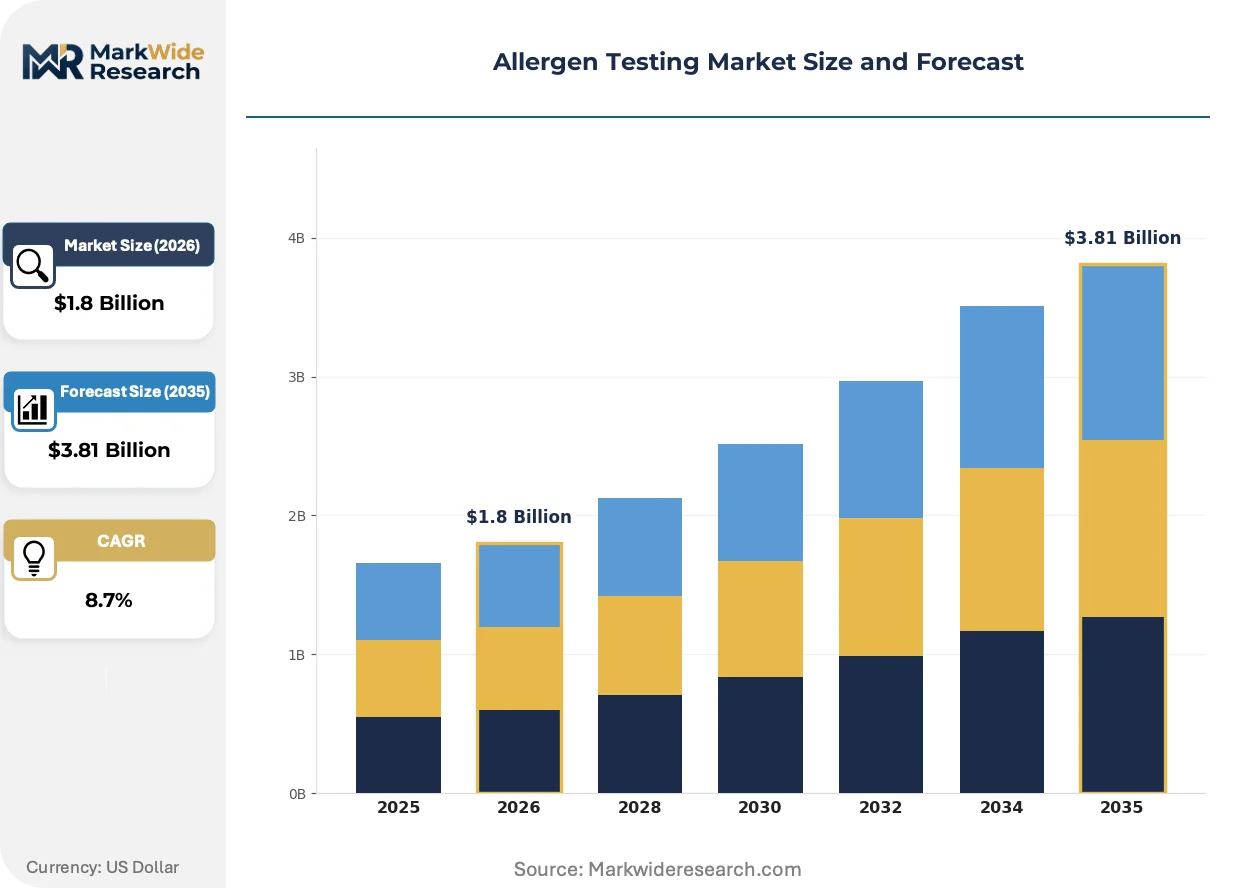
Market Dynamics
Preventive allergen verification mandates are compressing testing timelines across food manufacturing, forcing processors to migrate from batch-release testing to continuous in-line monitoring systems that interface directly with production control software.
Growth Catalysts
- FDA Food Safety Modernization Act:Preventive controls rules mandate validated allergen verification at critical control points, expanding demand for rapid immunoassay platforms in US food processing facilities.
- ELISA automation:High-throughput robotic sample handling systems reduce laboratory turnaround from days to hours, enabling diagnostic laboratories to absorb rising test volumes without proportional staffing increases.
- Germany:Updated DGAKI clinical guidelines accelerate serological testing adoption in pediatric allergy practices, shifting diagnostic workflows toward quantitative specific-IgE multiplexing.
Market Restraints
- Reference material scarcity:Certified allergen reference standards for emerging proteins lack batch consistency, creating calibration drift that compromises inter-laboratory result comparability.
- Reagent supply concentration:Monoclonal antibody production for key food allergen targets concentrates among contract biologics manufacturers in Switzerland and the Netherlands, exposing kit producers to single-source risk.
- Cross-reactivity limitations:Current immunoassay platforms cannot distinguish closely related protein isoforms, forcing confirmatory testing that extends diagnostic timelines and elevates operational costs.
Strategic Opportunities
- Point-of-care expansion:Lateral flow assay formats with smartphone-readable outputs enable restaurant and catering sector self-monitoring, bypassing laboratory infrastructure constraints in underserved markets.
- EU Food Information for Consumers Regulation:Mandatory quantitative threshold labeling for precautionary statements creates demand for validated detection methods at sub-ppm concentrations, opening premium kit positioning.
- Next-generation sequencing convergence:Metagenomic approaches to allergen identification promise multi-allergen detection from single samples, potentially displacing sequential single-analyte workflows in reference laboratories.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification processes extend 12-18 months, delaying market entry for new testing service providers and constraining capacity expansion.
- Legacy LIMS integration:Hospital laboratories face middleware compatibility failures when connecting new immunoassay analyzers to established laboratory information management systems, requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergen Testing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Prick Test, Intradermal Test, Patch Test, Serum Allergy Test Technology: Immunoassay, Enzyme-Linked Immunosorbent Assay, Western Blotting, Lateral Flow Assay End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Application: Food Allergies, Environmental Allergies, Drug Allergies, Insect Allergies |
| Companies Covered | Thermo Fisher Scientific Inc., Eurofins Scientific, SGS S.A., Intertek Group PLC, Merck KGaA, NEOGEN Corporation, Romer Labs Division Holding, Bureau Veritas S.A., Microbac Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergen Testing Market Trends and Innovations
Mass spectrometry platforms are penetrating food allergen verification workflows, displacing antibody-dependent methods in applications where protein denaturation or processing modifications compromise immunoassay accuracy.
Biosensor arrays employing surface plasmon resonance technology are converging with microfluidic sample preparation modules, enabling real-time allergen quantification without batch incubation steps. Large food manufacturers in the Netherlands and Belgium are piloting these systems at ingredient intake checkpoints. This convergence is compressing the verification window from hours to minutes, collapsing hold inventory requirements and accelerating production line turnover.
EFSA guidance on precautionary labeling thresholds is tightening quantitative performance requirements for commercial test kits, mandating method validation studies that demonstrate detection capability at regulatory action levels. Kit manufacturers must now submit extensive matrix-specific data packages to support label claims across diverse food categories. European contract laboratories are responding by consolidating validation service offerings, capturing margin from manufacturers lacking in-house regulatory affairs capacity.
Diagnostic procurement in Japan is consolidating around integrated service contracts that bundle reagent supply, instrument maintenance, and quality assurance oversight into per-test pricing structures. Hospital networks are displacing capital purchase models with operational expenditure frameworks that transfer obsolescence risk to vendors. This restructuring is most visible in Tokyo and Osaka metropolitan laboratory consortia, where standardized panels and unified reporting formats reduce inter-facility result variability.
Allergen Testing Market Segmentation
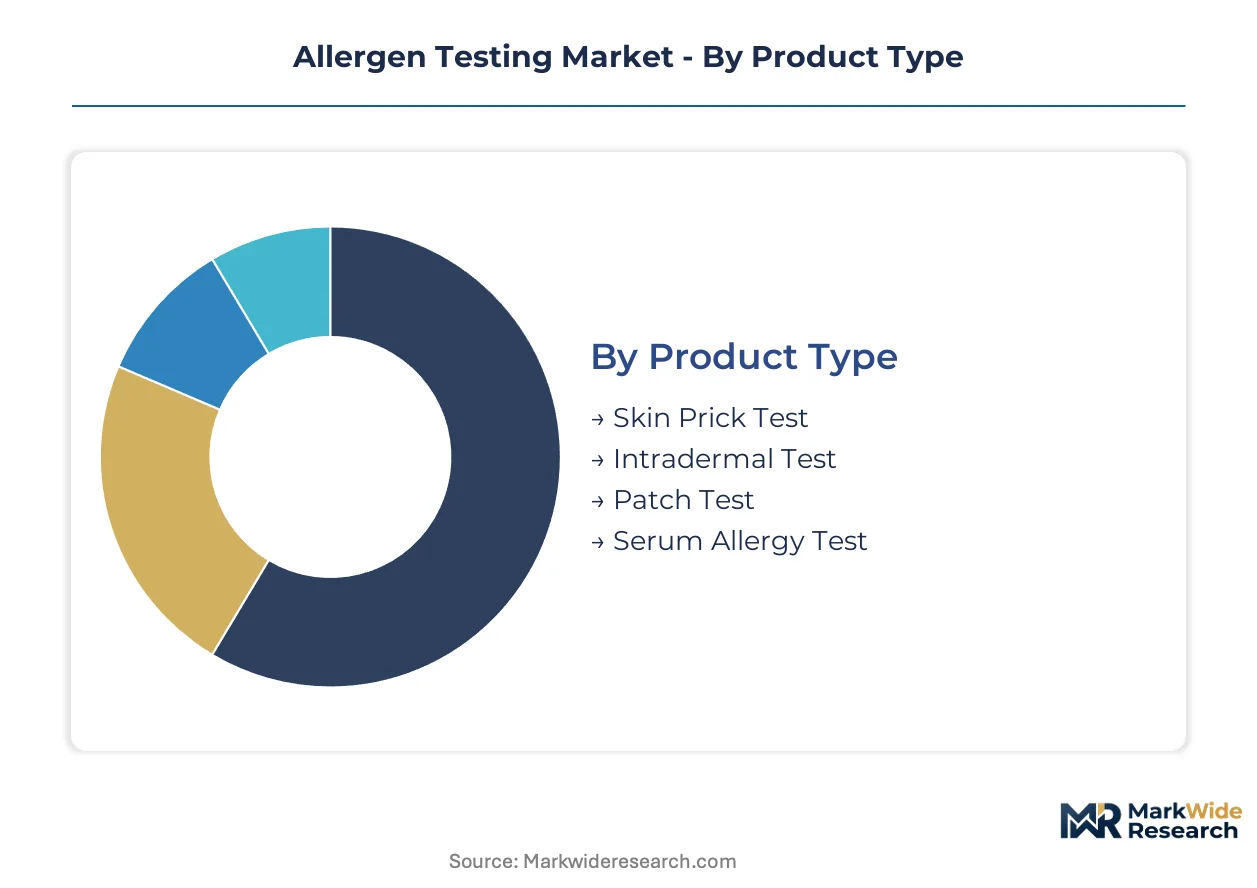
Allergen testing segmentation reveals divergent supply chain configurations across clinical diagnostics and food safety verification. Each category maps distinct procurement patterns, from hospital laboratory automation investments to food processor in-line monitoring systems.
Product Type:
Supply concentration clusters around automated platforms that reduce technician handling time and standardize result reporting across high-volume settings.
- Serum Allergy Test:Quantitative specific-IgE multiplexing enables simultaneous detection of multiple allergen-specific antibodies from single serum samples. Demand concentrates in German pediatric allergy practices following updated DGAKI clinical guidelines that prioritize objective serological confirmation over subjective symptom history. The shift displaces single-analyte workflows and elevates reagent consumption per patient encounter.
- Skin Prick Test:Percutaneous allergen introduction with standardized extract concentrations remains the first-line diagnostic for immediate hypersensitivity assessment. Primary demand flows through Japanese hospital outpatient departments where integrated service contracts bundle reagent supply with per-test pricing structures. Cost pressure from operational expenditure frameworks limits capital investment in alternative platforms.
- Intradermal Test:Deeper dermal allergen injection for delayed hypersensitivity evaluation serves niche diagnostic confirmation needs.
- Patch Test:Extended epidermal exposure protocols identify contact allergens through delayed type IV reactions.
Serum Allergy Test absorbs the bulk of installed capacity; Skin Prick Test is expanding most quickly.
Technology:
Cost tier differentiation separates high-throughput laboratory automation from rapid point-of-care formats that bypass infrastructure requirements.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection of allergen-specific antibodies or proteins through enzyme-substrate reactions achieves picogram-per-milliliter sensitivity thresholds. Food processors in the United States deploy ELISA platforms at critical control points to satisfy FDA Food Safety Modernization Act preventive controls mandates. Robotic sample handling systems compress turnaround from days to hours without proportional staffing increases.
- Immunoassay:Broad antibody-antigen binding detection methods encompass chemiluminescence and fluorescence variants beyond ELISA formats. Diagnostic laboratories in Tokyo and Osaka metropolitan consortia standardize on automated immunoassay analyzers with unified reporting formats that reduce inter-facility result variability. Middleware integration failures with legacy LIMS systems create implementation delays and custom development costs.
- Lateral Flow Assay:Membrane-based immunochromatography delivers qualitative results within minutes for environmental and food screening applications.
- Western Blotting:Protein separation and antibody detection confirms allergen identity through molecular weight verification.
Immunoassay commands the highest absolute test volume; Lateral Flow Assay gains share fastest in food service self-monitoring applications.
End User:
Customer type determines pricing structure and service bundling, with hospital networks shifting from capital purchase to operational expenditure frameworks.
- Diagnostic Laboratories:Centralized high-throughput facilities process samples from multiple collection points with ISO 17025 accreditation requirements. Eurofins Scientific anchors its European network at food processing hubs, capturing pharmaceutical and food industry contracts through validated method portfolios. Accreditation timelines extending 12-18 months constrain new entrant capacity expansion.
- Hospitals:In-house laboratory services integrate allergen testing within broader clinical pathology departments. Japanese hospital networks in metropolitan consortia displace capital purchase models with per-test pricing that transfers instrument obsolescence risk to vendors. Standardized panels reduce inter-facility result variability across Tokyo and Osaka clusters.
- Clinics:Lower-volume settings prioritize rapid turnaround and minimal sample handling complexity.
- Research Institutions:Method development and validation studies support regulatory submission requirements for commercial test kit manufacturers.
Diagnostic Laboratories absorb the bulk of installed capacity; Hospitals are expanding most quickly through operational expenditure restructuring.
Application:
Volume concentration reflects regulatory enforcement intensity and labeling compliance thresholds across food and pharmaceutical sectors.
- Food Allergies:Detection of allergenic proteins in biological specimens and food matrices dominates commercial test kit demand. EFSA guidance on precautionary labeling thresholds and EU Food Information for Consumers Regulation mandate quantitative detection at sub-ppm concentrations. Mass spectrometry platforms penetrate verification workflows where protein denaturation compromises immunoassay accuracy.
- Environmental Allergies:Aeroallergen sensitivity assessment supports asthma and allergic rhinitis management protocols. Demand concentrates in German pediatric practices where clinical guideline updates accelerate serological testing adoption. Multiplexing capabilities replace sequential single-analyte workflows.
- Drug Allergies:Hypersensitivity evaluation for pharmaceutical compounds serves specialized clinical populations.
- Insect Allergies:Venom-specific IgE detection guides immunotherapy candidacy decisions.
Food Allergies absorbs the bulk of installed capacity; Environmental Allergies is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized testing clusters concentrate around pharmaceutical and food processing hubs that leverage tax-advantaged research zones to anchor laboratory capacity. The United States, Germany, Japan, Netherlands, and United Kingdom each host distinct regulatory environments that shape local demand patterns and compliance requirements for allergen verification services.
United States
FDA enforcement of Food Safety Modernization Act preventive controls mandates validated allergen verification at critical control points across food manufacturing. The regulatory framework compresses testing timelines and expands demand for rapid immunoassay platforms. Greater Boston and Research Triangle Park clusters anchor contract laboratory capacity serving pharmaceutical and food processor clients.
Germany
Updated DGAKI clinical guidelines accelerate serological testing adoption in pediatric allergy practices throughout Bavaria and North Rhine-Westphalia. EFSA guidance on precautionary labeling thresholds tightens quantitative performance requirements for commercial test kits. Munich and Cologne metropolitan laboratory consortia standardize on automated immunoassay analyzers with unified reporting formats.
Japan
Hospital network procurement consolidation around integrated service contracts transfers instrument obsolescence risk to vendors through per-test pricing structures. METI standards shape diagnostic equipment qualification requirements for clinical laboratory accreditation. Tokyo and Osaka metropolitan clusters displace capital purchase models with operational expenditure frameworks.
Netherlands
Large food manufacturers pilot surface plasmon resonance biosensor arrays at ingredient intake checkpoints, collapsing verification windows from hours to minutes. EU Food Information for Consumers Regulation mandates clear quantitative thresholds that shape test kit performance requirements. Rotterdam and Amsterdam processing hubs anchor European contract laboratory networks.
United Kingdom
ISO 17025 accreditation demands filter laboratory eligibility for pharmaceutical and food industry contracts, extending certification timelines 12-18 months. MHRA guidance aligns with evolving EFSA threshold harmonization efforts for precautionary labeling. London and Cambridge clusters concentrate method development and validation service offerings.
Allergen Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with diagnostic laboratories and food safety verification services following distinct concentration patterns. The vendor base organizes around three archetypes: diversified analytical instrument suppliers, specialized contract testing networks, and focused immunoassay kit manufacturers. Consolidation pressures intensify as laboratory automation requirements raise capital barriers for new entrants. Strategic moves center on geographic network expansion and regulatory validation service bundling.
Within the diversified instrument tier, Thermo Fisher Scientific Inc. exemplifies scale-driven positioning across hospital laboratory supply chains. Eurofins Scientific and SGS S.A. occupy anchor positions in European contract testing, representing the network-architecture archetype that captures compliance margins through validated method portfolios and geographic coverage density.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Eurofins Scientific |
| SGS S.A. |
| Intertek Group PLC |
| Merck KGaA |
| NEOGEN Corporation |
| Romer Labs Division Holding |
| Bureau Veritas S.A. |
| Microbac Laboratories |
| Others |
Pricing and Supply Chain Analysis
Monoclonal antibody production costs in Switzerland and the Netherlands cascade downstream through reagent pricing tiers, with validated immunoassay kits commanding premium positioning against unvalidated alternatives in food processor procurement.
Pricing Analysis
Lead-time compression drives pricing stratification across premium, standard, and economy tiers, with validated allergen verification methods for FDA Food Safety Modernization Act compliance attracting 40-60% markups over research-use-only equivalents. Price differentiation hinges on ISO 17025 certification tier and automation compatibility, with diagnostic laboratories in Japan showing least price sensitivity under integrated service contracts. Pricing pressure stems from contract laboratory consolidation in Europe, while food processors in the United States absorb premium tier costs to avoid regulatory enforcement exposure.
Supply Chain Analysis
Single-source vulnerability sits with contract biologics manufacturers in Switzerland and the Netherlands for monoclonal antibody feedstocks. Reagent supply draws from German precision instrumentation clusters and Chinese membrane substrate producers for lateral flow components. Tariff exposure on biologics imports threatens kit margin stability. Distribution runs through authorized distributor networks anchored at Rotterdam and Singapore logistics hubs, with direct-to-laboratory channels gaining share in North American hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Food Safety Modernization Act preventive controls create a regulatory moat that filters out undercapitalized entrants and anchors pricing power for validated method holders.
For Market Incumbents:Cement defensibility through captive supply of monoclonal antibody reagents and ISO 17025-accredited validation services that emerging competitors cannot replicate within 12-18 month accreditation windows. Threat from mass spectrometry platform displacement in food verification applications demands R&D investment in multi-analyte convergence capabilities.
For New Entrants and Emerging Players:E-commerce direct channels enable bypass of entrenched distributor relationships in point-of-care lateral flow segments, where restaurant and catering self-monitoring remains underpenetrated. White-space concentrates in smartphone-readable environmental screening kits for underserved Asia-Pacific food service markets, with regulatory arbitrage through CE marking pathway offering fastest commercialization route.
For Investors and Strategic Acquirers:Distressed-cycle entries favor contract testing networks with established EFSA validation portfolios in Germany and the Netherlands, where laboratory automation capex requirements have strained mid-tier balance sheets. Long-term viability centers on regulatory validation asset depth rather than instrument hardware. Signal to watch: FDA-EFSA threshold harmonization progress as indicator of method obsolescence risk for single-jurisdiction players.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Service Bundling | Captures compliance margin from manufacturers lacking in-house regulatory affairs capacity under EFSA guidance. |
| Point-of-Care Platform Launch | Enables restaurant sector self-monitoring bypassing laboratory infrastructure constraints in emerging markets. |
| Backward Integration into Reagent Supply | Secures monoclonal antibody feedstock against single-source concentration risk in Swiss and Dutch biologics. |
| Metropolitan Laboratory Consortium Expansion | Standardizes per-test pricing frameworks across Tokyo and Osaka hospital networks transferring obsolescence risk. |
| Mass Spectrometry Workflow Integration | Displaces antibody-dependent methods where protein processing modifications compromise immunoassay accuracy. |
Research Methodology
Independent corroboration across laboratory accreditation databases, regulatory filing repositories, and instrument procurement records underwrites the qualitative findings. Primary interviews with diagnostic laboratory directors, food safety quality managers, clinical allergists, and reagent procurement officers combined with secondary validation from FDA warning letters, EFSA scientific opinions, and ISO 17025 accreditation registries. Bottom-up test volume modeling and top-down market sizing triangulate to segment-level outputs.
Comparable-period anchoring to historical regulatory enforcement intensity and laboratory automation investment cycles shapes the projection framework. Segmentation dimensions span product type, technology platform, end-user category, and application across the modeling period. CAGR derivation incorporates test volume elasticity to guideline updates, with instrument replacement cycles and reference material availability as industry-specific forecast inputs.
The model holds under stable regulatory threshold definitions; deviation in FDA-EFSA harmonization timelines or monoclonal antibody supply disruptions would shift trajectory. Forecasts reflect documented assumptions about accreditation timeline stability and reagent batch consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Bottled Water Testing Equipment Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Food Testing, Inspection, and Certification Market