
 Dairy Testing Services Market | 2026-2036
Dairy Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Testing Services Market Outlook
Skilled microbiologist shortages across certified dairy laboratories is unwinding testing turnaround times and pushing automation investment. SGS SA leverages its pan-European laboratory network to sustain high-volume raw milk screening contracts with major cooperatives. Eurofins Scientific SE anchors its competitive position through specialized PCR-based pathogen detection protocols for cheese matrices. Bureau Veritas SA competes on geographic reach, operating accredited dairy testing facilities across multiple continents to serve multinational dairy manufacturers.
Dairy testing services encompass analytical procedures that verify chemical composition, microbiological safety, nutritional content, and contaminant levels in milk-derived products, employing methods capable of detecting somatic cell counts below regulatory thresholds and antibiotic residues at parts-per-billion sensitivity to ensure consumer protection and trade compliance. Microbiological testing commands the largest service type share due to mandatory pathogen screening requirements, while contaminant testing represents the fastest-expanding category as veterinary drug residue regulations tighten across export markets. Chromatography and spectroscopy technologies dominate current laboratory infrastructure, though PCR adoption is accelerating fastest among dairy manufacturers seeking same-day Salmonella and Listeria confirmation.
FDA dairy safety standards, EU REACH chemical frameworks, and China's SAMR national food safety protocols collectively shape testing demand by mandating specific analytical methods and maximum residue limits that laboratories must demonstrate proficiency in before market access. EMA veterinary medicine guidelines and ISO 17025 accreditation requirements further constrain which service providers qualify for commercial dairy testing contracts. Stakeholders must monitor evolving regulatory harmonization between export destinations to determine whether centralized multi-jurisdiction testing investments or region-specific laboratory partnerships offer superior compliance economics.
Market Dynamics
Regulatory tightening across raw milk supply chains is compressing testing turnaround requirements and forcing automation investments to offset microbiologist shortages.
Growth Catalysts
- FDA dairy safety standards:Processed cheese manufacturers in the United States are expanding testing protocols to meet pathogen screening mandates, creating sustained service demand.
- PCR-based pathogen detection:Dairy manufacturers seeking same-day Salmonella and Listeria confirmation are accelerating adoption of molecular diagnostic methods.
- China's SAMR antibiotic residue limits:Raw milk suppliers across Chinese provinces face tightened veterinary drug screening requirements, expanding laboratory service contracts.
Market Restraints
- Skilled microbiologist shortages:Certified dairy laboratories face recruitment gaps that unwind testing throughput capacity and extend result delivery timelines.
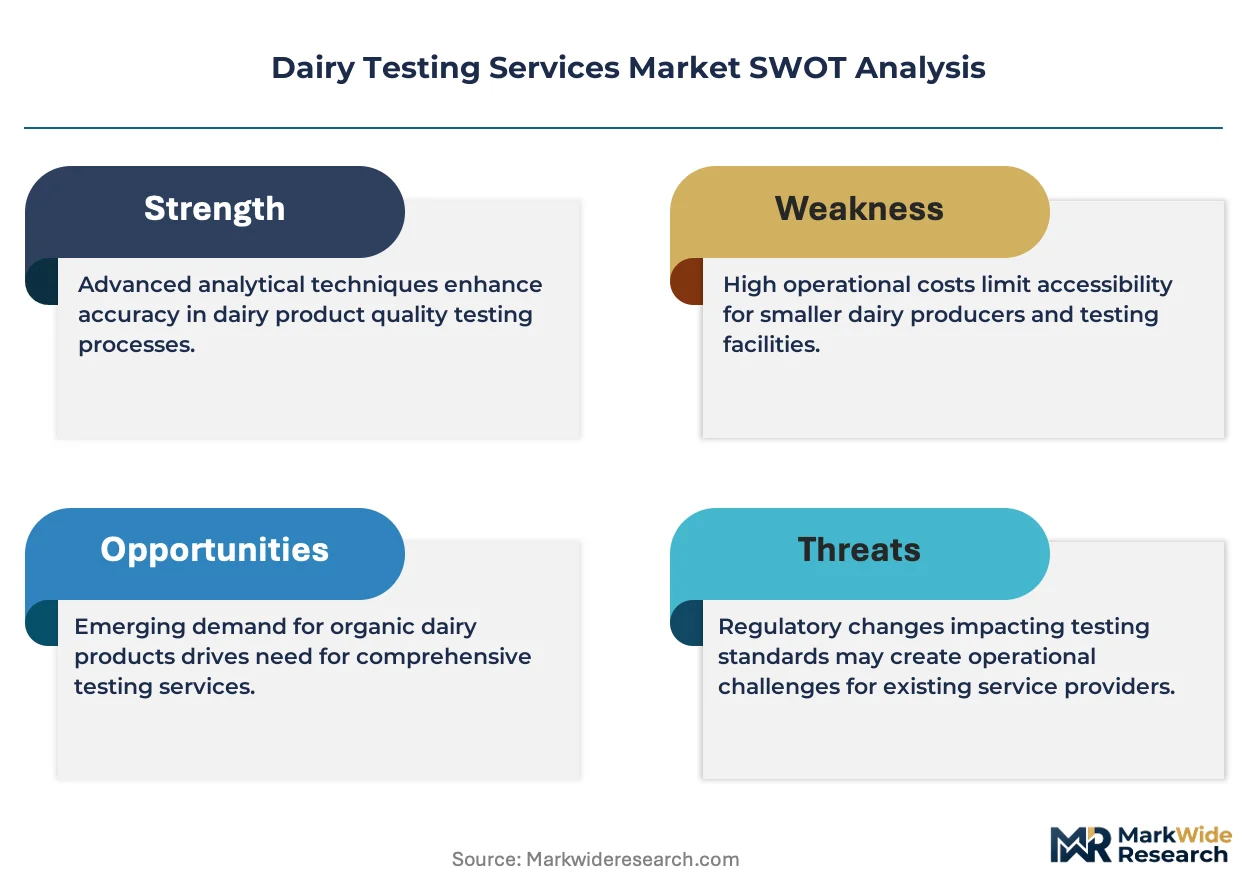
- ISO 17025 accreditation costs:Proficiency demonstration requirements for commercial dairy testing contracts impose substantial fixed compliance expenditures on service providers.
- Chromatography infrastructure lock-in:Existing spectroscopy and chromatography equipment investments slow transition to faster PCR-based detection platforms.
Strategic Opportunities
- India's FSSAI dairy safety expansion:India's national food regulator is extending mandatory testing requirements across cooperative dairy networks, opening laboratory service contracts.
- Blockchain-integrated traceability:Convergence of distributed ledger technology with real-time testing data is enabling tamper-proof supply chain verification for export markets.
- Contaminant testing specialization:Veterinary drug residue regulations tightening across export destinations represent the fastest-expanding service category for differentiated providers.
Industry Challenges
- Multi-jurisdiction harmonization complexity:Laboratories must demonstrate proficiency in FDA, EU REACH, and SAMR protocols simultaneously, straining quality management systems.
- Legacy chromatography integration:PCR adoption acceleration requires workflow reconfiguration alongside existing spectroscopy infrastructure without disrupting high-volume screening operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Testing Services Market |
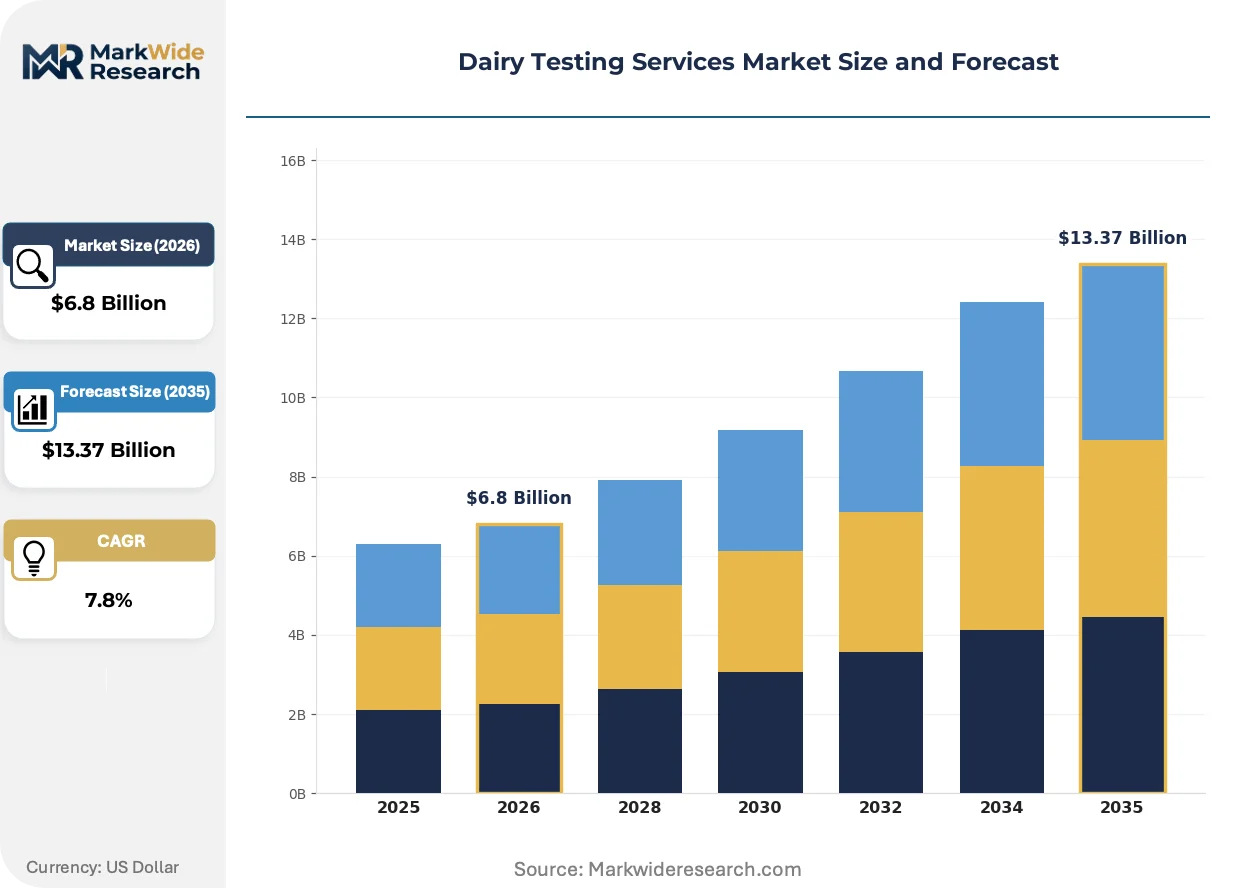
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.37 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Nutritional Analysis, Chemical Testing, Contaminant Testing Product Type: Raw Milk, Cheese, Yogurt, Butter End User: Dairy Manufacturers, Food Safety Agencies, Quality Control Laboratories, Retailers Technology: Chromatography, Spectroscopy, PCR, ELISA |
| Companies Covered | Intertek Group plc, Neogen Corporation, SGS SA, TÜV SÜD AG, Mérieux NutriSciences Corporation, Eurofins Scientific SE, ALS Limited, IDEXX Laboratories Inc., Bureau Veritas SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Testing Services Market Strategic Shifts
Automation and molecular diagnostics are compressing detection timelines while regulatory fragmentation across export markets is forcing laboratories to build multi-protocol capabilities.
PCR-based pathogen detection platforms deliver same-day Salmonella and Listeria confirmation with sensitivity exceeding traditional culture methods. Mid-sized dairy manufacturers in Germany and the Netherlands are adopting these systems at accelerating rates to meet cooperative screening contracts. This technology is supplanting 48-hour culture-based workflows and enabling just-in-time production scheduling previously impossible under extended quarantine holds.
The EU REACH chemical framework and F-Gas Regulation are mandating specific analytical methods for persistent organic pollutant screening in dairy fat matrices. Industrial consequence includes expanded gas chromatography-mass spectrometry capacity investments across European laboratories. Cheese exporters to Germany face the most stringent enforcement, driving centralized multi-jurisdiction testing partnerships over fragmented national laboratory networks.
Consolidated procurement by multinational dairy manufacturers is unbundling after-sales technical support from core testing fees and demanding outcome-based performance guarantees. Regional cooperatives in France and Wisconsin are replacing transactional per-sample pricing with annual service contracts tied to regulatory audit pass rates. This shift is most visible in North American processed cheese manufacturing, where FDA compliance documentation requirements favor long-term laboratory partnerships over spot-market testing arrangements.
Dairy Testing Services Market Segmentation
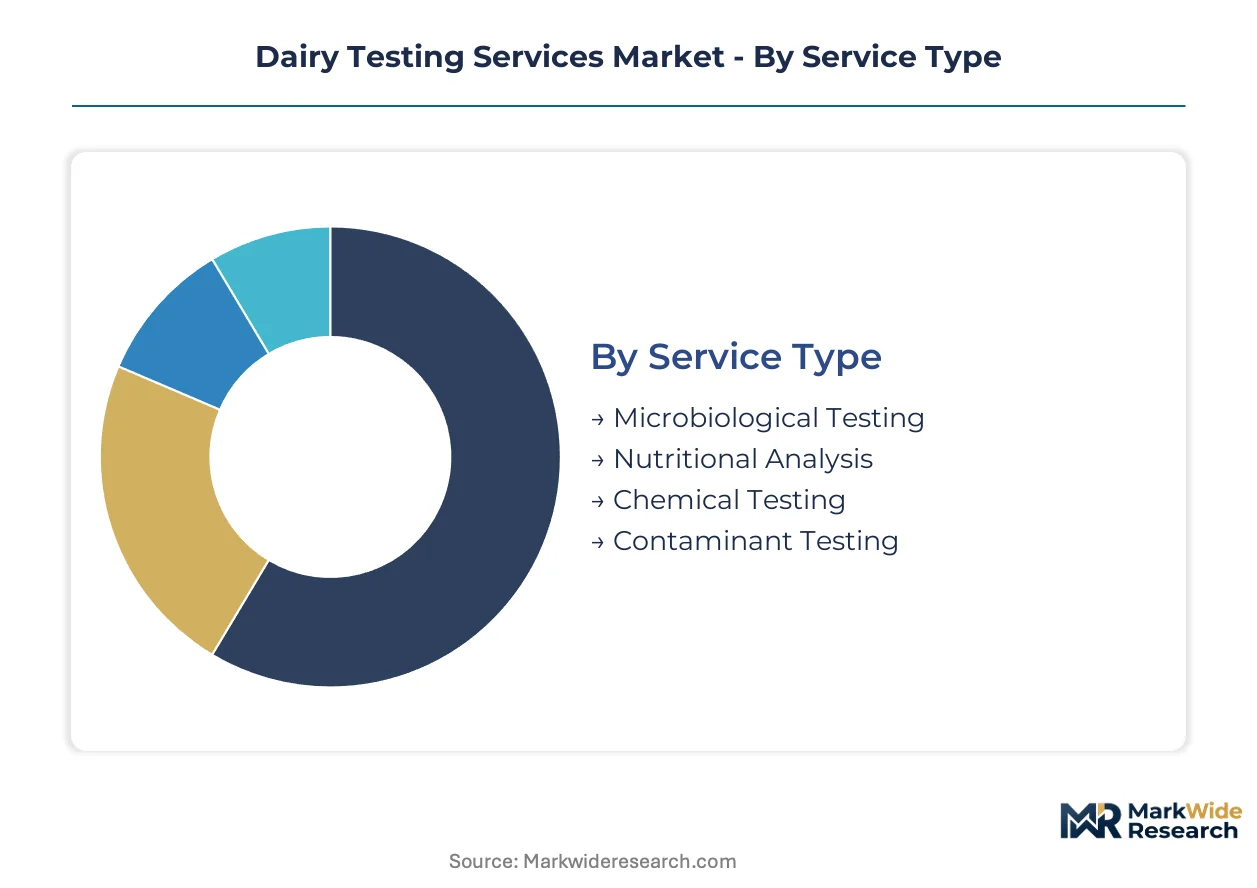
Dairy testing services fragment across service disciplines, product matrices, and detection technologies, each commanding distinct equipment footprints and regulatory compliance burdens. Laboratories configure capabilities around specific customer workflows, from cooperative raw milk screening to processed cheese export certification.
Service Type:
Substitution pressure concentrates most intensely on traditional culture-based methods as molecular diagnostics compress detection timelines and displace legacy protocols across high-volume contracts.
- Microbiological Testing:Pathogen screening protocols detect Salmonella, Listeria, and E. coli in milk-derived matrices at sensitivity thresholds mandated by FDA and EFSA. Demand concentrates in North American processed cheese manufacturing where cooperative contracts require 24-hour turnaround on raw milk intake screening.
- Contaminant Testing:Veterinary drug residue and mycotoxin detection operates at parts-per-billion sensitivity using LC-MS/MS platforms. Chinese SAMR antibiotic limit enforcement across provincial raw milk supply chains is expanding laboratory service contracts fastest among all service categories.
- Nutritional Analysis:Protein, fat, and carbohydrate quantification supports label claim verification and reformulation R&D.
- Chemical Testing:pH, acidity, and somatic cell count determination underpins grade classification and payment systems in cooperative procurement networks.
Microbiological testing retains volume leadership; contaminant testing holds the steepest expansion curve.
Product Type:
Cost tier differentiation separates commodity-grade screening from premium export certification, with cheese and butter commanding higher per-sample fees due to matrix complexity and extended extraction protocols.
- Raw Milk:Intake screening at dairy processing facilities encompasses somatic cell counts, antibiotic residues, and preliminary pathogen detection. Germany's dairy laboratories concentrate demand for rapid pathogen systems serving cooperative networks across Bavaria and Lower Saxony.
- Cheese:Extended aging matrices require specialized pathogen recovery methods and persistent organic pollutant screening under EU REACH frameworks. Export certification to Germany enforces the most stringent analytical requirements, driving centralized multi-jurisdiction testing partnerships.
- Yogurt:Fermented product testing emphasizes live culture enumeration and post-pasteurization contamination screening.
- Butter:Fat-soluble contaminant detection demands modified extraction workflows and GC-MS capacity investments.
Raw milk retains volume leadership; cheese holds the steepest expansion curve.
End User:
Customer type determines contract structure, with dairy manufacturers consolidating procurement under outcome-based performance guarantees while food safety agencies impose proficiency demonstration requirements.
- Dairy Manufacturers:In-house and outsourced testing protocols span intake screening, in-process monitoring, and finished product release. Processed cheese manufacturers in the United States are expanding testing protocols to meet FDA pathogen screening mandates, creating sustained service demand.
- Quality Control Laboratories:Independent third-party providers compete on ISO 17025 accreditation scope and geographic coverage. SGS SA leverages its pan-European laboratory network to sustain high-volume raw milk screening contracts with major cooperatives.
- Food Safety Agencies:Regulatory surveillance and enforcement sampling generates contract laboratory demand with strict chain-of-custody protocols.
- Retailers:Private label dairy product testing supports shelf-life validation and supplier audit requirements.
Dairy manufacturers retain volume leadership; quality control laboratories hold the steepest expansion curve.
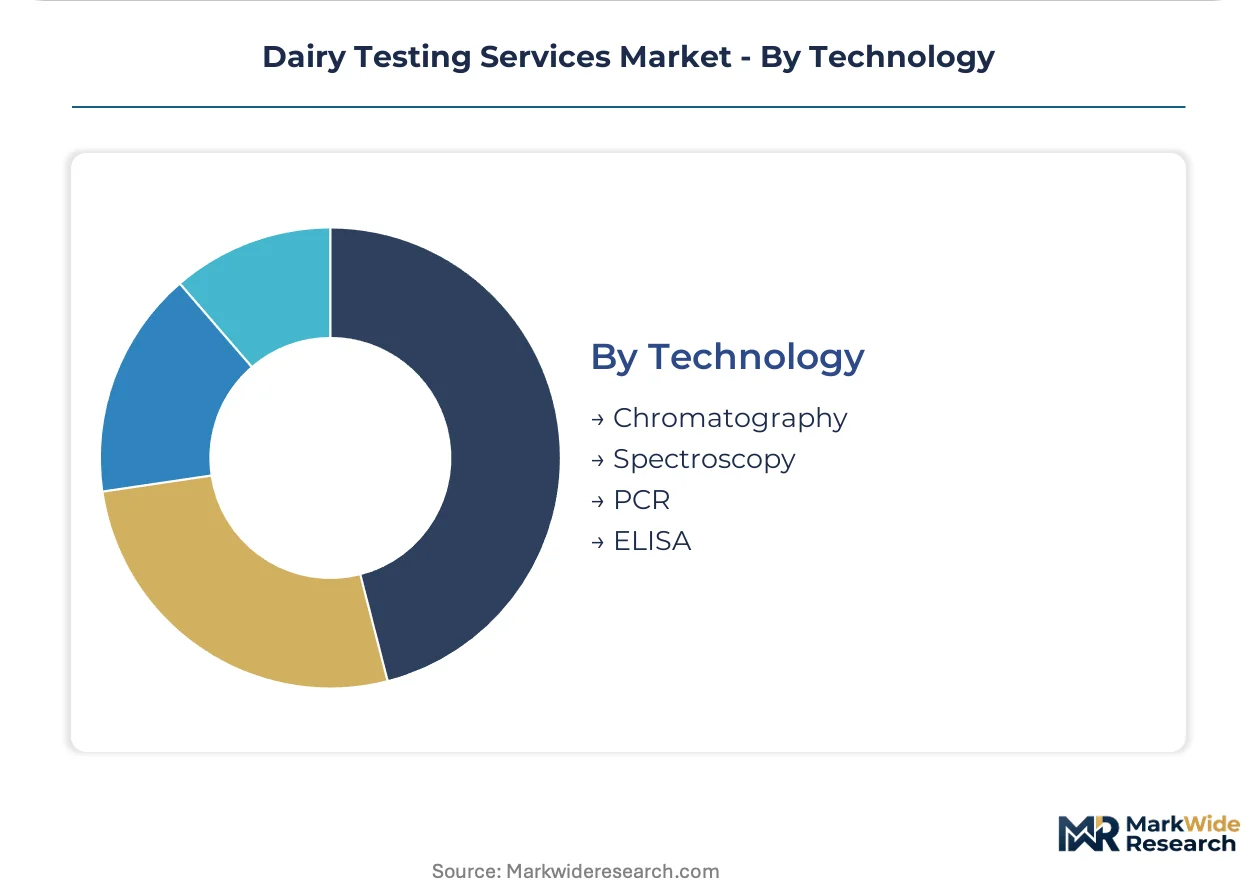
Technology:
Technology maturity curves separate established chromatography infrastructure from accelerating PCR adoption, with capital intensity and workflow reconfiguration costs constraining transition timelines.
- Chromatography:Gas and liquid chromatography platforms dominate persistent organic pollutant and veterinary drug residue quantification in dairy fat matrices. EU REACH chemical frameworks and F-Gas Regulation mandate specific analytical methods, expanding GC-MS capacity investments across European laboratories.
- PCR:Polymerase chain reaction platforms deliver same-day Salmonella and Listeria confirmation with sensitivity exceeding traditional culture methods. Mid-sized dairy manufacturers in Germany and the Netherlands are adopting these systems at accelerating rates to meet cooperative screening contracts.
- Spectroscopy:Infrared and mass spectrometry methods support rapid compositional analysis for payment grading and intake screening.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective screening for antibiotic residues and allergens in lower-throughput settings.
Chromatography retains volume leadership; PCR holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dairy safety standards anchor United States demand, while tightening veterinary drug regulations across export corridors concentrate laboratory investment in Germany and China.
United States
Processed cheese manufacturers in Wisconsin and California are expanding pathogen screening protocols to meet FDA dairy safety mandates. The Pasteurized Milk Ordinance requires certified laboratories for interstate commerce. Chicago-area testing facilities process high volumes for Midwest cooperative networks.
Germany
Dairy laboratories across Bavaria and Lower Saxony concentrate demand for rapid pathogen detection systems serving cooperative networks. EU REACH chemical frameworks mandate specific analytical methods for persistent organic pollutant screening. Cheese exporters in the Allgäu region face the most stringent enforcement, driving centralized testing partnerships.
China
Raw milk suppliers across provincial supply chains face tightened veterinary drug screening requirements under SAMR protocols. National food safety regulators continue compressing antibiotic residue limits. Testing laboratories in Shandong and Inner Mongolia are expanding capacity to serve dairy processing clusters.
India
Cooperative dairy networks in Gujarat and Maharashtra are extending mandatory testing requirements under FSSAI expansion programs. The national food regulator mandates somatic cell count and antibiotic residue screening for organized sector procurement. Anand-based laboratories are scaling operations to serve Amul and regional cooperative supply chains.
Netherlands
Mid-sized dairy manufacturers are accelerating PCR platform adoption to meet cooperative screening contracts for same-day pathogen confirmation. EFSA guidelines and national dairy quality regulations enforce strict microbiological standards. Testing facilities in Friesland serve concentrated cooperative processing infrastructure.
Dairy Testing Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pan-regional laboratory networks competing against technology-focused niche providers. The market structure rewards geographic coverage and accreditation breadth simultaneously. Three archetypes dominate: multi-continental testing conglomerates with ISO 17025 scope across jurisdictions, rapid diagnostics specialists with PCR platform expertise, and regional cooperative-anchored laboratories with embedded procurement relationships. Competitive moves concentrate on strategic partnerships for multi-jurisdiction compliance coverage and automation investments to offset microbiologist shortages.
Within the multi-continental tier, SGS SA, Eurofins Scientific SE, and Bureau Veritas SA exemplify the integrated laboratory network archetype. SGS SA leverages pan-European infrastructure to sustain high-volume raw milk screening contracts. Eurofins Scientific SE occupies a position anchored through specialized PCR-based pathogen detection protocols. Bureau Veritas SA represents geographic reach competition through accredited dairy testing facilities across multiple continents.
| Leading Market Players |
|---|
| Intertek Group plc |
| Neogen Corporation |
| SGS SA |
| TÜV SÜD AG |
| Mérieux NutriSciences Corporation |
| Eurofins Scientific SE |
| ALS Limited |
| IDEXX Laboratories Inc. |
| Bureau Veritas SA |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at ISO 17025-accredited laboratories in Germany and the United States shapes both supply concentration and price floors, as fixed accreditation costs and microbiologist shortages prevent marginal players from undercutting established providers on routine screening contracts.
Pricing Analysis
Per-sample fees in Wisconsin and California exceed those in Shandong province by a factor reflecting labor costs and regulatory documentation burdens. Contract-based long-term offtake dominates, with annual service agreements tied to FDA audit pass rates replacing transactional pricing. Price differentiation rests on ISO 17025 scope breadth and geographic coverage, with pan-continental networks commanding premiums over single-facility competitors. Cost compression in commodity-grade raw milk screening is intensifying because cooperative procurement offices are consolidating vendor panels. Dairy manufacturers with in-house laboratories exhibit lowest price sensitivity; regional cooperatives without captive testing capacity face highest procurement pressure.
Supply Chain Analysis
Germany and the United States anchor high-throughput chromatography and PCR platform manufacturing, while China concentrates production of consumables and reagent kits for veterinary drug residue detection. Laboratory equipment draws from precision optics suppliers in Japan, semiconductor components from Taiwan, and specialized enzymes from Denmark. Single-source vulnerability concentrates in CRISPR primer synthesis for pathogen detection assays. Distribution runs through manufacturer-direct sales for large dairy processors and regional distributor networks serving cooperative laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent testing providers must defend against substitution by rapid at-home diagnostic platforms and in-house PCR adoption among large dairy manufacturers seeking same-day turnaround without external laboratory dependency.
For Market Incumbents: Consolidate accreditation scope across FDA, EU REACH, and SAMR protocols to capture multi-jurisdiction export certification demand from cheese manufacturers. Acquire regional cooperative-anchored laboratories in India and the Netherlands to preempt white-space entry. Automation investment in Bavaria and Lower Saxony facilities offsets microbiologist recruitment gaps while preserving throughput capacity.
For New Entrants and Emerging Players: ISO 17025 fast-track partnerships with existing pan-European networks offer immediate credential access without full accreditation timelines. Target India's FSSAI expansion programs across Gujarat and Maharashtra cooperative networks, where incumbent coverage remains thin. Position on PCR platform specialization for same-day Salmonella confirmation, displacing 48-hour culture methods in mid-sized German dairy manufacturers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rapid diagnostics specialists with installed PCR bases over chromatography-heavy legacy providers facing infrastructure lock-in. Five-to-ten-year viability hinges on molecular platform transition completion before culture-based method obsolescence accelerates. Acquisition target archetype: regional laboratories with embedded cooperative relationships and underutilized ISO 17025 scope. Signal to watch: SAMR antibiotic limit enforcement intensity across Chinese provincial supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| PCR Platform Deployment | Same-day Salmonella confirmation displaces 48-hour culture methods in German cooperatives. |
| Multi-Jurisdiction Accreditation | Simultaneous FDA, EU REACH, and SAMR scope captures cheese export certification demand. |
| Automation Investment | Robotic sample handling offsets microbiologist shortages at high-volume raw milk screening facilities. |
| Blockchain Traceability Integration | Tamper-proof testing data verification opens premium export market access for dairy manufacturers. |
| Contaminant Testing Specialization | Veterinary drug residue expertise at parts-per-billion sensitivity differentiates providers in Chinese SAMR enforcement. |
Study Parameters
A spread of perspectives from laboratory operations directors, dairy cooperative procurement managers, regulatory affairs specialists at FDA and SAMR, and PCR platform engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through ISO 17025 accreditation databases, FDA warning letter archives, SAMR regulatory bulletins, and EU REACH substance restriction updates. Bottom-up triangulation against top-down market sizing from equipment installation records and reagent consumption data anchored volume estimates.
Segmentation dimensions modeled span service type, product matrix, detection technology, and end-user archetype across the projection horizon. Analytical framework derived CAGRs from equipment replacement cycles, regulatory mandate implementation timelines, and cooperative procurement contract renewal patterns. Forecast inputs incorporated PCR adoption curves in Germany and the Netherlands, SAMR enforcement intensity trajectories across Chinese provinces, and FSSAI expansion program rollout schedules in India.
Underlying assumptions cover regulatory harmonization stability, equipment cost decline curves, and microbiologist labor market tightness, with deviation risk concentrated in abrupt SAMR protocol revisions or PCR platform reliability breakthroughs enabling full in-house substitution. Recalibration cycles align with material shifts in FDA dairy safety standard updates and EU REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Food Testing Services Market