
 Food Safety Software Market | 2026-2036
Food Safety Software Market Size, Share, and Industry Trends Forecast 2026-2036
Food Safety Software Market Intelligence
Food safety auditor shortages across the hospitality and manufacturing sectors is reorganizing how enterprises procure automated compliance platforms. SafetyChain leverages cloud infrastructure to serve mid-market processors with distributed facility networks. Ideagen Safefood 360° anchors its position through integrated quality management modules that span supplier qualification to finished-product release. FoodLogiQ competes on blockchain-enabled traceability, differentiating its offering for protein and produce supply chains.
Food safety software comprises digital platforms that automate hazard analysis, temperature monitoring, corrective action tracking, and regulatory documentation across food production and distribution environments. These systems typically integrate IoT sensor feeds, mobile inspection workflows, and centralized dashboards to enforce HACCP plans and FSMA compliance in real time. Cloud-based solutions occupy the dominant revenue position due to lower deployment friction and automatic regulatory update propagation. Artificial Intelligence is the fastest-growing technology segment, with machine learning models flagging contamination risks from pattern anomalies in production data. Traceability applications command premium pricing as lot-level tracking becomes mandatory for high-risk commodities.
The FDA enforces FSMA Section 204 traceability recordkeeping requirements, compelling covered entities to maintain digital event logs for designated foods. USDA FSIS inspection protocols and ISO 22000 certification standards further shape software feature roadmaps, particularly in meat and poultry processing. The EU's General Food Law and rapidly advancing digitization under the European Food Safety Authority's data collection frameworks are elevating cross-border compliance complexity. Stakeholders must evaluate platform interoperability against evolving multi-jurisdiction audit formats before committing to long-term contracts.
Market Dynamics
FSMA Section 204 traceability mandates are compressing procurement timelines as restaurant chains and protein processors scramble to deploy lot-level tracking before enforcement deadlines hit. Cloud infrastructure investments by mid-market operators are redrawing competitive boundaries between integrated suites and point solutions.
Growth Catalysts
- IoT sensor networks:Temperature monitoring hardware is dropping below $15 per node, enabling real-time HACCP enforcement in quick-service kitchens and cold-chain warehouses.
- FDA FSMA Section 204:Mandatory digital event logs for high-risk foods are forcing covered entities to replace paper-based traceability within 24 months.
- Auditor shortages:The American Society for Quality reports 40% fewer certified food safety auditors than 2019, accelerating automation of inspection workflows.
Market Restraints
- Implementation costs:Enterprise deployments require $200K-$500K in integration labor, freezing mid-market buyers in evaluation cycles.
- Cloud concentration:Three hyperscalers control 78% of food safety SaaS infrastructure, creating single-point-of-failure risk for multi-site operators.
- Legacy ERP incompatibility:AS/400 and on-premise SAP instances in meatpacking plants block API-based data flows without expensive middleware.
Strategic Opportunities
- Smallholder supplier onboarding:Produce distributors in Mexico and Central America lack digital traceability, creating white space for mobile-first platforms.
- AI predictive contamination:Machine learning models analyzing sanitation sensor data can flag listeria risk 48 hours before swab tests.
- Blockchain-IoT convergence:Immutable ledgers paired with automated sensor feeds are commanding 40% pricing premiums in premium protein supply chains.
Industry Challenges
- Data science talent scarcity:Food manufacturers compete with fintech for Python-trained analysts who can configure anomaly detection models.
- Multi-jurisdiction audit formats:ISO 22000, BRC, and SQF certification bodies use incompatible data schemas, forcing redundant system configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Safety Software Market |
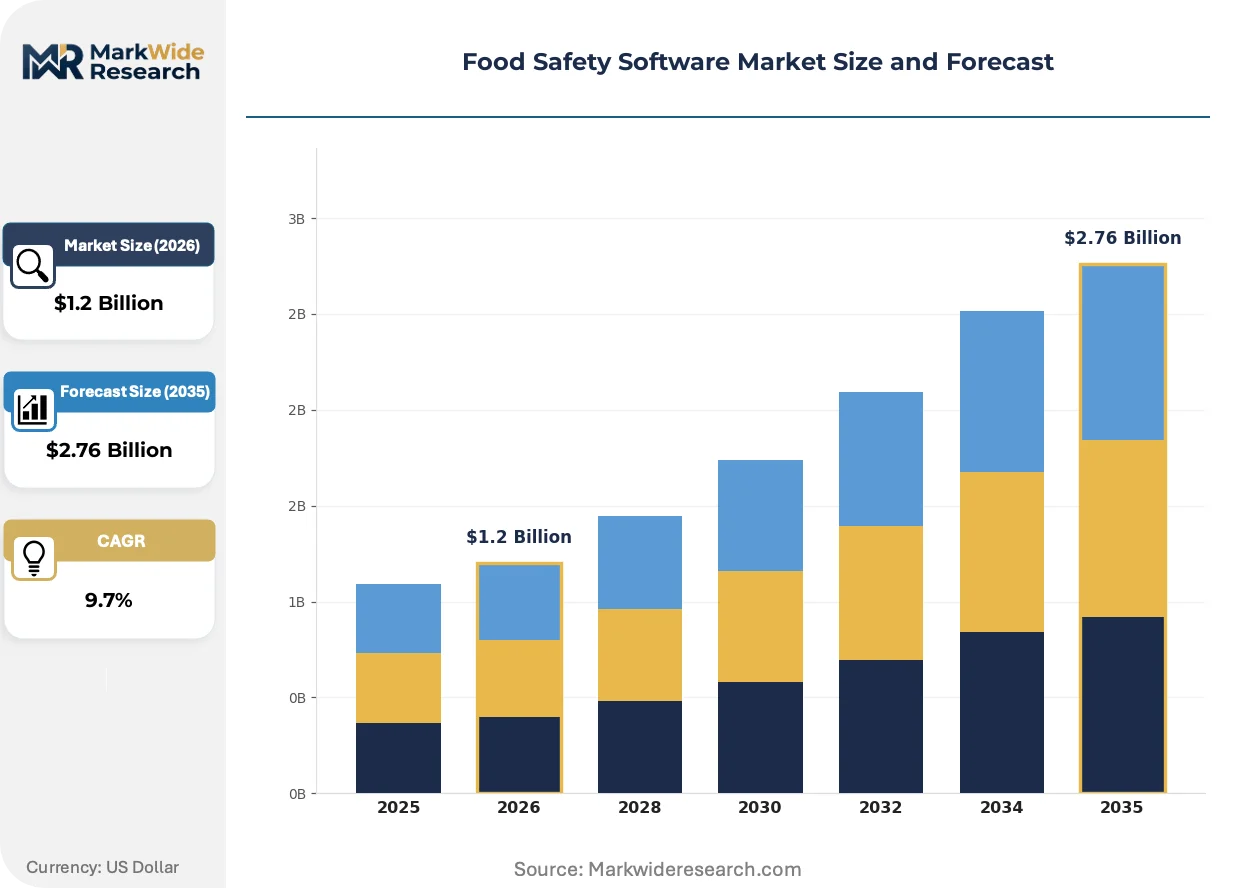
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.76 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premise Solutions, Mobile Applications, Compliance Management Tools End User: Food Manufacturers, Distributors, Retailers, Restaurants Technology: Blockchain, Artificial Intelligence, IoT, Data Analytics Application: Quality Assurance, Regulatory Compliance, Risk Management, Traceability |
| Companies Covered | FoodDocs, Xenia, Jadian, NORMEX, FoodReady, SafetyChain, Ideagen Safefood 360°, GFSC Group, FoodLogiQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Safety Software Market Strategic Shifts & Innovations
Artificial intelligence is rewriting how contamination risks surface, while regulatory deadlines compress deployment windows. Platform architectures are splitting between lightweight mobile tools and heavy enterprise suites.
Machine learning-based hazard prediction is bifurcating the vendor landscape. These models ingest sanitation schedules, temperature logs, and supplier quality data to flag contamination probability. Large protein processors with dedicated data science teams are building in-house capabilities, while mid-market operators subscribe to SaaS prediction modules. The technology is bifurcating pricing power toward platforms with proprietary training datasets spanning multiple facilities.
EU General Food Law digitization mandates are elevating cross-border compliance complexity. EFSA's new data collection frameworks require harmonized electronic formats for risk assessment submissions. Protein exporters to the European Union are retrofitting traceability systems to capture additional allergen and origin attributes, diverting R&D budgets from feature innovation toward regulatory alignment.
Subscription-based compliance monitoring is displacing perpetual license models in the mid-market. Foodservice distributors previously bought on-premise software with three-year amortization; they now prefer per-location monthly fees with automatic regulatory updates. This shift is most visible among US-based restaurant chains with 50-200 locations, where CFOs prioritize OpEx predictability over capital efficiency.
Food Safety Software Market Segmentation
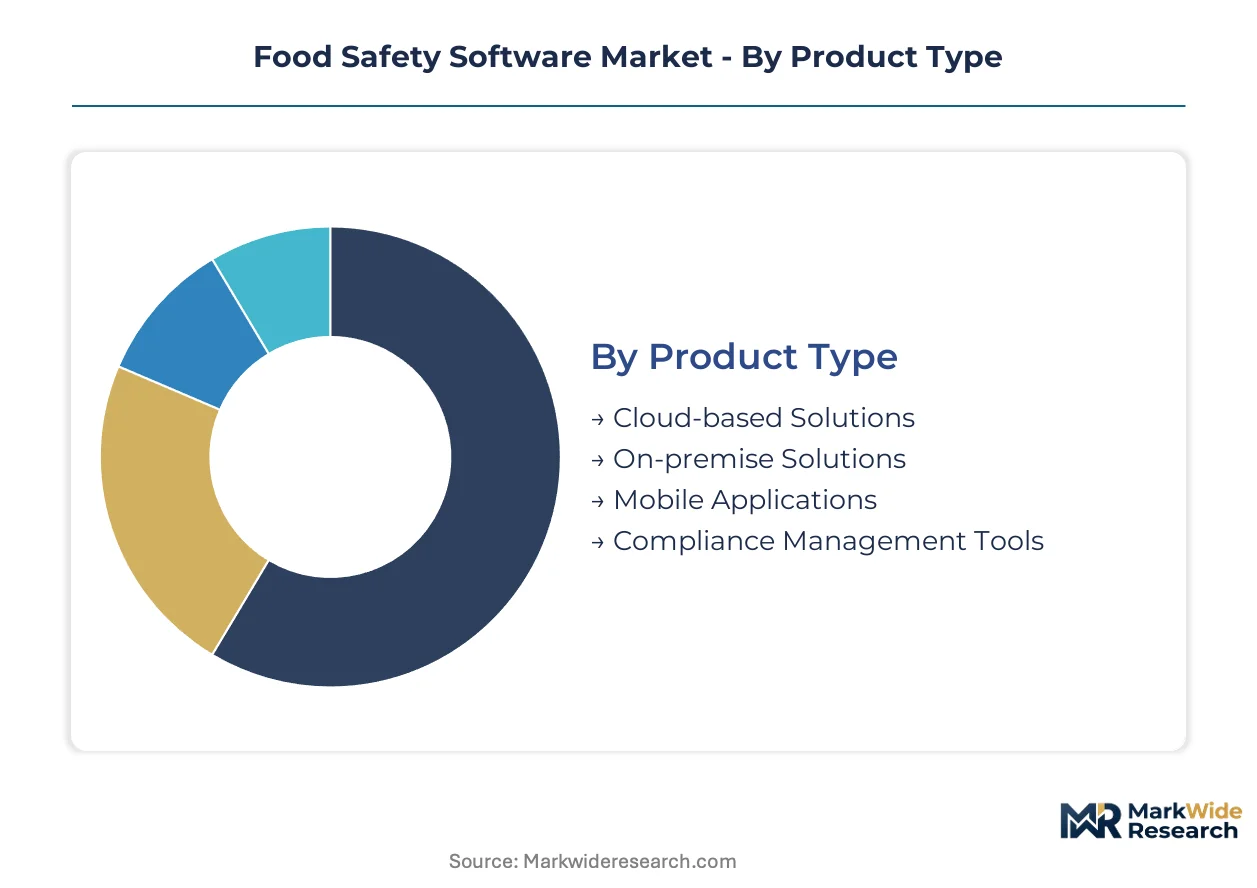
Food safety software procurement patterns diverge sharply across deployment models and end-use contexts. Buyers weigh integration complexity against regulatory urgency when selecting between cloud-native platforms and legacy on-premise systems.
Product Type:
Cloud-based solutions face intensifying substitution pressure from AI-enhanced mobile platforms that bypass traditional infrastructure requirements entirely.
- Cloud-based Solutions:Multi-tenant architectures with automatic FSMA update propagation dominate mid-market processor procurement. Restaurant chains with 50-200 locations in the United States prioritize OpEx predictability over capital deployment.
- On-premise Solutions:Air-gapped installations persist in defense-contracted protein processing and classified government foodservice operations. AS/400 legacy dependencies in meatpacking plants create API friction that blocks cloud migration.
- Mobile Applications:Offline-capable inspection workflows with QR code lot scanning serve field auditors in distributed facility networks.
- Compliance Management Tools:Point solutions for HACCP documentation target smallholder supplier onboarding in Mexican and Central American produce distribution.
Cloud-based solutions anchor the volume base while mobile applications gain share at the steepest rate.
End User:
Cost tier stratification separates enterprise-grade integrated suites from lightweight point solutions across buyer categories.
- Food Manufacturers:Protein processors with dedicated data science teams build in-house machine learning capabilities for contamination prediction. Mid-market operators subscribe to SaaS prediction modules instead.
- Distributors:Cold-chain warehouse operators deploy temperature monitoring hardware below $15 per node for real-time HACCP enforcement.
- Retailers:Grocery chains mandate blockchain-enabled traceability from premium protein suppliers, accepting 40% pricing premiums for immutable lot records.
- Restaurants:Quick-service operators compress procurement timelines to meet FDA FSMA Section 204 enforcement deadlines.
Food manufacturers anchor the volume base while restaurants gain share at the steepest rate.
Technology:
Application maturity separates production-ready sensor networks from experimental predictive models still requiring human validation loops.
- Blockchain:Immutable ledgers paired with automated IoT feeds command premium pricing in premium protein supply chains. EU exporters retrofit systems to capture additional allergen attributes for EFSA harmonized submissions.
- Artificial Intelligence:Machine learning models analyzing sanitation sensor data flag listeria risk 48 hours before swab tests. Python-trained analysts configure anomaly detection in competition with fintech recruiters.
- IoT:Temperature monitoring nodes enable real-time cold-chain enforcement across quick-service kitchens and distribution centers.
- Data Analytics:Pattern recognition dashboards consolidate multi-facility quality metrics for centralized compliance oversight.
IoT anchors the volume base while artificial intelligence expands most quickly.
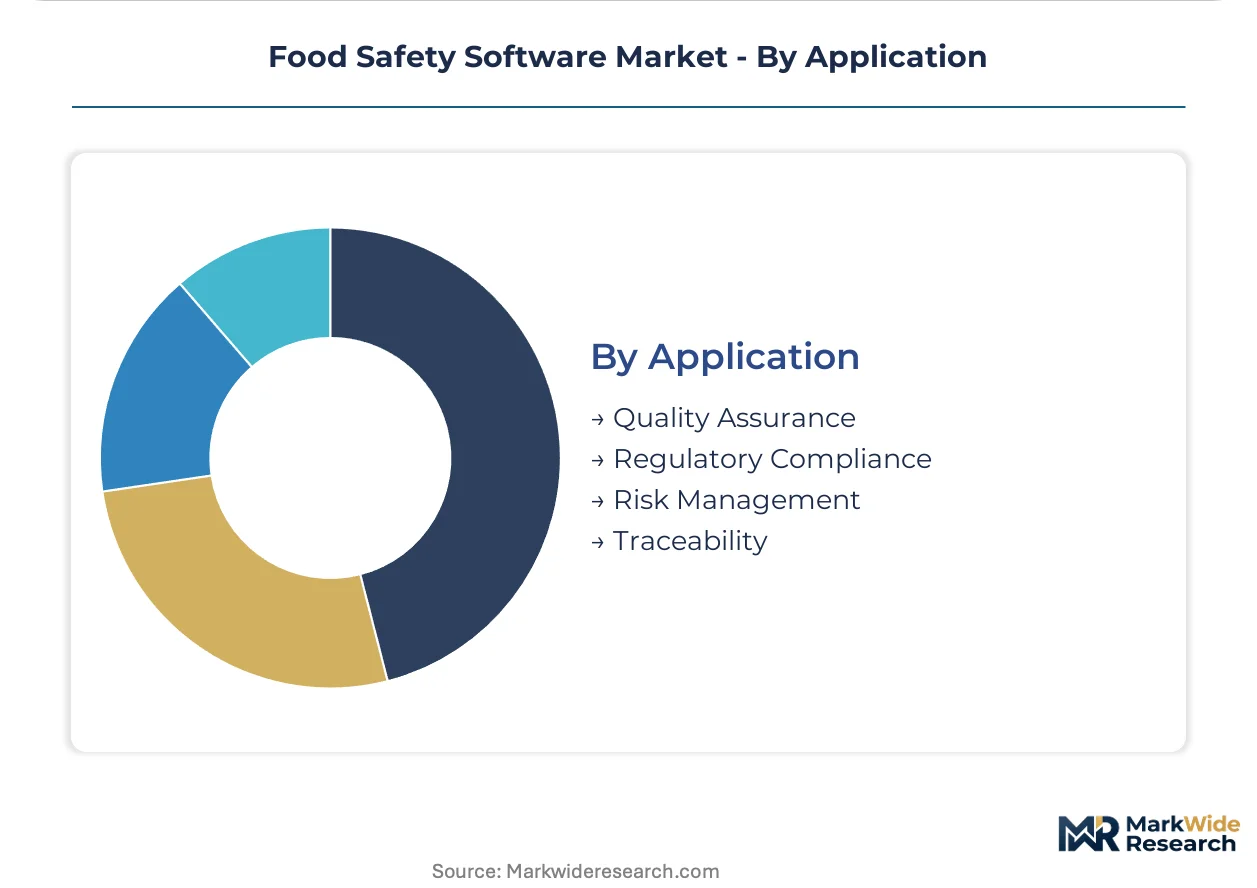
Application:
Customer type differentiation separates preventive quality investments from reactive compliance spending triggered by enforcement deadlines.
- Quality Assurance:Integrated quality management modules span supplier qualification through finished-product release. ISO 22000, BRC, and SQF certification bodies force redundant system configurations.
- Regulatory Compliance:Digital event logs for high-risk foods replace paper-based traceability within compressed procurement windows. USDA FSIS inspection protocols shape meat and poultry software roadmaps.
- Risk Management:Predictive sanitation scheduling reduces contamination probability through pattern-based hazard flagging.
- Traceability:Lot-level tracking mandates elevate cross-border compliance complexity for protein exporters to the European Union.
Regulatory compliance anchors the volume base while traceability climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA traceability mandates under FSMA Section 204 are compressing procurement timelines across the United States. Restaurant chains and protein processors face enforcement deadlines that accelerate software deployment decisions.
United States
Quick-service operators with 50-200 locations prioritize cloud-native platforms for OpEx predictability. FDA FSMA Section 204 mandates digital event logs for high-risk foods within compressed windows. Chicago and Dallas-Fort Worth anchor cold-chain warehouse deployments where temperature monitoring nodes drop below $15 per unit.
Germany
Meatpacking plants in Baden-Württemberg and Lower Saxony retrofit traceability systems for EU General Food Law digitization. EFSA harmonized submission requirements demand additional allergen and origin attributes. Munich-based processors invest in integrated quality management modules spanning supplier qualification to finished-product release.
China
Domestic food manufacturers adopt AI-enhanced sanitation monitoring for listeria risk prediction. SAMR traceability standards for high-risk commodities align with export market requirements. Yangtze River Delta processors in Shanghai and Suzhou deploy blockchain-IoT convergence for premium protein supply chains.
Brazil
Protein exporters to the European Union retrofit systems for EFSA cross-border compliance complexity. ANVISA digital health surveillance frameworks elevate documentation requirements. São Paulo and Minas Gerais cold-chain operators substitute paper-based traceability with mobile-first inspection workflows.
India
FSSAI food safety compliance mandates accelerate SaaS procurement among mid-market processors. Smallholder supplier onboarding in produce distribution creates white space for mobile-first platforms. Maharashtra and Gujarat enterprise accounts with multi-site operations concentrate demand for cloud infrastructure.
Food Safety Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with tiered pricing separating enterprise-grade suites from lightweight point solutions. Cloud-native platforms with automatic regulatory update propagation command premium positioning against on-premise legacy installations. Two strategic archetypes dominate: integrated quality management suites spanning supplier qualification to release, and blockchain-enabled traceability specialists for premium protein supply chains. Competitive moves concentrate on M&A for data science talent and strategic partnerships for smallholder supplier onboarding.
Within the integrated suite tier, SafetyChain and Ideagen Safefood 360° exemplify cloud infrastructure approaches for mid-market processors with distributed facility networks. FoodLogiQ occupies a position representing blockchain-IoT convergence for immutable lot records in protein and produce supply chains. These three anchors illustrate how vendor positioning splits between predictive AI modules and regulatory compliance automation.
| Leading Market Players |
|---|
| FoodDocs |
| Xenia |
| Jadian |
| NORMEX |
| FoodReady |
| SafetyChain |
| Ideagen Safefood 360° |
| GFSC Group |
| FoodLogiQ |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure substitution for on-premise installations is redrawing supply geography toward hyperscaler data centers in the United States, Ireland, and Singapore while compressing pricing economics through subscription standardization. This displacement simultaneously elevates buyer power among mid-market restaurant chains and fragments margin capture across software vendors competing on regulatory update velocity.
Pricing Analysis
North American enterprise deployments command 35-50% premiums over equivalent Southeast Asian implementations due to FSMA compliance bundling and after-sales implementation support. SaaS-tiered pricing stratifies across premium AI-enhanced modules, standard cloud-native suites, and economy mobile-only tiers, with differentiation resting on ISO 22000 certification depth and predictive analytics integration. Cost compression in the mid-market tier is intensifying because hyperscaler infrastructure commoditizes core platform delivery. Quick-service operators with 50-200 locations exhibit highest price sensitivity, while protein exporters to the European Union accept elevated fees for EFSA-aligned traceability configurations.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and Rotterdam elevates inbound logistics costs for temperature monitoring hardware sourced from Shenzhen and Taipei manufacturing clusters. Software development capacity concentrates in the United States, India, and Ireland, with implementation services drawing from Eastern European technical talent pools. The supply chain rests on semiconductor components for IoT sensor nodes, cloud compute credits from three dominant hyperscalers, and Python-trained data science labor competing with fintech recruiters. Single-source vulnerability permeates cloud infrastructure concentration, with downstream distribution running through direct enterprise sales teams, systems integrator partnerships, and mobile app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Python-trained data scientists capable of configuring anomaly detection models represent the critical capability gap constraining platform differentiation, with food manufacturers losing talent to fintech recruiters at accelerating rates.
For Market Incumbents: Shield installed base relationships by embedding predictive AI modules that increase switching costs for mid-market processors with distributed facility networks. Deepen backward integration into proprietary training datasets spanning multiple facilities to defend against SaaS prediction module substitutes. Prioritize certification investment in ISO 22000, BRC, and SQF alignment to capture auditor shortage-driven automation demand. For New Entrants and Emerging Players: Lead with mobile-first inspection workflows targeting smallholder supplier onboarding in Mexican and Central American produce distribution, the most penetrable white space lacking digital traceability infrastructure. Anchor go-to-market through produce distributor partnerships that aggregate fragmented grower networks. Target blockchain-IoT convergence for premium protein supply chains where immutable ledgers command pricing premiums. For Investors and Strategic Acquirers: The market sits at a regulatory-deadline compression phase that favors platforms with automatic FSMA update propagation and established multi-site deployment playbooks. Long-term viability centers on data science talent acquisition and proprietary training dataset accumulation. Monitor FDA enforcement timeline acceleration as the primary inflection indicator for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Prediction Module Launch | Machine learning contamination flagging addresses auditor shortages across protein processing facilities. |
| Blockchain-IoT Platform Integration | Immutable sensor feeds satisfy EU General Food Law digitization mandates for premium exporters. |
| Smallholder Supplier Partnership | Mobile-first onboarding captures white space in Mexican and Central American produce distribution. |
| Hyperscaler Infrastructure Agreement | Multi-cloud deployment mitigates single-point-of-failure risk for multi-site restaurant operators. |
| Regulatory Update Automation | Automatic FSMA Section 204 propagation compresses procurement timelines for quick-service chains. |
Research Approach
A spread of perspectives from food safety officers at protein processors, compliance directors at restaurant chains, CTOs at cold-chain distributors, and regulatory affairs leads at software vendors converged on the working assumptions. Primary interviews combined with secondary validation from FDA FSMA guidance documents, USDA FSIS inspection protocols, EFSA data collection frameworks, and ISO 22000 certification body requirements. Bottom-up deployment sizing across 50-200 location restaurant chains and top-down market aggregation triangulated volume estimates.
Segmentation dimensions modeled span deployment model, organization size, technology type, and application use case across the projection horizon. Deployment model captures cloud-native, on-premise, mobile, and compliance tool categories. Organization size stratifies enterprise, mid-market, and smallholder tiers. Technology type tracks IoT, AI, blockchain, and data analytics adoption patterns. CAGRs derived from facility expansion rates, regulatory deadline enforcement schedules, and sensor hardware cost curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of FSMA Section 204, continued hyperscaler infrastructure availability, and stable data science labor supply would require recalibration. Forecasts reflect assumptions regarding regulatory timeline adherence, cloud migration velocity among meatpacking plants with AS/400 dependencies, and AI model accuracy validation protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Bar Inspection System Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market
Food Safety and Standards
Food Certification Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Pathogen Reduction Systems Market