
 Amylase Testing Market | 2026-2036
Amylase Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Amylase Testing Market Outlook
Synthetic substrate chemistry is consolidating around chromogenic reagent formats that replace older iodine-starch methods, reducing assay variability and shortening turnaround times. Novozymes leverages its industrial enzyme heritage to anchor supply relationships with diagnostic reagent manufacturers. DSM sustains competitive positioning through specialized biocatalyst R&D programs targeting clinical assay applications. Amano Enzyme differentiates via precision fermentation capabilities that yield batch-consistent amylase reference materials.
Amylase testing encompasses laboratory analytical methods that quantify alpha-amylase enzyme activity in biological specimens, typically employing defined substrate hydrolysis rates measured at 37 degrees Celsius with pH stabilization between 6.7 and 7.0. These assays serve primary diagnostic functions for acute pancreatitis, mumps complications, and salivary gland disorders across clinical and veterinary settings. Reagents and kits capture the dominant value share given recurring consumption patterns, while enzymatic assays maintain technology leadership due to standardized CLSI protocols and broad instrument compatibility. Spectrophotometry instrumentation occupies the premium tier where laboratories seek automated throughput, whereas immunoassay formats represent the fastest-expanding segment through point-of-care integration.
The FDA governs in vitro diagnostic reagent classifications under 21 CFR 809, while the Clinical Laboratory Improvement Amendments mandate proficiency testing for amylase assay accuracy. ISO 15189 accreditation requirements in Europe and Japan's PMDA quality management standards further shape product registration pathways and laboratory purchasing criteria. Stakeholders must monitor evolving harmonization efforts between FDA and IVD-R regulations in Europe, as divergent performance validation requirements will determine which assay platforms achieve multi-jurisdictional commercialization.
Market Dynamics
Chromogenic substrate chemistry is displacing iodine-starch methods across diagnostic laboratories, compressing assay turnaround times while elevating precision requirements for reagent manufacturers. This substrate transition is reshaping procurement criteria and forcing capital redeployment toward automated spectrophotometry platforms.
Growth Catalysts
- CLSI Protocol Harmonization:Standardized enzymatic assay methodologies reduce inter-laboratory variability, accelerating kit adoption in hospital networks seeking accreditation compliance.
- Point-of-Care Expansion:Immunoassay format miniaturization enables amylase testing outside centralized laboratories, opening ambulatory and emergency department channels.
- Veterinary Diagnostics:Companion animal pancreatitis screening protocols in specialty clinics drive parallel demand for species-validated reagent formulations.
Market Restraints
- Reference Material Scarcity:Batch-consistent human pancreatic amylase calibrators concentrate among limited fermentation specialists, creating supply vulnerability.
- Regulatory Divergence:FDA 21 CFR 809 classification requirements and EU IVD-R performance validation standards impose duplicative clinical studies, extending commercialization timelines.
- Substitute Biomarkers:Lipase assays demonstrate superior pancreatitis specificity in acute presentations, pressuring amylase test volume in emergency settings.
Strategic Opportunities
- Asia-Pacific Laboratory Consolidation:China's hospital network centralization creates demand for high-throughput automated platforms in tier-one cities.
- CLIA Waived Test Development:FDA clearance for waived complexity amylase assays would unlock physician office laboratory segments.
- Digital Pathology Convergence:Integration of spectrophotometric data with laboratory information systems enables predictive analytics for pancreatitis risk stratification.
Industry Challenges
- Multiplexing Expertise Gap:Clinical laboratories lack personnel trained in combined amylase-lipase panel optimization on integrated chemistry analyzers.
- Proficiency Testing Burden:CLIA-mandated external quality assessment programs require continuous reagent lot validation, consuming technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amylase Testing Market |
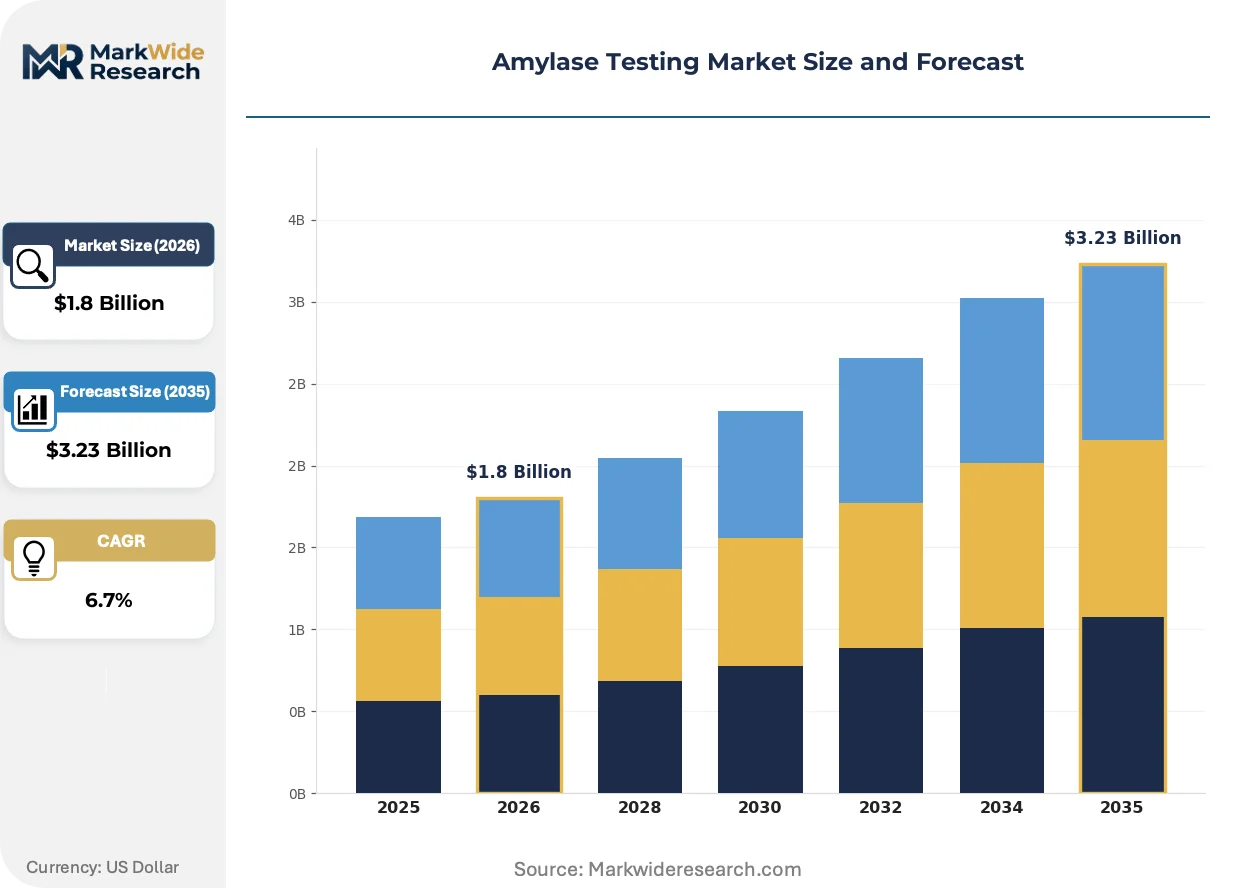
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Technology: Enzymatic Assays, Chromatography, Immunoassays, Spectrophotometry Application: Clinical Diagnosis, Research Studies, Veterinary Testing, Food Industry |
| Companies Covered | Novozymes, DSM, BASF, Amano Enzyme, DuPont, Advanced Enzyme Technologies, AB Enzymes, Suzhou Sino Enzymes, Shenzhen Leveking Bio-Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amylase Testing Market Strategic Shifts
Synthetic substrate engineering and assay automation are converging to redefine performance benchmarks. These developments are compressing the gap between reference laboratory accuracy and point-of-care convenience.
Dry chemistry reagent strips are integrating chromogenic indicator systems with solid-phase stabilization, enabling room-temperature storage and simplified workflow. Reference laboratories in Germany and Japan are adopting these formats for satellite clinic networks. The technology is integrating decentralized testing infrastructure into centralized quality frameworks without sacrificing traceability.
EU IVD-R technical documentation requirements are mandating clinical performance studies with defined pancreatitis patient cohorts, elevating evidence standards above predecessor directives. Reagent manufacturers must now submit post-market surveillance plans with defined safety indicators. Medium-sized diagnostic companies are responding through strategic partnerships with academic medical centers to access characterized specimen biobanks.
Hospital procurement committees are consolidating chemistry and immunoassay contracts under single-source agreements, displacing best-of-breed reagent purchasing. Integrated delivery networks in the United States are negotiating multi-year supply arrangements that bundle amylase testing with broader metabolic panels. This concentration is most visible in Medicare Advantage plan-affiliated health systems seeking standardized cost-per-test metrics across affiliated laboratories.
Amylase Testing Market Segmentation
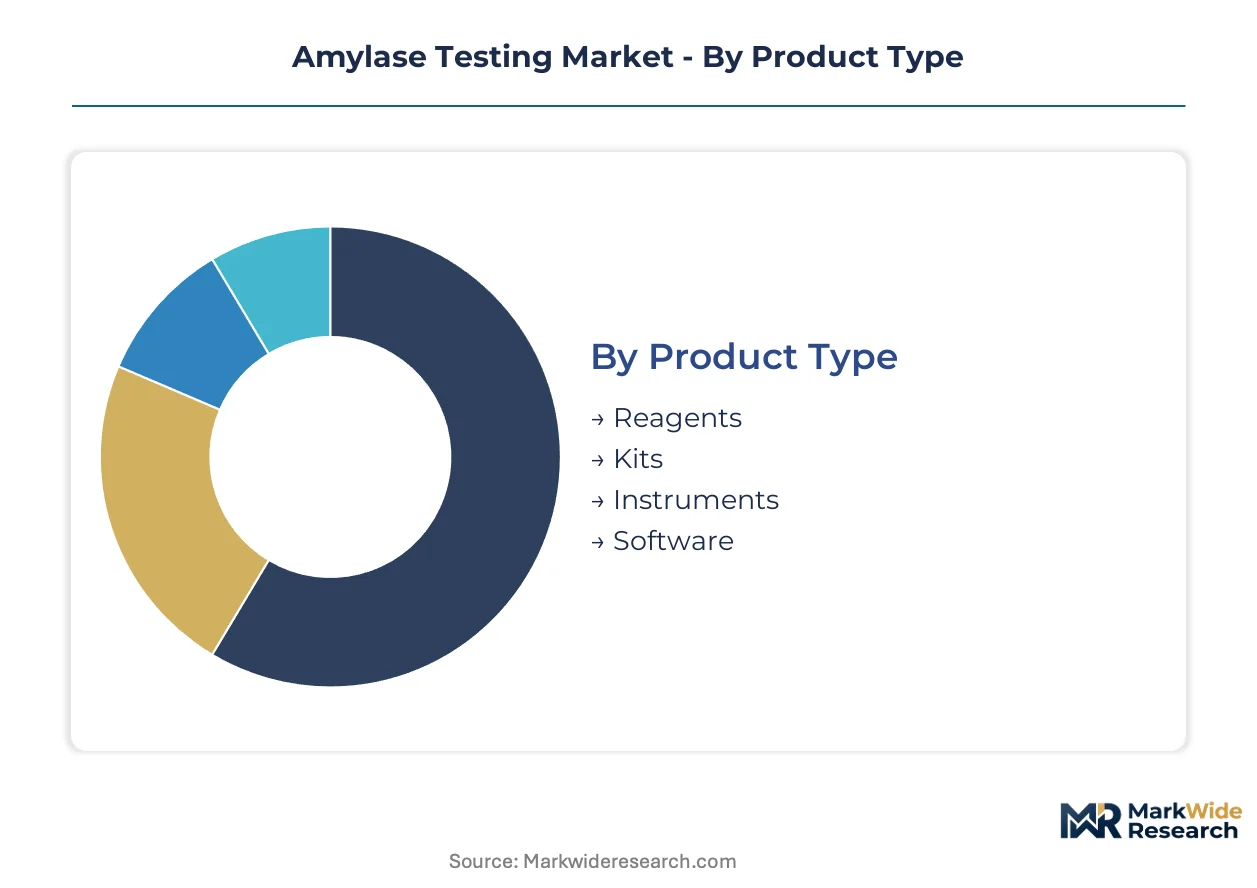
Amylase testing procurement diverges sharply across clinical settings, with hospital networks prioritizing automated throughput while point-of-care channels demand simplified workflow formats. Understanding these segment boundaries clarifies where reagent manufacturers must configure distinct pricing and service models.
Product Type:
Procurement committees weight recurring consumption against capital depreciation cycles when allocating budgets across product categories.
- Reagents:Chromogenic substrate formulations dominate hospital purchasing through defined substrate hydrolysis chemistry standardized at 37 degrees Celsius. United States hospital networks centralize high-volume contracts for these consumables under multi-year metabolic panel agreements.
- Kits:Pre-configured assay packages bundle calibrators, controls, and chromogenic substrates for CLSI-compliant enzymatic methodologies. Diagnostic laboratories in Germany and Japan adopt these formats for satellite clinic networks requiring traceable quality frameworks.
- Instruments:Automated spectrophotometry platforms serve reference laboratories seeking throughput optimization.
- Software:Laboratory information system modules integrate spectrophotometric data with predictive analytics capabilities.
Reagents lead on scale; kits lead on momentum.
End User:
Testing volume concentrates where accreditation requirements and reimbursement structures align.
- Hospitals:Emergency departments and central laboratories process acute pancreatitis panels under CLIA-mandated proficiency testing programs. Integrated delivery networks negotiate bundled contracts covering amylase testing within broader chemistry menus.
- Diagnostic Laboratories:Independent reference facilities serve outpatient and ambulatory channels with high-throughput automated platforms. China's tier-one city hospital network centralization creates demand for these centralized testing infrastructures.
- Research Institutions:Academic medical centers access characterized specimen biobanks for EU IVD-R clinical performance studies.
- Home Care:Physician office laboratories await FDA clearance for waived complexity amylase assays.
Hospitals anchor volume concentration; diagnostic laboratories are expanding most quickly.
Technology:
Substrate chemistry transitions are compressing the accuracy gap between reference methods and decentralized formats.
- Enzymatic Assays:Standardized CLSI protocols measuring alpha-amylase activity through defined substrate hydrolysis rates maintain broad instrument compatibility across chemistry analyzers. These assays retain technology leadership in accreditation-compliant reference laboratories.
- Immunoassays:Miniaturized format development enables point-of-care deployment outside centralized laboratories. Dry chemistry reagent strips integrating chromogenic indicators with solid-phase stabilization support room-temperature storage for ambulatory and emergency department channels.
- Chromatography:High-resolution separation methods serve specialized research applications requiring isoform differentiation.
- Spectrophotometry:Automated platforms occupy the premium instrumentation tier for high-throughput processing.
Enzymatic assays dominate installed base; immunoassays gain share fastest.
Application:
Clinical validation requirements and specimen source characteristics determine reagent formulation specifications.
- Clinical Diagnosis:Acute pancreatitis screening protocols drive primary demand, though lipase assays demonstrate superior specificity in emergency presentations. FDA 21 CFR 809 classification requirements and EU IVD-R performance validation standards shape reagent registration pathways for human diagnostic use.
- Veterinary Testing:Companion animal pancreatitis screening in specialty clinics requires species-validated amylase reference materials. Precision fermentation capabilities yield batch-consistent calibrators for these parallel diagnostic channels.
- Research Studies:Post-market surveillance plans with defined safety indicators support academic medical center partnerships.
- Food Industry:Industrial enzyme heritage from fermentation specialists anchors supply relationships for non-clinical applications.
Clinical diagnosis commands revenue concentration; veterinary testing shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratory networks in the United States concentrate the highest amylase testing volumes, with hospital procurement committees driving standardization across integrated delivery systems. Regulatory frameworks and reimbursement structures create divergent adoption patterns across national markets.
United States
Emergency department screening protocols and Medicare Advantage plan standardization sustain demand for high-throughput automated platforms. The FDA's 21 CFR 809 classification requirements and CLIA proficiency testing mandates shape reagent purchasing criteria. Hospital networks in the Northeast Corridor and Texas Medical Center anchor centralized testing infrastructure under multi-year metabolic panel contracts.
Germany
Reference laboratory accreditation under ISO 15189 drives adoption of chromogenic substrate formats with traceable quality frameworks. The country's national pharmaceutical regulator enforces EU IVD-R technical documentation requirements for clinical performance studies. Industrial clusters in Bavaria and North Rhine-Westphalia host satellite clinic networks deploying dry chemistry reagent strips for decentralized testing.
Japan
PMDA quality management standards and aging-related pancreatitis incidence elevate precision requirements for enzymatic assays. METI industrial policy supports biocatalyst R&D programs targeting clinical applications. The Kanto region around Tokyo concentrates diagnostic reagent manufacturing and academic medical center partnerships for post-market surveillance.
China
Hospital network centralization in tier-one cities creates demand for automated spectrophotometry platforms at scale. NMPA medical device regulations and GB standards govern in vitro diagnostic reagent registration. The Yangtze River Delta and Pearl River Delta anchor domestic reagent manufacturing clusters serving provincial laboratory networks.
India
Specialty veterinary clinics in metropolitan areas drive parallel demand for species-validated amylase formulations. CDSCO medical device rules and state-level laboratory accreditation programs shape procurement pathways. Maharashtra and Karnataka host diagnostic laboratory chains expanding pancreatitis screening protocols for companion animals.
Amylase Testing Market Competitive Environment
Strategic partnerships dominate the current landscape as reagent manufacturers seek access to characterized specimen biobanks and academic medical center networks. The vendor base concentrates around fermentation specialists with precision capabilities and diversified chemical conglomerates with diagnostic reagent divisions. Three archetypes prevail: industrial enzyme heritage players, specialized biocatalyst R&D firms, and precision fermentation specialists. Competitive moves center on supply relationship anchoring and batch-consistent reference material production.
Within the industrial enzyme heritage tier, Novozymes and DSM exemplify supply relationship anchoring with diagnostic reagent manufacturers. Amano Enzyme occupies a position among precision fermentation specialists yielding batch-consistent amylase reference materials. These three entities represent distinct strategic postures—Novozymes as a Danish industrial biotechnology corporation, DSM as a Dutch science-based company, and Amano Enzyme as a Japanese specialized enzyme producer—each sitting within differentiated capability domains rather than competing directly on identical value propositions.
| Leading Market Players |
|---|
| Novozymes |
| DSM |
| BASF |
| Amano Enzyme |
| DuPont |
| Advanced Enzyme Technologies |
| AB Enzymes |
| Suzhou Sino Enzymes |
| Shenzhen Leveking Bio-Engineering |
| Others |
Value Chain & Pricing Dynamics
Captive fermentation capacity anchors supply positioning and pricing power for chromogenic substrate manufacturers serving diagnostic reagent producers. Novozymes, DSM, and Amano Enzyme maintain backward integration into precision enzyme production, insulating their reference material pricing from spot-market volatility in industrial biocatalysts.
Pricing Analysis
Input-cost pass-through from precision fermentation operations determines reagent pricing trajectories for chromogenic substrate formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared reference materials from ISO-compliant research-grade products and unvalidated bulk formulations. Cost compression in economy-tier substrates is intensifying because Chinese domestic manufacturers are scaling fermentation capacity for export markets. Hospital procurement committees exhibit lowest price sensitivity for premium-tier materials with CLIA-mandated traceability, while research institutions drive volume in price-elastic standard-grade segments.
Supply Chain Analysis
China's NMPA domestic-content requirements for medical device registration are reshaping sourcing patterns for multinational reagent manufacturers. Supply concentrates in Denmark, the Netherlands, and Japan for precision fermentation-derived amylase reference materials, with China and India expanding capacity for chromogenic indicator chemicals. Raw material dependencies include microbial fermentation feedstocks, chromogenic substrate precursors, and stabilized enzyme formulations. Single-source vulnerability concentrates in batch-consistent human pancreatic amylase calibrators from limited fermentation specialists. Distribution runs through integrated delivery network procurement committees in the United States and hospital network centralization authorities in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amylase testing market compounds steadily as chronic pancreatitis incidence rises with aging demographics across developed economies. Recurring reagent consumption patterns generate predictable revenue streams for suppliers with anchored hospital contracts.
For Market Incumbents: Acquire characterized specimen biobank access to satisfy EU IVD-R clinical performance study requirements. Consolidate supply relationships with tier-one city hospital networks in China before NMPA localization mandates harden. Defend against lipase assay substitution by embedding amylase testing within bundled metabolic panel contracts that penalize unbundling.
For New Entrants and Emerging Players: Capture the veterinary diagnostics channel where species-validated reagent formulations face limited incumbent specialization. Target India's metropolitan specialty clinics for companion animal pancreatitis screening protocols. Establish go-to-market positioning through CDSCO-registered reagent kits for provincial laboratory networks lacking centralized procurement leverage.
For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation specialists because reference material scarcity concentrates pricing power among batch-consistent producers. The five-to-ten year viability window favors acquisition of mid-cap enzyme manufacturers with anchored diagnostic reagent supply contracts. Watch FDA CLIA waived complexity clearance decisions as the inflection signal unlocking physician office laboratory segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Batch-consistent amylase reference materials command premium positioning in CLIA-mandated proficiency testing programs. |
| EU IVD-R Clinical Performance Study Partnership | Academic medical center biobank access satisfies post-market surveillance documentation requirements for reagent registration. |
| Integrated Delivery Network Contract Consolidation | Multi-year metabolic panel agreements in Medicare Advantage-affiliated health systems lock out competing reagent suppliers. |
| Point-of-Care Immunoassay Miniaturization | Dry chemistry reagent strip formats enable emergency department deployment outside centralized laboratory infrastructure. |
| China NMPA Localization Compliance | Domestic fermentation capacity addresses hospital network centralization demand in Yangtze River Delta provincial laboratories. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market's diagnostic laboratory networks. Primary interviews with hospital procurement managers, clinical laboratory directors, regulatory affairs specialists at reagent manufacturers, and veterinary diagnostic clinic operators combined with secondary validation from FDA 510(k) filings, NMPA medical device registration databases, EU IVD-R technical documentation repositories, and hospital GPO contract disclosures. Bottom-up reagent volume estimates and top-down market sizing triangulated through cross-reference with fermentation capacity disclosures and metabolic panel reimbursement codes.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, technology format, and application setting. CAGRs derived from trend extrapolation of hospital network contract values, point-of-care device placement rates, and veterinary clinic expansion trajectories. Forecast inputs incorporated CLIA proficiency testing mandate expansion timelines and NMPA localization policy implementation phases.
Regulatory approval delays, reference material supply disruptions, and lipase assay substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about continued CLSI protocol harmonization and sustained Medicare Advantage plan standardization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Fresh Food Residue Testing Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Global Lipid Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Meat Species Identification Kits Market