
 Food Allergens and Intolerance Testing Market | 2026-2036
Food Allergens and Intolerance Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Food Allergens and Intolerance Testing Market Analysis
European contract laboratories is consolidating as larger testing networks absorb regional specialists to meet cross-border food safety mandates. Eurofins Scientific leverages its pan-European laboratory footprint to anchor allergen validation services for packaged food exporters. SGS SA competes through specialized immunoassay capabilities that differentiate its offering from generalist competitors. Bureau Veritas controls significant share of Asia-Pacific food certification workflows, extending its reach into intolerance testing for hospitality supply chains.
Food allergens and intolerance testing encompasses analytical methods that detect specific proteins, antibodies, or immune responses triggered by dietary components, employing techniques such as enzyme-linked immunosorbent assay (ELISA) with detection thresholds reaching parts per million for major allergens. These tests serve commercial food safety compliance, clinical diagnosis of immunoglobulin E-mediated reactions, and consumer-directed dietary management. Serum IgE testing dominates hospital and laboratory revenue streams due to quantitative precision and reimbursement familiarity, while at-home kits represent the fastest-expanding delivery mode as direct-to-consumer channels reduce access friction for intolerance screening. Peanut allergen detection commands premium pricing in manufacturing settings because of anaphylaxis severity and zero-tolerance regulatory thresholds in multiple jurisdictions.
The FDA enforces allergen labeling through the Food Allergen Labeling and Consumer Protection Act, compelling manufacturers to validate cleaning protocols and ingredient sourcing through documented third-party testing. EFSA's scientific opinions on threshold doses for major allergens shape EU reference doses that member state regulators transpose into binding food business operator obligations. ISO 17025 accreditation requirements from national standards bodies determine laboratory eligibility for commercial testing contracts. Stakeholders must monitor evolving regulatory recognition of component-resolved diagnostics versus whole-extract testing, as this technical distinction will determine reimbursement and competitive positioning across clinical and industrial segments.
Market Dynamics
Regulatory enforcement of zero-tolerance allergen thresholds across multiple jurisdictions is compressing testing timelines and forcing manufacturers to embed validation deeper into supply chain workflows.
Growth Catalysts
- FALCPA Mandates:The FDA's Food Allergen Labeling and Consumer Protection Act compels domestic manufacturers to document third-party verification of cleaning protocols and ingredient sourcing.
- Component-Resolved Diagnostics:Molecular allergology techniques that identify specific protein epitopes are replacing whole-extract serology in tertiary care centers.
- Direct-to-Consumer Channels:At-home IgG and IgE testing kits bypass clinical gatekeepers, expanding addressable population for intolerance screening.
Market Restraints
- Reference Material Scarcity:Certified allergen standards for method validation remain concentrated among three European metrology institutes.
- Reimbursement Friction:Component-resolved diagnostics lack consistent CPT code recognition across US private payers.
- ELISA Kit Shelf Instability:Enzyme-linked immunosorbent assay reagents degrade under temperature excursion, constraining distribution to cold-chain-capable logistics networks.
Strategic Opportunities
- Asia-Pacific Hospitality Certification:Hotel chains in Thailand and Vietnam are adopting intolerance testing protocols to capture inbound dietary-restricted tourism.
- ISO 17025 Convergence:Accreditation harmonization between EU notified bodies and Gulf Cooperation Council regulators opens unified testing protocols for exporters.
- Mass Spectrometry Integration:LC-MS/MS platforms that detect multiple allergen markers simultaneously are displacing single-analyte immunoassays in high-throughput laboratories.
Industry Challenges
- Cross-Reactivity Interpretation:Clinicians lack standardized decision support tools for distinguishing co-sensitization from genuine clinical allergy in polysensitized patients.
- Laboratory Information System Interoperability:Proprietary data formats from competing instrument manufacturers obstruct seamless integration with hospital electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Allergens and Intolerance Testing Market |
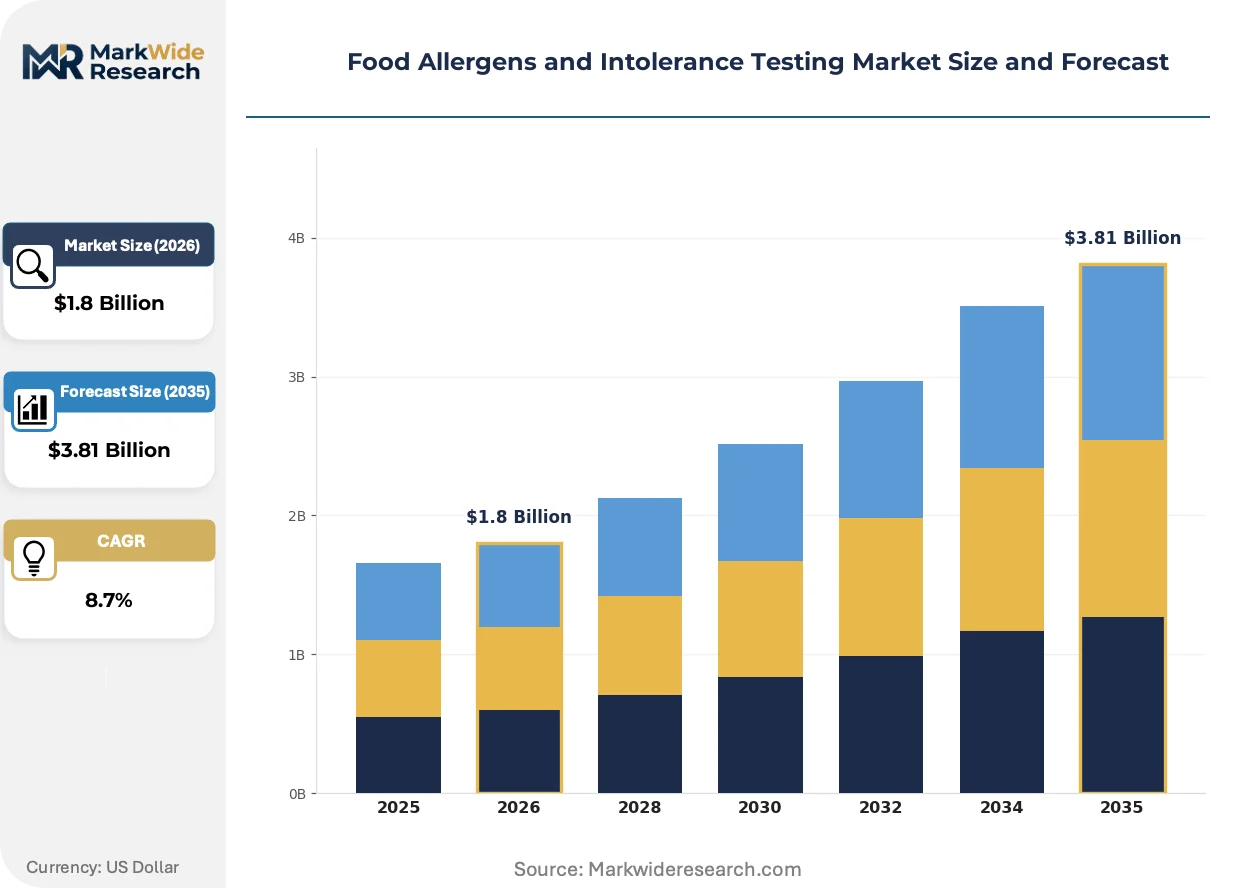
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Skin Prick Test, Serum IgE Test, Elimination Diet, Patch Test Allergen Type: Peanuts, Shellfish, Milk, Gluten End User: Hospitals, Laboratories, Home Care, Clinics Delivery Mode: Lab-based Testing, At-Home Kits, Mobile Testing, In-Hospital Testing |
| Companies Covered | SGS SA, Eurofins Scientific, Intertek Group plc, Bureau Veritas, NEOGEN Corporation, Mérieux NutriSciences, Agilent Technologies, ALS Limited, Microbac Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Allergens and Intolerance Testing Market Emerging Trajectories
Multiplex protein detection platforms are compressing analytical workflows while regulatory recognition of threshold-based risk assessment is reshaping compliance economics across food manufacturing.
Biosensor arrays employing surface plasmon resonance are absorbing routine allergen screening volume from centralized laboratories. Mid-sized food manufacturers in the Netherlands and Belgium are adopting these platforms for in-house verification. The technology is absorbing tasks previously outsourced to third-party ISO 17025 laboratories, compressing contract testing revenue in the premium manufacturing segment.
EFSA's scientific opinions on reference doses for major allergens are transposing into binding obligations for EU food business operators. Member state regulators are now enforcing quantitative risk assessment rather than presence-absence detection. Packaged food exporters to Germany and France must demonstrate compliance with these threshold-based frameworks, accelerating investment in quantitative analytical methods.
Hospital procurement departments are unbundling serology testing from bundled laboratory service contracts. Standalone allergen-specific IgE panels are migrating to direct purchasing agreements with specialized reference laboratories. This pattern is most visible in US metropolitan health systems where laboratory benefit management programs are extracting molecular diagnostics from legacy outreach arrangements.
Food Allergens and Intolerance Testing Market Segmentation
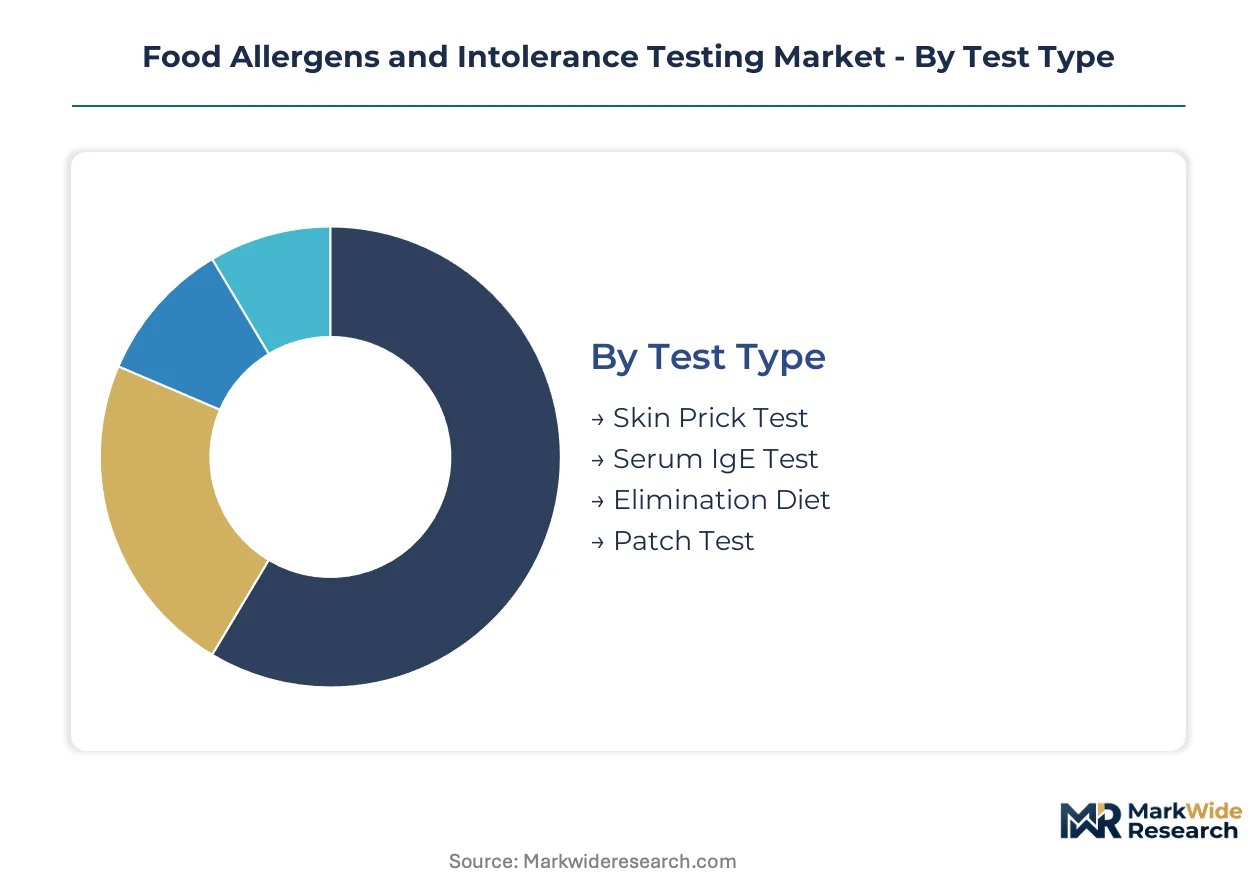
Testing modality and delivery channel choices determine reimbursement pathways, regulatory compliance burdens, and margin structures across the food allergen diagnostics value chain. Segment concentration reflects divergent clinical utility, manufacturing throughput requirements, and direct-to-consumer accessibility.
Test Type:
Supply concentration in serology platforms has concentrated manufacturing capacity among specialized immunoassay producers with cold-chain distribution networks.
- Serum IgE Test:Quantitative immunoassay platforms detect allergen-specific antibodies in venous blood samples with standardized calibration traceable to WHO reference preparations. Hospital laboratories in the United States and Germany absorb the majority of installed systems due to CPT code familiarity and EMA diagnostic guideline alignment. Component-resolved diagnostics are displacing whole-extract methods in tertiary referral centers.
- Skin Prick Test:Percutaneous allergen introduction with wheal measurement remains the first-line diagnostic in pediatric allergy clinics. Demand concentrates in France and Italy where national health systems reimburse office-based provocation testing.
- Elimination Diet:Supervised dietary exclusion protocols with symptom monitoring require specialized dietitian involvement.
- Patch Test:Delayed hypersensitivity assessment for contact dermatitis variants linked to food proteins.
Serum IgE testing absorbs the bulk of installed capacity; elimination diet protocols are expanding most quickly among functional medicine practices.
Allergen Type:
Cost tier differentiation separates premium-priced anaphylaxis-risk analytes from commodity intolerance markers with lower regulatory stringency.
- Peanuts:Arachis hypogaea protein detection commands manufacturing premium due to zero-tolerance thresholds in FDA and EFSA enforcement regimes. Food processors in the United States and United Kingdom validate cleaning protocols with parts-per-million sensitivity requirements. Anaphylaxis severity drives litigation exposure and insurance-driven testing frequency.
- Gluten:Gliadin and glutenin peptide quantification serves both celiac disease diagnosis and gluten-free manufacturing certification. Italian and Spanish diagnostic networks maintain high throughput for HLA-DQ2/DQ8 genotyping correlation.
- Milk:Casein and whey protein differentiation supports pediatric allergy management.
- Shellfish:Tropomyosin detection for crustacean and mollusk sensitivity assessment.
Peanut allergen testing commands the highest unit economics; gluten diagnostics show the steepest expansion trajectory in food manufacturing verification.
End User:
Volume concentration in hospital procurement has fragmented as laboratory benefit management programs unbundle specialized serology from legacy service contracts.
- Laboratories:ISO 17025-accredited reference facilities and hospital-based clinical laboratories process high-throughput IgE panels with automated immunoassay platforms. Eurofins and SGS networks in Europe absorb significant commercial food safety volume. Mass spectrometry integration is displacing single-analyte workflows.
- Hospitals:Inpatient and emergency department testing for acute allergic reactions with rapid turnaround requirements. United States metropolitan health systems drive direct purchasing agreement migration.
- Home Care:Direct-to-consumer IgG and IgE kits bypass clinical gatekeepers.
- Clinics:Outpatient allergy specialist practices with point-of-care capabilities.
Laboratories retain the dominant share of commercial testing volume; home care channels are gaining share fastest through e-commerce distribution.
Delivery Mode:
Customer type stratification separates institutional procurement with compliance documentation from consumer-directed screening with limited clinical interpretation.
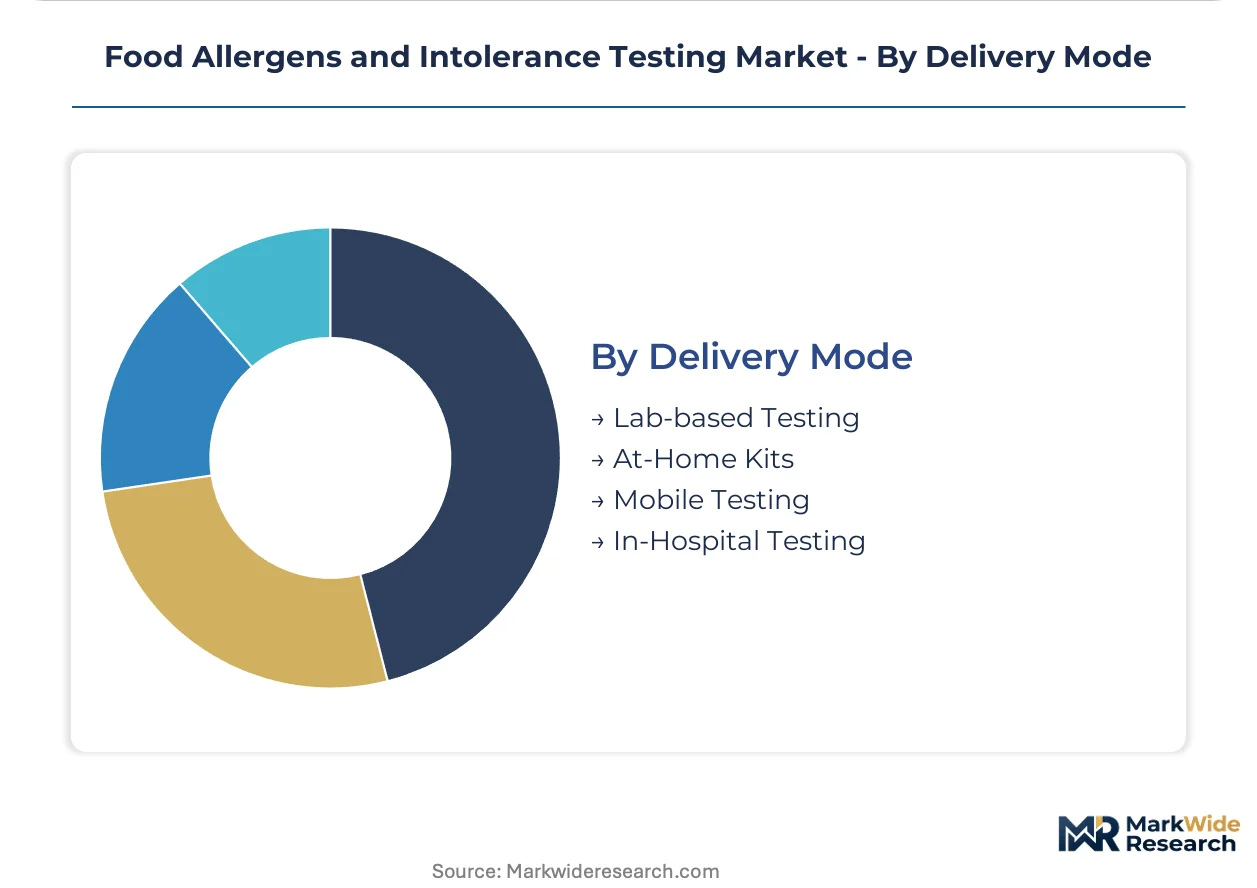
- Lab-based Testing:Centralized analytical services with chain-of-custody documentation for regulatory submission and legal defensibility. Cold-chain logistics and accredited method validation constrain viable providers. EFSA threshold-based risk assessment mandates quantitative capabilities.
- At-Home Kits:Finger-prick blood collection with mail-back analysis or rapid lateral flow devices. Direct-to-consumer channels in the United States and United Kingdom reduce access friction for intolerance screening.
- In-Hospital Testing:Emergency and perioperative allergy assessment with immediate result requirements.
- Mobile Testing:Workplace and community screening events with portable equipment.
Lab-based testing maintains the largest revenue base; at-home kits are climbing the fastest as consumer health autonomy expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic reagent manufacturing clusters in Massachusetts and California supply analytical platforms to testing laboratories worldwide. Celiac disease screening demand in Minnesota and peanut allergy prevalence in Georgia drive clinical test utilization patterns. Regulatory enforcement divergence between FDA zero-tolerance thresholds and EFSA quantitative risk frameworks shapes regional service requirements.
United States
FDA enforcement of FALCPA mandates compels domestic food manufacturers to document third-party verification protocols. Peanut allergen detection commands premium pricing due to litigation exposure and zero-tolerance thresholds. The Minneapolis-St. Paul metropolitan area hosts reference laboratories processing high-throughput IgE panels for Midwest health systems.
Germany
EFSA threshold-based risk assessment frameworks are transposing into binding obligations for food business operators. Member state regulators now enforce quantitative compliance rather than presence-absence detection. The Rhine-Ruhr industrial corridor concentrates ISO 17025-accredited facilities serving packaged food exporters to France and Benelux markets.
United Kingdom
Direct-to-consumer IgG and IgE testing kits bypass clinical gatekeepers through e-commerce channels. The Medicines and Healthcare products Regulatory Agency oversees in vitro diagnostic compliance for mail-back analysis services. Greater London hosts specialized reference laboratories unbundling serology from legacy hospital outreach contracts.
Japan
PMDA recognition of component-resolved diagnostics is displacing whole-extract serology in tertiary referral centers. Wheat allergy prevalence drives demand for quantitative allergen-specific IgE testing. The Kanto region around Tokyo concentrates hospital procurement departments adopting standalone molecular diagnostic panels.
Australia
TGA oversight of in vitro diagnostic devices determines market entry pathways for imported testing platforms. Shellfish tropomyosin detection supports coastal population allergy management requirements. Sydney and Melbourne metropolitan health systems drive direct purchasing agreement migration for specialized reference laboratory services.
Food Allergens and Intolerance Testing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue point-of-care biosensor miniaturization and direct-to-consumer channel expansion. The vendor base stratifies across three tiers: pan-regional laboratory networks with ISO 17025 accreditation, specialized immunoassay producers with cold-chain distribution capabilities, and at-home kit assemblers leveraging e-commerce fulfillment. Dominant competitive moves include laboratory network consolidation to capture cross-border food safety mandates and mass spectrometry platform integration to displace single-analyte workflows.
Within the pan-regional laboratory network tier, SGS SA, Eurofins Scientific, and Bureau Veritas represent archetypal positioning. SGS SA exemplifies specialized immunoassay differentiation from generalist competitors. Eurofins Scientific occupies a position leveraging pan-European laboratory footprint for allergen validation services. Bureau Veritas anchors Asia-Pacific food certification workflow concentration extending into hospitality supply chain intolerance testing.
| Leading Market Players |
|---|
| SGS SA |
| Eurofins Scientific |
| Intertek Group plc |
| Bureau Veritas |
| NEOGEN Corporation |
| Mérieux NutriSciences |
| Agilent Technologies |
| ALS Limited |
| Microbac Laboratories |
| Others |
Supply Flow & Price Mechanics
FDA zero-tolerance allergen thresholds and EFSA quantitative risk frameworks are forcing food manufacturers to unbundle validation services from bundled procurement contracts, compelling testing providers to absorb cold-chain logistics costs and recalibrate pricing tiers around certification speed rather than volume discounts.
Pricing Analysis
Warranty and calibration bundling separates ISO 17025-accredited reference laboratories from commodity kit assemblers in contract structures. Three-tier pricing stratifies across emergency turnaround, standard batch validation, and economy screening tiers with certification grade and geographic delivery cost as primary differentiation levers. Cost compression in the economy tier is intensifying as at-home kit producers bypass clinical gatekeepers and erode hospital laboratory margins. Food manufacturers show highest price sensitivity for routine batch testing, while litigation-exposed peanut allergen validation commands premium insensitivity.
Supply Chain Analysis
Workforce availability constraints in Massachusetts and California diagnostic reagent manufacturing clusters are tightening specialized immunoassay production capacity. Supply concentrates in Germany and the United Kingdom for ELISA platform assembly, with critical inputs including WHO-traceable reference sera, stabilized enzyme conjugates, and surface plasmon resonance sensor chips. Single-source vulnerability runs through European metrology institutes for certified allergen standards. Distribution runs through cold-chain-capable logistics networks with chain-of-custody documentation for regulatory submission.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food allergen testing market sits in a technology-transition phase as mass spectrometry platforms displace single-analyte immunoassays in high-throughput laboratories, reshaping competitive economics for incumbent and emerging players alike.
For Market Incumbents: Cement accreditation moats through ISO 17025 convergence investments across EU notified bodies and Gulf Cooperation Council regulators to capture cross-border exporter demand. Deepen backward integration into stabilized reagent manufacturing in Massachusetts and California clusters to defend margin position against biosensor miniaturization threats from point-of-care entrants. For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels in the United Kingdom and United States offer the most penetrable white-space for intolerance screening kits bypassing clinical gatekeepers. Target hospitality supply chain certification in Thailand and Vietnam where hotel chains are adopting intolerance protocols for dietary-restricted tourism. Pursue rapid lateral flow device development with mail-back analysis services as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors specialized immunoassay producers with cold-chain distribution capabilities and pan-regional laboratory networks. Long-term viability hinges on mass spectrometry platform integration and component-resolved diagnostics reimbursement recognition. Watch for CPT code adoption signals for molecular allergology techniques as the inflection indicator for tertiary care center procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Platform Integration | LC-MS/MS multi-marker detection displaces single-analyte ELISA workflows in high-throughput laboratories. |
| ISO 17025 Accreditation Convergence | Harmonization between EU notified bodies and GCC regulators opens unified testing protocols for exporters. |
| Direct-to-Consumer Channel Expansion | E-commerce distribution of at-home IgG and IgE kits bypasses clinical gatekeepers in United States and United Kingdom markets. |
| Component-Resolved Diagnostics Investment | Molecular allergology techniques replace whole-extract serology in tertiary referral centers with PMDA and FDA recognition. |
| Asia-Pacific Hospitality Certification | Hotel chains in Thailand and Vietnam adopt intolerance testing protocols to capture inbound dietary-restricted tourism. |
Methodological Framework
Document review covered FDA enforcement records, EFSA scientific opinions, ISO 17025 accreditation databases, and hospital procurement contracts, complemented by interviews with diagnostic laboratory directors, food safety compliance officers, and regulatory affairs specialists at notified bodies. Secondary validation drew from customs trade data for reagent imports, SEC filings for publicly listed testing networks, and CMS reimbursement code databases. Bottom-up and top-down triangulation reconciled instrument installation counts with service revenue estimates across the analysis window.
Segment-level outputs for test type, allergen type, end user, and delivery mode were generated through elasticity modeling of procurement pattern shifts and technology substitution rates. CAGRs were derived from instrument replacement cycles, regulatory mandate implementation timelines, and direct-to-consumer channel penetration curves. Forecast inputs included EFSA threshold adoption trajectories in EU member states and PMDA component-resolved diagnostics recognition patterns in Japanese tertiary centers.
The model holds under steady regulatory enforcement intensity and stable cold-chain logistics capacity; deviation in reimbursement code recognition for molecular diagnostics or temperature excursion events in enzyme reagent distribution would shift volume projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Genetically Modified Food Safety Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Global Dairy Testing Market