
 Food Traceability Market | 2026-2036
Food Traceability Market Size, Share, and Industry Trends Forecast 2026-2036
Food Traceability Market Intelligence
ISO 22000 certification is collapsing the supplier base as smaller traceability vendors fail to meet integrated food safety management requirements. IBM Corporation leverages its blockchain infrastructure to anchor enterprise-grade provenance platforms for multinational food brands. SGS SA competes through its global inspection and audit network, sustaining credibility across third-party verification workflows. Honeywell International Inc. dominates industrial automation layers, extending sensor-to-cloud architectures that capture lot-level data across cold chains.
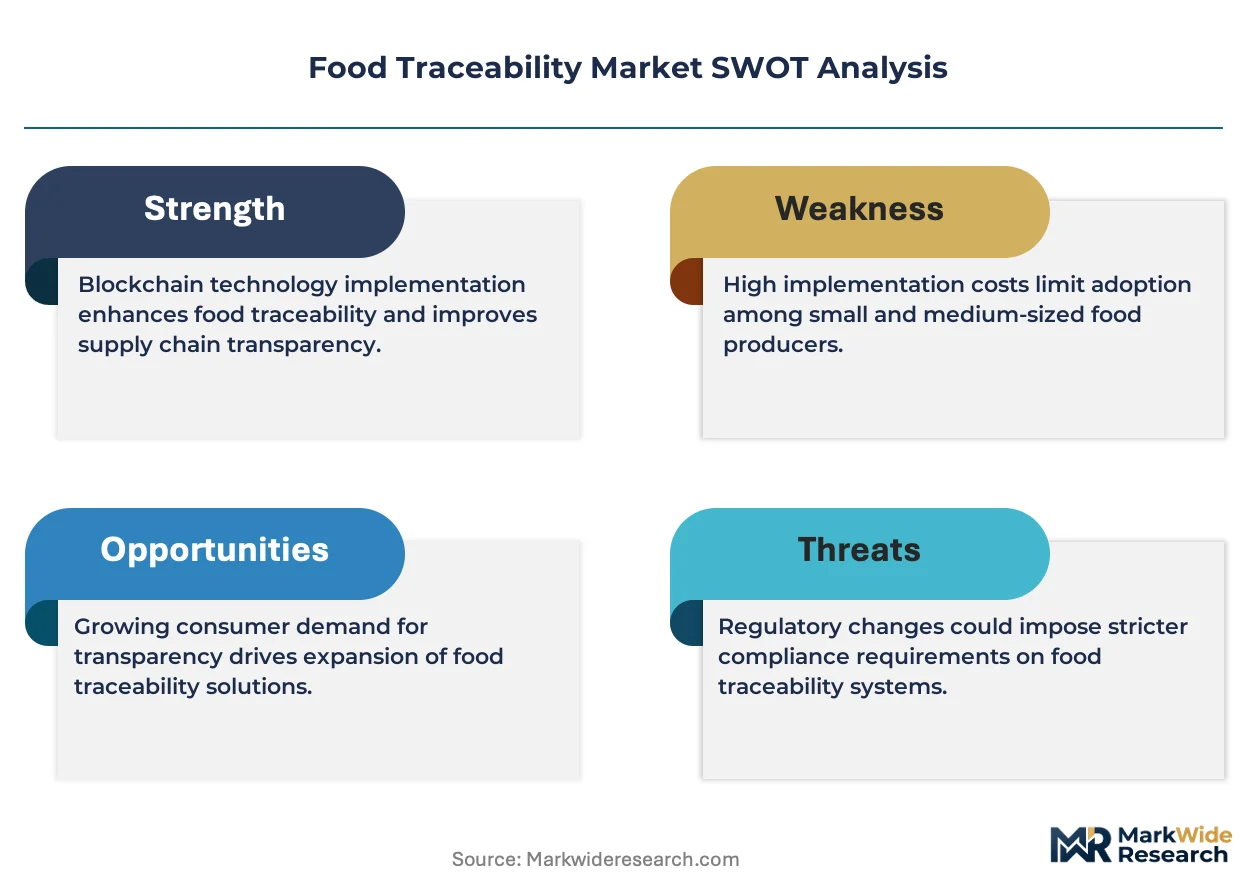
Food traceability encompasses the systematic recording, tracking, and verification of product movement, transformation, and origin across supply chain nodes using encoded identifiers, distributed ledgers, and environmental sensors. Its primary commercial purpose is to enable rapid contamination containment, authenticate label claims, and satisfy downstream liability requirements. Blockchain deployments command premium investment as immutable ledgers resolve multi-party trust gaps in fragmented supply networks. RFID and IoT integration within the technology segment is accelerating fastest where real-time temperature and location telemetry prevent spoilage losses. Cloud deployment models are capturing margin pools by reducing upfront capital barriers for mid-sized processors and regional distributors.
The FDA's Food Safety Modernization Act traceability rule mandates granular record-keeping for high-risk foods, compelling technology upgrades across US-based supply chains. EFSA's coordinated risk assessment protocols and REACH-aligned chemical residue tracking in Europe are converging with national enforcement by France's ANSES and Germany's BfR to standardize cross-border data formats. Stakeholders must decide whether to build compliant data architectures in-house or subscribe to interoperable platforms before regulatory deadlines harden competitive barriers.
Market Dynamics
Blockchain infrastructure is fragmenting competitive positioning across food traceability by collapsing multi-party trust costs that previously locked buyers into vertically integrated platforms. Smaller processors now access enterprise-grade provenance verification without captive IT investments.
Growth Catalysts
- FDA Food Safety Modernization Act:The traceability rule mandates granular lot-level record-keeping for high-risk foods, compelling technology upgrades across US-based supply chains and expanding addressable market for verification software.
- Meat processors in Germany:National enforcement under BfR documentation requirements is accelerating demand for integrated cold-chain sensors and encoded identifier systems ahead of EU-wide standardization.
- RFID-IoT convergence:Real-time temperature and location telemetry prevents spoilage losses in perishable distribution, justifying hardware investment through quantified waste reduction.
Market Restraints
- ISO 22000 certification costs:Integrated food safety management requirements are collapsing the supplier base as smaller traceability vendors fail to absorb compliance expenditure.
- Cloud subscription dependency:Mid-sized processors face recurring operational expenditure pressure that compresses margin recovery from traceability premiums.
- Legacy ERP incompatibility:Proprietary data formats in incumbent manufacturing execution systems create friction for API-based traceability module deployment.
Strategic Opportunities
- EU Farm to Fork Strategy:The European Green Deal mandate for stricter origin documentation across member states creates regulatory tailwind for provenance platform providers before 2030 enforcement deadlines.
- France's ANSES protocols:Coordinated risk assessment alignment with EFSA is standardizing cross-border data formats, enabling interoperable platform subscription models.
- Sensor-to-cloud architectures:Honeywell's industrial automation layer extension captures lot-level data across cold chains, opening hardware-software bundling in dairy and seafood verticals.
Industry Challenges
- Blockchain talent scarcity:Distributed ledger architecture expertise concentrates in financial technology, forcing food traceability vendors to compete for implementation specialists.
- Multi-party data governance:Competing commercial interests across suppliers, processors, and retailers delay consensus on shared ledger access protocols and liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Traceability Market |
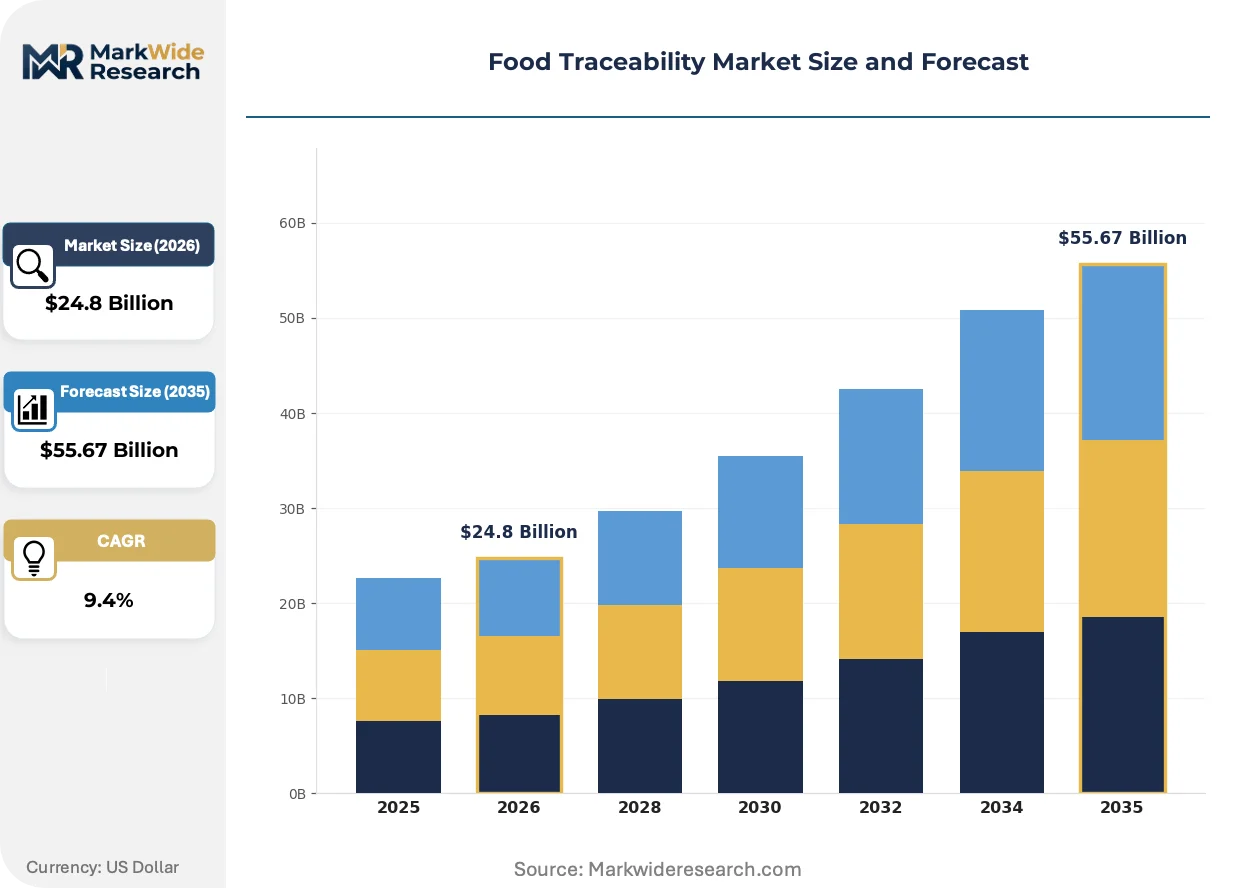
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $55.67 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, QR Codes, RFID, IoT Application: Meat, Dairy, Produce, Packaged Foods End User: Retailers, Manufacturers, Distributors, Food Service Deployment: Cloud, On-Premises, Hybrid, Others |
| Companies Covered | C.H. Robinson, IBM Corporation, SGS SA, Thermo Fisher Scientific, Optel Group, Honeywell International Inc., Cognex Corporation, FoodLogiQ, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Traceability Market Strategic Shifts & Innovations
Distributed ledger architectures are fragmenting established platform economics by enabling permissionless verification networks that bypass centralized intermediary control. This structural shift compresses switching costs and accelerates vendor rotation.
Blockchain is fragmenting competitive positioning in enterprise provenance by collapsing the trust premiums that previously sustained vertically integrated platform providers. Multinational food brands adopt immutable ledger infrastructure at accelerating pace to resolve multi-party verification gaps. The technology is fragmenting market concentration by enabling mid-sized processors to access equivalent documentation credibility without proprietary system investment.
REACH-aligned chemical residue tracking converges with EFSA coordinated risk assessment protocols to standardize cross-border data formats across Europe. France's ANSES and Germany's BfR national enforcement is hardening compliance timelines for origin documentation. Meat processors in Germany face the most acute adjustment pressure as they reconfigure supplier audit workflows ahead of mandatory integration deadlines.
Buyer procurement patterns are compressing toward subscription-based platform access that eliminates upfront capital barriers for regional distributors. Cloud deployment models displace on-premise infrastructure investment in mid-tier processing operations. This shift is most visible in North American grocery retail, where blockchain-based provenance tracking expands to meet consumer transparency expectations without captive IT development.
Food Traceability Market Segmentation
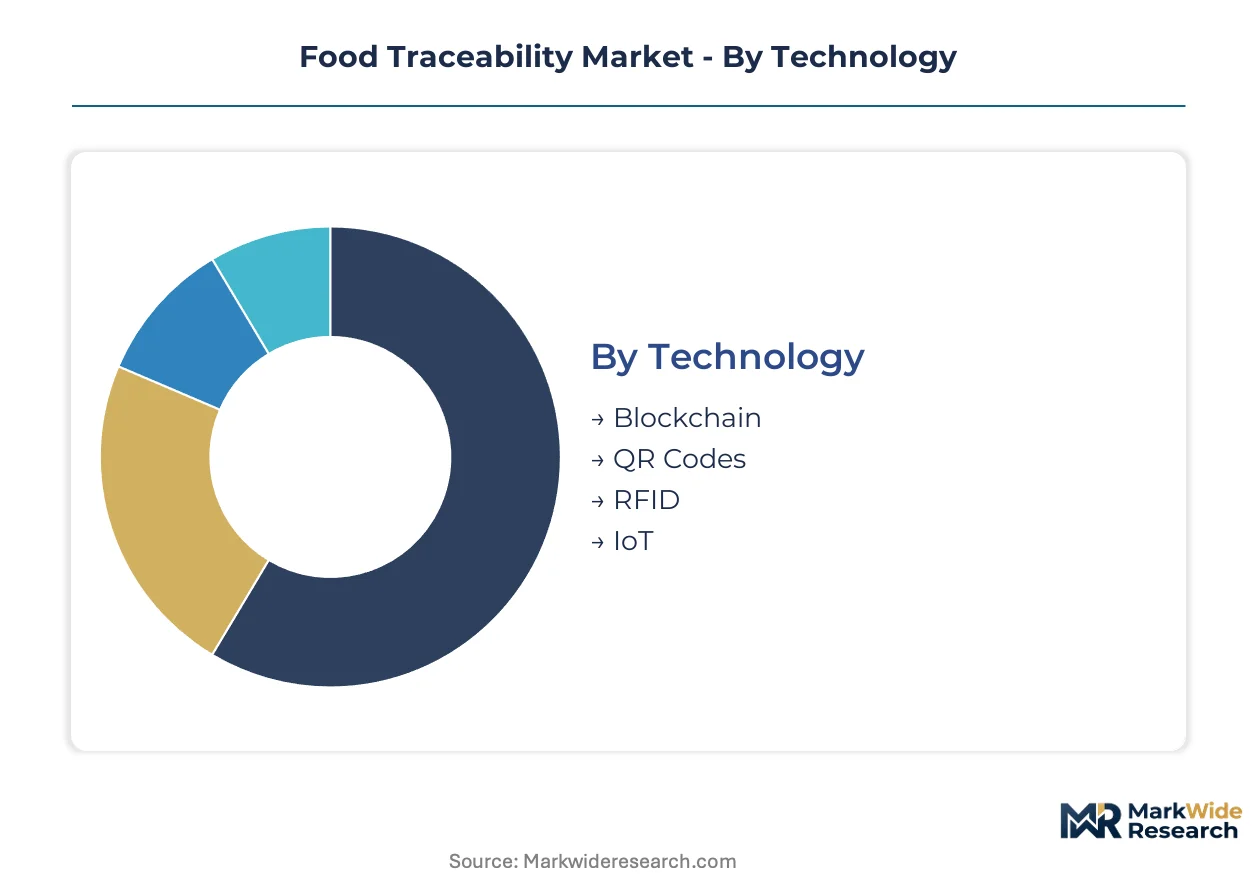
Segmentation in food traceability determines technology procurement patterns, regulatory compliance pathways, and margin capture potential across supply chain tiers. Distinct deployment models and end-user requirements create divergent vendor strategies within each category.
Technology:
Geographic demand concentration varies sharply by technology maturity, with blockchain and IoT solutions export-led while QR codes and basic RFID remain domestically oriented.
- Blockchain:Distributed ledger architectures enable immutable multi-party verification without centralized intermediary control. Demand concentrates among multinational food brands in Germany and the US seeking to resolve cross-border trust gaps ahead of EU Farm to Fork deadlines.
- IoT:Sensor networks capture real-time temperature, humidity, and location telemetry across cold chains. Adoption accelerates in North American grocery retail and German meat processing where spoilage losses justify hardware investment through quantified waste reduction.
- RFID:Encoded identifier systems automate lot-level tracking through radio-frequency interrogation. Deployment clusters in US-based supply chains responding to FDA Food Safety Modernization Act record-keeping mandates.
- QR Codes:Two-dimensional matrix barcodes provide low-cost consumer-facing provenance access. Uptake dominates domestic markets where transparency premiums support simple smartphone-based verification.
Blockchain holds the largest share; momentum sits with IoT as sensor-to-cloud architectures gain traction fastest.
Application:
Cost tier differentiation separates premium perishable categories from commoditized packaged segments, with compliance expenditure absorbed differently across margin structures.
- Meat:Species verification and cold-chain integrity dominate functional requirements. German processors under BfR enforcement face acute pressure to reconfigure supplier audit workflows with encoded identifier integration.
- Dairy:Temperature-sensitive distribution demands real-time environmental monitoring. Demand clusters in France where ANSES protocols align with EFSA standardization timelines.
- Produce:Fresh fruit and vegetable traceability focuses on origin authentication and pesticide residue documentation. Cloud deployment models reduce capital barriers for regional distributors in this fragmented supplier base.
- Packaged Foods:Shelf-stable categories prioritize label claim verification and recall efficiency. Subscription-based platform access displaces on-premise investment among mid-tier manufacturers.
Meat commands the highest compliance expenditure; packaged foods represent the steepest expansion trajectory as regulatory scope broadens.
End User:
Customer type determines data architecture requirements, with retailers driving interoperability standards while manufacturers absorb integration complexity.
- Retailers:Grocery chains mandate supplier data format compliance to enable shelf-level provenance display. North American expansion of blockchain tracking responds to consumer transparency expectations without captive IT development.
- Manufacturers:Processors bridge upstream supplier documentation with downstream retailer requirements. Legacy ERP incompatibility creates friction for API-based traceability module deployment in this segment.
- Distributors:Logistics intermediaries require lot-level visibility without ownership of production data. Hybrid deployment models balance control with capital efficiency for mid-sized operators.
- Food Service:Restaurants and institutional caterers prioritize rapid contamination containment over origin storytelling. Cloud subscriptions reduce upfront barriers for fragmented regional operators.
Retailers anchor demand volume; food service is expanding most quickly as regulatory enforcement reaches prepared meal categories.
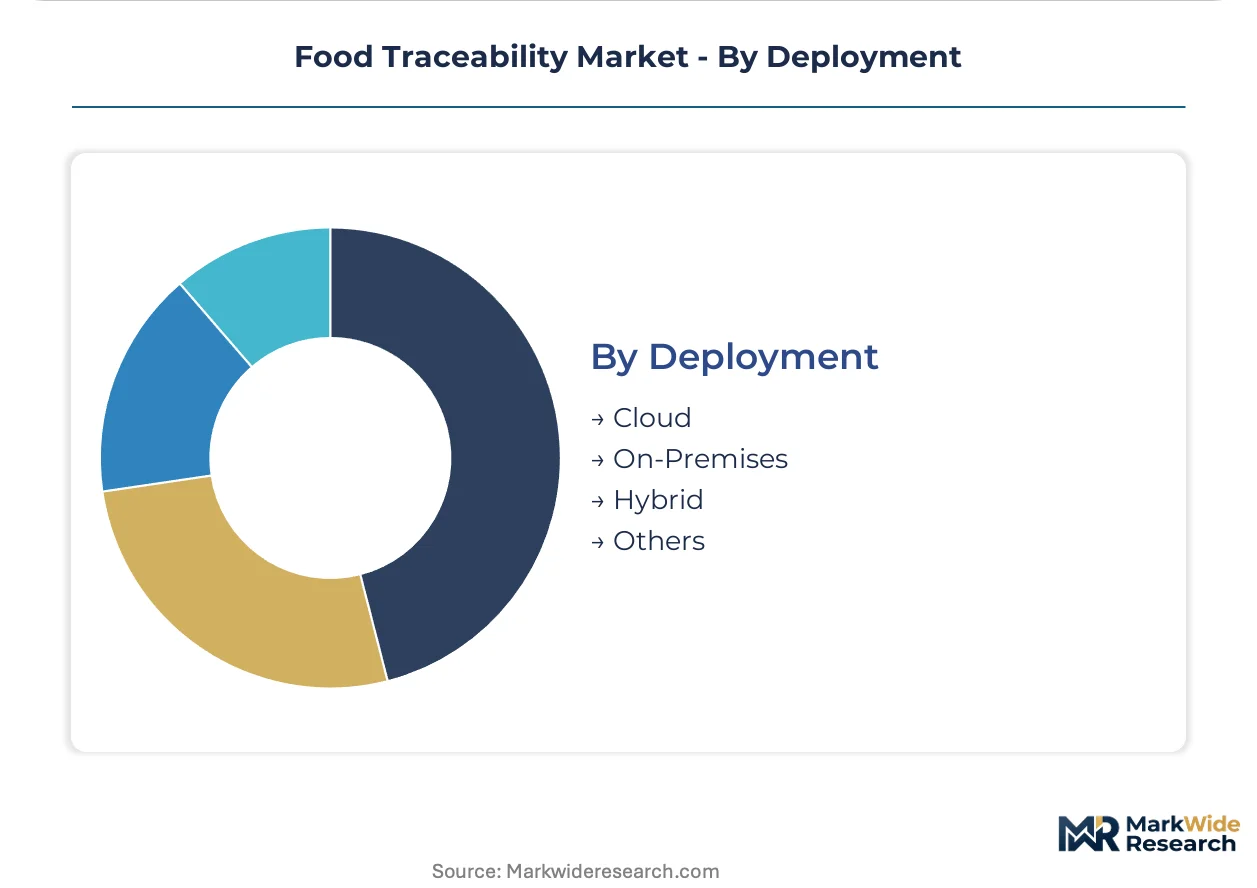
Deployment:
Supply concentration in cloud infrastructure providers is compressing margin recovery for mid-sized processors facing recurring operational expenditure pressure.
- Cloud:Subscription-based platform access eliminates upfront capital barriers and accelerates deployment timelines. Mid-sized processors across all geographies favor this model despite long-term cost accumulation.
- On-Premises:Captive infrastructure investment persists among large multinationals with legacy security requirements and dedicated IT resources.
- Hybrid:Mixed architectures segment sensitive production data on-site while leveraging cloud analytics for downstream sharing. This configuration appeals to German meat processors balancing BfR documentation mandates with supplier confidentiality concerns.
- Others:Edge computing and private blockchain networks serve specialized requirements in remote processing facilities with intermittent connectivity.
Cloud deployment holds dominant share; hybrid configurations are gaining share fastest as data governance complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers cluster in jurisdictions with stringent documentation mandates. Regulatory enforcement intensity varies sharply across national food safety regimes, shaping technology procurement patterns and platform deployment timelines.
United States
Multinational food brands and grocery retailers drive demand for blockchain-based provenance verification. The FDA Food Safety Modernization Act traceability rule compels granular lot-level record-keeping for high-risk foods. Chicago and Minneapolis-St. Paul anchor cold-chain technology adoption as meat processors reconfigure supplier audit workflows.
Germany
Meat processors face acute pressure from BfR documentation requirements tightening national food safety enforcement. The EU Farm to Fork Strategy mandates stricter origin documentation across member states ahead of 2030 deadlines. Bavaria and Lower Saxony concentrate sensor-to-cloud architecture deployment in dairy and livestock processing corridors.
France
ANSES coordinated risk assessment protocols align with EFSA standardization timelines, accelerating cloud platform subscriptions. The European Green Deal enforcement hardens compliance timelines for origin documentation in prepared meal categories. The Île-de-France region anchors demand for interoperable data format solutions linking upstream suppliers with retail chains.
China
Domestic food safety scandals propel blockchain adoption among premium protein importers and e-commerce platforms. SAMR enforcement of traceability requirements intensifies for imported cold-chain products. Yangtze River Delta processing clusters deploy IoT sensor networks to capture real-time temperature telemetry across seafood distribution.
Canada
Health Canada alignment with FDA documentation standards creates cross-border platform interoperability requirements. CFIA enforcement of Safe Food for Canadians Regulations drives encoded identifier adoption in beef and pork export channels. Ontario and Alberta meat processing corridors integrate RFID systems to satisfy US retailer data format mandates.
Food Traceability Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive automation and inspection capabilities. Market structure exhibits moderate concentration at the infrastructure layer, with fragmentation persisting in specialized software modules. Two strategic archetypes dominate: integrated hardware-software bundlers leveraging sensor-to-cloud architectures, and audit-network operators sustaining credibility through third-party verification workflows. Competitive moves center on strategic partnerships with retail chains and technology licensing to mid-tier processors.
Within the industrial automation tier, Honeywell International Inc. and Cognex Corporation exemplify hardware-anchored positioning. IBM Corporation occupies a distinct position as a blockchain infrastructure provider. SGS SA represents the third-party verification archetype through its global inspection network. Zebra Technologies and C.H. Robinson sit within logistics-technology convergence, bridging transportation management with lot-level visibility. These five entities collectively span the functional requirements of enterprise food traceability procurement.
| Leading Market Players |
|---|
| C.H. Robinson |
| IBM Corporation |
| SGS SA |
| Thermo Fisher Scientific |
| Optel Group |
| Honeywell International Inc. |
| Cognex Corporation |
| FoodLogiQ |
| Zebra Technologies |
| Others |
Cost & Logistics Intelligence
Cloud subscription models displacing on-premise infrastructure simultaneously redistribute supply geography toward hyperscaler hubs and compress margin recovery for mid-sized processors facing recurring operational expenditure pressure.
Pricing Analysis
Cost-plus contracts with cloud infrastructure indexation dominate mid-tier processor procurement, embedding hyperscaler pricing volatility into traceability platform operating costs. Three-tier pricing structure across enterprise-grade, professional, and basic subscription levels differentiates by API call volume and data retention depth. Pricing pressure stems from ISO 22000 certification expenditure collapsing the vendor base and concentrating buyer leverage among surviving integrators. Regional distributors exhibit highest price sensitivity due to thin margin structures, while multinational brands absorb premium tiers for audit-network credibility.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for RFID tags and IoT sensor chipsets feeding traceability hardware production. German and US-based automation specialists draw from Taiwanese wafer supply and Chinese rare earth processing for magnetic components in encoded identifier systems. Single-source vulnerability concentrates in advanced sensor MEMS fabrication, where foundry capacity constraints ripple through cold-chain hardware lead times. Distribution runs through third-party logistics integrators bundling transportation management with lot-level visibility software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs formidable defensive moats as compliance deadlines harden data architecture requirements and elevate switching costs for incumbent platform subscribers.
For Market Incumbents: Secure audit-network accreditation ahead of EU Farm to Fork enforcement timelines to preempt competitor certification gaps. Deepen backward integration into sensor hardware production to capture margin pools escaping to industrial automation vendors, while defending against cloud-native entrants through hybrid deployment pre-configuration. For New Entrants and Emerging Players: API interoperability gaps in legacy ERP systems present immediate white-space opportunity for middleware specialists bridging manufacturing execution with traceability modules. Food service verticals remain under-penetrated relative to retail and manufacturing, offering lower competitive intensity for subscription-based contamination containment solutions pitched through distributor channel partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated automation-hardware providers with captive sensor-to-cloud architectures, as these entities capture margin across multiple technology layers. The inflection signal to monitor is BfR enforcement acceleration triggering mandatory integration deadlines and compressing procurement timelines for German meat processors.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Infrastructure Partnership | Resolves multi-party trust gaps for multinational brands ahead of EU Farm to Fork deadlines. |
| Sensor-to-Cloud Architecture Extension | Captures lot-level cold-chain data across dairy and seafood verticals for Honeywell-positioned vendors. |
| Third-Party Audit Network Expansion | SGS SA leverages global inspection presence to sustain credibility across verification workflows. |
| Hybrid Deployment Pre-Configuration | Balances BfR documentation mandates with supplier confidentiality for German meat processors. |
| API Interoperability Module Development | Bridges legacy ERP friction points delaying traceability adoption among mid-tier manufacturers. |
Research Approach
A standing panel of food safety compliance officers, cold-chain operations directors, grocery retail procurement leads, and blockchain platform engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA Food Safety Modernization Act filings, EFSA coordinated risk assessment protocols, EU Farm to Fork Strategy documentation, and customs records of RFID and sensor hardware trade flows. Bottom-up segment sizing triangulated against top-down regulatory mandate scope to ensure consistency.
Outputs were validated against external benchmarks including hyperscaler cloud revenue disclosures, industrial automation vendor segment reporting, and third-party audit network expansion announcements. The analytical framework modeled technology type, application vertical, end-user archetype, and deployment architecture across the projection horizon. CAGRs were derived from regulatory deadline pacing, technology substitution curves, and platform subscription growth trajectories in documented enterprise deployments.
Forecasts assume regulatory continuity in FDA enforcement timelines and EU Farm to Fork implementation schedules; material policy acceleration or delay would require re-modeling. Specific risks include blockchain talent scarcity constraining implementation velocity and multi-party data governance disputes delaying shared ledger consensus. Recalibration cycles align with material shifts in BfR documentation enforcement intensity and cloud infrastructure pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
UK Food Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Mycotoxin Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Food Allergens and Intolerance Testing Market
Food Safety Testing
Food Allergen Testing Market