
 Food and Beverages Disinfection Market | 2026-2036
Food and Beverages Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Disinfection Market Intelligence
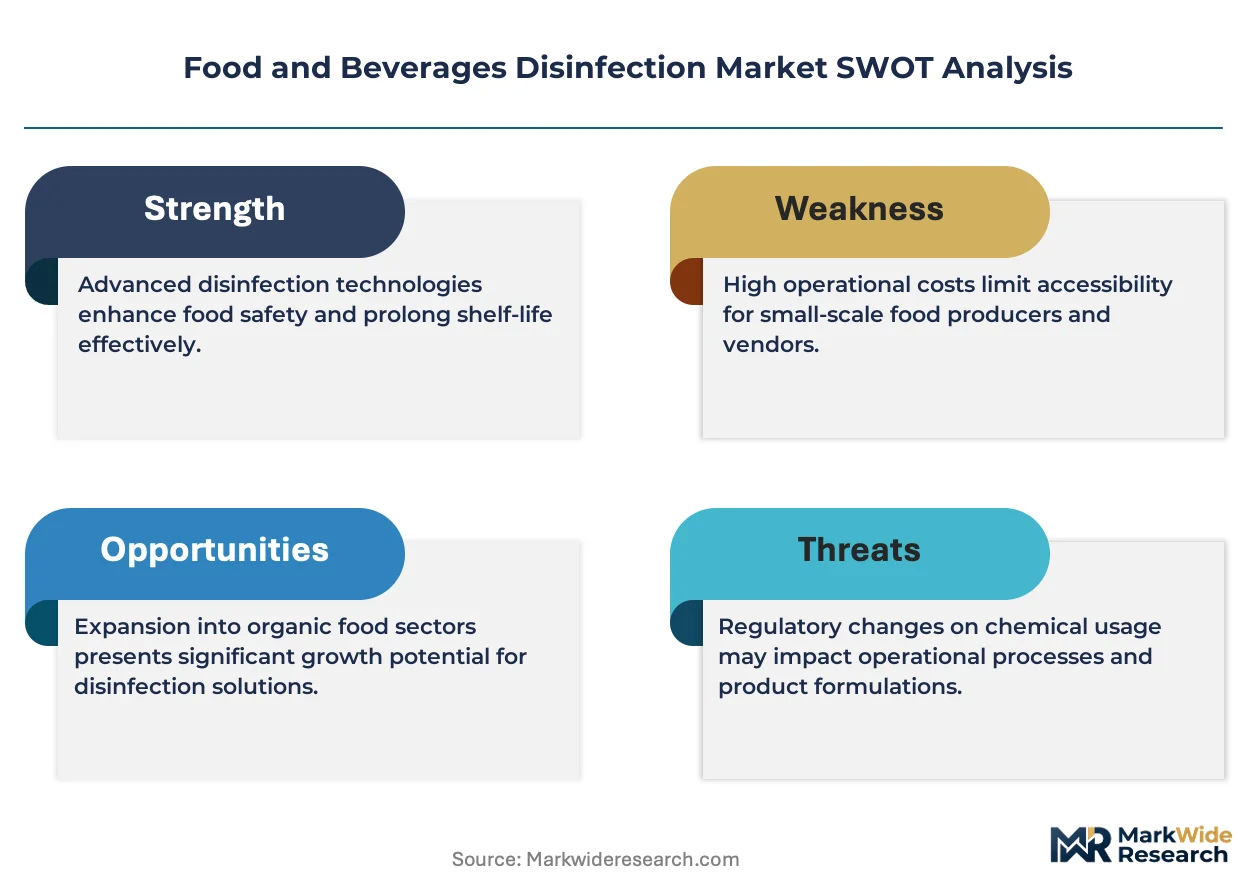
The European Union's Biocidal Products Regulation (BPR) is restructuring the cost-of-entry calculus for chemical disinfectant formulators. Ecolab leverages its extensive service network and integrated solutions to support large food processors in navigating compliance. Solvay differentiates through its portfolio of high-performance peroxygens, including hydrogen peroxide and peracetic acid, for food contact surface applications. These regulations create a barrier for smaller players unable to fund the required toxicological and efficacy studies.
Food and beverages disinfection involves the application of chemical or physical methods to eliminate or reduce pathogenic microorganisms on surfaces, equipment, water, and in the air. These methods must achieve a specific log reduction of target pathogens without leaving harmful residues or altering the sensory properties of the final product. Chemical sprays, particularly those based on quaternary ammonium compounds, remain a dominant product type due to their cost-effectiveness. Within applications, surface sanitization commands the largest share, while water treatment systems using ultraviolet disinfectants represent the fastest-growing segment.
Regulatory oversight is stringent, with the U.S. Environmental Protection Agency (EPA) and Food and Drug Administration (FDA) governing disinfectant claims and food contact safety. In parallel, China's National Health Commission and the State Administration for Market Regulation (SAMR) enforce GB standards for disinfectants used in food production facilities. Key decisions for equipment manufacturers revolve around integrating automated disinfection systems versus developing standalone solutions for legacy processing lines.
Market Dynamics
The central dynamic in the food and beverages disinfection market is the conflict between increasingly stringent, geography-specific regulations like the EU's Biocidal Products Regulation and the persistent demand from processors for cost-effective, broad-spectrum antimicrobial solutions.
Growth Catalysts
- US Food Safety Modernization Act:The FSMA's mandate for preventive controls is compelling meat, poultry, and produce processors to upgrade their sanitation protocols, directly spurring investment in validated disinfection technologies to mitigate pathogen risks like Salmonella and E. coli.
- Clean-Label Consumer Demand:Preference for products with minimal chemical additives is expanding the use of physical disinfection methods, such as ultraviolet (UV-C) light and ozone, particularly in the organic beverage and fresh-cut produce segments.
- German Food Processing Clusters:Germany's extensive network of food manufacturing hubs creates concentrated demand for advanced, automated clean-in-place (CIP) systems, serving as a key adoption center for integrated disinfection solutions in Europe.
Market Restraints
- EU Biocidal Products Regulation:The substantial cost and lengthy data-generation timelines required to register active substances and formulated products under the BPR create a formidable market entry barrier for disinfectant formulators, especially smaller entities.
- Residue Limit Restrictions:Regulatory bodies in various regions impose strict Maximum Residue Limits (MRLs) for certain chemical agents, such as quaternary ammonium compounds, on food-contact surfaces, which limits their application scope in ready-to-eat food processing.
- Precursor Chemical Costs:Price volatility for key raw materials used in peroxygens, including hydrogen peroxide and acetic acid, directly impacts the production costs of peracetic acid (PAA) disinfectants, pressuring formulator margins.
Strategic Opportunities
- Air Disinfection Systems:Treating air within processing facilities to control airborne pathogens like Listeria monocytogenes is an emerging application, creating opportunities for technologies like UV-C air handlers and dry fogging systems in high-risk environments.
- IoT-Enabled Validation:The convergence of automated disinfection systems with IoT sensors offers a new frontier for service-based models, providing real-time monitoring and data logging of critical parameters like concentration and contact time for compliance.
- Southeast Asia Standards Upgrades:As food processors in countries like Vietnam and Thailand elevate their food safety standards to meet export requirements for Europe and the US, demand for effective and documented disinfection solutions is rising.
Industry Challenges
- Legacy System Integration:Retrofitting automated disinfection systems into existing, older food processing plants often involves significant engineering challenges and high capital costs, slowing adoption among operators with constrained budgets.
- Specialized Talent Scarcity:A shortage of technicians with the expertise to install, validate, and maintain advanced disinfection systems, particularly ozone and electrolysis-based technologies, creates an operational bottleneck for food manufacturers.
- Validation Protocol Gaps:A lack of globally harmonized standards for validating the efficacy of novel, non-thermal disinfection technologies can delay their acceptance by multinational corporations seeking uniform safety protocols across their operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Disinfection Market |
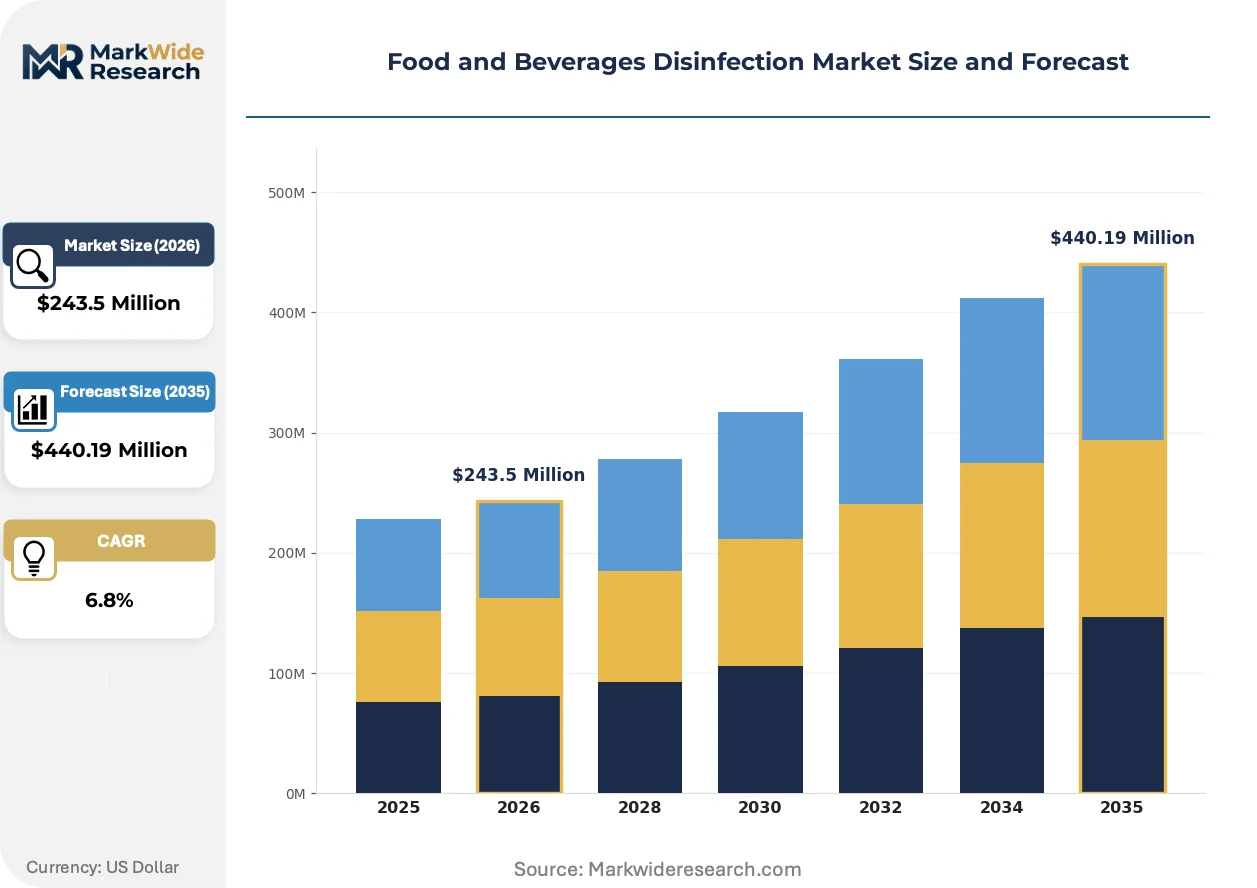
| Market Size in 2026 | $243.5 Million |
| Market Size in 2035 | $440.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet Disinfectants, Ozone Generators, Chemical Sprays, Electrolyzed Water Systems, Thermal Disinfectants Application: Surface Sanitization, Water Treatment, Equipment Sterilization, Air Purification, Packaging Disinfection End User: Food Processing Units, Beverage Manufacturers, Cold Storage Facilities, Quality Testing Labs, Packing Operations Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers, Foodservice Equipment Vendors |
| Companies Covered | Ecolab, Solvay, Neogen Corporation, Evonik Industries, BASF SE, Diversey, Kersia Group, Halma plc, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Disinfection Market Strategic Shifts & Innovations
Automation is fundamentally altering disinfection protocols, moving the industry from scheduled, manual cleanings toward data-driven, validated sanitation events. This shift enhances efficacy documentation for regulators and improves operational efficiency for food and beverage producers.
Automated Clean-in-Place Systems Connected Clean-in-Place (CIP) systems integrate sensors to monitor parameters like temperature, chemical concentration, and flow rate. Major dairy and beverage producers are adopting these systems to optimize resource consumption. This technology is modularizing the disinfection process, enabling processors to run customized, verified cleaning cycles for specific pieces of equipment based on soil load, rather than relying on inefficient, plant-wide flushes.
Regulatory Enforcement in Asia China's State Administration for Market Regulation (SAMR) is intensifying enforcement of its GB standards, which govern disinfectant efficacy and residue testing for food production environments. This regulatory pressure forces suppliers to provide extensive validation data to maintain market access. The infant formula and beverage sectors face the most rigorous scrutiny, accelerating their shift toward compliant, high-performance disinfection agents and systems.
Service-Based Procurement Models Food processors are increasingly utilizing "disinfection-as-a-service" agreements for advanced equipment like UV reactors or ozone generators. This model replaces large upfront capital investments with a recurring operational expense that bundles equipment, maintenance, and compliance support. The trend is most visible among mid-sized bakeries and fresh produce packers in North America and Europe seeking to deploy superior technology without major capital outlay.
Food and Beverages Disinfection Market Segmentation
Understanding the varied segments within the food and beverages disinfection market provides clarity on where investment in new technologies and services is most impactful. Different product types, applications, and end-user requirements influence purchasing decisions and drive innovation across the industry value chain.
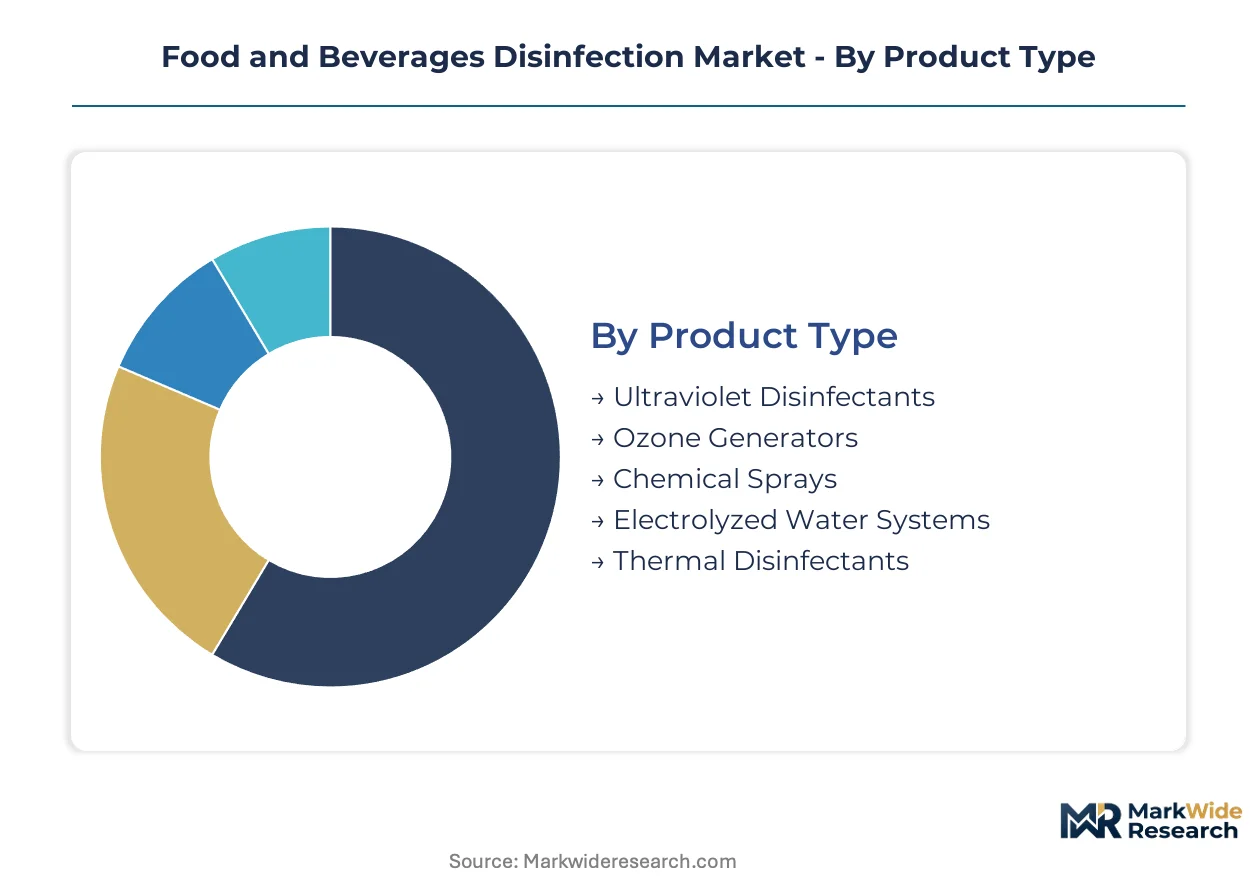
Product Type:
The product type segmentation highlights how food processors are upgrading their disinfection technologies, moving from legacy systems to more efficient solutions that meet evolving regulatory standards.
- Chemical Sprays:These formulations, often based on quaternary ammonium compounds or chlorine, provide broad-spectrum antimicrobial action for surface and equipment disinfection. Their cost-effectiveness drives widespread adoption across diverse food processing environments.
- Ultraviolet Disinfectants:UV-C light systems use germicidal lamps to inactivate microorganisms by disrupting their DNA, offering a chemical-free disinfection method for water, air, and surfaces. Beverage manufacturers and fresh-cut produce packers increasingly deploy these systems for validated pathogen control.
- Ozone Generators:These systems produce ozone gas for water treatment and air purification, effectively oxidizing pathogens and contaminants without chemical residues.
- Electrolyzed Water Systems:Producing hypochlorous acid solutions through electrolysis, these systems offer on-site generation of disinfectants for various cleaning and sanitizing tasks.
- Thermal Disinfectants:High-temperature steam or hot water methods provide effective sterilization for equipment and surfaces, particularly in dairy and beverage processing.
Chemical Sprays sit at the top of the volume ranking, with Ultraviolet Disinfectants climbing the fastest.
Application:
Application segments define the operational areas where disinfection protocols deliver critical food safety outcomes and influence overall plant efficiency for food and beverage producers.
- Surface Sanitization:This application involves disinfecting food contact and non-food contact surfaces, including floors, walls, and processing lines, to prevent cross-contamination. Strict regulatory oversight from bodies like the U.S. FDA mandates validated protocols for surface hygiene.
- Water Treatment:Disinfection of process water, rinse water, and wastewater ensures microbial safety and compliance with environmental discharge limits, crucial for beverage production and fresh produce washing. Ultraviolet systems and ozone are gaining traction in this segment.
- Equipment Sterilization:Regular sterilization of processing machinery, tanks, and pipelines is vital for preventing biofilm formation and ensuring product integrity.
- Air Purification:Controlling airborne pathogens and spores within processing facilities minimizes contamination risks, particularly in high-care areas and cold storage environments.
- Packaging Disinfection:Sanitizing primary and secondary packaging materials prevents microbial transfer to finished products, extending shelf life and ensuring consumer safety.
Surface Sanitization commands the largest share of application volume, while Water Treatment systems are expanding most quickly.
End User:
The end-user classification delineates distinct customer types, each with specific regulatory compliance needs and operational scales for disinfection solutions.
- Food Processing Units:This segment includes a broad range of facilities handling meat, poultry, dairy, bakery, and prepared foods, each requiring tailored disinfection strategies. These units face stringent food safety audits and must comply with national regulations like the US FSMA.
- Beverage Manufacturers:Producers of soft drinks, juices, dairy beverages, and alcoholic drinks demand high-level disinfection for aseptic filling lines, water treatment, and packaging. Their focus on product stability and shelf life drives investment in advanced systems.
- Cold Storage Facilities:Maintaining hygienic conditions in refrigerated and frozen storage environments is critical to prevent pathogen growth and cross-contamination.
- Quality Testing Labs:These facilities require sterile environments and disinfected equipment to ensure accurate microbial analysis of food and beverage samples.
- Packing Operations:Businesses focused on packaging fresh produce, meats, or prepared meals rely on effective disinfection to maintain product quality and extend freshness.
Food Processing Units represent the broadest demand base, with Beverage Manufacturers demonstrating significant growth in aseptic applications.
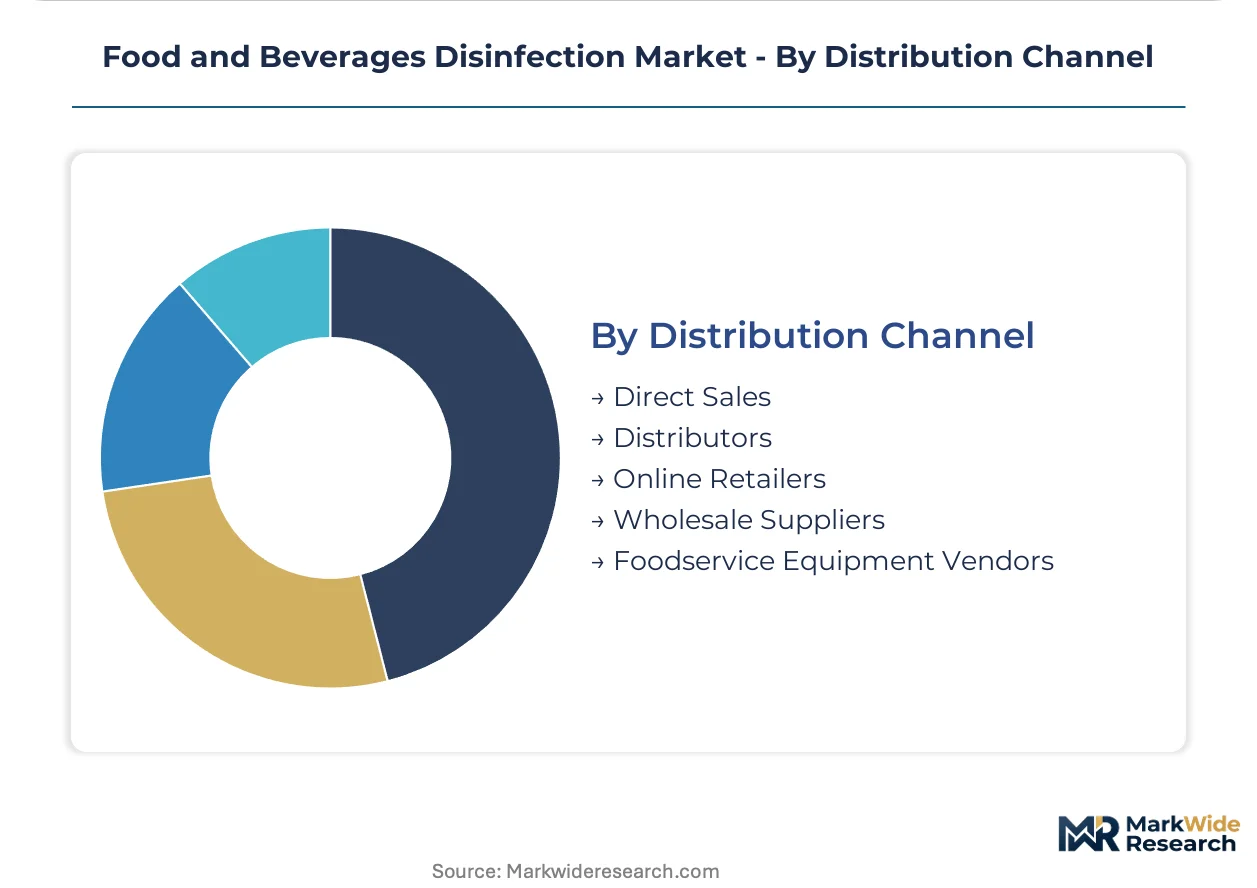
Distribution Channel:
Distribution channels illustrate the varied pathways through which disinfection products reach end-users, reflecting different margin structures and service requirements across the market.
- Direct Sales:Large chemical manufacturers and integrated solution providers often employ direct sales teams to engage major food and beverage processors, offering customized solutions and technical support. This channel facilitates complex installations and ongoing service contracts.
- Distributors:Regional and national distributors serve a wide array of smaller to mid-sized food businesses, providing access to a broad portfolio of disinfection chemicals and equipment. Distributors offer localized inventory and logistical support.
- Online Retailers:E-commerce platforms provide a convenient channel for purchasing standard disinfection products and smaller equipment, catering to businesses seeking quick procurement and competitive pricing.
- Wholesale Suppliers:These suppliers provide bulk quantities of disinfection chemicals and consumables to larger operations or other distributors, often at reduced unit costs.
- Foodservice Equipment Vendors:Specialized vendors integrate disinfection systems directly into food preparation and serving equipment, particularly for commercial kitchens and institutional settings.
Direct Sales channels handle high-volume, integrated solutions, while Distributors serve a fragmented customer base with varied product needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A global pool of specialized technical talent underpins the food and beverages disinfection market, driving innovation and localized application expertise. Regulatory frameworks across key geographies shape market demand and technology adoption. This dynamic environment fosters regional specialization in disinfection solutions.
United States
Meat, poultry, and produce processors in the United States prioritize upgrading sanitation protocols to mitigate pathogen risks. The US Food Safety Modernization Act (FSMA) mandates stricter preventive controls, spurring investment in validated disinfection technologies. California's Central Valley, a major agricultural hub, sees concentrated demand for advanced water treatment and surface sanitization systems for fresh produce.
Germany
German food manufacturing hubs create concentrated demand for advanced, automated clean-in-place (CIP) systems. The European Union's Biocidal Products Regulation (BPR) influences disinfectant formulation choices and market entry for chemical suppliers. Bavaria's extensive dairy and brewing sectors are key adoption centers for integrated disinfection solutions in Europe.
China
China's infant formula and beverage sectors face rigorous scrutiny, accelerating their shift toward compliant, high-performance disinfection agents and systems. The State Administration for Market Regulation (SAMR) intensifies enforcement of GB standards for disinfectant efficacy and residue testing. The Yangtze River Delta region, with its dense food processing infrastructure, drives demand for validated disinfection solutions.
Vietnam
As food processors in Vietnam elevate their food safety standards to meet export requirements for Europe and the US, demand for effective disinfection solutions is rising. National food safety regulations increasingly align with international benchmarks, pushing for technology upgrades. Ho Chi Minh City's burgeoning food and beverage processing zones are experiencing significant investment in advanced hygiene systems.
Brazil
Brazil's large-scale meat, poultry, and beverage processing industries require robust disinfection protocols to ensure product safety and export compliance. ANVISA, the country's health surveillance agency, enforces stringent food safety regulations impacting disinfectant use. São Paulo state, a major agricultural and industrial center, exhibits strong demand for water treatment and equipment sterilization technologies.
Food and Beverages Disinfection Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure within food and beverages disinfection. Large chemical manufacturers and integrated solution providers form the top tier, offering comprehensive service models. Strategic partnerships and portfolio diversification are common competitive moves to address evolving regulatory landscapes and technological advancements.
Integrated solution providers such as Ecolab, alongside chemical specialists like Solvay and Evonik Industries, anchor the competitive landscape. Ecolab leverages its extensive service network to support large food processors with integrated solutions. Solvay differentiates through its portfolio of high-performance peroxygens for food contact surface applications. German-based Evonik Industries exemplifies large chemical producers with diversified portfolios supplying key raw materials and formulated disinfectants to the food industry.
| Leading Market Players |
|---|
| Ecolab |
| Solvay |
| Neogen Corporation |
| Evonik Industries |
| BASF SE |
| Diversey |
| Kersia Group |
| Halma plc |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
The divergence between validated, high-performance disinfection solutions and commodity chemical sprays drives distinct pricing and supply chain configurations. Regulatory compliance costs and technological integration significantly influence market value across the food and beverages disinfection sector.
Pricing Analysis
The bundled-vs-unbundled service split shapes pricing within the food and beverages disinfection market. Disinfection-as-a-service models, offering integrated equipment and compliance support, command premium pricing. Price differentiation stems from regulatory certification levels, such as those required by the US FDA or EU BPR, and the level of integration with automated processing lines. Pricing pressure intensifies on commodity chemical sprays due to fluctuating precursor chemical costs and strict residue limits. Smaller food processors and legacy facilities exhibit higher price sensitivity compared to large beverage manufacturers seeking validated, integrated solutions.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers for advanced disinfection systems like UV-C lamps and ozone generators. Geographic supply concentration for key raw materials, such as hydrogen peroxide and acetic acid, often centers in chemical manufacturing hubs like Germany and China. The supply chain relies on these chemical inputs and specialized equipment components. Regulatory restrictions, particularly under the EU Biocidal Products Regulation, introduce a structural risk by limiting active substance availability. Distribution runs through direct sales channels for complex integrated solutions and regional distributors for broader access to commodity chemicals and smaller equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food and beverages disinfection market functions as a regulatory compounder, with the US Food Safety Modernization Act (FSMA) driving substantial investment in advanced sanitation protocols.
For Market Incumbents: Cement your market position by expanding integrated service offerings that bundle advanced equipment with compliance validation support. Invest in R&D for next-generation, residue-free disinfection agents to counter the threat of increasingly stringent Maximum Residue Limits. Deepen vertical integration into critical component manufacturing for physical disinfection technologies like UV-C systems, ensuring supply stability amidst global component scarcity.
For New Entrants and Emerging Players: A significant price-point gap exists between premium automated systems and basic chemical solutions, creating white space for novel offerings. Target underpenetrated segments like air disinfection systems in high-risk processing environments or IoT-enabled validation platforms for mid-sized fresh produce packers. A service-based procurement model, offering "disinfection-as-a-service," provides a compelling go-to-market angle, reducing upfront capital expenditure for end-users.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized technological capabilities meet fragmented service delivery, creating attractive acquisition targets. The long-term viability of this market over the next decade remains robust, driven by persistent food safety demands and evolving regulatory landscapes. Target niche specialists in advanced physical disinfection methods (e.g., ozone, electrolyzed water) or software providers offering IoT-enabled compliance and data logging. The intensity of regulatory enforcement in emerging markets like Southeast Asia serves as a critical signal to watch for accelerated adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Integrated Service Networks | Broadens market reach and strengthens customer loyalty through comprehensive compliance solutions. |
| Invest in Residue-Free Disinfection R&D | Addresses clean-label consumer demand and mitigates risks from tightening regulatory residue limits. |
| Develop IoT-Enabled Validation Platforms | Enhances data-driven compliance and operational efficiency for food and beverage processors. |
| Target Southeast Asia Market Entry | Capitalizes on rising food safety standards and export requirements in rapidly developing economies. |
| Offer Disinfection-as-a-Service Models | Lowers capital barriers for mid-sized operators, accelerating adoption of advanced technologies. |
Research Approach
Direct dialogue with food safety managers, plant engineers, procurement leads, and regulatory compliance officers provided qualitative grounding. This primary research was rigorously validated against secondary sources, including EPA/FDA guidelines, EU Biocidal Products Regulation documentation, China's GB standards, and industry association reports. A multi-pronged approach, combining bottom-up market sizing with top-down validation, ensured comprehensive data triangulation.
The quantitative model produced granular market forecasts across the analysis window by segmenting data by product type, application, end-user, distribution channel, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected future demand, incorporating inputs such as global food production volumes and anticipated regulatory enforcement budgets. This framework provides a detailed outlook.
Caveats apply where new pathogen outbreaks, sudden regulatory shifts, or significant raw material price shocks could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption and market dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
High-Throughput Food Allergen Screening Test Instruments Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Residual Lactose Analyzer Market