
 UAE Cereal Bar Market | 2026-2036
UAE Cereal Bar Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Cereal Bar Market Analytics
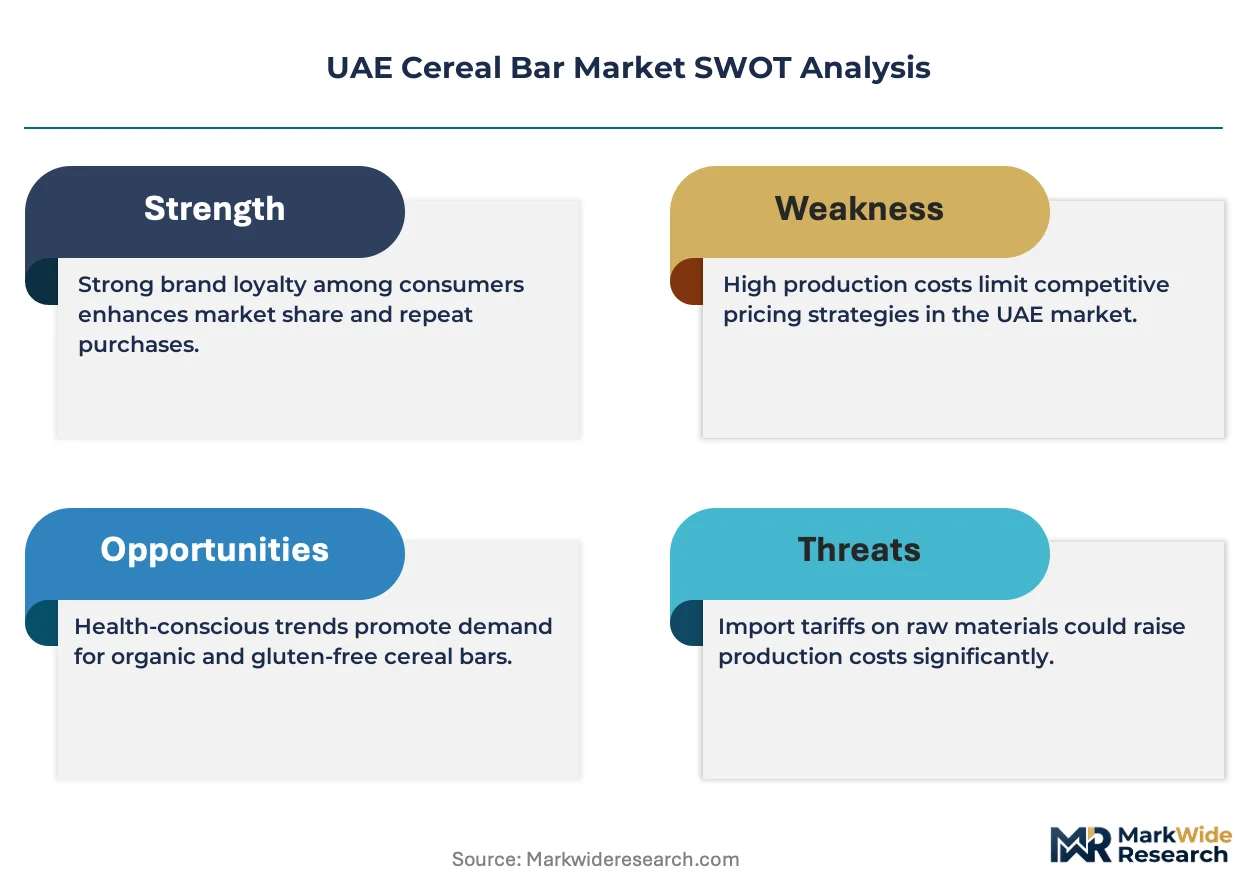
MOHAP's front-of-pack labeling requirements is hardening demand for clean-label formulations across the Emirates. Nestle leverages its regional manufacturing footprint to sustain shelf presence in Carrefour and Lulu hypermarkets. General Mills anchors its portfolio through Nature Valley brand recognition among expatriate households. Kellogg's competes via specialized protein bar lines targeting gym-centric retail channels.
A cereal bar is a compressed, shelf-stable snack composed of baked or unbaked grains, binding syrups, and functional additives such as whey protein or chicory root fiber, formed through extrusion or cold-press molding to deliver portable nutrition. Its primary commercial purpose is to provide measured macronutrient delivery for time-constrained consumption occasions. Protein bars command premium positioning due to elevated per-unit margins and athlete loyalty, while fiber-enriched variants attract diabetic and weight-management segments seeking low-glycemic options. Online retailers represent the fastest-growing distribution channel, though supermarkets retain volume dominance through impulse-placement strategies at checkout zones.
MOHAP enforces additive limits and nutritional claims verification, while the UAE's adoption of GCC Standardization Organization (GSO) food safety protocols shapes import compliance for international suppliers. ESMA's product conformity schemes further condition market access through mandatory testing and certification cycles. Stakeholders must monitor evolving sugar-tax discussions and halal certification granularity as these frameworks will determine which formulations achieve scalable distribution across the seven emirates.
Market Dynamics
MOHAP's front-of-pack labeling mandate is compressing formulation timelines across Emirates-based manufacturers, forcing rapid clean-label transitions before enforcement windows close.
Growth Catalysts
- Protein fortification technology:Cold-press extrusion methods now embed whey isolates at higher densities without textural degradation, expanding functional snack appeal among Dubai fitness communities.
- ESMA conformity schemes:Mandatory halal certification granularity is creating trusted product tiers that command shelf priority in Carrefour and Lulu hypermarket networks.
- Abu Dhabi:Government workplace wellness programs subsidize healthy vending machine installations, embedding cereal bars into institutional procurement channels.
Market Restraints
- Date syrup input volatility:Regional harvest fluctuations in Saudi Arabia and Oman squeeze binding agent costs, compressing margins on mid-tier formulations.
- Single-source chicory fiber:European inulin suppliers dominate functional fiber inputs, exposing Emirates manufacturers to euro-denominated price swings and shipping delays through Rotterdam.
- Substitution threat:Fresh protein boxes and refrigerated Greek yogurt packs capture identical meal-replacement occasions with superior freshness signaling.
Strategic Opportunities
- Sharjah and Northern Emirates:Retail infrastructure gaps in Ajman, Fujairah, and Ras Al Khaimah leave convenience-store channels underdeveloped versus Dubai saturation.
- Airline catering procurement:Emirates and Etihad Airways seek compact, shelf-stable nutrition for crew and premium economy passengers, creating B2B volume contracts.
- MOHAP sugar-tax preparation:Anticipatory reformulation investments ahead of potential levy implementation will position early movers for post-tax competitive advantage.
Industry Challenges
- Food technologist scarcity:Specialized expertise in clean-label binding systems and halal certification documentation remains concentrated in Dubai, constraining production scaling in peripheral emirates.
- Legacy ERP integration:Batch-tracking requirements under GSO food safety protocols force mid-tier manufacturers to retrofit legacy inventory systems for full supply-chain traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Cereal Bar Market |
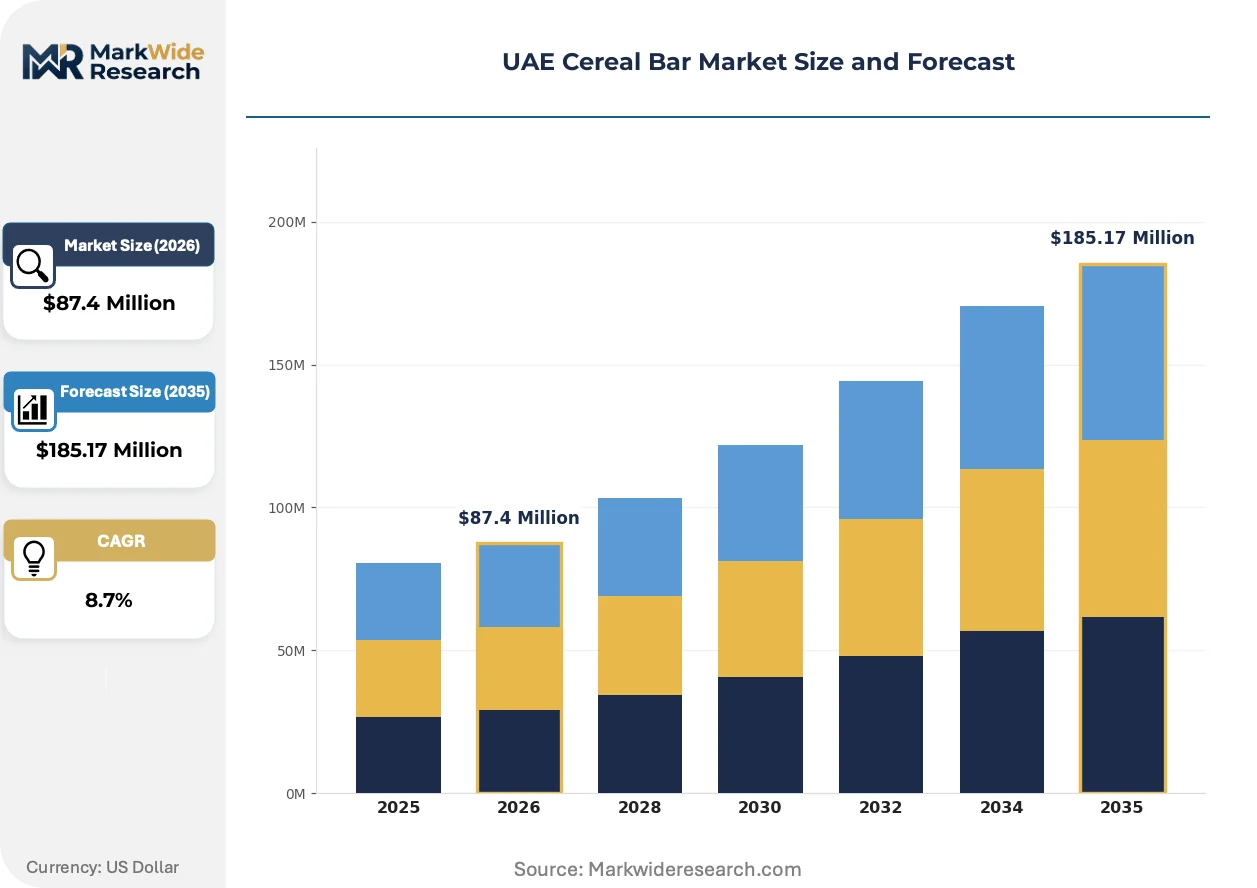
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Granola, Protein, Fiber-Enriched Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores End User: Fitness Enthusiasts, Students, Busy Professionals, Health-Conscious Consumers Packaging Type: Single-Serve Packets, Boxes, Bulk Packaging, Resealable Pouches |
| Companies Covered | Nestle, General Mills, Kellogg's, Be Natural, Clif Bar & Company, Nature Valley, Urban Bites, Morningside Foods, Weetabix Food Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Cereal Bar Market Evolving Landscape
Clean-label binding technologies and regulatory disclosure mandates are compressing traditional formulation cycles while opening premium positioning for verified functional claims.
Chicory root fiber is converging with date paste sweetening systems to deliver low-glycemic binding matrices without artificial additives. Abu Dhabi-based diabetic and weight-management segments are adopting these reformulations faster than Dubai's mass market, compressing the innovation-to-shelf timeline from eighteen months to under eight months for compliant manufacturers.
MOHAP's nutritional claims verification protocol now requires third-party laboratory documentation for protein content assertions. This industrial consequence has eliminated shelf-space access for unverified imports while benefiting Emirates-based producers with in-house testing capabilities. Protein-enriched variants face the tightest compliance scrutiny, with gym-centric retail channels demanding batch-specific certificates.
Impulse placement at checkout zones is fragmenting as online subscription models capture routine replenishment purchases. Dubai's time-constrained professional segment now sources monthly protein bar deliveries through noon.com and Amazon.ae, displacing unplanned supermarket acquisitions. This channel rotation is most visible in Dubai Marina and Downtown Dubai residential clusters where delivery density supports same-day fulfillment economics.
UAE Cereal Bar Market Segmentation
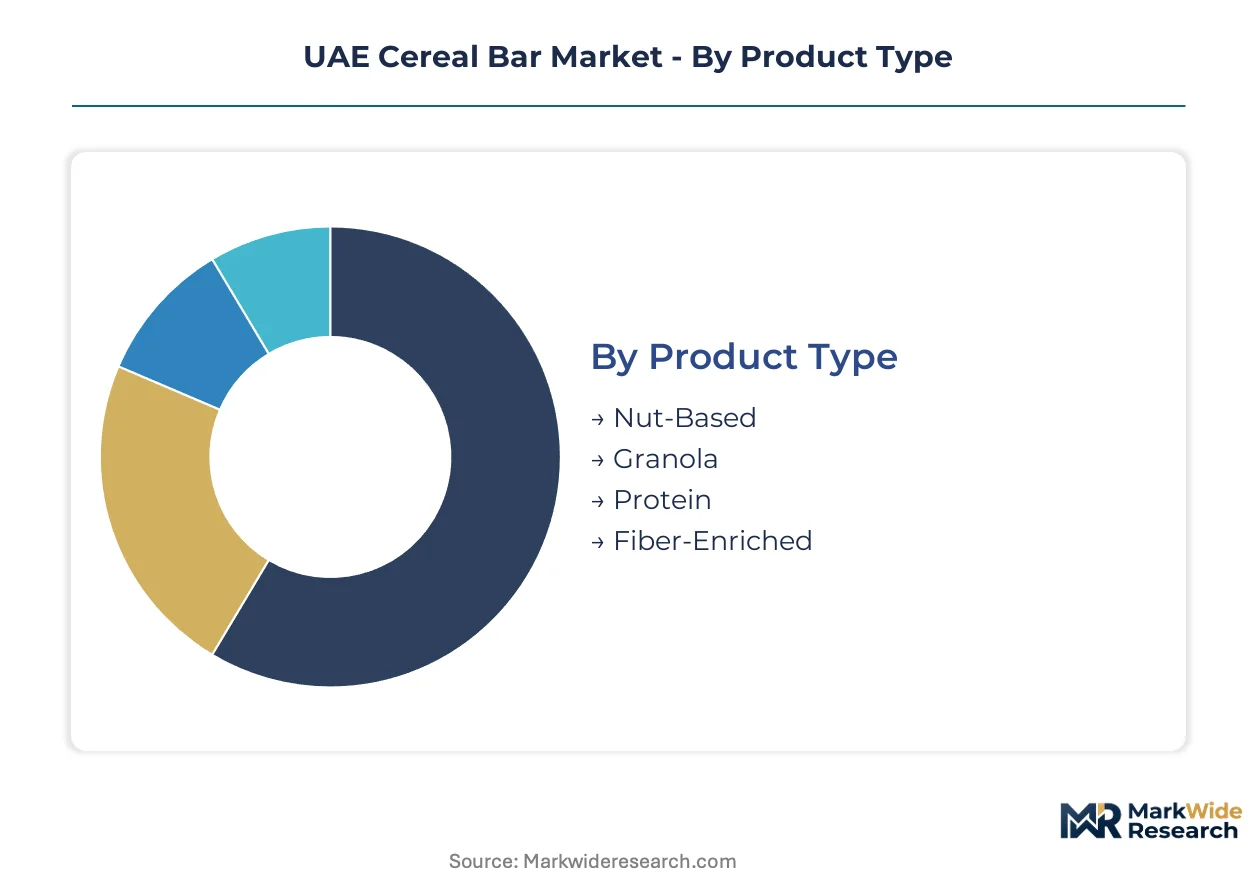
Product differentiation across the Emirates follows distinct consumption occasions and channel economics. Manufacturers align formulation investments with regulatory thresholds and retail placement premiums rather than pursuing uniform portfolio coverage.
Product Type:
Supply concentration in Dubai's manufacturing zones favors high-margin functional formats with halal certification complexity.
- Protein:Cold-pressed whey isolate bars deliver 20-30g protein per unit through extrusion methods that preserve texture under ESMA additive limits. Dubai Marina fitness clubs and Abu Dhabi government workplace programs concentrate procurement of these SKUs, with gym-centric retail channels demanding batch-specific protein verification certificates.
- Fiber-Enriched:Chicory root inulin formulations target diabetic and weight-management segments through low-glycemic binding matrices. Abu Dhabi's clinical nutrition channels adopt these faster than Dubai's mass market, compressing innovation-to-shelf timelines for compliant Emirates-based producers.
- Nut-Based:Almond and date paste compositions dominate traditional retail with simpler halal documentation requirements.
- Granola:Baked oat clusters with honey or date syrup binding serve price-sensitive convenience store channels across Sharjah and Northern Emirates.
Protein formats absorb the bulk of installed capacity; fiber-enriched variants are expanding most quickly.
Distribution Channel:
Channel economics in the Emirates split between impulse-driven physical retail and subscription-based replenishment models.
- Online Retailers:noon.com and Amazon.ae capture routine monthly replenishment from Dubai's professional segment, with same-day fulfillment economics viable in Marina and Downtown residential clusters. Subscription models displace unplanned supermarket acquisitions among time-constrained consumers.
- Supermarkets:Carrefour and Lulu hypermarket networks retain volume dominance through checkout zone placement strategies, though impulse placement is fragmenting as online penetration deepens.
- Convenience Stores:Underdeveloped infrastructure in Ajman, Fujairah, and Ras Al Khaimah leaves this channel concentrated in Dubai and Abu Dhabi urban cores.
- Health Food Stores:Specialized protein bar SKUs with third-party verification documentation command shelf priority in gym-adjacent retail.
Supermarkets retain the deepest inventory positions; online retailers are climbing the fastest.
End User:
User segmentation reflects occupational density patterns across the seven emirates rather than demographic spreads.
- Busy Professionals:Dubai's finance and consulting workforce drives meal-replacement consumption through office vending installations and subscription delivery, with government workplace wellness programs in Abu Dhabi subsidizing healthy procurement channels.
- Fitness Enthusiasts:Gym-centric retail channels in Dubai Marina and Jumeirah Lake Towers demand verified protein content with batch-specific documentation under MOHAP nutritional claims protocols.
- Health-Conscious Consumers:Diabetic and weight-management segments in Abu Dhabi adopt low-glycemic reformulations ahead of Dubai's mass market.
- Students:University campus vending in Sharjah and Dubai concentrates demand for price-accessible granola and nut-based formats.
Busy professionals absorb the bulk of premium SKU capacity; fitness enthusiasts are gaining share fastest.
Packaging Type:
Packaging configuration aligns with channel handling requirements and institutional procurement specifications.
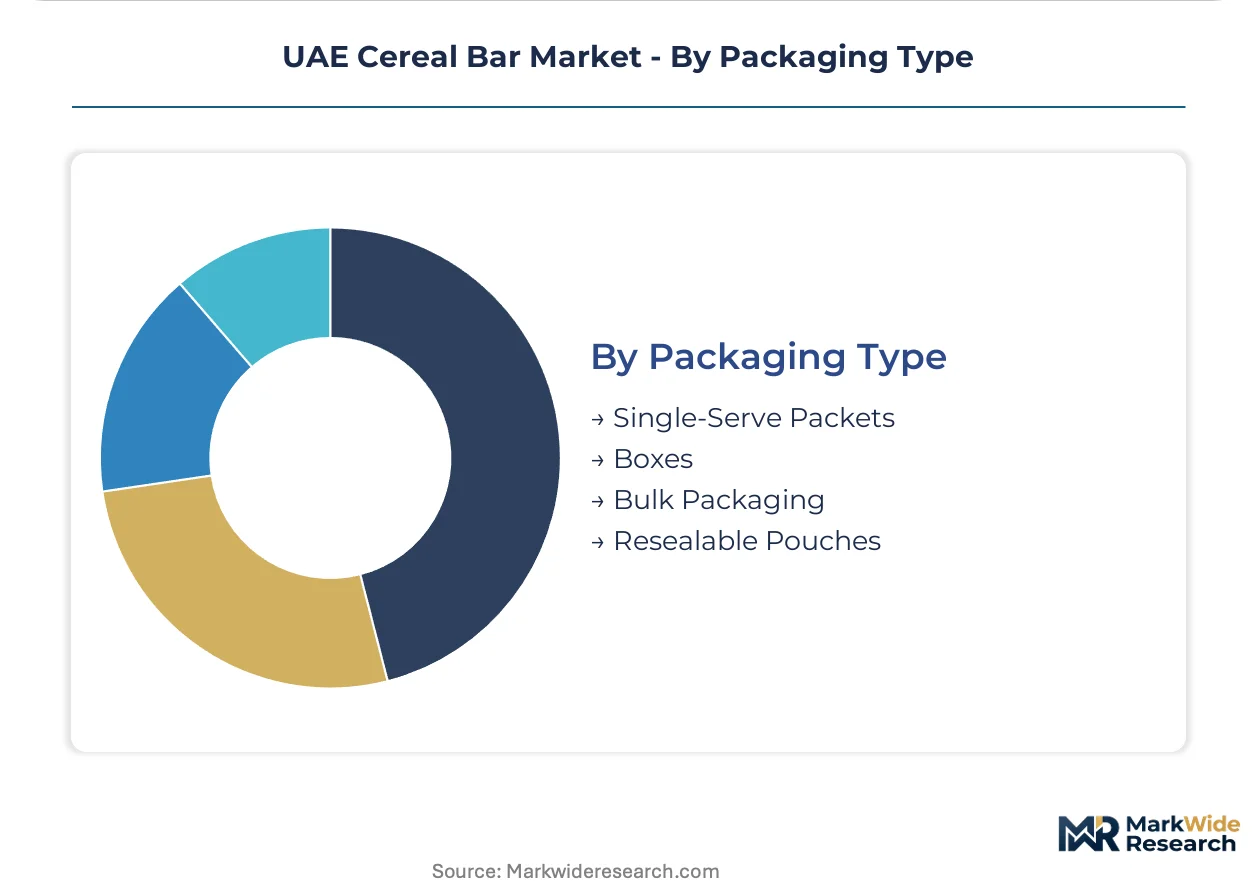
- Single-Serve Packets:Individual wrapped units dominate impulse placement at supermarket checkout zones and airline catering procurement for Emirates and Etihad Airways crew nutrition programs.
- Boxes:Multi-count packaging serves subscription replenishment models through online retailers with monthly delivery frequencies.
- Bulk Packaging:Institutional procurement for government workplace programs and hospitality channels concentrates demand in Abu Dhabi and Dubai corporate campuses.
- Resealable Pouches:Flexible formats target health food store channels with premium positioning and extended shelf-life requirements.
Single-serve packets absorb the bulk of production line allocation; boxes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing concentrates in Dubai and Abu Dhabi free zones while consumption spreads across all seven emirates with pronounced urban-rural gradients. Production capacity outpaces Northern Emirates demand, creating distribution-intensive supply patterns southward toward Sharjah and the northern tier.
Dubai
Dubai Marina and Jumeirah Lake Towers fitness clusters absorb premium protein bar volumes through gym-adjacent retail channels. MOHAP's front-of-pack labeling enforcement windows are compressing formulation timelines for Jebel Ali-based manufacturers. Al Quoz industrial zone hosts cold-press extrusion facilities serving Carrefour and Lulu hypermarket networks with halal-certified production lines.
Abu Dhabi
Government workplace wellness programs subsidize healthy vending installations across ministry campuses and sovereign wealth fund headquarters. The emirate's clinical nutrition channels adopt low-glycemic fiber formulations faster than Dubai's mass market. Khalifa Industrial Zone manufacturers supply institutional procurement contracts for Etihad Airways crew nutrition programs.
Sharjah
University campus vending concentrates demand for price-accessible granola formats among student populations. Retail infrastructure gaps relative to Dubai create convenience-store channel underdevelopment that local distributors are addressing through phased route expansion. Hamriyah Free Zone packaging converters serve Emirates-based cereal bar producers with flexible film and single-serve packet capacity.
Northern Emirates
Ajman, Fujairah, and Ras Al Khaimah present retail penetration opportunities where modern trade format density lags southern emirates. Traditional grocery and independent convenience channels dominate with nut-based and date-sweetened formats that require simpler halal documentation. Distribution economics from Dubai hubs determine product availability and pricing tiers in these markets.
Al Ain
This interior oasis city maintains distinct consumption patterns tied to agricultural heritage and Bedouin-influenced dietary preferences. Local date processing cooperatives supply binding agent inputs to regional manufacturers. Retail modernization is accelerating through Lulu and Carrefour expansion, displacing traditional souk channels for packaged snack categories.
UAE Cereal Bar Market Competitive Landscape
The competitive structure tilts toward multinational FMCG conglomerates with regional manufacturing footprints. Nestle, General Mills, and Kellogg's anchor shelf presence through hypermarket network relationships and brand recognition among expatriate households. Three archetypes dominate: global nutrition conglomerates with Gulf distribution infrastructure, regional halal-specialist manufacturers with ESMA certification depth, and agile local entrants targeting fitness-channel premium positioning. Competitive moves center on anticipatory reformulation ahead of sugar-tax implementation and halal certification granularity investments that secure shelf priority.
Within the global nutrition conglomerate tier, Nestle leverages its Middle East manufacturing base to sustain volume leadership in modern trade channels. General Mills anchors portfolio positioning through Nature Valley brand equity among Western expatriate segments. Kellogg's occupies a specialized position via protein bar lines distributed through gym-centric retail. Among regional specialists, Urban Bites and Morningside Foods exemplify agile local production models with accelerated clean-label transition capabilities. These Emirates-based manufacturers compress innovation-to-shelf timelines by co-locating formulation, testing, and ESMA certification documentation.
| Leading Market Players |
|---|
| Nestle |
| General Mills |
| Kellogg's |
| Be Natural |
| Clif Bar & Company |
| Nature Valley |
| Urban Bites |
| Morningside Foods |
| Weetabix Food Company |
| Others |
Value Network & Pricing Analysis
MOHAP's front-of-pack labeling mandate gates qualified supply and premium-tier pricing access by forcing clean-label reformulation investments that only Emirates-based manufacturers with in-house testing capabilities can absorb. This regulatory filter compresses margins on mid-tier imports while rewarding verified domestic producers with shelf priority and protein bar price premiums.
Pricing Analysis
Per-unit protein content anchors value-based pricing tiers across gym-centric retail channels, with batch-verified whey isolate bars commanding substantial premiums over unverified imports. Three-tier pricing structure across premium, standard, and economy levels separates ESMA-certified functional formats from conventional granola and nut-based alternatives. Pricing pressure stems from date syrup input volatility originating in Saudi Arabian and Omani harvest fluctuations, squeezing binding agent costs for mid-tier formulations. Busy professionals in Dubai Marina and Downtown clusters exhibit lowest price sensitivity through subscription replenishment models, while students in Sharjah university corridors drive volume at economy price points.
Supply Chain Analysis
Regional distribution centers in Jebel Ali and Khalifa Industrial Zone anchor hub-and-spoke patterns radiating toward Northern Emirates retail infrastructure gaps. Manufacturing concentrates in the UAE, with cold-press extrusion capacity clustering in Dubai free zones and Abu Dhabi government-proximate facilities. Raw material dependencies draw from European inulin suppliers for chicory root fiber, Saudi Arabian and Omani date syrup harvests for binding agents, and imported whey isolates for protein fortification. Single-source chicory fiber exposure creates euro-denominated price swing vulnerability through Rotterdam shipping lanes. Distribution runs through Carrefour and Lulu hypermarket networks for volume, with noon.com and Amazon.ae capturing subscription replenishment in high-density residential clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE cereal bar market sits in a formulation technology transition phase, with cold-press extrusion methods displacing legacy baked formats by embedding functional additives without textural degradation under tightening MOHAP additive limits.
For Market Incumbents: Lock in halal certification granularity investments that secure shelf priority in Carrefour and Lulu networks ahead of potential sugar-tax implementation. Deepen backward integration into date syrup supply through direct sourcing agreements with Saudi Arabian and Omani agricultural cooperatives, insulating margin structures from harvest-driven input volatility that threatens mid-tier positioning. For New Entrants and Emerging Players: Airline catering procurement contracts represent the most penetrable white-space channel, with Emirates and Etihad Airways seeking compact shelf-stable nutrition for crew and premium economy passengers. Target underdeveloped convenience-store infrastructure in Ajman, Fujairah, and Ras Al Khaimah through phased route expansion from Dubai distribution hubs, leveraging simpler halal documentation requirements for nut-based and date-sweetened formats that bypass protein verification complexity. For Investors and Strategic Acquirers: MOHAP's enforcement window closure for front-of-pack labeling is the leading indicator that clean-label transition capabilities will determine scalable distribution access across the seven emirates. Long-term viability in this market rests on acquiring Emirates-based manufacturers with co-located formulation, testing, and ESMA certification documentation that compress innovation-to-shelf timelines. Watch for anticipatory reformulation investments ahead of sugar-tax discussions as the signal that early movers are positioning for post-tax competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | MOHAP's additive limits and nutritional claims verification protocol eliminates unverified import shelf access. |
| Halal Certification Granularity Expansion | ESMA conformity schemes create trusted product tiers commanding priority in Carrefour and Lulu hypermarkets. |
| Airline Catering Procurement Pursuit | Emirates and Etihad Airways B2B volume contracts offer institutional anchoring beyond retail channel fragmentation. |
| Northern Emirates Distribution Buildout | Retail infrastructure gaps in Ajman, Fujairah, and Ras Al Khaimah create first-mover convenience-store positioning. |
| Subscription Model Platform Integration | noon.com and Amazon.ae capture routine replenishment from Dubai's time-constrained professional segment. |
Research Methodology
Independent corroboration across primary interviews with food technology directors, MOHAP regulatory affairs specialists, Carrefour and Lulu category buyers, and Emirates-based manufacturing executives underwrites the qualitative findings. Secondary validation draws from GSO food safety protocol documentation, ESMA product conformity scheme filings, MOHAP nutritional labeling circulars, and GCC customs trade records. Bottom-up SKU-level demand modeling and top-down macro consumption trend analysis triangulate volume and value estimates.
Comparable-period anchoring to historical consumption patterns across Dubai, Abu Dhabi, Sharjah, and Northern Emirates emirates establishes the forecast baseline over the projection horizon. Segmentation dimensions span product type, distribution channel, end user archetype, and packaging configuration, with protein verification documentation requirements and halal certification tiers serving as industry-specific modeling inputs. CAGRs derive from trend extrapolation adjusted for regulatory enforcement timelines and channel migration patterns.
Caveats apply where MOHAP sugar-tax implementation timing, date syrup harvest volatility, or euro-denominated chicory fiber price swings could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Asia-Pacific Snack Bar Market
Snacks
Veggie Chips Market
Snacks
Poland Snack Bar Market
Snacks
Kale Chips Market
Snacks
Low Fat Granola Market
Snacks
UAE Snack Bar Market
Snacks
Meat Snacks Market
Snacks
Snacks Market
Snacks
Jerky Snacks Market
Snacks
India Energy Bar Market
Snacks
Australia Snack Bar Market
Snacks
UK Snack Market
Snacks
South America Energy Bar Market
Snacks
South Korea Snack Bar Market
Snacks
Tortilla Mix Market
Snacks
Fried Potato Chips Market